
 Thailand Oil and Gas Upstream Market | 2026-2036
Thailand Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Oil and Gas Upstream Market Analytics
The gap between premium deepwater exploration portfolios and commodity-grade onshore production is repositioning capital allocation across Thailand's upstream sector. PTTEP leverages its dominant concession holdings to sustain output from the Erawan and Bongkot gas fields. Chevron Thailand E&P anchors its position through operational scale at the Pattani Trough, while TotalEnergies SE competes via specialized subsea expertise at the M9 and M11 blocks.
Thailand oil and gas upstream operations encompass the exploration, drilling, and extraction of crude oil and natural gas from subsurface reservoirs, typically targeting formations at depths of 1,500 to 4,000 meters beneath the Gulf of Thailand and onshore Khorat Plateau. These activities supply feedstock to the country's gas-fired power generation fleet and petrochemical complexes, with natural gas accounting for roughly two-thirds of primary energy consumption. Offshore drilling commands the largest equipment commitment as operators push into deeper water, while enhanced recovery applications are gaining structural importance as legacy fields deplete. Well completion services concentrate margin pools where reservoir complexity demands bespoke perforation and stimulation design.
Thailand's Department of Mineral Fuels administers concession rounds and production-sharing frameworks that directly shape field economics and foreign operator participation. The Petroleum Act, alongside Environmental Impact Assessment requirements enforced by the national environmental regulator, dictates drilling permits, flaring limits, and decommissioning bonds. Stakeholders must monitor how fiscal term negotiations and carbon accounting rules will alter project returns on marginal field investments.
Market Dynamics
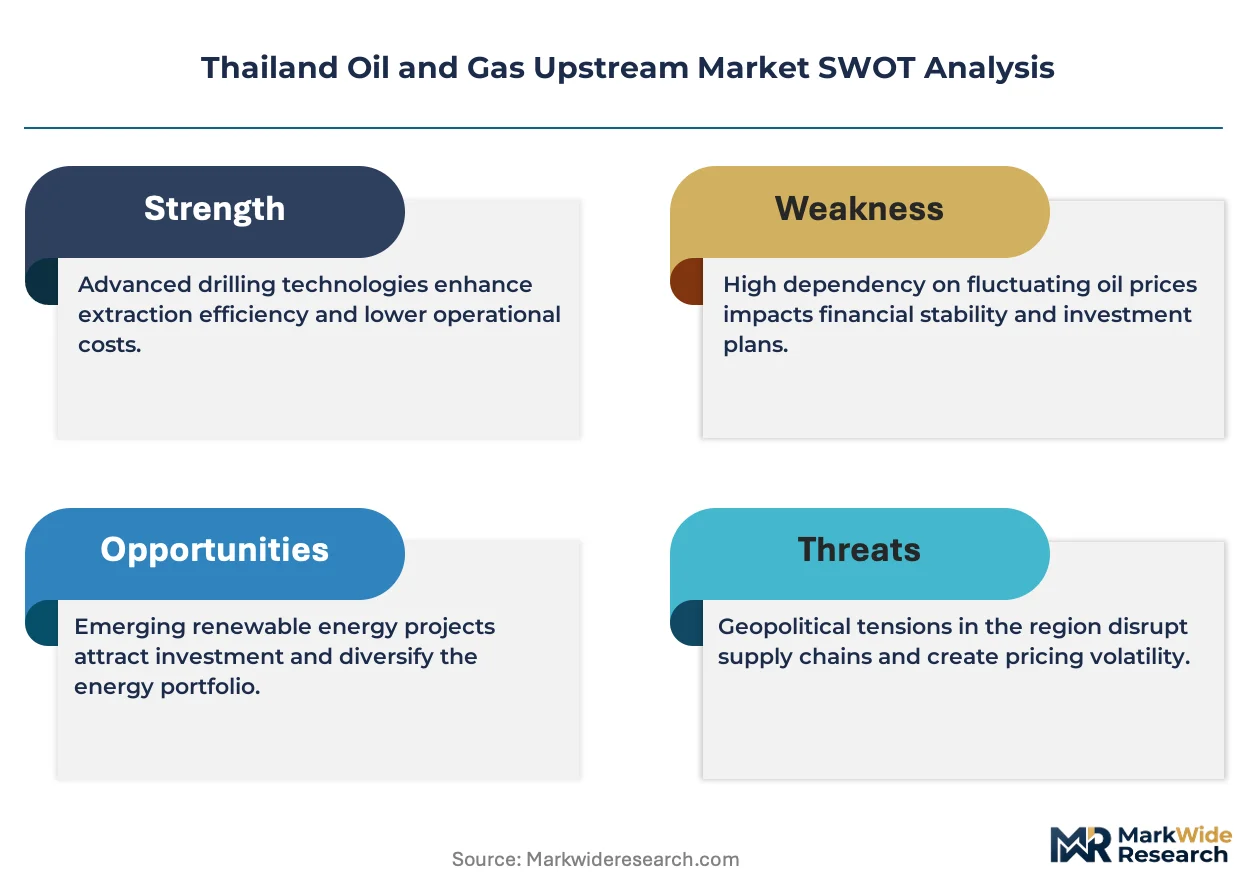
Thailand's upstream sector faces a structural squeeze between maturing offshore reservoirs and the Department of Mineral Fuels' tightened fiscal terms under revised production-sharing contracts. Operators must now justify capital deployment against declining well productivity and carbon accounting requirements.
Growth Catalysts
- Enhanced Recovery Mandates:The Petroleum Act incentivizes tertiary recovery methods across depleted Gulf of Thailand blocks. Chemical EOR and gas injection projects qualify for extended concession terms.
- Power Sector Gas Demand:State utilities anchor offtake through long-term supply agreements. Cogeneration plants and combined-cycle facilities require steady feedstock volumes.
- Khorat Plateau Unconventionals:Onshore tight gas formations in the northeast attract specialized drilling contractors. Horizontal well completions unlock previously uneconomic sandstone reservoirs.
Market Restraints
- Offshore Service Cost Volatility:Jack-up rig dayrates fluctuate with regional demand cycles. Deepwater vessel availability constrains campaign timing in the Pattani Trough.
- Domestic Supply Concentration:PTTEP controls majority concession acreage. Foreign operators face partnership requirements and carried-interest obligations.
- Reservoir Complexity Limits:Subsurface faulting and compartmentalization reduce recovery factors. Geosteering demands outpace local directional drilling capacity.
Strategic Opportunities
- Marginal Field Redevelopment:Small-scale FPSO and subsea tieback solutions target stranded reserves. Modular production systems reduce minimum economic field size.
- Carbon Capture Integration:Depleted gas fields offer sequestration potential. The national climate framework may qualify storage projects for carbon credit mechanisms.
- Digital Twin Adoption:Real-time reservoir simulation and predictive maintenance converge. Integrated asset models optimize artificial lift and compression scheduling.
Industry Challenges
- Subsea Engineering Talent Gap:Deepwater completion design and flow assurance expertise remain scarce. Universities produce insufficient petroleum engineers with offshore specialization.
- Decommissioning Liability Uncertainty:Bond calculations and site restoration standards lack precedent. Operators delay abandonment decisions pending regulatory clarity from the Department of Mineral Fuels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Oil and Gas Upstream Market |
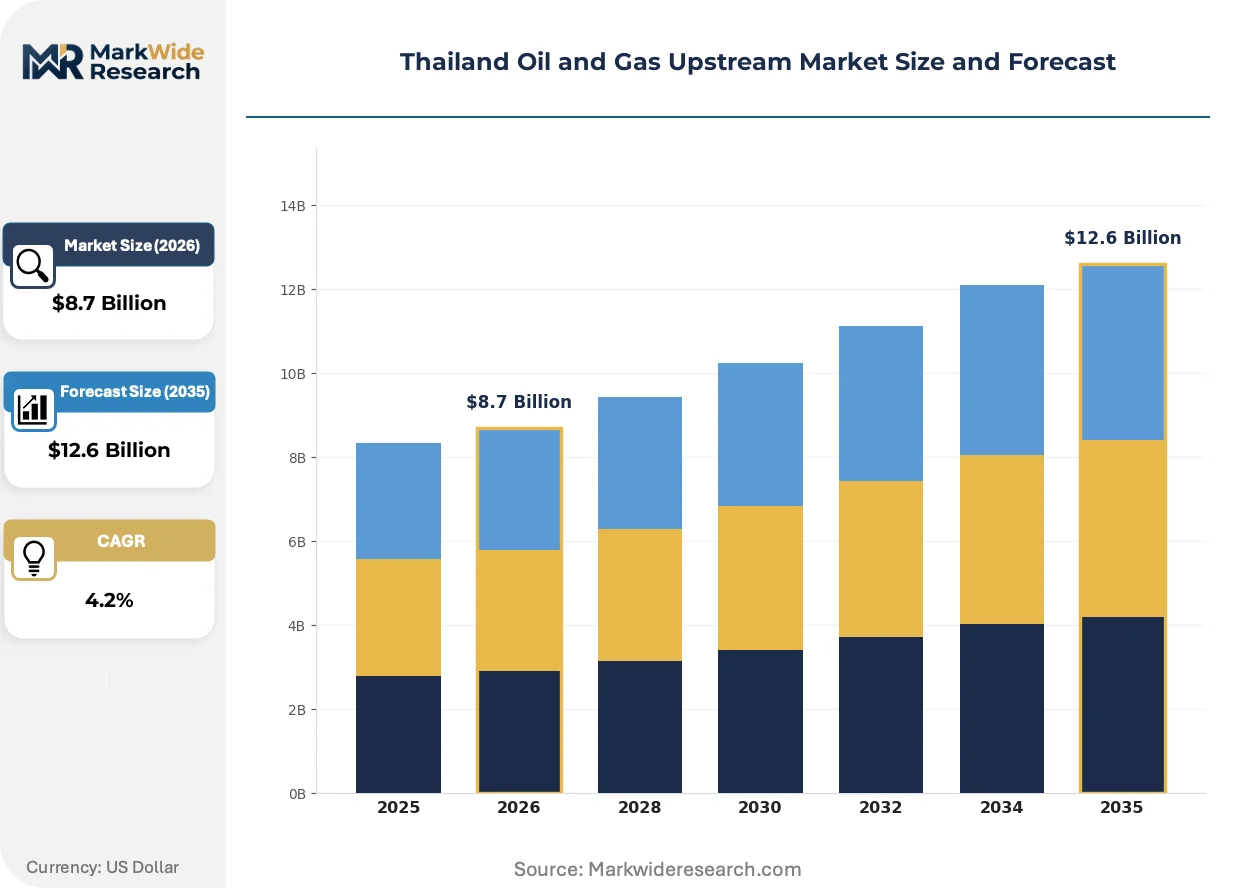
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Offshore Drilling, Onshore Drilling, Hydraulic Fracturing, Seismic Survey Service Type: E&P Services, Well Completion, Reservoir Management, Production Optimization Equipment Type: Drilling Rigs, Subsea Equipment, Pumps, Compressors Application: Exploration, Production, Development, Enhanced Recovery |
| Companies Covered | Mitsui Oil Exploration (MOECO), TotalEnergies SE, PTTEP, Palang Sophon Ltd., KrisEnergy, Chevron Thailand E&P, Mubadala Energy Thailand, Bangchak Corp., Valeura Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Oil and Gas Upstream Market Evolving Landscape
Digitalization and emissions accountability are redefining how Thailand's upstream operators extract value from aging assets. Technology deployment now prioritizes recovery optimization over pure volume growth.
Advanced subsea processing systems are integrating multiphase pumping and wet gas compression at the seabed. PTTEP and concession partners deploy these units to extend plateau production from remote well clusters. The technology is integrating marginal field economics into development planning by eliminating surface platform capital.
Thailand's Environmental Impact Assessment requirements now mandate methane monitoring and flaring reduction across all drilling permits. The national environmental regulator enforces continuous emissions reporting tied to license renewals. Offshore gas processing facilities face the steepest compliance costs, driving investment in vapor recovery and closed-flare systems.
Integrated service contracts are displacing discrete equipment procurement across well construction programs. Operators bundle directional drilling, logging, and completion services under single-vendor arrangements. This consolidation concentrates in the Gulf of Thailand's brownfield campaigns where campaign efficiency outweighs unit cost minimization.
Thailand Oil and Gas Upstream Market Segmentation
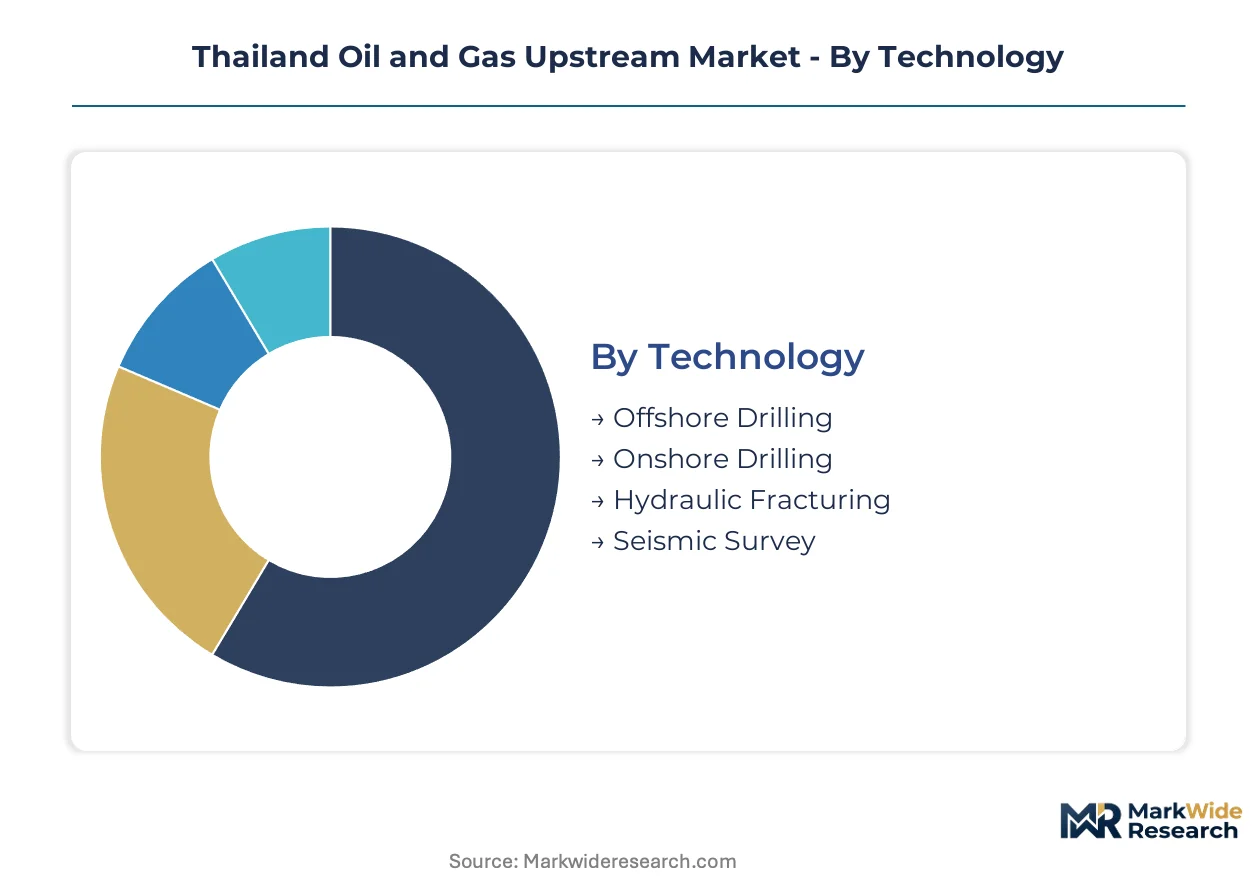
Segmentation of Thailand's upstream market reveals how capital flows concentrate across distinct technical domains and service categories. Equipment procurement patterns and contractor selection criteria vary sharply between offshore gas developments and marginal field redevelopment campaigns.
Technology:
Offshore drilling platforms and seismic acquisition systems dominate supplier order books across the Gulf of Thailand, while onshore tight gas projects in the northeast drive specialized fracturing demand.
- Offshore Drilling:Jack-up rigs and platform drilling packages target the Pattani Trough and Erawan-Bongkot field complexes at water depths reaching 100 meters. PTTEP and concession partners anchor fleet utilization through multi-well development programs.
- Onshore Drilling:Conventional rotary rigs and workover units concentrate on the Khorat Plateau's tight sandstone formations. Horizontal well campaigns require precision directional steering and underbalanced drilling capabilities.
- Hydraulic Fracturing:Multi-stage stimulation unlocks low-permeability reservoirs in the Phu Horm and Nam Phong fields.
- Seismic Survey:3D and 4D acquisition supports field redevelopment and carbon storage site characterization.
Offshore drilling absorbs the bulk of installed capacity; hydraulic fracturing is expanding most quickly.
Service Type:
Integrated service bundling is displacing discrete procurement as operators prioritize campaign efficiency over unit cost optimization across brownfield developments.
- E&P Services:Exploration and production contracts span seismic interpretation, drilling management, and field development planning. International operators rely on these services to meet local content requirements under Department of Mineral Fuels frameworks.
- Well Completion:Perforating, gravel packing, and intelligent completion installations command premium margins where reservoir compartmentalization demands bespoke design. Subsea tieback completions dominate Gulf of Thailand campaign schedules.
- Reservoir Management:Static and dynamic modeling services optimize depletion strategies across mature gas fields.
- Production Optimization:Artificial lift design and gas compression scheduling extend plateau production from declining wells.
Well completion captures the steepest margin pools; production optimization is gaining share fastest as fields mature.
Equipment Type:
Capital deployment concentrates on subsea infrastructure and compression systems that eliminate surface platform requirements for marginal field developments.
- Subsea Equipment:Multiphase pumps, wet gas compressors, and subsea processing modules integrate at the seabed to extend remote well cluster economics. These systems reduce development capex for stranded reserves in the Pattani Trough.
- Drilling Rigs:Jack-up units and platform rigs constitute the largest equipment category by contracted value. Regional rig availability constraints shape campaign timing for PTTEP and foreign operators.
- Pumps:Electrical submersible and hydraulic pumping systems support artificial lift programs.
- Compressors:Onshore and offshore compression trains maintain delivery pressure for gas pipeline specifications.
Subsea equipment commands the highest unit capital intensity; pumps represent the largest installed base by unit count.
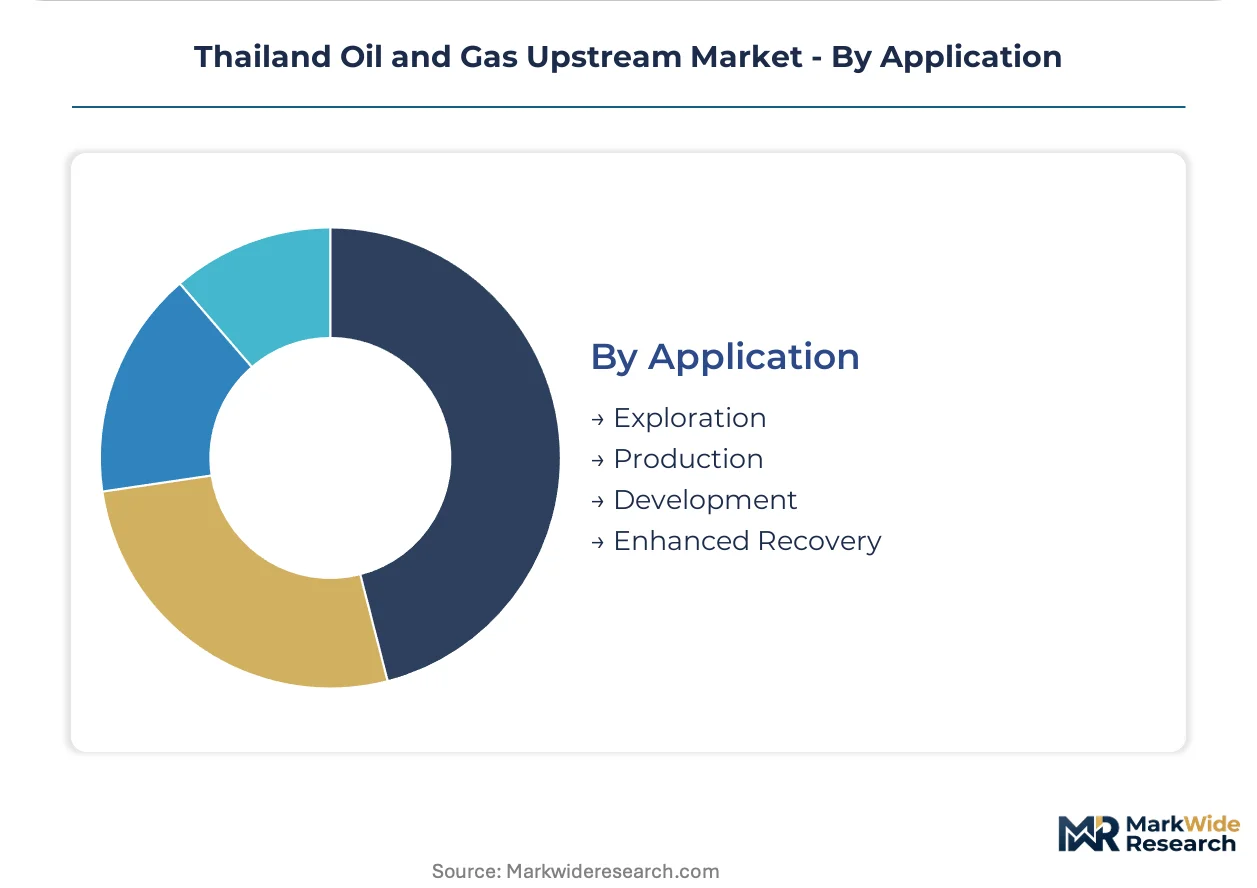
Application:
Activity mix is shifting from greenfield exploration toward enhanced recovery and redevelopment as legacy fields deplete and exploration success rates decline.
- Production:Sustaining output from the Erawan, Bongkot, and satellite fields dominates operational expenditure. Gas processing and pipeline delivery infrastructure supports state utility offtake agreements.
- Enhanced Recovery:Gas injection, chemical EOR, and pressure maintenance programs qualify for extended concession terms under Petroleum Act incentives. These projects target recovery factor improvements in depleted Gulf of Thailand blocks.
- Exploration:Frontier drilling in deeper water and unconventional plays attracts limited capital allocation.
- Development:Greenfield project execution concentrates on marginal field tiebacks and platform upgrades.
Production accounts for the majority of recurring service demand; enhanced recovery is climbing the fastest as operators pursue concession extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf of Thailand's Pattani Trough anchors upstream activity, with Bangkok-based operators coordinating offshore campaigns and Rayong's petrochemical corridor consuming the bulk of natural gas output.
Central Gulf Coast
The Pattani Trough and Erawan-Bongkot field complexes drive jack-up rig demand and subsea infrastructure deployment. The Department of Mineral Fuels administers production-sharing contracts that shape foreign operator economics. Rayong's Map Ta Phut industrial estate processes associated gas for power generation and chemical feedstock.
Northeastern Khorat Plateau
Tight sandstone formations in Khon Kaen and Udon Thani provinces attract horizontal drilling specialists targeting unconventional gas reserves. The Petroleum Act incentivizes enhanced recovery projects with extended concession terms. Nam Phong and Phu Horm field clusters anchor onshore service contractor activity.
Southern Peninsula
The Malay Basin's marginal fields offshore Songkhla and Nakhon Si Thammarat test subsea tieback economics. Environmental Impact Assessment requirements govern flaring limits and decommissioning bonds. Operators trial modular FPSO solutions to unlock stranded reserves at reduced capital intensity.
Bangkok Metropolitan Administration
Corporate headquarters and technical service centers concentrate in the capital, with PTTEP and concession partners coordinating field operations from central offices. The national environmental regulator enforces methane monitoring tied to license renewals. Engineering procurement functions cluster in the central business district.
Thailand Oil and Gas Upstream Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical specialization and concession access. The upstream sector consolidates around state-affiliated operators with dominant acreage holdings and international majors with deepwater expertise. Three archetypes define competitive positioning: integrated national champions controlling legacy concessions, international oil companies deploying specialized subsea capabilities, and independent developers targeting marginal field opportunities. Consolidation pressure favors operational scale and portfolio diversification as primary defensive moves.
Within the national champion tier, PTTEP anchors domestic production through its Erawan and Bongkot field dominance. Chevron Thailand E&P exemplifies international major positioning through operational scale at the Pattani Trough. TotalEnergies SE occupies a specialized niche via subsea expertise at the M9 and M11 blocks. These three represent distinct competitive archetypes rather than interchangeable market participants.
| Leading Market Players |
|---|
| Mitsui Oil Exploration (MOECO) |
| TotalEnergies SE |
| PTTEP |
| Palang Sophon Ltd. |
| KrisEnergy |
| Chevron Thailand E&P |
| Mubadala Energy Thailand |
| Bangchak Corp. |
| Valeura Energy |
| Others |
Value Network & Pricing Analysis
Thailand's Environmental Impact Assessment requirements for methane monitoring and flaring reduction gate qualified supply access and premium-tier pricing for compliant service providers. Operators lacking vapor recovery systems or closed-flare infrastructure face exclusion from high-margin well completion contracts, concentrating pricing power among certified contractors.
Pricing Analysis
Outcome-based pricing tied to production uptime and recovery factor improvements anchors premium service tiers in Thailand's upstream market. Well completion services command the steepest margins where reservoir compartmentalization demands bespoke perforation design. Cost compression in standard drilling services is intensifying because jack-up rig dayrate volatility erodes contractor margins. National operators with dominant concession holdings exhibit the lowest price sensitivity; independent developers targeting marginal fields show the highest.
Supply Chain Analysis
Thailand's Department of Mineral Fuels local-content mandates reshape sourcing patterns for subsea equipment and specialized drilling services. Fabrication of jack-up rigs and platform packages draws from Singapore, South Korea, and China. Critical inputs include high-grade steel forgings, subsea umbilicals, and directional drilling electronics. Single-source vulnerability concentrates in deepwater vessel availability for Pattani Trough campaigns. Distribution runs through Bangkok-based engineering procurement offices coordinating Rayong port logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's upstream sector is consolidating around operational scale and concession access as maturing reservoirs and tightened fiscal terms squeeze weaker contractors from brownfield campaigns.
For Market Incumbents:Acquire subsea engineering talent pools to offset the scarcity of deepwater completion designers threatening project execution timelines. Lock in long-term jack-up rig contracts before regional demand cycles tighten vessel availability. Backward integration into artificial lift manufacturing secures margin capture as production optimization services gain share.
For New Entrants and Emerging Players:Thailand's revised Petroleum Act incentives for enhanced recovery projects open a window for specialized chemical EOR and gas injection service providers. Target marginal field redevelopment campaigns in the Malay Basin where modular FPSO solutions reduce capital barriers. Pursue partnerships with PTTEP as carried-interest obligations constrain foreign operator independence.
For Investors and Strategic Acquirers:Concession extension announcements under enhanced recovery mandates are the leading indicator that stranded reserve economics are improving. Over a multi-year horizon, acquisition targets cluster around subsea equipment fabricators with wet gas compression capabilities and digital twin platform developers. Watch for carbon storage site characterization contracts as signals of sequestration revenue materialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Processing Integration | Eliminates surface platform capital for Pattani Trough marginal fields. |
| Enhanced Recovery Certification | Qualifies operators for Petroleum Act concession extensions. |
| Digital Twin Deployment | Optimizes artificial lift scheduling across Erawan-Bongkot complexes. |
| Carbon Capture Site Characterization | Positions depleted gas fields for national climate framework credits. |
| Integrated Service Bundling | Consolidates directional drilling, logging, and completion under single vendors. |
Research Methodology
Regulatory filings from Thailand's Department of Mineral Fuels, Environmental Impact Assessment records, and concession round documentation formed the secondary backbone for market sizing. Primary interviews with upstream project managers, drilling contractors, subsea equipment procurement leads, and reservoir engineering consultants validated operational assumptions. Bottom-up rig count and service line revenue estimates triangulated against top-down national production forecasts.
Historical trendline analysis of jack-up rig utilization, well completion campaign counts, and enhanced recovery project awards established baseline growth patterns. Segmentation modeling spanned technology type, service category, equipment class, and application focus across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating power sector gas offtake agreements and petrochemical feedstock requirements.
The model assumes a particular technology adoption path for subsea processing and digital twin deployment; alternative pathways for carbon capture integration would alter the outlook. Forecasts reflect assumptions around concession term negotiations and reservoir complexity limits. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sucker Rod Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Well Casing Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market