
 Global Deep-Well Disposal Services Market | 2026-2036
Global Deep-Well Disposal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Deep-Well Disposal Services Market Analysis
Class I hazardous waste certification is unwinding the competitive landscape for deep-well disposal services. Clean Harbors, Inc. anchors its position through vertical integration across waste collection, transportation, and injection operations. Weatherford International plc leverages specialized wellbore construction expertise to compete in high-pressure formation projects. Baker Hughes Company dominates technology leadership with advanced monitoring and cementing systems that extend well integrity.
Deep-well disposal services involve the engineered injection of liquid wastes into confined geologic formations at depths typically exceeding one thousand meters below freshwater aquifers, requiring casing programs, cement bonds, and continuous pressure monitoring to prevent subsurface contamination. The primary purpose is permanent isolation of industrial effluents, produced water, and hazardous byproducts from biological and hydrological systems. Commercial service providers capture the largest margin pools through long-term offtake contracts with oil and gas producers, while hazardous waste streams command premium pricing due to stringent EPA permitting and liability structures. Monitoring solutions within the technology segment represent the fastest-growing category as operators face intensified real-time reporting obligations.
EPA Underground Injection Control regulations, OSHA workplace safety standards, and state-level environmental agency permits collectively shape market access and operational compliance costs for deep-well operators. The EU Green Deal and REACH frameworks constrain cross-border waste movements, redirecting European industrial effluent toward domestic treatment or third-country disposal. Stakeholders must monitor evolving seismicity protocols and induced earthquake liability thresholds as regulators link injection volumes to subsurface stress changes.
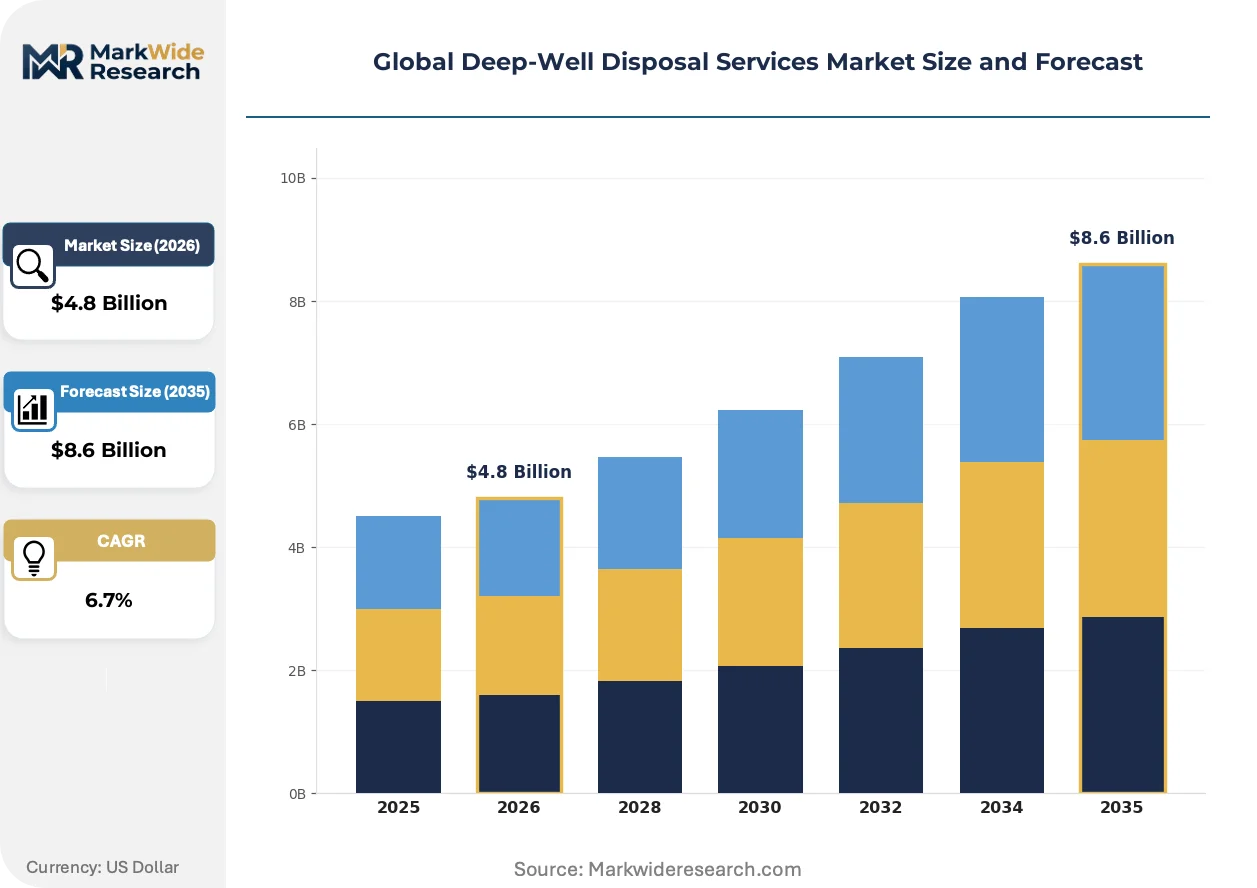
Market Dynamics
Class I hazardous waste certification is compressing supply availability while EPA Underground Injection Control rulemaking accelerates permit timelines, creating a structural bottleneck where qualified disposal capacity commands premium offtake terms.
Growth Catalysts
- Produced water volumes:Permian Basin oil and gas operators generate rising effluent streams requiring permanent geologic isolation, tightening available injection capacity and extending contract durations.
- REACH framework constraints:European industrial effluent faces restricted cross-border movement under EU Green Deal directives, redirecting hazardous liquid waste toward certified deep-well networks.
- Texas Railroad Commission seismicity protocols:Stricter induced earthquake monitoring requirements in the Midland-Odessa corridor are consolidating permitted capacity under operators with advanced pressure management systems.
Market Restraints
- Specialized casing steel supply:High-collapse-grade tubulars for high-pressure formations concentrate with limited domestic mills, exposing project timelines to metals price volatility.
- Permit approval timelines:EPA Underground Injection Control Class I certification requires 18-24 month review cycles, freezing capital deployment until final authorization.
- Surface treatment alternatives:Advanced evaporation and crystallization technologies for produced water reduce dependency on subsurface disposal in water-scarce regions.
Strategic Opportunities
- Brazil pre-salt development:Offshore production growth generates untreated effluent volumes lacking sufficient onshore disposal infrastructure, opening greenfield permit positions.
- Real-time monitoring convergence:Fiber-optic distributed temperature sensing combined with AI-driven pressure analytics enables predictive well integrity management.
- Carbon capture co-injection:Class VI sequestration wells share subsurface characterization requirements with hazardous waste disposal, allowing dual-use asset development.
Industry Challenges
- Geoscience talent scarcity:Reservoir engineering expertise for high-pressure formation characterization remains concentrated among retiring specialists, constraining project velocity.
- Legacy wellbore integration:Converting depleted oil and gas wells to disposal service requires cement bond re-evaluation and mechanical integrity testing under current EPA standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Deep-Well Disposal Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Commercial, Industrial, Hazardous Waste, Non-Hazardous Waste End User: Oil & Gas, Mining, Utilities, Chemical Manufacturing Regulatory Compliance: Federal Standards, State Regulations, Local Ordinances, International Guidelines Technology: Injections Systems, Waste Treatment, Monitoring Solutions, Waste Analysis |
| Companies Covered | Weatherford International plc, Clean Harbors, Inc., Halliburton Company, R360 Environmental Solutions, Veolia Environnement S.A., Baker Hughes Company, National Oilwell Varco, Inc., SCS Engineers, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Deep-Well Disposal Services Market Emerging Trajectories
Deep-well disposal operations are digitizing monitoring infrastructure while regulatory frameworks tighten real-time reporting obligations, compressing the window between anomaly detection and corrective response.
Advanced fiber-optic sensing is fragmenting traditional pressure-monitoring architectures. Distributed acoustic sensing cables deployed along casing strings detect micro-seismic events and fluid movement in real time. Major Permian and Bakken operators now specify fiber-inclusive completion designs for new Class I wells. This capability is fragmenting the market between technology-equipped providers and conventional pressure-monitoring vendors.
EPA Underground Injection Control rulemaking is mandating continuous mechanical integrity verification. The 2024 proposed amendments require automated pressure transient analysis and quarterly external mechanical integrity testing. Service providers in Texas, Louisiana, and Oklahoma are retrofitting existing wellheads with automated shutoff systems. Small independent operators lacking capital reserves face accelerated asset retirement.
Long-term offtake contracting is displacing spot-market disposal arrangements. Oil and gas producers seek 10-15 year volume commitments to secure capacity amid permit scarcity. Midstream companies in the Delaware Basin now structure take-or-pay agreements with minimum volume guarantees. This shift is most pronounced among Permian operators with multi-decade drilling inventories.
Global Deep-Well Disposal Services Market Segmentation
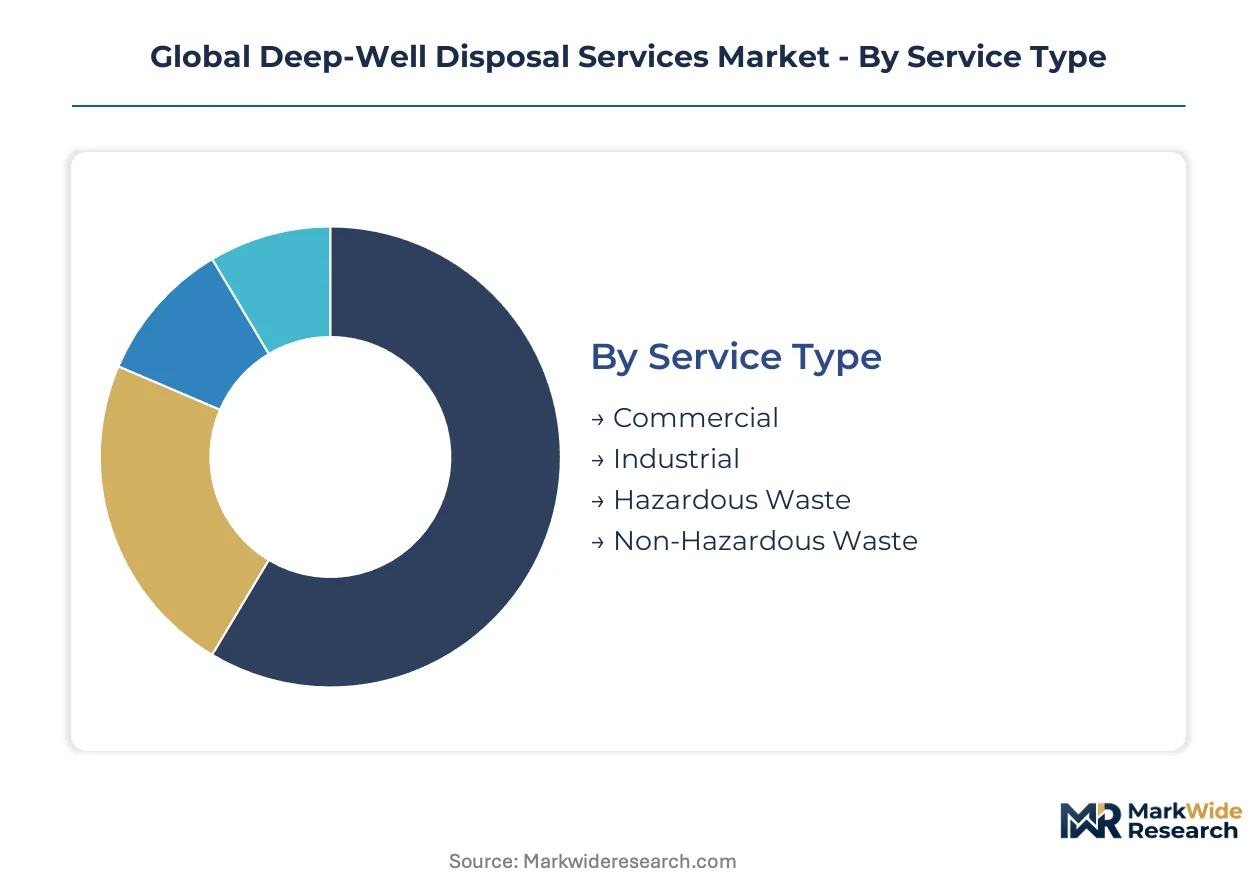
Deep-well disposal services fragment across service tiers, regulatory jurisdictions, and technical capabilities that determine project economics and competitive positioning. Understanding these segment boundaries clarifies where operators capture premium returns versus commodity margins.
Service Type:
Commercial services concentrate in Texas, Louisiana, and Oklahoma where Class I permitting infrastructure is mature, while hazardous waste streams increasingly cross borders to access certified capacity.
- Commercial:Third-party providers operate injection facilities under long-term offtake contracts with oil and gas producers. Permian Basin operators dominate demand as produced water volumes strain surface treatment alternatives.
- Industrial:Captive disposal infrastructure serving single-site manufacturing or refining complexes. Chemical plants along the Gulf Coast maintain dedicated well networks to isolate process effluents from product liability exposure.
- Hazardous Waste:EPA Class I certification mandates specialized casing programs, cement bonds, and continuous pressure monitoring. Premium pricing reflects 18-24 month permit timelines and stringent liability structures.
- Non-Hazardous Waste:Produced water and brine streams requiring geologic isolation without hazardous classification. Delaware Basin midstream companies structure minimum volume guarantees to secure capacity.
Hazardous waste holds the largest share; momentum sits with commercial services as independents exit under capital pressure.
End User:
Volume concentration varies sharply by sector, with oil and gas generating effluent streams measured in billions of barrels annually while mining and utilities operate at smaller scale.
- Oil & Gas:Permian, Bakken, and Eagle Ford operators generate rising produced water volumes as drilling intensifies. Midland-Odessa corridor seismicity protocols now restrict injection rates, tightening available capacity.
- Mining:Extractive operations produce acid mine drainage and process water requiring permanent isolation. Appalachian coal regions and Western copper belts drive domestic demand.
- Utilities:Coal-fired power plants discharge flue gas desulfurization wastewater and ash pond effluent. EPA effluent limitation guidelines redirect these streams toward deep-well networks as surface discharge permits tighten.
- Chemical Manufacturing:Petrochemical complexes along the Houston Ship Channel and Louisiana River Corridor generate organic and inorganic liquid byproducts. REACH framework constraints in Europe redirect cross-border effluent toward domestic disposal capacity.
Oil and gas commands the dominant volume position; utilities are gaining share fastest as coal plant wastewater regulations tighten.
Regulatory Compliance:
Permit jurisdiction determines project feasibility timelines, with federal Class I certification creating the highest barriers to market entry.
- Federal Standards:EPA Underground Injection Control rules govern well construction, mechanical integrity testing, and area-of-review requirements. Proposed amendments mandate automated pressure transient analysis and quarterly external mechanical integrity verification.
- State Regulations:Texas Railroad Commission seismicity protocols, Louisiana Department of Environmental Quality permits, and Oklahoma Corporation Commission rules layer additional operational constraints. State-level induced earthquake liability thresholds vary significantly.
- Local Ordinances:County-level zoning and setback requirements affect facility siting. Permian Basin counties increasingly impose buffer zones around residential development.
- International Guidelines:EU Green Deal directives constrain cross-border waste movements. Brazil's ANVISA and environmental agency frameworks govern pre-salt development effluent disposal.
Federal standards represent the binding constraint for premium capacity; state regulations are expanding fastest as seismicity protocols proliferate.
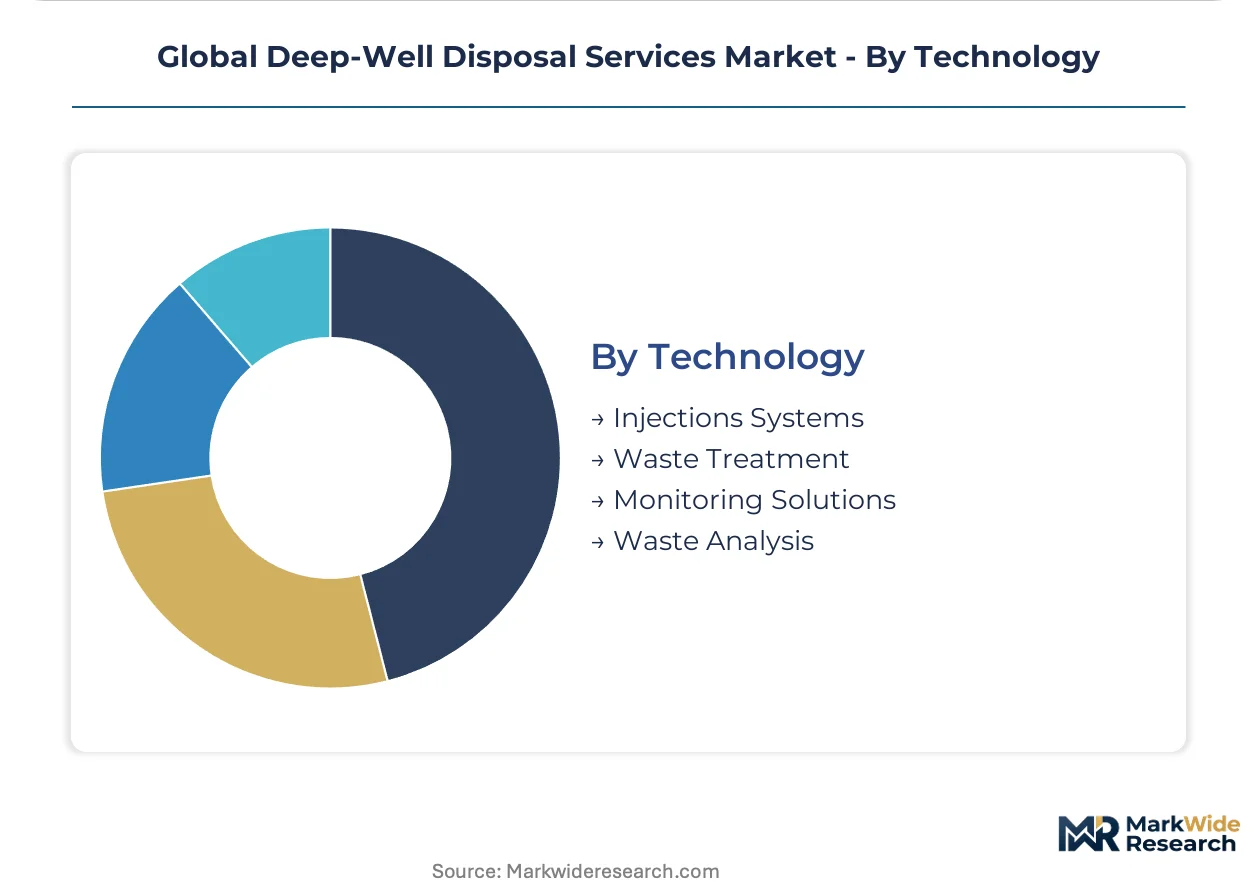
Technology:
Capital allocation shifts toward monitoring infrastructure as real-time reporting obligations compress response windows for anomaly detection.
- Injections Systems:High-pressure pumps, wellhead assemblies, and automated shutoff systems manage fluid delivery into confined formations. Advanced fiber-optic sensing is fragmenting traditional pressure-monitoring architectures.
- Waste Treatment:Pre-injection conditioning including filtration, pH adjustment, and compatibility testing. Surface treatment alternatives including evaporation and crystallization reduce subsurface disposal dependency in water-scarce regions.
- Monitoring Solutions:Distributed acoustic sensing cables deployed along casing strings detect micro-seismic events and fluid movement in real time. Major Permian and Bakken operators now specify fiber-inclusive completion designs.
- Waste Analysis:Laboratory characterization of chemical composition, radioactivity, and compatibility with formation fluids. AI-driven pressure analytics enable predictive well integrity management.
Injection systems anchor current revenue; monitoring solutions are climbing the fastest as digitization mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of hazardous liquid waste from European chemical manufacturers increasingly terminate at United States disposal facilities as REACH framework constraints tighten cross-border movement permissions. Import dependency for certified deep-well capacity concentrates in Texas, Louisiana, and Oklahoma terminals. Domestic infrastructure gaps in Brazil and Middle Eastern production zones create outbound shipment volumes toward established North American networks.
United States
Permian Basin oil and gas operators generate produced water volumes exceeding surface treatment capacity, forcing permanent geologic isolation commitments. EPA Underground Injection Control Class I certification timelines stretch to 24 months, freezing new capacity deployment. Midland-Odessa corridor seismicity protocols now restrict injection rates under Texas Railroad Commission oversight, consolidating permitted operations under pressure-managed facilities.
Canada
Alberta oil sands bitumen extraction produces tailings pond effluent requiring deep-well disposal as surface containment regulations tighten. The country's national environmental regulator layers provincial permitting with federal impact assessments for cross-border waste movements. Calgary-based midstream companies now structure long-term offtake agreements with United States disposal networks to secure capacity amid domestic permit scarcity.
Brazil
Pre-salt offshore oil development generates untreated production effluent lacking sufficient onshore disposal infrastructure, creating import demand for treatment technology. ANVISA and the national environmental agency framework govern effluent characterization but permit timelines lag production growth. Rio de Janeiro state petrochemical complexes increasingly contract international service providers for hazardous waste stream certification.
Germany
Rhine-Ruhr chemical manufacturing clusters face restricted export pathways for hazardous liquid byproducts under EU Green Deal waste shipment controls. ECHA REACH compliance costs redirect domestic effluent toward specialized treatment facilities or third-country disposal. Bavarian industrial zones now invest in captive deep-well networks to isolate process wastewater from product liability exposure.
Saudi Arabia
Eastern Province oil production generates rising formation water volumes as mature fields require enhanced recovery operations. The national environmental regulator implements groundwater protection standards modeled on EPA Underground Injection Control frameworks. Jubail Industrial City petrochemical complexes evaluate dedicated disposal well construction to replace evaporative lagoon treatment systems.
Global Deep-Well Disposal Services Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. Publicly traded environmental services conglomerates anchor market structure through integrated waste collection-to-injection operations, while private operators concentrate in regional hazardous waste niches. Three archetypes dominate: vertically integrated environmental services platforms, oilfield service technology providers, and specialized waste management contractors. Capacity expansion and strategic partnerships constitute the primary competitive moves as permit scarcity extends contract durations.
Within the integrated environmental services tier, Clean Harbors, Inc. and Veolia Environnement S.A. exemplify operators combining waste collection infrastructure with certified disposal assets. Weatherford International plc and Baker Hughes Company occupy positions among oilfield service technology providers leveraging wellbore construction expertise for high-pressure formation projects.
| Leading Market Players |
|---|
| Weatherford International plc |
| Clean Harbors, Inc. |
| Halliburton Company |
| R360 Environmental Solutions |
| Veolia Environnement S.A. |
| Baker Hughes Company |
| National Oilwell Varco, Inc. |
| SCS Engineers |
| Schlumberger Limited |
| Others |
Supply Flow & Price Mechanics
EPA Underground Injection Control Class I certification gates both supply qualification and price differentiation simultaneously, compressing available disposal capacity while elevating premium tiers for hazardous waste streams that clear stringent mechanical integrity and area-of-review standards.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing as the dominant model, with hazardous waste streams commanding premium tiers over non-hazardous produced water based on permit scarcity and liability exposure. Price differentiation rests on certification grade and volume scale, where minimum volume guarantees secure preferential rates amid capacity constraints. Cost compression in non-hazardous tiers is intensifying because surface treatment alternatives reduce dependency on subsurface disposal. Midstream operators in the Permian Basin demonstrate lowest price sensitivity due to regulatory-driven capacity lock-in, while independent oil and gas producers face acute sensitivity to per-barrel disposal costs.
Supply Chain Analysis
Extended lead times for high-collapse-grade casing steel concentrate inventory risk with domestic mills in the United States, Japan, and Germany. Raw material dependencies draw from specialized tubular manufacturing, cement additives for zonal isolation, and fiber-optic sensing cables. Single-source vulnerability runs through limited domestic steel capacity for extreme-pressure formations. Distribution feeds from mill-direct procurement through oilfield service distributors to disposal facility operators, with project-based logistics dominating high-volume hazardous waste movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep-well disposal services occupy early-cycle expansion as produced water volumes from unconventional oil and gas development outpace surface treatment capacity, driving permanent geologic isolation commitments across North American production basins.
For Market Incumbents: Consolidate permitted capacity positions in the Midland-Odessa corridor under Texas Railroad Commission seismicity protocols before regulatory thresholds tighten further. Acquire fiber-optic monitoring capabilities to defend against technology-equipped entrants fragmenting the pressure-monitoring segment. Backward integration into waste collection infrastructure deepens customer captivity and secures volume commitments. For New Entrants and Emerging Players: Real-time monitoring service layers remain under-served by legacy pressure-monitoring vendors, creating entry points for AI-driven predictive analytics providers. Brazil pre-salt development offers the most penetrable geography given lagging onshore disposal infrastructure. Partner with international oilfield service technology providers to bypass capital-intensive well construction barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across monitoring solutions as digitization mandates spread, favoring asset-light technology specialists over heavy infrastructure plays. Target acquisition archetypes include regional hazardous waste specialists with mature Class I permits and proprietary geologic characterization databases. Watch EPA Underground Injection Control rulemaking velocity as the signal for permit scarcity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Permit Portfolio Expansion | Class I certification in Texas and Louisiana secures decades-long revenue visibility under EPA Underground Injection Control rules. |
| Fiber-Optic Monitoring Deployment | Distributed acoustic sensing cables differentiate service providers as real-time reporting obligations compress response windows. |
| Long-Term Offtake Contracting | Take-or-pay agreements with Permian Basin operators lock in minimum volume guarantees amid structural capacity scarcity. |
| Carbon Capture Co-Injection Development | Class VI sequestration wells leverage shared subsurface characterization with hazardous waste disposal for dual-use asset economics. |
| Brazil Greenfield Permit Positioning | ANVISA framework navigation captures pre-salt production effluent volumes lacking sufficient domestic disposal infrastructure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating disposal facility engineering directors, oil and gas producer water management leads, EPA Underground Injection Control permitting specialists, and oilfield service technology procurement managers. Secondary validation drew from EPA permit databases, Texas Railroad Commission seismicity incident reports, SEC 10-K environmental liability disclosures, and IEA unconventional oil production water intensity benchmarks. Bottom-up facility capacity modeling triangulated against top-down oil and gas produced water volume projections.
Across the analysis window, forecasts segmented by service tier, regulatory compliance jurisdiction, waste stream classification, and end-use sector concentration. CAGR derivation incorporated historical permit approval velocity, produced water-to-oil ratios by basin maturity, and regulatory amendment implementation timelines. Modeled inputs included Permian Basin drilling inventory projections and EU Green Deal waste shipment restriction enforcement patterns.
Forecasts assume regulatory continuity in EPA Underground Injection Control and Texas Railroad Commission seismicity protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Oil Hose Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Well Cementing Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Global Completion Equipment and Services Market