
 Romania Oil and Gas Market | 2026-2036
Romania Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Oil and Gas Market Analytics
API-grade specification upgrades across upstream extraction is reorganizing procurement priorities for Romanian operators. OMV Petrom SA leverages integrated refining and retail networks across the Carpathian Basin. Romgaz SA anchors domestic natural gas supply through mature onshore fields in Transylvania. Black Sea Oil & Gas differentiates through offshore development expertise at the Neptun Deep block.
Romania oil and gas encompasses crude petroleum extraction, natural gas recovery, refining operations, and hydrocarbon distribution through pipeline and retail networks, with sulfur content below 0.5% for refined diesel meeting EU transport fuel standards. The sector powers electricity generation, industrial process heat, and petrochemical feedstock supply for Central European manufacturing. Exploration services dominate capital allocation as operators target Black Sea deepwater reserves, while distribution infrastructure remains the most mature segment with established pipeline corridors. Processing unit technology commands premium pricing due to EU emissions compliance requirements and refinery modernization mandates.
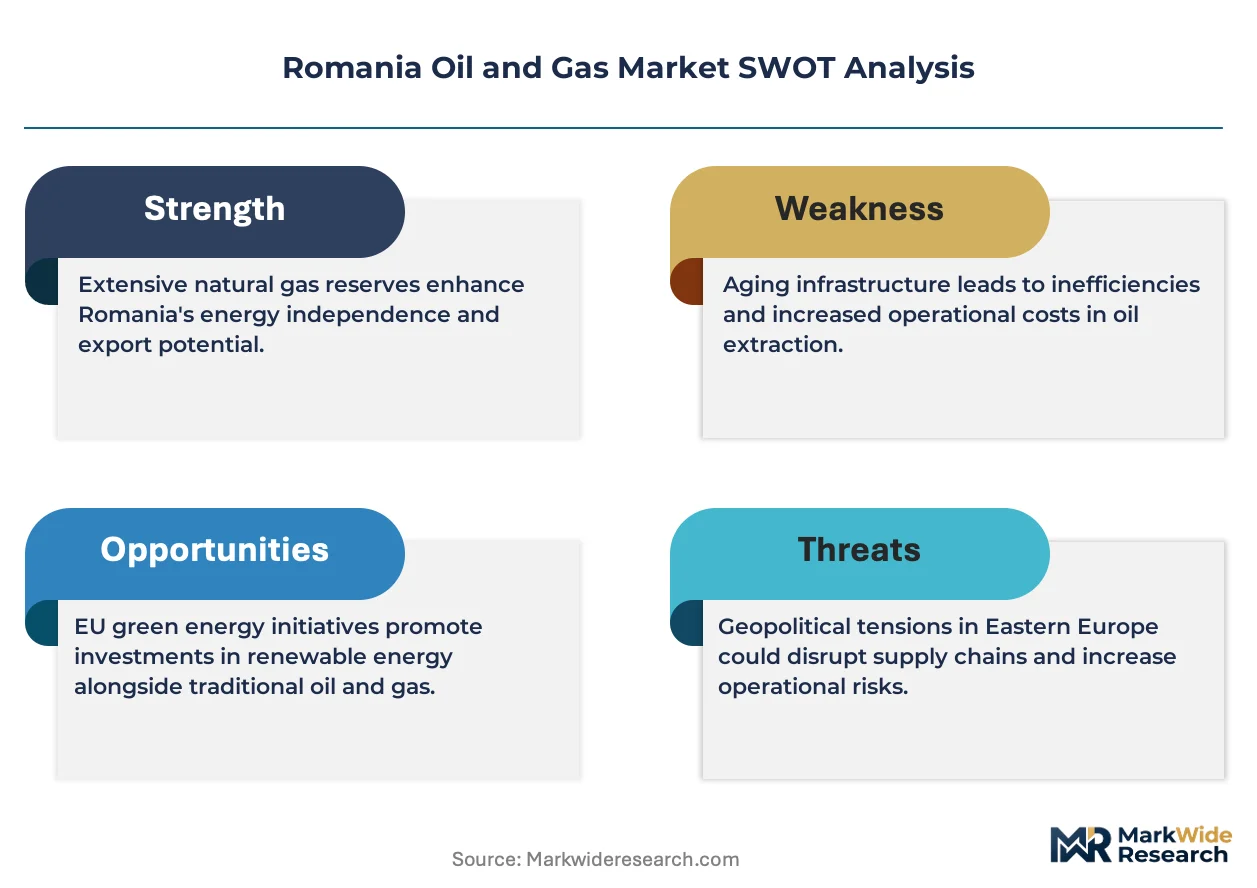
Romania's National Agency for Mineral Resources, the Romanian Energy Regulatory Authority, and EU F-Gas Regulation collectively shape offshore concession terms, pipeline tariff structures, and equipment emissions standards for market participants. ANRE's transmission access rules directly determine independent producer market entry feasibility for new Black Sea field developers. Stakeholders must monitor regulatory clarity on offshore fiscal terms before committing final investment decisions for deepwater extraction platforms.
Market Dynamics
Black Sea deepwater exploration is redrawing Romania's upstream investment map as operators deploy capital toward Neptun Deep development while navigating tighter fiscal terms from the National Agency for Mineral Resources.
Growth Catalysts
- EU F-Gas Regulation:Equipment emissions standards are accelerating refinery modernization programs across Ploiești industrial corridors, creating replacement demand for processing units.
- Petrochemical feedstock localization:Domestic Black Sea production is displacing imported naphtha supplies for Transylvania polymer manufacturing facilities.
- Muntenia demand concentration:Bucharest industrial corridors and surrounding refineries concentrate hydrocarbon offtake, reducing distribution logistics costs for pipeline operators.
Market Restraints
- Offshore licensing friction:ANRE's tightened concession terms compress capital deployment timelines and elevate project abandonment risk for deepwater developers.
- Pipeline tariff rigidity:Transmission access rules limit independent producer market entry, constraining supply diversification for new Black Sea field operators.
- Refinery margin compression:EU emissions compliance mandates elevate processing costs relative to non-European competitors, pressuring domestic refining economics.
Strategic Opportunities
- Transylvania carbon capture integration:Mature onshore gas fields offer geological storage capacity for industrial emissions reduction projects.
- API-grade specification upgrades:Enhanced extraction standards create premium equipment procurement windows for domestic service providers.
- Bucharest corridor hydrogen blending:Existing natural gas infrastructure enables pilot programs for industrial heat decarbonization.
Industry Challenges
- Deepwater engineering talent scarcity:Specialized subsea platform construction expertise concentrates outside Romania, requiring imported labor or training partnerships.
- Legacy refinery integration complexity:Modern emissions control systems must interface with mid-20th century processing units without extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Oil and Gas Market |
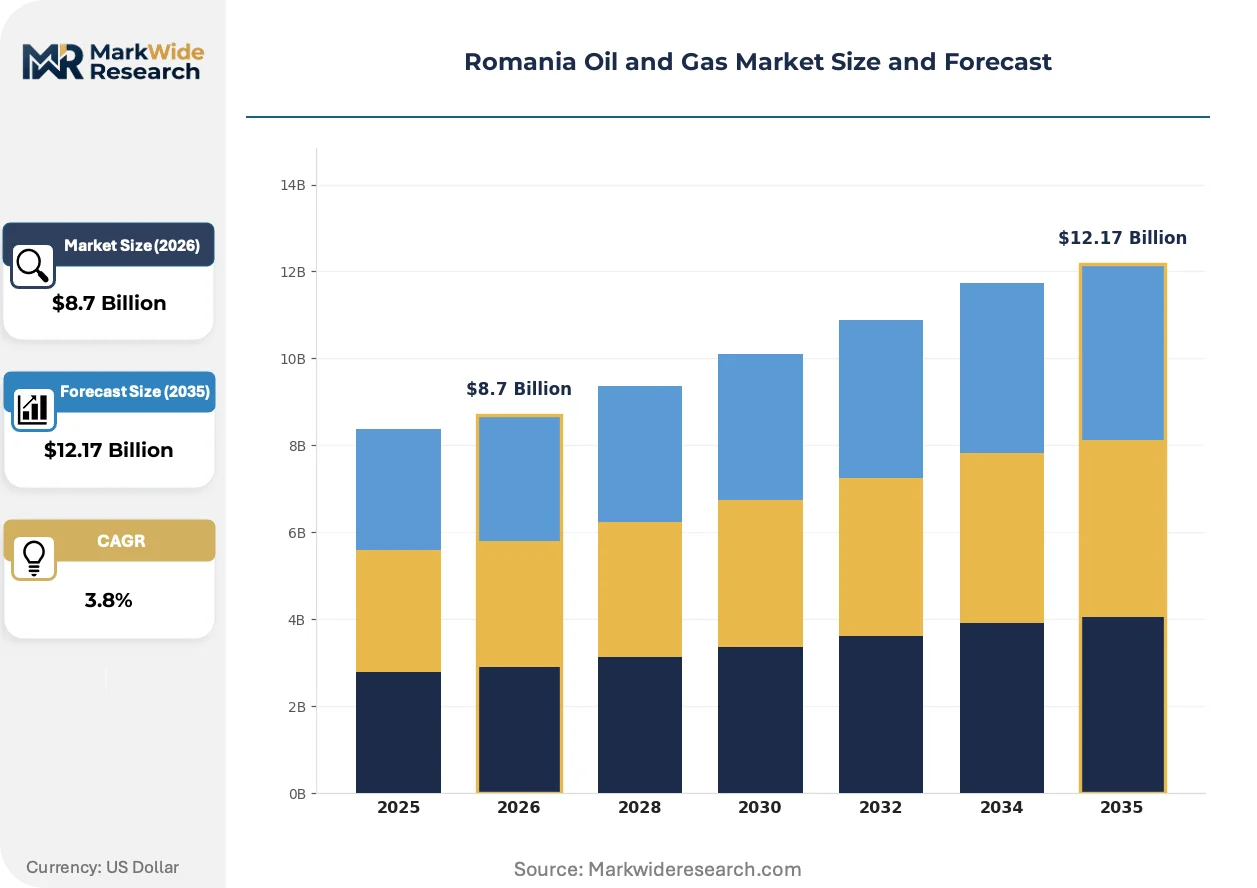
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Distribution Technology: Seismic Survey, Drilling Equipment, Processing Units, Safety Systems End User: Utilities, Industrial Sectors, Residential Clients, Petrochemical Plants Application: Electricity Generation, Fuel Production, Heating, Chemical Manufacturing |
| Companies Covered | TotalEnergies SE, Rompetrol S.A., OMV Petrom SA, SOCAR, Black Sea Oil & Gas, Romgaz SA, Lukoil Oil Company, MOL Group, Exxon Mobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Oil and Gas Market Evolving Landscape
Digital reservoir characterization and automated drilling systems are compressing exploration timelines while regulatory pressure on methane intensity reshapes operational priorities across Romanian extraction assets.
Subsea tieback architecture is displacing conventional platform development for marginal Black Sea fields. Independent operators favor satellite well connections to existing processing infrastructure. This approach is displacing capital-intensive standalone facility construction, lowering breakeven thresholds for deepwater exploration.
EU F-Gas Regulation phase-down schedules are mandating refrigerant transitions in LNG handling and gas processing equipment. Romanian operators face accelerated replacement cycles for cooling systems. Midstream infrastructure around Constanța port facilities bears the highest compliance burden due to cryogenic storage requirements.
Long-term offtake contracting is fragmenting as industrial buyers seek shorter tenors with price reopener clauses. Petrochemical plants in the Ploiești cluster now negotiate annual supply adjustments rather than decade-long agreements. This pattern concentrates among polymer producers exposed to volatile naphtha input costs.
Romania Oil and Gas Market Segmentation
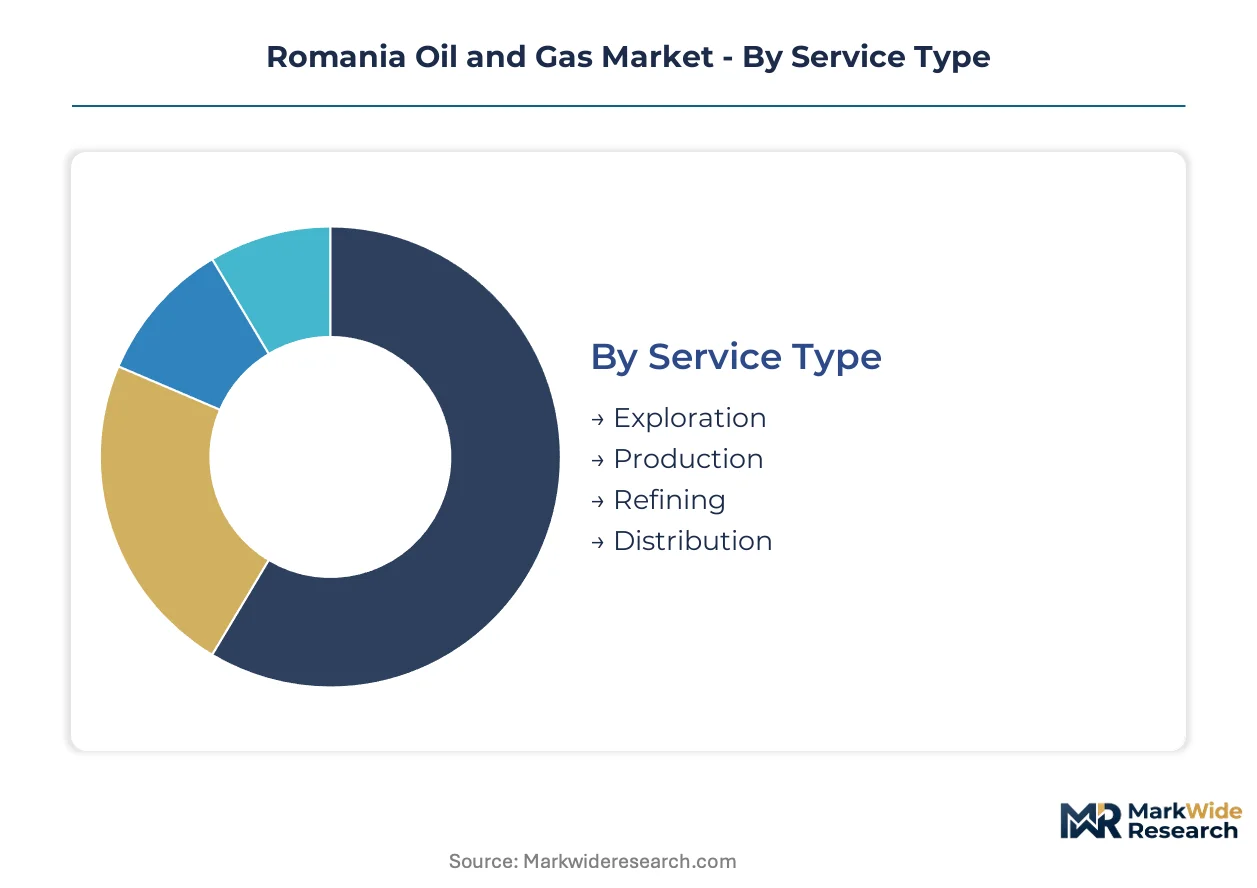
Romania's oil and gas segmentation reveals distinct procurement patterns across upstream exploration, midstream processing, and downstream distribution. Each category carries specific regulatory footprints from ANRE and the National Agency for Mineral Resources that shape supplier selection criteria and capital allocation priorities.
Service Type:
Domestic operators concentrate capital in production and refining segments serving Muntenia industrial corridors, while exploration services draw international contractors for Black Sea deepwater projects.
- Exploration:Seismic surveying and reservoir characterization services target Neptun Deep block development. ANRE's tightened offshore licensing terms compress capital deployment timelines for seismic contractors bidding on deepwater concessions.
- Production:Extraction operations span mature onshore fields in Transylvania and emerging Black Sea platforms. Romgaz SA anchors domestic supply through mature gas fields while independent operators develop offshore reserves.
- Refining:Processing operations concentrate around Ploiești industrial clusters meeting EU transport fuel sulfur specifications below 0.5%. EU F-Gas Regulation mandates drive modernization programs for emissions control systems.
- Distribution:Pipeline and retail networks serve Bucharest industrial corridors with established infrastructure. Transmission access rules determine independent producer market entry feasibility for new field developers.
Refining commands the established base. The steepest expansion runs through exploration.
Technology:
Equipment procurement stratifies between high-specification offshore systems commanding premium pricing and standardized onshore technologies serving mature field operations.
- Seismic Survey:Advanced 3D and 4D imaging systems map Black Sea subsurface structures for Neptun Deep development. Contractors face compressed timelines between survey completion and licensing submission deadlines.
- Drilling Equipment:Deepwater rigs and directional drilling systems access offshore reserves beneath 100+ meter water depths. Specialized subsea platform construction expertise concentrates outside Romania, requiring imported labor or training partnerships.
- Processing Units:Refinery modernization programs replace mid-20th century equipment with EU emissions-compliant systems. Ploiești facilities integrate new emissions control without extended shutdown windows.
- Safety Systems:Blowout preventers, fire suppression, and emergency shutdown equipment meet offshore regulatory mandates. ANRE inspection protocols drive replacement cycles for aging platform safety infrastructure.
Processing units command the established base. The steepest expansion runs through drilling equipment.
End User:
Demand concentration varies sharply between large-volume industrial offtake in Muntenia and dispersed residential consumption across Transylvania and Moldova.
- Utilities:Power generators and district heating operators procure natural gas under long-term supply agreements. Bucharest industrial corridors concentrate the highest volume offtake for combined heat and power facilities.
- Industrial Sectors:Manufacturing facilities in Ploiești and surrounding regions consume refined products and process heat. Steel, cement, and ceramics producers face carbon reduction pressures affecting fuel switching decisions.
- Residential Clients:Household heating demand concentrates in urban centers with established gas distribution networks. Rural areas rely on propane and heating oil where pipeline infrastructure remains underdeveloped.
- Petrochemical Plants:Polymer manufacturers in Transylvania source naphtha feedstock from domestic Black Sea production displacing imported supplies. Annual supply adjustments with price reopener clauses replace decade-long agreements.
Industrial sectors command the established base. The steepest expansion runs through petrochemical plants.
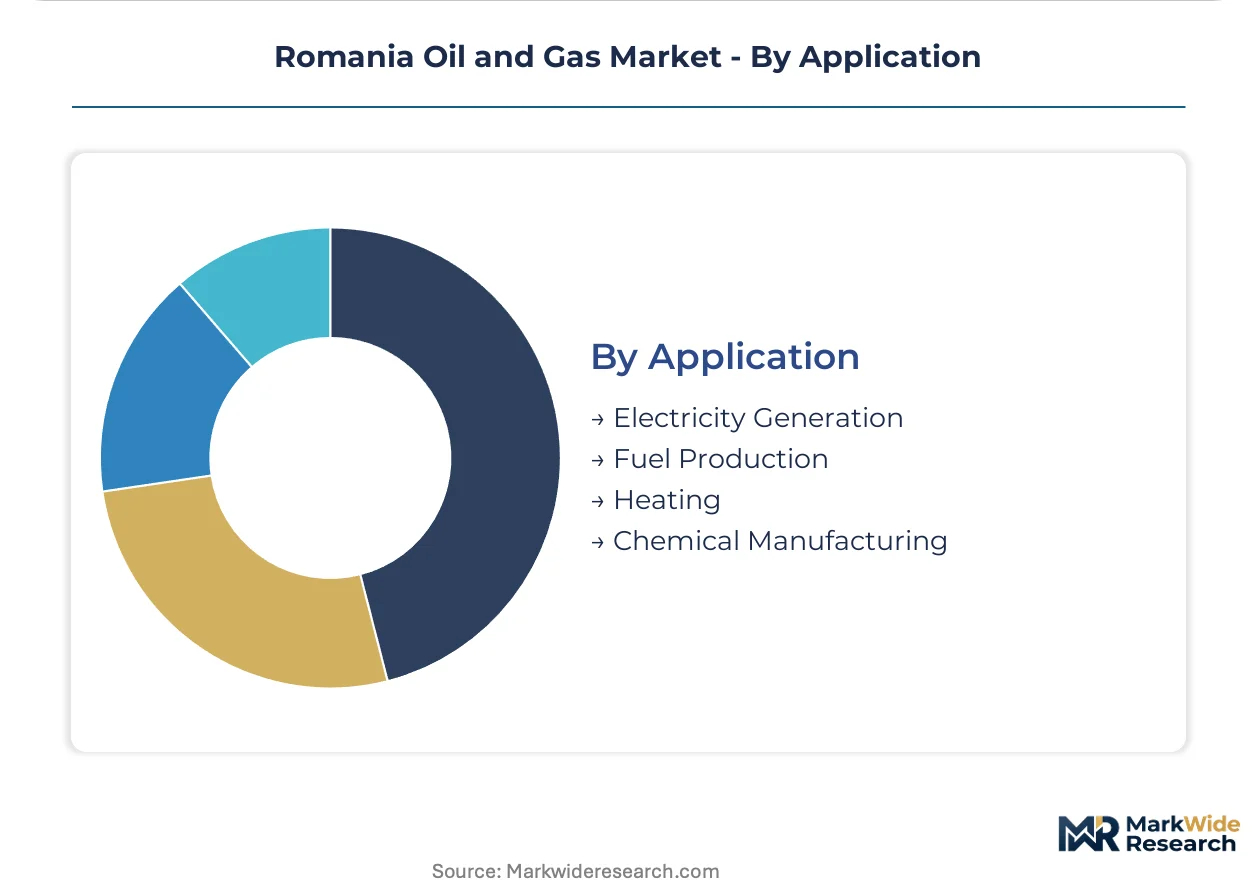
Application:
End-use applications span energy conversion, material transformation, and thermal services with distinct regulatory compliance burdens under EU emissions frameworks.
- Electricity Generation:Natural gas-fired turbines provide dispatchable capacity balancing renewable intermittency. Grid operators prioritize domestic Black Sea supply for energy security objectives.
- Fuel Production:Refined diesel and gasoline meet EU transport specifications for sulfur content and biofuel blending mandates. Ploiești refineries supply Central European markets through established pipeline corridors.
- Heating:Residential and commercial thermal applications consume natural gas through district networks and individual boilers. Seasonal demand peaks strain transmission capacity during winter months.
- Chemical Manufacturing:Hydrocarbon feedstocks supply polymer, fertilizer, and specialty chemical production. Transylvania facilities leverage geological storage capacity in mature gas fields for carbon capture integration.
Fuel production commands the established base. The steepest expansion runs through chemical manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream investment clusters around the Black Sea continental shelf while refining capacity concentrates in the Ploiești industrial corridor. Distribution infrastructure radiates from Bucharest toward Transylvania and Moldova. Regulatory authority from ANRE and the National Agency for Mineral Resources shapes capital deployment across all three zones.
Muntenia
Ploiești refineries and Bucharest industrial corridors drive hydrocarbon offtake concentration. EU F-Gas Regulation mandates accelerate emissions control modernization at processing facilities. Petrochemical plants in this zone are expanding feedstock purchases from domestic Black Sea production.
Transylvania
Mature onshore gas fields anchor Romgaz SA's domestic supply operations. The region offers geological storage capacity for carbon capture integration projects. Cluj-Napoca and surrounding industrial areas consume natural gas for manufacturing process heat.
Dobrogea
Constanța port facilities bear the highest EU F-Gas compliance burden due to cryogenic LNG storage requirements. Black Sea Oil & Gas operates offshore development at the Neptun Deep block from this coastal zone. Midstream infrastructure connects deepwater production to onshore processing terminals.
Moldova
Rural heating demand relies on propane and heating oil where pipeline infrastructure remains underdeveloped. Residential consumption patterns differ sharply from industrial Muntenia. Iasi and regional urban centers represent expansion targets for gas distribution network operators.
Romania Oil and Gas Market Competitive Landscape
Concentration sits with integrated national champions controlling refining and retail networks across the Carpathian Basin. The competitive structure tiers between offshore specialists, state-backed incumbents, and international majors with Black Sea concessions. Strategic archetypes include vertically integrated refiners, deepwater exploration specialists, and regional downstream distributors. Dominant competitive moves involve portfolio diversification into petrochemical feedstocks and strategic partnerships for subsea engineering capacity.
Among integrated operators, OMV Petrom SA and Romgaz SA represent the state-affiliated tier with established onshore production bases. Black Sea Oil & Gas occupies a specialist position in deepwater development. International majors including TotalEnergies SE and Exxon Mobil Corporation exemplify the concession-holder archetype targeting Neptun Deep reserves. Lukoil Oil Company and MOL Group represent regional Eastern European players with cross-border downstream networks. SOCAR and Rompetrol S.A. anchor the import-dependent refining segment.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Rompetrol S.A. |
| OMV Petrom SA |
| SOCAR |
| Black Sea Oil & Gas |
| Romgaz SA |
| Lukoil Oil Company |
| MOL Group |
| Exxon Mobil Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracting with annual price reopener clauses locks in supply access for Ploiești petrochemical plants while preserving visibility on naphtha input costs against volatile Black Sea production benchmarks. This structure concentrates pricing power with integrated operators controlling both upstream extraction and downstream processing assets.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across Romanian hydrocarbon processing equipment. Three-tier pricing structure across premium, standard, and economy levels separates API-certified subsea systems from standardized onshore drilling packages. Cost compression in mid-range processing units is intensifying because refinery modernization programs demand emissions-compliant replacements without extended shutdown windows. Industrial buyers in the Muntenia corridor exhibit the highest price sensitivity due to volatile polymer feedstock margins, while offshore operators at Neptun Deep demonstrate lower sensitivity given project finance structures.
Supply Chain Analysis
Extended lead times for subsea platform components stretch procurement timelines beyond compressed ANRE licensing deadlines. Equipment sourcing draws from Germany, Norway, and South Korea for high-specification drilling systems and emissions control technology. Raw material dependencies center on specialized steel alloys, high-pressure valves, and cryogenic storage materials. Single-source vulnerability concentrates in subsea engineering expertise requiring imported labor or training partnerships. Distribution runs through Constanța port facilities connecting Black Sea production to Ploiești refining corridors and Bucharest industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in automated reservoir monitoring and predictive maintenance contracts are expanding faster than hardware sales as operators prioritize operational uptime over capital equipment ownership. Recurring revenue from digital asset management layers offers superior margin stability compared to episodic exploration equipment procurement.
For Market Incumbents: Shield integrated refining positions by accelerating backward integration into Black Sea feedstock supply before independent producers secure transmission access. Prioritize certification investment in EU F-Gas-compliant processing systems to capture replacement cycles at Ploiești facilities. Channel control through captive pipeline networks limits competitor market entry under ANRE's tariff structures.
For New Entrants and Emerging Players: Lead with subsea engineering partnerships targeting marginal field tieback architectures at Neptun Deep satellite developments. White-space concentration sits in cryogenic storage modernization at Constanța LNG terminals facing accelerated refrigerant transition timelines. Petrochemical feedstock localization in Transylvania polymer manufacturing offers the most penetrable entry angle through naphtha supply contracts with annual adjustment clauses.
For Investors and Strategic Acquirers: Specialist offshore contractors with subsea platform construction expertise represent the priority acquisition archetype given talent scarcity outside Romania. Long-term viability hinges on regulatory clarity from the National Agency for Mineral Resources stabilizing fiscal terms across the analysis window. The signal to watch is final investment decision announcements for deepwater extraction platforms indicating capital deployment confidence.
| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Tieback Architecture Deployment | Reduces breakeven thresholds for marginal Black Sea fields through satellite well connections. |
| EU F-Gas Compliance Modernization | Captures replacement demand at Ploiești refineries facing emissions control mandates. |
| Domestic Feedstock Integration | Displaces imported naphtha supplies for Transylvania polymer manufacturing facilities. |
| Carbon Capture Storage Partnerships | Leverages mature Transylvania gas fields for industrial emissions reduction projects. |
| Hydrogen Blending Pilot Programs | Utilizes existing Bucharest corridor infrastructure for industrial heat decarbonization trials. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork engaged upstream project developers at Black Sea Oil & Gas, refinery operations directors at Ploiești industrial clusters, ANRE regulatory affairs specialists, and petrochemical procurement managers at Transylvania polymer facilities. Secondary sources incorporated National Agency for Mineral Resources concession databases, EU F-Gas Regulation implementation schedules, ANRE transmission tariff filings, and customs records tracking hydrocarbon equipment imports. Bottom-up segment sizing triangulated against top-down macroeconomic energy demand projections.
Sensitivity analysis across regulatory scenario variants tests forecast robustness over the projection horizon. The analytical framework models value trajectories across service type, technology tier, end-user category, and application segment dimensions. CAGRs derive from weighted average growth patterns across upstream exploration, midstream processing, and downstream distribution channels. Key inputs include Black Sea reserve certification timelines, refinery modernization capex cycles, and petrochemical feedstock substitution elasticities.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules and ANRE offshore fiscal frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Frac Stack Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Well Casing Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
United Kingdom LNG Market