
 Middle-East and Africa Pigging Services Market | 2026-2036
Middle-East and Africa Pigging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Pigging Services Market Foresight
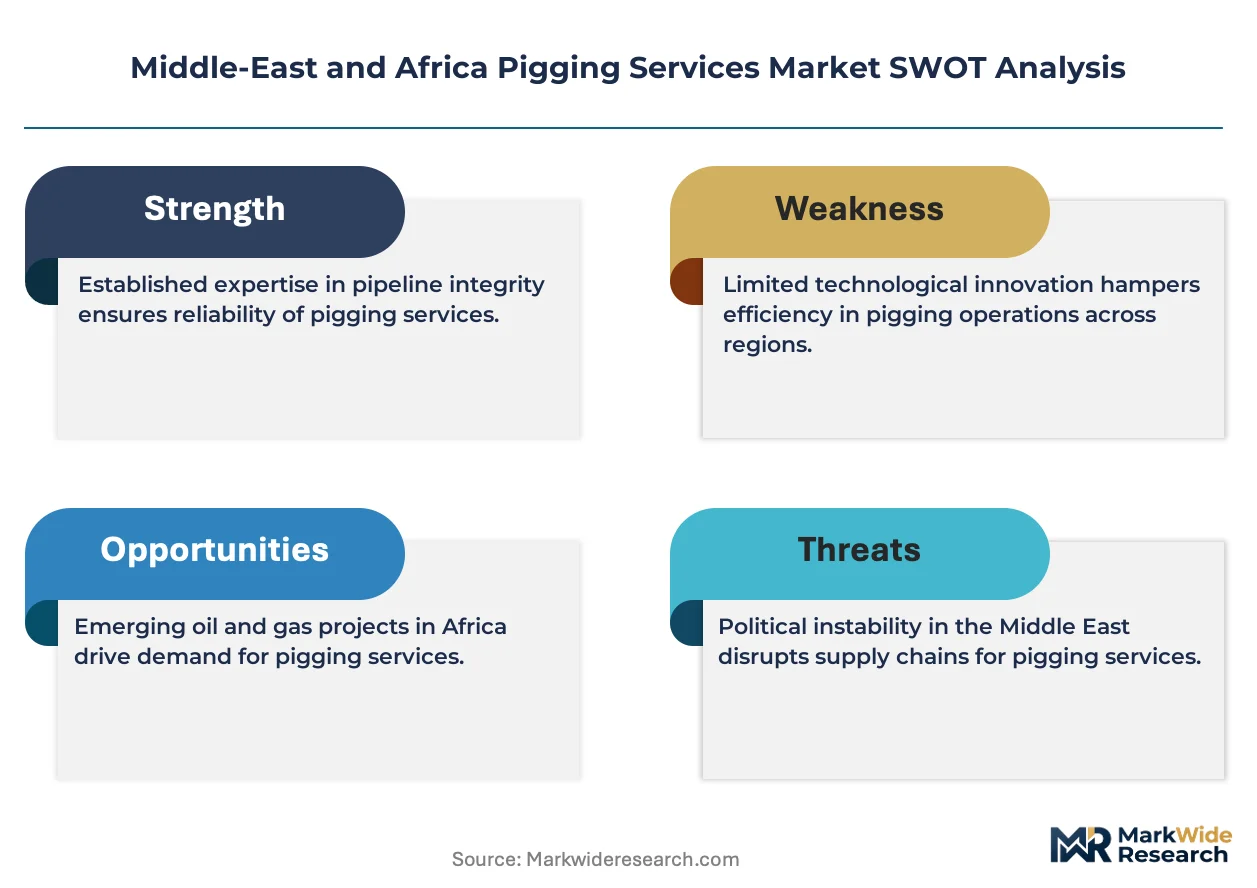
Midstream operators are unwinding capital allocation from greenfield construction toward lifecycle asset management. T.D. Williamson Inc. leverages its technology leadership in magnetic flux leakage inspection systems across Saudi Aramco contracts. Baker Hughes Company anchors its regional position through integrated cleaning and diagnostic service bundles. NDT Global Services Ltd differentiates via ultrasonic crack detection capabilities tailored to sour gas environments.
Pigging services encompass the mechanical propulsion of devices through pipelines to execute cleaning, inspection, or product separation without system shutdown, typically operating at pressures between 30 and 200 bar depending on pipeline classification and fluid characteristics. The primary commercial purpose centers on maintaining throughput efficiency, preventing catastrophic failure, and extending asset life in hydrocarbon and process fluid networks. Smart pigs equipped with inertial mapping and multi-sensor arrays command premium pricing within the technology dimension, while reactive pigs retain volume share in routine debris removal. Cleaning services generate the largest revenue pool by service type, though inspection contracts exhibit superior margin profiles due to data analytics add-ons.
Saudi Arabia's national standards body and the UAE's civil defense authorities enforce mandatory inline inspection intervals for cross-border hydrocarbon lines, creating recurring demand cycles independent of commodity price swings. South Africa's occupational health and safety regulator extends coverage to chemical processing corridors, broadening pigging applicability beyond oil and gas. Egypt's petroleum ministry has drafted pipeline integrity regulations modeled on Gulf precedents, signaling jurisdictional expansion. Stakeholders must calibrate technology portfolios against divergent national certification requirements rather than treating the region as a unified compliance zone.
Market Dynamics
Pipeline integrity mandates across the Gulf Cooperation Council are forcing midstream operators to convert reactive maintenance into predictive asset management programs, reshaping contract structures toward multi-year inspection frameworks.
Growth Catalysts
- Mandatory Inline Inspection Protocols:Saudi Arabia's national standards body enforces recurring assessment intervals for hydrocarbon transport lines, creating recurring revenue streams independent of oil price cycles.
- Niger Delta Infrastructure Rehabilitation:Chronic corrosion and vandalism in Nigeria's onshore networks drives demand for combined cleaning and diagnostic pigging services.
- Sour Gas Field Development:Ultrasonic crack detection technologies address hydrogen-induced cracking in high-sulfide environments across UAE and Qatar production corridors.
Market Restraints
- Specialized Equipment Import Dependency:Magnetic flux leakage toolsets and sensor arrays originate from North American and European fabrication centers, exposing operators to currency volatility and extended lead times.
- Skilled Technician Scarcity:Certified pipeline inspection engineers concentrate in Saudi Arabia and the UAE, constraining service expansion into Egypt and Algeria.
- Alternative Monitoring Technologies:Distributed acoustic sensing and fiber-optic leak detection systems compete for capital allocation in greenfield pipeline designs.
Strategic Opportunities
- Egyptian Regulatory Alignment:Draft pipeline integrity regulations modeled on Gulf precedents signal jurisdictional expansion for established service providers.
- Chemical Processing Corridor Diversification:South Africa's occupational health and safety regulator extends coverage to industrial chemical networks, broadening pigging applicability beyond hydrocarbons.
- Data Analytics Service Bundling:Inspection contractors can capture margin expansion by integrating predictive failure modeling with raw sensor outputs.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Divergent national qualification requirements across Saudi Arabia, UAE, and Egypt force technology portfolio calibration rather than standardized service deployment.
- Legacy Pipeline Compatibility:Aging infrastructure with irregular diameters and weld seam variations limits smart pig navigation and data quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Pigging Services Market |
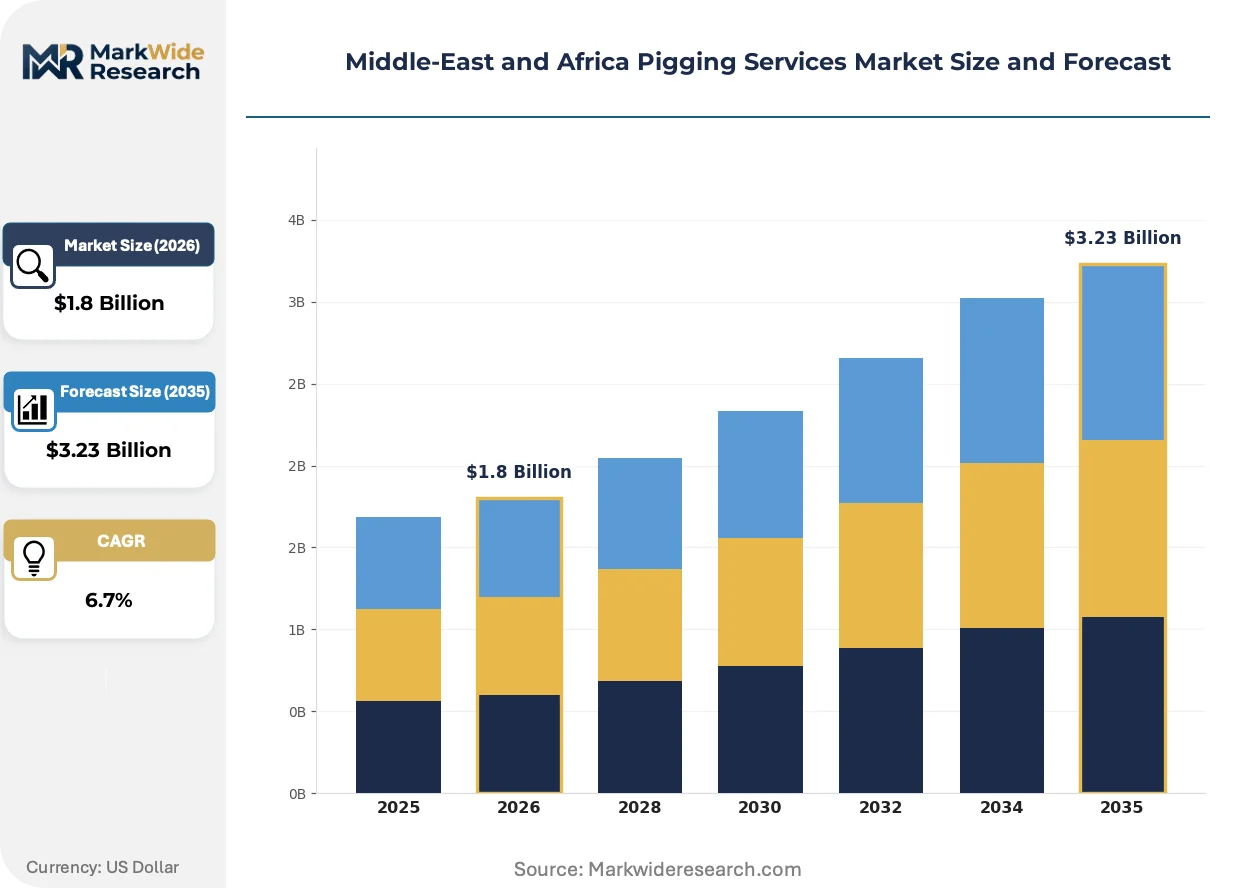
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Inspection, Maintenance, Product Separation End User: Oil & Gas, Water Utilities, Chemical Manufacturers, Food Processing Technology: Smart Pigs, Reactive Pigs, Inline Pigs, Specialty Pigs Application: Pipelines, Storage Tanks, Process Equipment, Marine Vessels |
| Companies Covered | ROSEN Group, T.D. Williamson Inc., Baker Hughes Company, NDT Global Services Ltd, SGS SA, Enduro Pipeline Services, A.Hak Industrial Services, IGP Pipeline Services, CleanGas Solutions, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Pigging Services Market Shifts & Advancements
Sensor fusion architectures and autonomous propulsion systems are redefining operational capabilities, while regulatory harmonization efforts and procurement model evolution reshape commercial relationships across the value chain.
Multi-sensor smart pigs integrating magnetic flux leakage, ultrasonic testing, and inertial mapping are fragmenting the traditional service hierarchy between specialized inspection contractors and general maintenance providers. National oil companies in Saudi Arabia and the UAE now specify combined geometry and metal-loss assessment in single-run contracts. This convergence compresses pricing power for single-technology vendors while elevating integrated service premiums.
Saudi Arabia's national standards body and the UAE's civil defense authorities have synchronized mandatory inline inspection intervals for cross-border hydrocarbon lines. This regulatory alignment reduces operational flexibility for operators but creates predictable demand cycles for certified service providers. Egyptian regulators are drafting comparable frameworks, extending compliance geography southward.
Long-term service agreements with embedded performance guarantees are displacing transactional spot contracts in Abu Dhabi and Qatar. National oil companies now bundle cleaning, inspection, and remediation under unified vendor accountability. This shift concentrates procurement volume with integrated providers and marginalizes specialized single-service contractors in the Gulf's largest markets.
Middle-East and Africa Pigging Services Market Segmentation
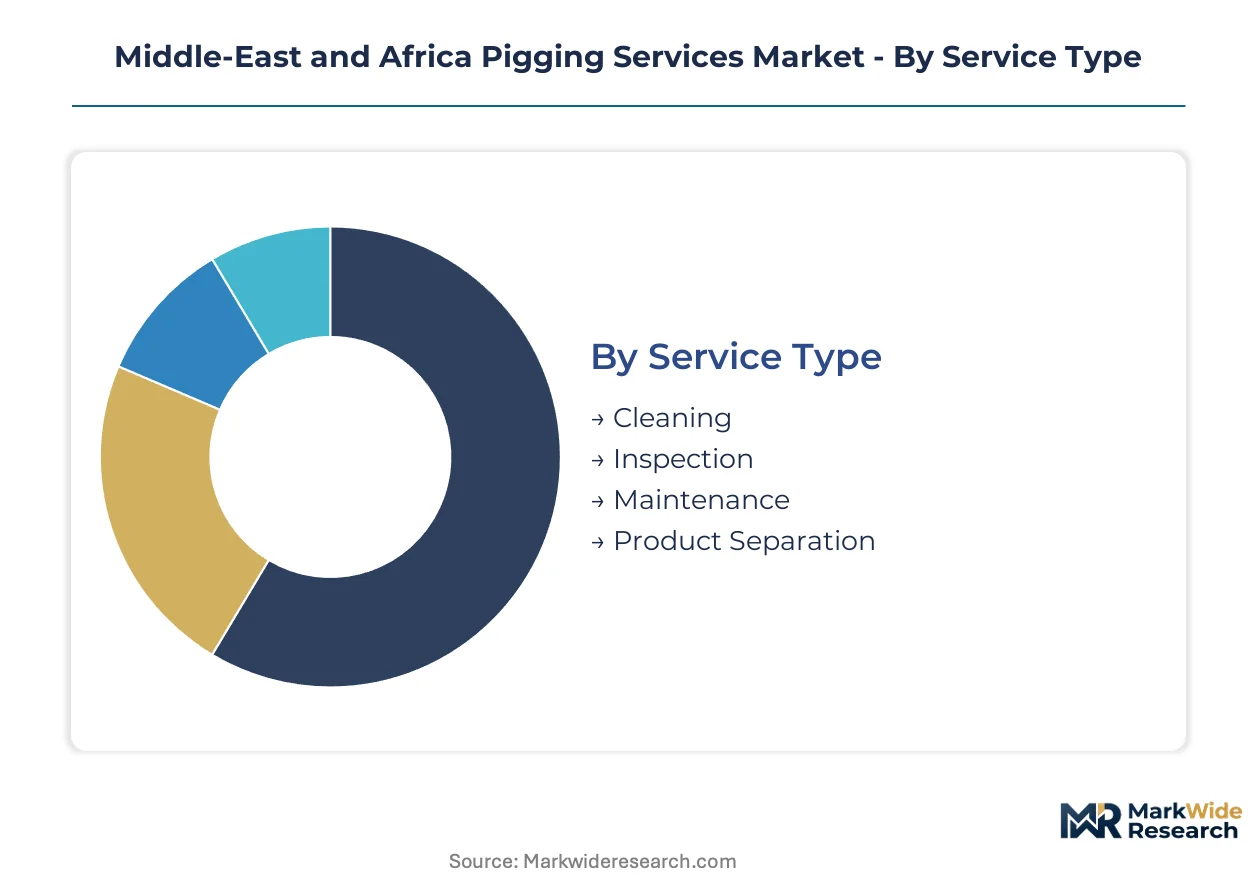
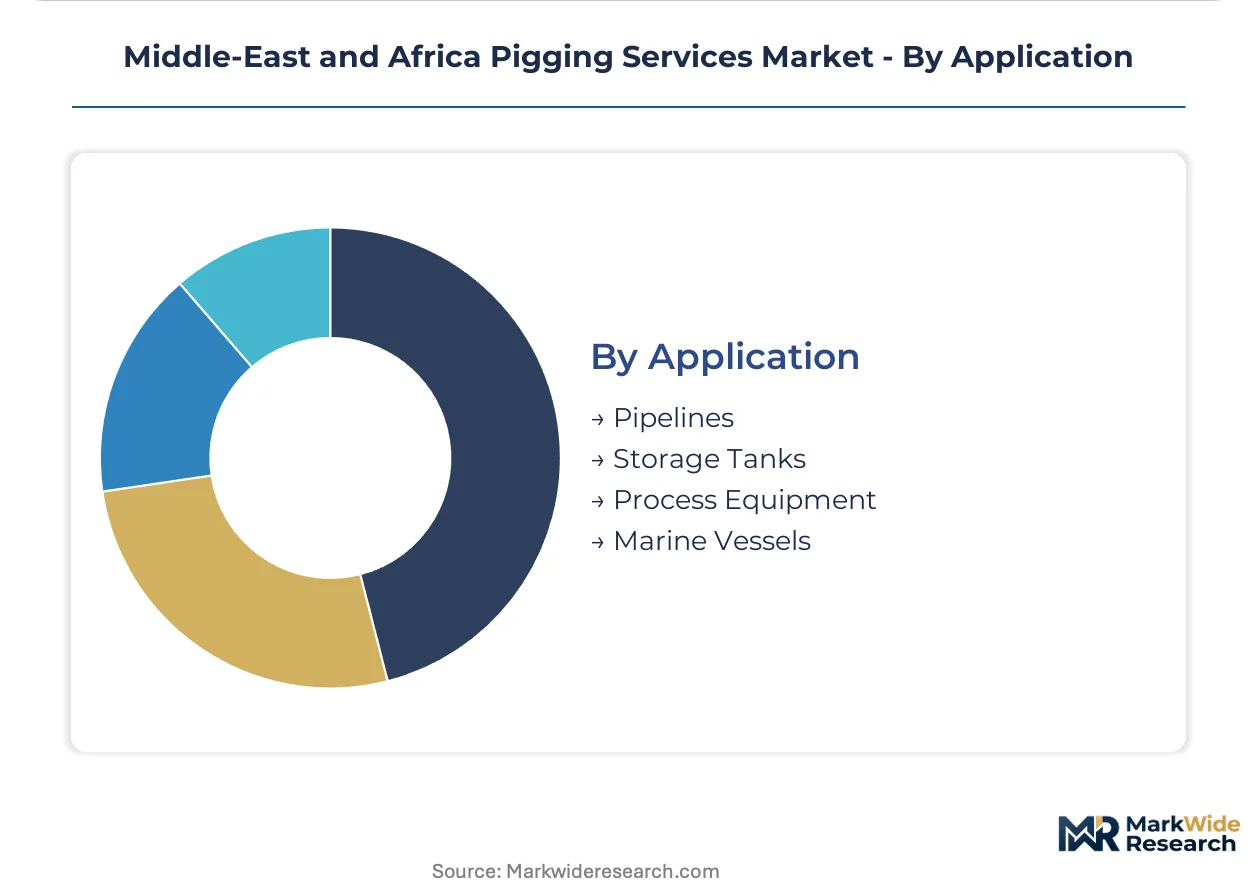
Segmentation reveals how regulatory mandates and asset lifecycle demands fragment procurement patterns across the Middle-East and Africa. Understanding these divisions exposes where technology premiums concentrate versus where commoditized volumes dominate.
Service Type:
Saudi Arabia's national standards body mandates distinct service intervals for cleaning versus inspection, creating divergent contract structures and margin profiles.
- Cleaning:Mechanical debris removal and wax scraping operations utilize foam, brush, and magnetic pigs at pressures between 30 and 150 bar. Demand concentrates in Nigeria's Niger Delta where chronic vandalism and corrosion accelerate fouling, driven by joint integrity programs from international oil companies operating aging onshore networks.
- Inspection:Inline assessment deploys magnetic flux leakage and ultrasonic sensors to detect metal loss, cracks, and geometric anomalies. Saudi Aramco's multi-year framework agreements prioritize this segment, driven by mandatory assessment intervals for cross-border hydrocarbon lines that operate independent of oil price cycles.
- Maintenance:Scheduled intervention programs combine cleaning with preliminary damage assessment for asset life extension.
- Product Separation:Batch pigging isolates distinct hydrocarbon grades or chemical products within multi-product pipelines.
Established volume favors cleaning; emerging adoption favors inspection.
End User:
Cost tier differentiation separates premium technology deployment from standardized service procurement.
- Oil & Gas:Midstream operators and national oil companies command the dominant share of contract value. Abu Dhabi National Oil Company bundles cleaning, inspection, and remediation under unified vendor accountability, displacing transactional spot contracts.
- Water Utilities:Desalination plant intake pipelines and municipal distribution networks in Saudi Arabia and UAE require periodic cleaning and leak detection services.
- Chemical Manufacturers:South Africa's occupational health and safety regulator extends coverage to industrial chemical corridors, broadening pigging applicability beyond hydrocarbons.
- Food Processing:Hygienic pipeline systems for dairy and beverage transport utilize specialized cleaning pigs with sanitary-grade materials.
Technology premiums cluster in oil and gas; regulatory expansion drives chemical processing.
Technology:
Application complexity determines sensor density and autonomous capability requirements.
- Smart Pigs:Multi-sensor platforms integrate magnetic flux leakage, ultrasonic testing, and inertial mapping for comprehensive defect characterization. UAE and Qatar sour gas fields deploy ultrasonic crack detection variants to address hydrogen-induced cracking, driven by high-sulfide production environments.
- Reactive Pigs:Simple mechanical devices respond to pipeline conditions without active control systems. Egypt's draft pipeline integrity regulations will accelerate displacement of this category as compliance standards align with Gulf precedents.
- Inline Pigs:Standard propulsion units for routine cleaning and gauging operations in predictable pipeline geometries.
- Specialty Pigs:Custom-engineered solutions for irregular diameters, tight radius bends, or extreme temperature/pressure conditions.
Smart pigs capture margin expansion; reactive pigs retain volume in deferred maintenance markets.
Application:
Geographic asset concentration shapes regional service provider clustering.
- Pipelines:Cross-border hydrocarbon transport lines dominate procurement volume. Saudi Arabia and UAE civil defense authorities synchronize mandatory inline inspection intervals, creating predictable demand cycles for certified contractors.
- Storage Tanks:Terminal cleaning and floor inspection services address sediment accumulation and corrosion in crude and product storage facilities.
- Process Equipment:Refinery and petrochemical plant internal cleaning and inspection requires specialized access pigging solutions.
- Marine Vessels:Subsea pipeline tie-ins and offshore loading systems utilize marine-grade pigs for saltwater exposure environments.
Onshore pipelines anchor contract value; subsea marine applications represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider capacity clusters in Saudi Arabia and the UAE, with secondary nodes emerging in Nigeria and Egypt as regulatory frameworks mature. Equipment fabrication remains import-dependent, extending lead times for specialized magnetic flux leakage and ultrasonic inspection toolsets.
Saudi Arabia
Saudi Aramco's multi-year framework agreements anchor regional contract value, while the national standards body enforces mandatory inline inspection intervals for cross-border hydrocarbon lines. SFDA-aligned technical specifications govern equipment certification for sour gas environments. The Eastern Province concentration around Dhahran and Jubail Industrial City hosts the densest cluster of certified inspection engineers and service depots.
United Arab Emirates
ADNOC's bundled procurement models displace spot contracts across Abu Dhabi's onshore and offshore production corridors. MOHAP and civil defense authorities synchronize inspection mandates with Saudi counterparts, creating predictable compliance cycles. Dubai and Jebel Ali serve as the primary import hub for North American and European fabricated pigging equipment, with local assembly operations expanding in Ras Al Khaimah.
Nigeria
International oil company joint integrity programs address chronic pipeline vandalism and corrosion in the Niger Delta onshore network. The Department of Petroleum Resources maintains prescriptive maintenance guidelines without Gulf-style mandatory inspection intervals. Lagos and Port Harcourt concentrate service provider technical staff, though security constraints limit interior deployment.
Egypt
Draft pipeline integrity regulations modeled on Saudi and UAE precedents signal jurisdictional expansion for established contractors. The petroleum ministry's regulatory development creates preparatory demand for compliance-capable inspection services. The Suez Canal Economic Zone and Cairo-Alexandria industrial corridor represent the primary near-term addressable infrastructure base.
South Africa
The occupational health and safety regulator extends coverage to chemical processing corridors beyond hydrocarbons, broadening pigging applicability. Sasol's Secunda synthetic fuels complex and Durban's petrochemical cluster generate specialized demand for process equipment cleaning. Gauteng and KwaZulu-Natal provinces concentrate the limited domestic technical certification capacity.
Middle-East and Africa Pigging Services Market Competitive Landscape
Concentration sits with integrated technology providers capable of bundling cleaning, inspection, and remediation under unified vendor accountability. The market structure divides between multinational oilfield service conglomerates with captive fabrication capabilities and regional specialists dependent on imported equipment. Three archetypes dominate: full-service integrated providers, technology-specific inspection contractors, and local maintenance operators. Competitive positioning hinges on multi-year framework agreements displacing transactional spot contracts, and predictive analytics service bundling capturing margin expansion beyond raw sensor outputs.
Among the integrated tier, Baker Hughes Company and T.D. Williamson Inc. exemplify full-service positioning through combined geometry and metal-loss assessment capabilities. NDT Global Services Ltd occupies a specialized niche within ultrasonic crack detection for sour gas environments. ROSEN Group and SGS SA represent European-origin diversified inspection and certification providers with regional compliance expertise. Regional specialists including Enduro Pipeline Services, A.Hak Industrial Services, and IGP Pipeline Services concentrate on execution-scale cleaning and maintenance contracts. CleanGas Solutions anchors the emerging Egyptian market preparatory to regulatory finalization.
| Leading Market Players |
|---|
| ROSEN Group |
| T.D. Williamson Inc. |
| Baker Hughes Company |
| NDT Global Services Ltd |
| SGS SA |
| Enduro Pipeline Services |
| A.Hak Industrial Services |
| IGP Pipeline Services |
| CleanGas Solutions |
| Others |
Supply & Pricing Matrix
Multi-year framework agreements with performance guarantees lock in supply access for Gulf operators while establishing predictable price visibility across inspection cycles. Saudi Aramco's bundled procurement models and ADNOC's unified vendor accountability structures concentrate volume with integrated providers, compressing spot-market pricing power and elevating long-term contract premiums.
Pricing Analysis
Saudi Arabia's national standards body dictates the pricing tier structure through mandatory inline inspection intervals that stratify contracts by technology complexity. Three-tier pricing separates smart pig diagnostics with data analytics bundling from standard cleaning services and reactive maintenance interventions. Cost compression in the reactive pig tier is intensifying because Egyptian regulatory alignment is accelerating displacement of basic mechanical devices. National oil companies exhibit the least price sensitivity due to compliance-driven procurement, while regional maintenance operators in Nigeria's Niger Delta face acute margin pressure from security-constrained deployment costs.
Supply Chain Analysis
North America and Europe anchor fabrication of magnetic flux leakage toolsets and ultrasonic sensor arrays for Middle-East and Africa deployment. The regional service ecosystem draws from imported multi-sensor platforms, specialized propulsion units, and certified diagnostic electronics. Single-source vulnerability concentrates in high-precision sensor manufacturing, with limited alternative suppliers for hydrogen-induced crack detection variants. Distribution runs through Dubai and Jebel Ali as the primary import hub, with local assembly operations expanding in Ras Al Khaimah and Saudi Arabia's Eastern Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across Gulf Cooperation Council jurisdictions creates niche specialization opportunities as national standards diverge on certification requirements and inspection intervals.
For Market Incumbents: Compound technology leadership through captive fabrication capabilities for smart pig sensor arrays, defending against emerging ultrasonic crack detection specialists from European markets. Prioritize certification investment in Egypt's preparatory regulatory environment before draft pipeline integrity regulations finalize. Vertical integration into predictive analytics software layers captures margin expansion beyond raw sensor outputs. For New Entrants and Emerging Players: Lead with compliance-capable inspection services in Egypt's Suez Canal Economic Zone, exploiting the gap between draft regulations and established provider presence. Target South Africa's chemical processing corridor diversification, where occupational health and safety regulator expansion broadens pigging applicability beyond hydrocarbons. Pursue partnership-based go-to-market models with local maintenance operators to overcome skilled technician scarcity constraints. For Investors and Strategic Acquirers: Capital is best deployed toward integrated service providers with multi-year framework agreement track records in Saudi Arabia and UAE, positioned for Egyptian jurisdictional expansion. Acquisition target archetypes include ultrasonic inspection specialists with sour gas environment expertise and regional cleaning operators with established security protocols for Niger Delta deployment. Watch for regulatory finalization in Egypt as the inflection indicator for compliance-driven contract acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Pig Technology Licensing | Enables regional specialists to deploy multi-sensor platforms without captive R&D investment. |
| Long-term Service Agreement Expansion | ADNOC's bundled procurement models concentrate volume with unified accountability providers. |
| Predictive Analytics Capability Buildout | Data-driven failure modeling commands premium pricing beyond raw inline inspection outputs. |
| Egyptian Market Pre-positioning | Draft pipeline integrity regulations signal jurisdictional expansion for compliance-ready contractors. |
| Specialized Technician Certification Programs | Addresses skilled engineer scarcity constraining service expansion into Algeria and interior Nigeria. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pipeline integrity managers at national oil companies, maintenance directors at international oil company joint ventures, procurement leads at midstream operators, and technical certification specialists at regional service depots. Secondary validation drew from SFDA technical specifications, MOHAP civil defense mandates, Department of Petroleum Resources maintenance guidelines, and SEC filings from listed oilfield service conglomerates. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume estimates.
Across the analysis window, the forecasting framework modeled service type segmentation by technology intensity, end-user differentiation between hydrocarbon and chemical processing applications, and geographic regulatory cluster alignment. CAGRs derived from pipeline kilometer expansion forecasts, mandatory inspection interval frequencies, and technology substitution curves for smart pig displacement of reactive mechanical devices. Sour gas field development trajectories in UAE and Qatar informed ultrasonic crack detection demand assumptions.
Forecasts assume regulatory continuity in Saudi Arabia's national standards body mandates, UAE civil defense inspection protocols, and Egyptian petroleum ministry draft frameworks; material policy shifts would require re-modeling of compliance-driven contract cycles. Specific risks include alternative monitoring technology substitution, currency volatility affecting imported equipment costs, and security constraints limiting Niger Delta deployment. Recalibration cycles align with material shifts in national regulatory finalization, national oil company procurement model evolution, and sensor technology capability advances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Nigeria Oil and Gas Midstream Market