
 Kazakhstan Oil and Gas Market | 2026-2036
Kazakhstan Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Kazakhstan Oil and Gas Market Outlook
Kazakhstan's subsoil use code is decoupling legacy concession terms from modern production-sharing frameworks. Tengizchevroil leverages its super-giant field infrastructure to sustain output above half a million barrels daily. Karachaganak Petroleum Operating anchors the northwestern region through integrated gas processing and liquids extraction. National Company JSC KazMunayGas dominates transport corridors and strategic pipeline stakes across the republic.
Kazakhstan oil and gas encompasses upstream extraction, midstream logistics, and downstream processing of hydrocarbons with API gravities ranging from light Tengiz crude at 46° to heavy Kumkol grades near 20°. Exploration and drilling services command premium margins as operators target deep Paleozoic carbonate reservoirs beneath salt domes. Crude oil production remains the structural backbone while enhanced recovery technology represents the fastest-growing technology segment as water-alternating-gas injection extends plateau rates at mature super-giants. Export markets absorb the dominant production volume share, with petrochemical plants emerging as a higher-margin demand sink for associated gas liquids.
The Ministry of Energy enforces local content thresholds through the Law on Subsoil and Subsoil Use, while the Committee for Industrial Development administers price stabilization mechanisms for domestic liquefied petroleum gas. Environmental regulators aligned with Kazakhstan's carbon neutrality commitment are tightening methane venting standards and flaring penalties at production sites. Stakeholders must monitor how fiscal term renegotiations and green bond eligibility criteria for decarbonization projects reshape capital allocation across the petroleum value chain.
Market Dynamics
Water-alternating-gas injection systems are extending plateau production at Kazakhstan's Paleozoic carbonate reservoirs, compressing breakeven thresholds for mature super-giant fields while the Ministry of Energy tightens methane venting standards.
Growth Catalysts
- Enhanced Recovery Mandates:The Law on Subsoil and Subsoil Use incentivizes operators to deploy tertiary recovery methods at depleted reservoirs. Operators at Tengiz and Karachaganak fields accelerate water-alternating-gas adoption to maintain output above half a million barrels daily.
- China offtake expansion:Power plants across Xinjiang and Central Asia are signing long-term purchase agreements for Kazakh natural gas. Pipeline throughput via the Caspian Pipeline Consortium route is absorbing incremental production volumes.
- Carbon neutrality alignment:Kazakhstan's 2060 net-zero commitment is unlocking green bond eligibility for methane capture and flaring reduction projects. Decarbonization investments now qualify for preferential fiscal treatment under national development frameworks.
Market Restraints
- Deep drilling cost volatility:Exploration beneath salt domes into Paleozoic carbonate formations requires specialized high-pressure equipment. Input costs for premium drilling services fluctuate with global steel and alloy pricing.
- Midstream concentration risk:National Company JSC KazMunayGas controls strategic pipeline stakes and transport corridors across the republic. Alternative export routes face capacity constraints and transit negotiations.
- API gravity mismatch:Heavy Kumkol grades near 20° API require dedicated refining configurations. Light Tengiz crude at 46° API commands premium export pricing, creating internal allocation tensions.
Strategic Opportunities
- Western Kazakhstan gas processing:Karachaganak Petroleum Operating's integrated liquids extraction infrastructure supports expansion into higher-margin petrochemical feedstocks. Associated gas liquids remain underutilized relative to regional demand.
- Domestic LPG stabilization:The Committee for Industrial Development administers price mechanisms creating captive demand for liquefied petroleum gas. Petrochemical plants offer offtake security absent in volatile export markets.
- Digital twin convergence:Integration of subsurface modeling with real-time production analytics is compressing reservoir management cycles. Operators piloting these systems report faster optimization of water-alternating-gas injection patterns.
Industry Challenges
- Paleozoic carbonate expertise scarcity:Deep reservoir characterization and salt dome drilling require specialized geoscience capabilities. Local universities struggle to graduate sufficient petroleum engineers with carbonate system experience.
- Legacy concession renegotiation complexity:The subsoil use code decoupling process creates legal uncertainty for operators holding pre-2017 contracts. Fiscal term revisions demand multi-year regulatory engagement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kazakhstan Oil and Gas Market |
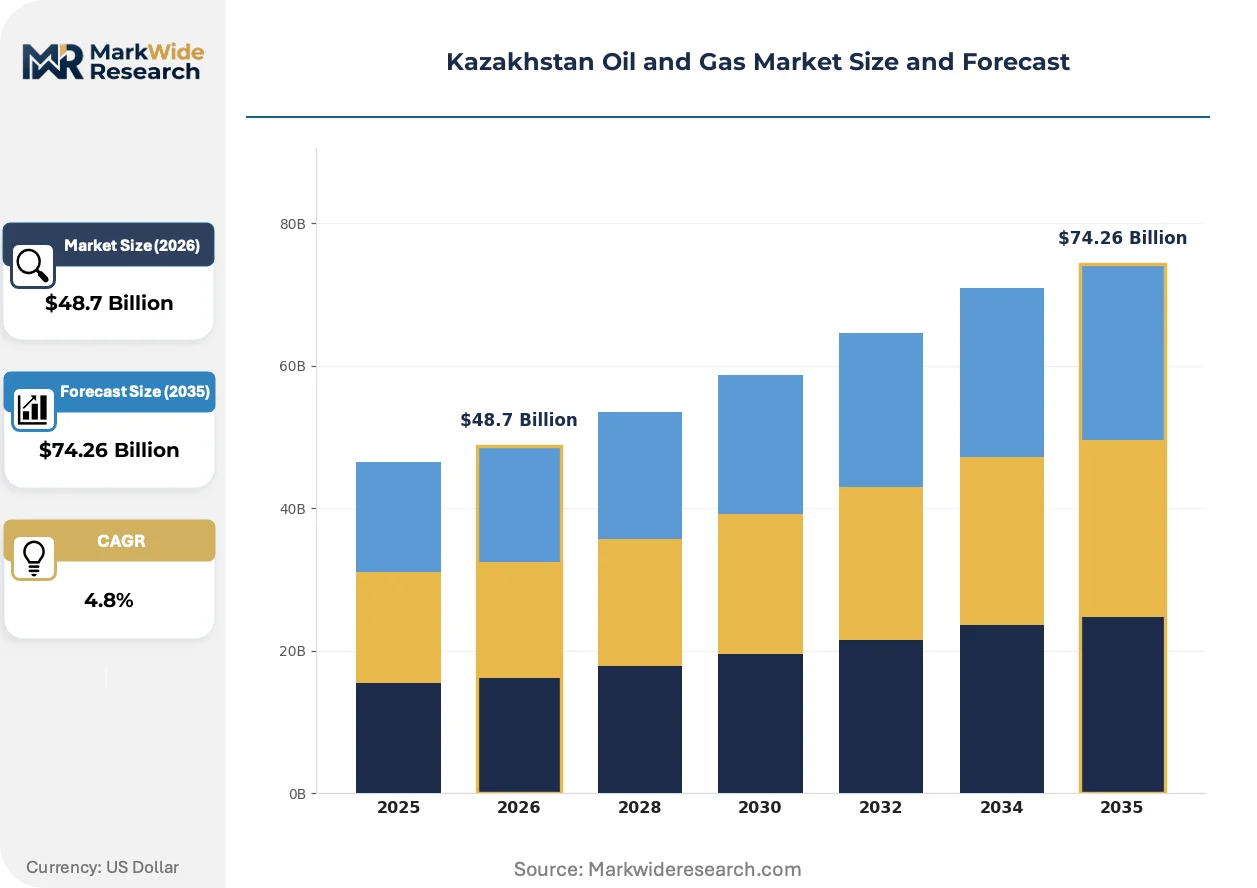
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Refining Production Type: Crude Oil, Natural Gas, Petrochemicals, LPG Technology: Surface, Subsea, Offshore, Enhanced Recovery End User: Power Plants, Petrochemical Plants, Industrial Users, Export Markets |
| Companies Covered | Karachaganak Petroleum Operating, Ozenmunaigas, National Company JSC (KazMunayGas), Embamunaigas, CNPC-Aktobemunaigas, Tengizchevroil, Mangistaumunaigas, Chevron Corporation, North Caspian Operating Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kazakhstan Oil and Gas Market Strategic Shifts
Digitalization of subsurface operations is compressing decision cycles for reservoir management. Operators now integrate real-time sensor networks with predictive analytics to optimize injection patterns and reduce unplanned downtime.
Modular gas processing units are decentralizing extraction economics at marginal fields across the Mangistau and Atyrau regions. Independent operators lacking integrated infrastructure deploy these systems to monetize stranded associated gas. The technology is decentralizing production ownership away from super-giant field consortia toward specialized mid-cap developers.
Kazakhstan's methane venting standards are tightening under environmental regulations aligned with the 2060 carbon neutrality commitment. The Ministry of Energy now imposes escalating penalties for routine flaring at production sites. Operators at Tengiz and Karachaganak are retrofitting vapor recovery systems and investing in closed-flare technologies to maintain license compliance.
Long-term offtake contracting is displacing spot market sales for natural gas exports. Chinese power utilities and Central Asian industrial consumers seek price predictability through decade-spanning purchase agreements. This pattern concentrates revenue visibility in pipeline-connected basins while marginalizing fields lacking transport infrastructure commitments.
Kazakhstan Oil and Gas Market Segmentation
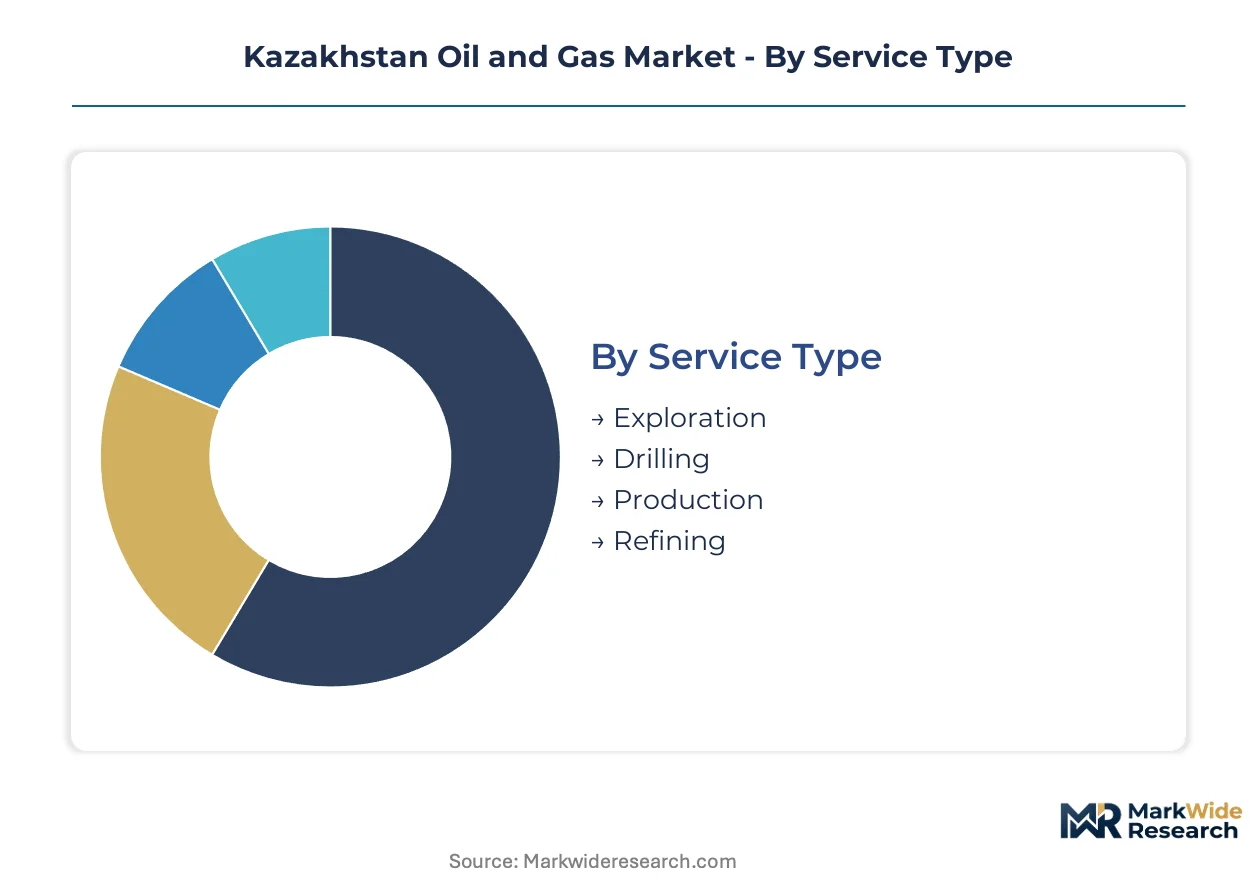
Segmentation reveals how capital deployment and regulatory exposure vary across Kazakhstan's petroleum value chain. Operators allocate resources differently depending on whether they target super-giant field infrastructure or marginal asset development.
Service Type:
Capital intensity peaks in exploration and drilling phases where specialized high-pressure equipment commands premium margins.
- Exploration:Geophysical surveys and reservoir characterization target deep Paleozoic carbonate formations beneath salt domes. Seismic acquisition concentrates around the Caspian basin where Tengizchevroil and Karachaganak Petroleum Operating hold legacy concessions. The Ministry of Energy's local content thresholds force joint ventures with domestic service providers.
- Drilling:Directional and extended-reach drilling penetrates reservoirs at depths exceeding six kilometers. Rig operators in the Atyrau and Mangistau regions face input cost volatility tied to global alloy and steel pricing. Water-alternating-gas injection well completions require corrosion-resistant metallurgy.
- Production:Surface facility operations and artificial lift systems sustain plateau rates at mature fields. Wellhead automation reduces unplanned downtime at Tengiz and Karachaganak.
- Refining:Downstream processing handles API gravity mismatches between light Tengiz crude and heavy Kumkol grades. Pavlodar and Atyrau refineries upgrade residue conversion capacity.
Drilling absorbs the bulk of installed capacity; exploration is expanding most quickly as operators target deeper horizons.
Production Type:
Volume concentration and margin profiles diverge sharply between liquid hydrocarbons and gas-based products.
- Crude Oil:Light sweet grades from Tengiz at 46° API command premium export pricing through the Caspian Pipeline Consortium route. Heavy Kumkol grades near 20° API require dedicated refining configurations and sell at discounts.
- Natural Gas:Associated gas from oil fields and dry gas from Karachaganak feed power plants across Xinjiang and Central Asia. Long-term offtake contracts with Chinese utilities displace spot market sales.
- Petrochemicals:Ethylene and polypropylene production leverages Karachaganak's integrated liquids extraction infrastructure. Domestic demand from packaging and construction sectors offers price stability.
- LPG:Liquefied petroleum gas output serves captive domestic markets under Committee for Industrial Development price stabilization mechanisms. Seasonal heating demand in rural Kazakhstan creates predictable offtake patterns.
Crude oil dominates export revenue; petrochemicals climb the fastest as operators seek higher-margin demand sinks for associated gas liquids.
Technology:
Technology selection determines breakeven thresholds and environmental compliance costs across Kazakhstan's diverse geology.
- Surface:Onshore production facilities and gathering systems handle the majority of Kazakh output. Pipeline networks from Tengiz and Karachaganak connect to Black Sea terminals.
- Subsea:Subsurface production systems and flowlines operate in shallow Caspian waters. Kashagan field development pioneered subsea architecture for harsh winter ice conditions.
- Offshore:Platform-based extraction in the Caspian requires ice-resistant structures and seasonal logistics windows. Environmental regulators impose strict methane venting standards on offshore operations.
- Enhanced Recovery:Water-alternating-gas injection and CO2 flooding extend plateau production at mature super-giants. Digital twin integration optimizes injection patterns in real time.
Surface infrastructure holds the largest installed base; enhanced recovery gains share fastest as tertiary methods penetrate depleted reservoirs.
End User:
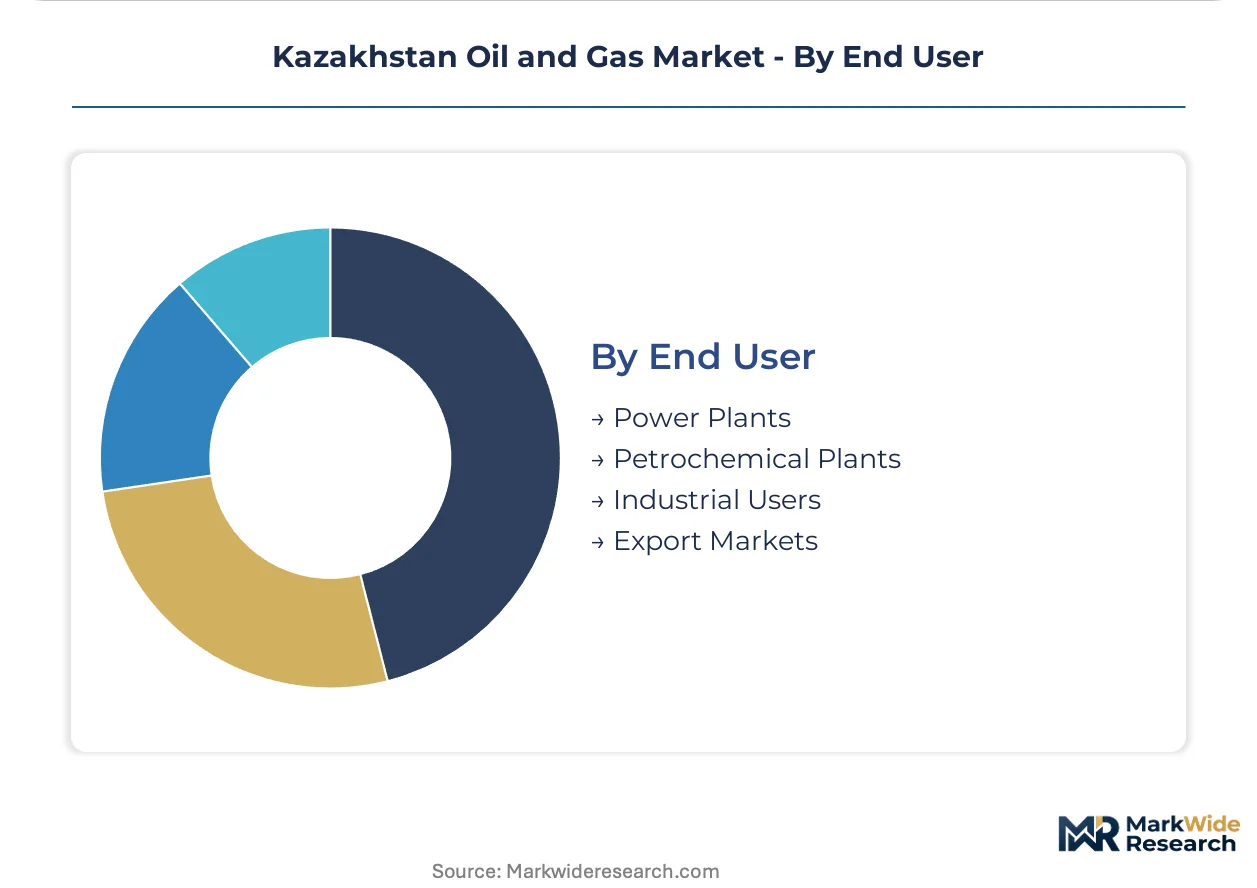
Customer type shapes contract duration, pricing mechanisms, and exposure to trade route disruptions.
- Power Plants:Combined-cycle gas turbines in Xinjiang and Central Asia burn Kazakh natural gas under decade-spanning purchase agreements. Pipeline throughput commitments provide revenue visibility absent in spot markets.
- Petrochemical Plants:Ethylene crackers and polymer units in Western Kazakhstan consume associated gas liquids. Karachaganak Petroleum Operating's integrated processing complex anchors regional feedstock supply.
- Industrial Users:Fertilizer manufacturers and steel mills in the republic purchase LPG and fuel oil under administered pricing schemes. Domestic price caps limit upside for producers.
- Export Markets:European refiners and Asian petrochemical complexes absorb the dominant production volume share. Caspian Pipeline Consortium capacity constraints create allocation tensions during maintenance periods.
Export markets command the largest volume share; petrochemical plants show the steepest expansion trajectory as domestic value-added processing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atyrau's petroleum special economic zone concentrates upstream investment through tax holidays and customs exemptions. The region anchors Kazakhstan's production base with direct pipeline access to Caspian export terminals.
Atyrau Region
Tengizchevroil's super-giant field infrastructure sustains output above half a million barrels daily. The Ministry of Energy enforces local content thresholds through the Law on Subsoil and Subsoil Use for all service contracts. Atyrau city hosts the dominant cluster of drilling contractors and equipment yards serving Paleozoic carbonate reservoirs.
Mangistau Region
Ozenmunaigas and Mangistaumunaigas operate mature fields requiring enhanced recovery investments to maintain plateau rates. The Committee for Industrial Development administers price stabilization mechanisms for domestic liquefied petroleum gas offtake. Aktau port facilities handle Caspian tanker loadings for Kashagan and Karachaganak crude exports.
West Kazakhstan Region
Karachaganak Petroleum Operating's integrated gas processing complex feeds regional petrochemical demand and power plant offtake. Environmental regulators aligned with Kazakhstan's carbon neutrality commitment impose escalating penalties for routine flaring at production sites. Oral city serves as the logistics hub for northwestern pipeline corridors connecting to Russian transit networks.
Aktobe Region
CNPC-Aktobemunaigas leverages Chinese capital for marginal field redevelopment and water-alternating-gas injection pilots. The subsoil use code decoupling process creates legal uncertainty for operators holding pre-2017 concession contracts. Aktobe city anchors the central Kazakh cluster of independent operators targeting stranded oil assets.
Pavlodar Region
Domestic refineries process heavy Kumkol grades near 20° API into fuel oil and asphalt for regional industrial users. The Law on Subsoil and Subsoil Use incentivizes tertiary recovery methods at depleted northeastern reservoirs. Pavlodar city's petrochemical complex consumes associated gas liquids under long-term supply agreements with upstream operators.
Kazakhstan Oil and Gas Market Competitive Environment
Western super-major consortia anchor one tier; national oil company subsidiaries and Chinese joint ventures hold operational positions across secondary basins. The structure concentrates around three field-development archetypes: super-giant integrated operators, state-dominated regional producers, and foreign-backed joint ventures targeting specific license blocks. Competitive positioning depends on pipeline access rights and enhanced recovery technology deployment. Operators defend margin positions through water-alternating-gas injection partnerships and modular gas processing unit installations.
Within the super-giant operator tier, Tengizchevroil and Karachaganak Petroleum Operating exemplify integrated consortium structures combining Chevron Corporation equity with national participation. National Company JSC KazMunayGas occupies a position across transport corridors and strategic pipeline stakes. These entities represent distinct archetypes: the Chevron-backed joint venture leverages deep carbonate expertise, while the national operator controls midstream infrastructure critical for export route diversification.
| Leading Market Players |
|---|
| Karachaganak Petroleum Operating |
| Ozenmunaigas |
| National Company JSC (KazMunayGas) |
| Embamunaigas |
| CNPC-Aktobemunaigas |
| Tengizchevroil |
| Mangistaumunaigas |
| Chevron Corporation |
| North Caspian Operating Company |
| Others |
Value Chain & Pricing Dynamics
Alloy and steel input costs for high-pressure drilling equipment cascade through Kazakhstan's petroleum value chain, compressing margins at directional drilling contractors before transmitting to long-term offtake premiums for pipeline-connected crude. The Ministry of Energy's local content thresholds force joint ventures with domestic service providers, embedding procurement rigidities that prop pricing tiers for exploration and drilling services.
Pricing Analysis
Short lead-time premiums dominate service contracting as operators at Tengiz and Karachaganak fields pay surcharges for expedited corrosion-resistant metallurgy in water-alternating-gas injection well completions. Contract-based long-term offtake structures govern natural gas sales to Chinese power utilities, with price differentiation hinging on pipeline throughput commitments and API gravity specifications. Cost compression in heavy Kumkol grades is intensifying because dedicated refining configurations lack export parity, while light Tengiz crude at 46° API commands the least price-sensitive buyer segment in European refinery procurement.
Supply Chain Analysis
Regional distribution centers in Atyrau and Aktau anchor hub-and-spoke patterns for drilling equipment and modular gas processing units serving the Mangistau and West Kazakhstan regions. Manufacturing concentration in China, South Korea, and Germany feeds high-pressure alloy dependencies for deep Paleozoic carbonate drilling, with logistics chokepoints at Caspian port facilities during ice season. Distribution runs through National Company JSC KazMunayGas-controlled pipeline corridors, concentrating single-source vulnerability for alternative export route development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kazakhstan's petroleum market operates as a supply-constrained system where Caspian Pipeline Consortium capacity limitations prop pricing power for pipeline-connected operators. The analysis window reveals structural bottlenecks in midstream infrastructure sustaining premium capture for integrated super-giant field consortia.
For Market Incumbents: Deploy water-alternating-gas injection partnerships to extend plateau production at mature super-giants while retrofitting vapor recovery systems to preempt methane venting penalty escalations. Deepen backward integration into modular gas processing unit manufacturing to offset alloy cost volatility threatening drilling service margins. For New Entrants and Emerging Players: Launch via modular gas processing unit deployment at stranded associated gas fields across the Mangistau region, targeting independent operators lacking integrated infrastructure. The Committee for Industrial Development's administered LPG pricing creates captive offtake security absent in volatile export markets, with petrochemical feedstock supply to Western Kazakhstan plants offering the most penetrable entry vector. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized carbonate drilling contractors in the Atyrau petroleum special economic zone as legacy concession renegotiations create legal uncertainty for pre-2017 contract holders. Watch for fiscal term clarity from subsoil use code decoupling processes as the inflection signal for capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Recovery Technology Licensing | Water-alternating-gas injection patents from Tengizchevroil transfer to Karachaganak and Kashagan field operators. |
| Backward Integration into Alloy Manufacturing | Domestic metallurgy joint ventures reduce exposure to global steel price volatility for drilling contractors. |
| Long-term Power Purchase Agreements | Chinese utilities in Xinjiang lock in decade-spanning natural gas offtake through Caspian Pipeline Consortium routes. |
| Green Bond Eligibility Structuring | Methane capture projects qualify for preferential fiscal treatment under Kazakhstan's carbon neutrality framework. |
| Digital Twin Platform Integration | Real-time subsurface modeling partnerships compress reservoir management cycles at Paleozoic carbonate fields. |
Study Parameters
Trade databases, customs records, and project development registries formed the secondary backbone, cross-referenced with primary interviews involving upstream operations managers at super-giant field consortia, procurement leads at National Company JSC KazMunayGas, drilling contractors in the Atyrau petroleum special economic zone, and environmental compliance officers aligned with Ministry of Energy methane regulations. Bottom-up field-level production data and top-down export throughput figures underwent triangulation to validate volume assumptions.
Historical trendline analysis across the analysis window incorporated capacity utilization rates at Tengiz and Karachaganak, pipeline throughput commitments via Caspian Pipeline Consortium infrastructure, and regional petrochemical demand trajectories. Segmentation modeling spanned service type, production type, technology deployment, and end-user contracting structure. CAGRs derived from production plateau sustainability curves and enhanced recovery penetration rates, with carbon neutrality policy stringency serving as a key scenario variable.
Regulatory enforcement shifts, alloy price volatility, and transit route geopolitics are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
North America Shale Market
Oil & Gas
Mud Mixers Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market