
 North America Oil and Gas Electric Submersible Pump Market | 2026-2036
North America Oil and Gas Electric Submersible Pump Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil and Gas Electric Submersible Pump Market Analytics
Aftermarket service revenue is narrowing the gap with original equipment margins across the North America oil and gas electric submersible pump landscape. Schlumberger Limited leverages its integrated artificial lift portfolio to capture recurring service contracts in the Permian and Bakken. Baker Hughes Company sustains manufacturing scale through its dedicated ESP production facilities in Oklahoma and Texas. Weatherford International plc anchors its regional position with extensive downhole diagnostics capabilities that reduce operator downtime.
An electric submersible pump for oil and gas applications is a multistage centrifugal pump assembly driven by a submersible electric motor, typically operating at depths exceeding 3,000 feet with power ratings from 100 to 1,500 horsepower, designed to lift hydrocarbons from wellbore to surface through progressive pressure staging. Multi-stage configurations dominate high-volume unconventional wells where pressure drawdown requirements exceed single-stage capacity, while permanent magnet motor variants are gaining traction for their improved electrical efficiency in extended-reach horizontal applications. Well extraction remains the primary revenue pool, though enhanced oil recovery applications are expanding fastest as mature fields in California and the Gulf of Mexico seek tertiary production methods.
The EPA enforces methane monitoring and leak detection standards that elevate demand for sealed ESP systems with reduced fugitive emissions profiles, while OSHA regulates electrical safety in hazardous classified locations where submersible motors operate. The Inflation Reduction Act's methane fee structure creates direct cost exposure for operators running legacy pump configurations, accelerating replacement cycles toward compliant equipment. Stakeholders must weigh capital allocation between new well installations and retrofit programs as regulatory thresholds tighten and field electrification expands.
Market Dynamics
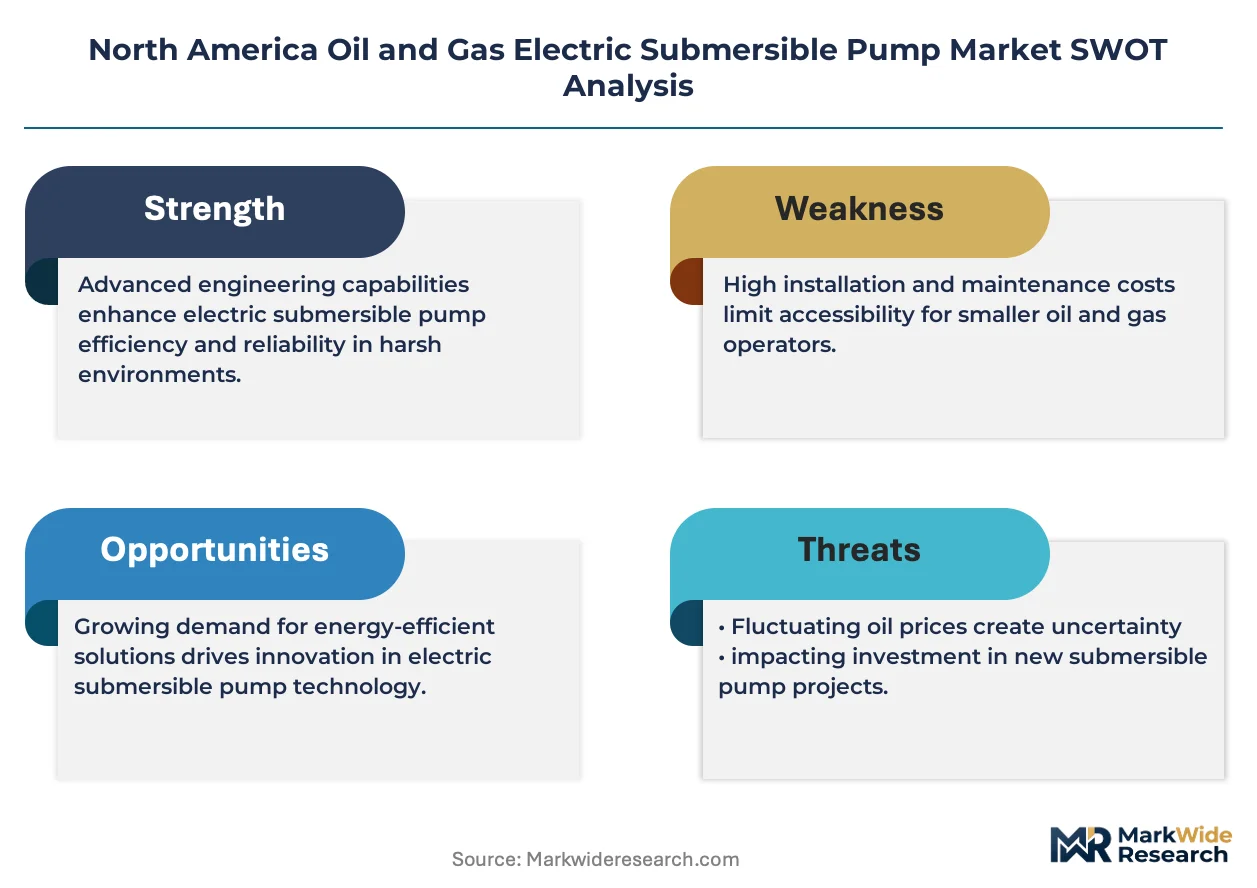
The Inflation Reduction Act's methane fee structure is compressing replacement cycles across the North America oil and gas electric submersible pump landscape, forcing operators to retire legacy configurations ahead of schedule.
Growth Catalysts
- Permian Basin drilling intensity:Horizontal well complexity in Texas and New Mexico requires multi-stage ESP systems for pressure drawdown management. Unconventional shale operators are expanding artificial lift deployment faster than conventional vertical plays.
- EPA methane monitoring standards:Sealed ESP configurations with reduced fugitive emissions profiles are becoming mandatory for regulatory compliance. The fee structure creates direct cost exposure that accelerates equipment refresh rates.
- Permanent magnet motor technology:Electrical efficiency gains in extended-reach horizontal applications are displacing induction motor variants. This technology reduces power consumption in deep wellbore environments.
Market Restraints
- Copper and rare earth input volatility:Permanent magnet motors depend on neodymium and dysprosium supply chains concentrated in China. Price swings in these materials compress manufacturing margins unpredictably.
- Specialized technician scarcity:Downhole diagnostics and ESP installation require certified artificial lift engineers. Training pipelines in Oklahoma and Texas cannot match field demand growth.
- Induction motor installed base:Decades of legacy equipment in California and Gulf of Mexico mature fields create substitution friction. Operators delay replacement despite efficiency penalties.
Strategic Opportunities
- California enhanced oil recovery:Tertiary production methods in mature fields are expanding fastest among application segments. Thermal and chemical EOR projects require specialized high-temperature ESP configurations.
- Electrification of field infrastructure:Grid-connected well pads enable variable frequency drive integration with ESP systems. This convergence reduces diesel generator dependency in Permian and Bakken operations.
- Performance-based service contracts:Operators in New Mexico are unbundling equipment procurement from maintenance obligations. This channel innovation shifts revenue toward recurring diagnostics and predictive intervention.
Industry Challenges
- Hazardous location certification timelines:OSHA electrical safety standards for Class I Division 1 environments extend product validation cycles. Manufacturers face backlog pressure at third-party testing facilities.
- Legacy SCADA integration complexity:New ESP monitoring systems must interface with decades-old wellhead automation infrastructure. Field retrofits require custom protocol bridges that inflate deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil and Gas Electric Submersible Pump Market |
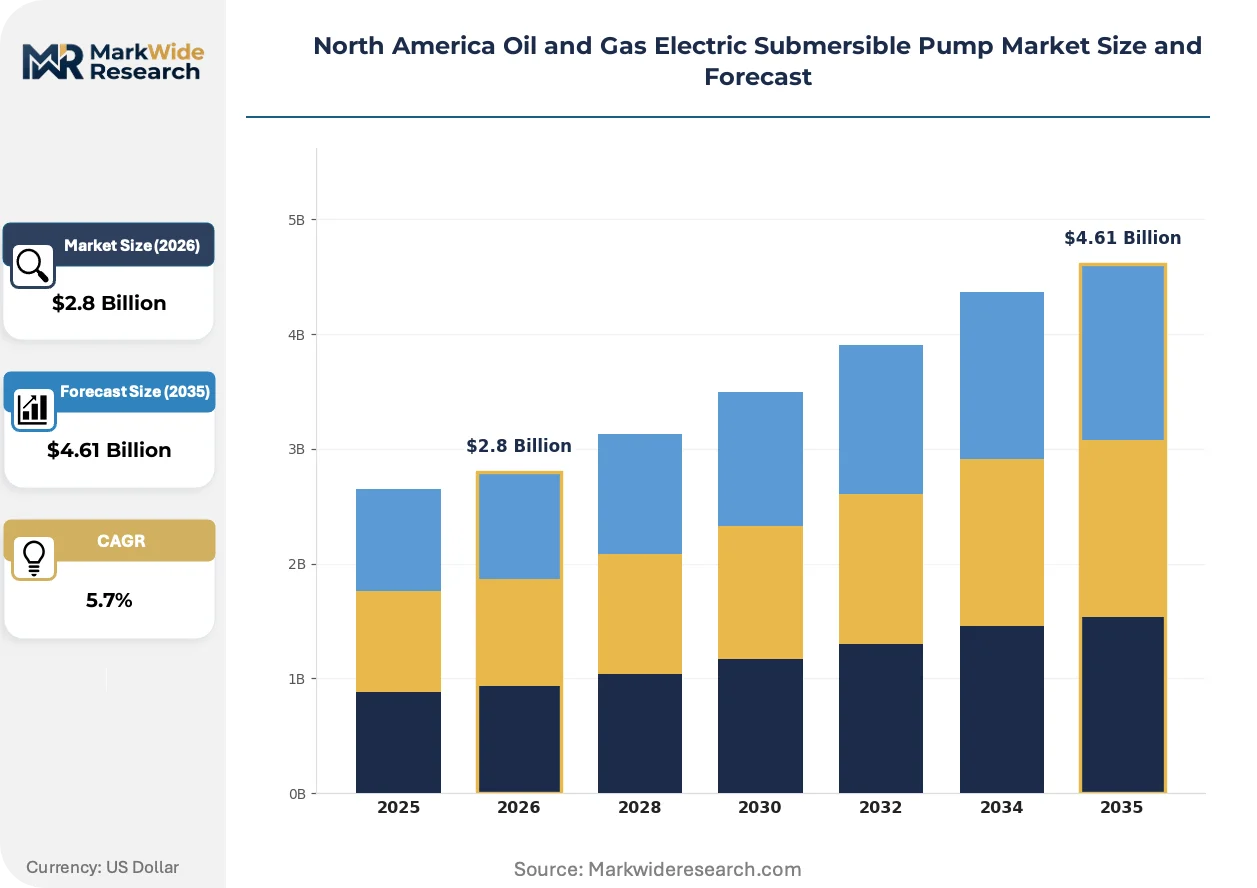
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Multi-stage, Variable Speed, Permanent Magnet Application: Well Extraction, Water Injection, Enhanced Oil Recovery, Natural Gas Production End User: Oil Producers, Gas Operators, Industrial Users, Environmental Agencies Technology: Submersible, Cable-deployed, Hydraulic, Hybrid |
| Companies Covered | Weatherford International plc, Novomet, Schlumberger Limited, Sulzer Ltd, Flowserve Corporation, Baker Hughes Company, Borets International Limited, Atlas Copco AB, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil and Gas Electric Submersible Pump Market Evolving Landscape
Permanent magnet motor technology is reshaping competitive positioning across the North America oil and gas electric submersible pump market, while regulatory pressure and procurement model evolution are compressing traditional equipment lifecycles.
Permanent magnet motor variants are migrating from niche applications to standard configurations in extended-reach horizontal wells. Operators in the Permian Basin are adopting these systems for their improved electrical efficiency at depths exceeding 3,000 feet. This migration is compressing induction motor market share and elevating power density requirements for submersible pump assemblies.
The EPA's methane emissions rules under the Inflation Reduction Act are mandating sealed system architectures with reduced fugitive emissions profiles. Equipment suppliers must redesign motor housings and cable penetrations to meet monitoring and leak detection standards. Gulf of Mexico offshore platforms and California onshore mature fields are responding fastest, accelerating replacement cycles toward compliant configurations.
Service unbundling is altering how operators acquire ESP capability across Texas and New Mexico. Equipment-only procurement is separating from installation and diagnostics contracts, with aftermarket providers capturing recurring revenue streams. This pattern is most visible among independent shale operators who lack captive artificial lift engineering teams and prefer outsourced performance guarantees.
North America Oil and Gas Electric Submersible Pump Market Segmentation
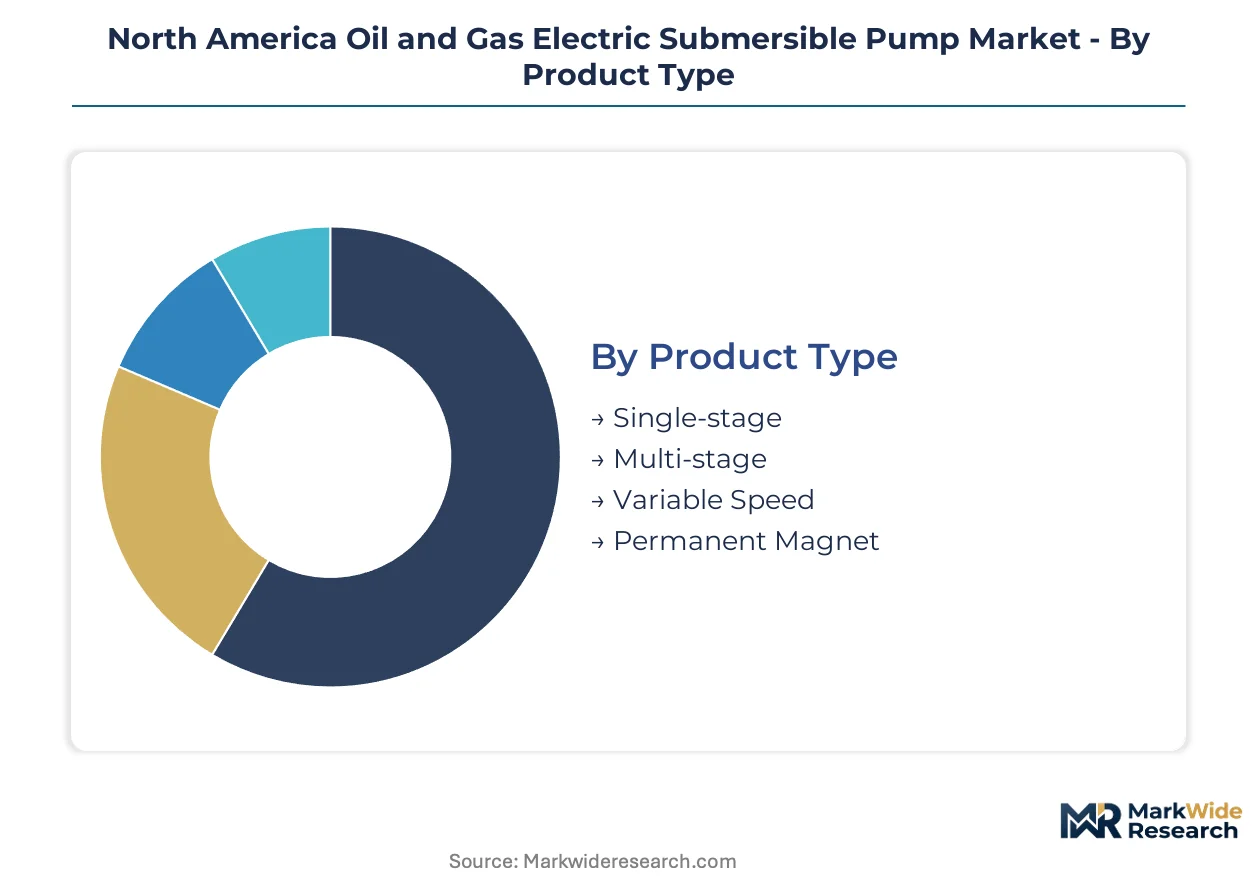
ESP procurement patterns diverge sharply across product configurations and operational contexts. Understanding segment-level replacement cycles and technology migration paths enables suppliers to calibrate inventory and service deployment.
Product Type:
Replacement cycles vary from 3-5 years for conventional induction systems to 7-10 years for sealed permanent magnet configurations, creating distinct revenue timing profiles across the installed base.
- Multi-stage:Centrifugal pump assemblies with 50-400 stages deliver pressure drawdown exceeding 3,000 psi for horizontal unconventional wells. Permian Basin operators in Texas and New Mexico deploy these systems at depths beyond 10,000 feet where single-stage capacity fails.
- Permanent Magnet:Synchronous motors with neodymium-dysprosium rotors achieve 94-96% electrical efficiency versus 85-89% for induction variants. The EPA's methane fee structure accelerates adoption in California and Gulf of Mexico fields where power costs compound regulatory exposure.
- Single-stage:Compact units suit marginal vertical wells with modest lift requirements.
- Variable Speed:Integrated variable frequency drives enable real-time flow modulation.
Multi-stage systems dominate installed base volumes. Permanent magnet configurations are where expansion concentrates fastest.
Application:
Revenue concentration tilts toward primary hydrocarbon lift, though tertiary recovery methods command premium pricing for specialized thermal and chemical-resistant configurations.
- Well Extraction:Artificial lift for oil and gas production accounts for the majority of unit deployments. Horizontal shale wells in the Permian and Bakken require continuous ESP operation with mean time between failures driving aftermarket service intensity.
- Enhanced Oil Recovery:Thermal steam flood and CO2 injection projects in California's mature fields demand high-temperature seals and corrosion-resistant metallurgy. These applications expand most quickly as tertiary recovery economics improve with oil price thresholds.
- Water Injection:Pressure maintenance in secondary recovery operations.
- Natural Gas Production:Dewatering coalbed methane and liquid-rich gas wells.
Well Extraction anchors equipment volumes. Enhanced Oil Recovery commands the steepest expansion trajectory.
End User:
Procurement authority fragments between integrated majors with captive engineering teams and independents outsourcing full artificial lift management.
- Oil Producers:Supermajors and shale independents in Texas, New Mexico, and North Dakota drive equipment demand. Integrated operators favor performance-based contracts while independents prefer bundled procurement with installation guarantees.
- Gas Operators:Appalachian and Haynesville producers deploy ESPs for liquid unloading and condensate recovery.
- Industrial Users:Refinery and petrochemical facilities utilize ESPs for process water handling.
- Environmental Agencies:Regulatory bodies in California and federal EPA programs specify equipment for groundwater remediation.
Oil Producers control the dominant share of capital allocation. Gas Operators represent the fastest-climbing customer category.
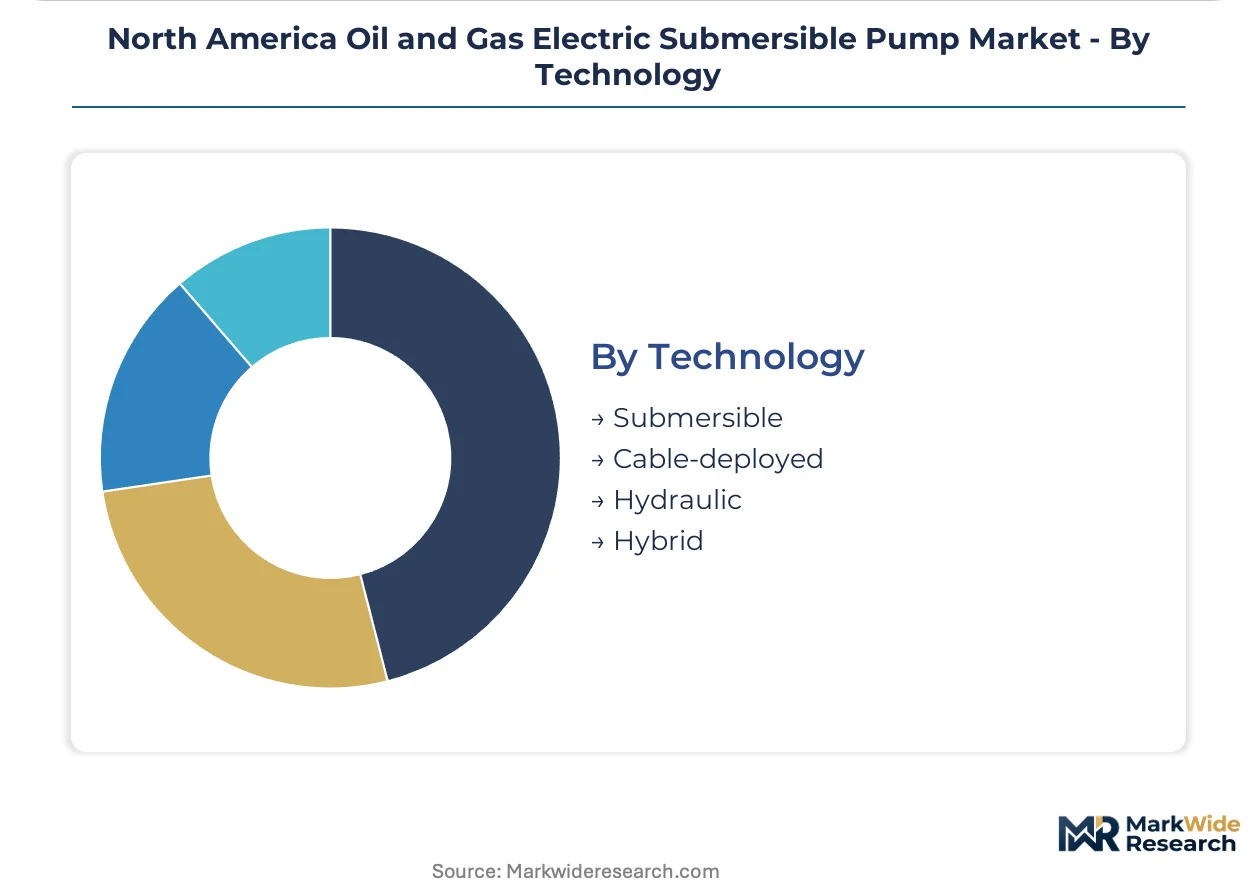
Technology:
Deployment methods reflect wellbore geometry constraints and intervention cost tradeoffs across onshore and offshore environments.
- Submersible:Standard motor-pump assemblies deployed on production tubing dominate conventional applications. Gulf of Mexico platforms and Permian land rigs both specify these systems, though offshore configurations require more rigorous OSHA hazardous location certification.
- Cable-deployed:Through-tubing retrievable systems minimize workover rig time. These technologies gain traction in mature California fields where well intervention economics favor reduced downtime over capital efficiency.
- Hydraulic:Surface-powered jet pump alternatives for high-gas-fraction wells.
- Hybrid:Combined electric-hydraulic systems for complex multiphase flow conditions.
Submersible technology holds the largest installed footprint. Cable-deployed systems are gaining share fastest in workover-intensive basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ESP manufacturing and service infrastructure clusters around Houston and Oklahoma City, with Permian Basin operators driving the dominant share of regional demand. The United States absorbs the vast majority of equipment deployments, though Canadian oil sands and Mexican offshore developments sustain secondary growth corridors.
United States
Permian Basin horizontal wells in Texas and New Mexico require multi-stage ESP systems for pressure drawdown management at depths exceeding 10,000 feet. The EPA's methane fee structure under the Inflation Reduction Act accelerates replacement cycles toward sealed permanent magnet configurations. Houston anchors the continent's largest concentration of artificial lift engineering and manufacturing facilities.
Canada
Thermal extraction projects in Alberta's oil sands deploy high-temperature ESP variants for steam-assisted gravity drainage operations. The country's national energy regulator maintains stringent electrical safety standards for hazardous classified locations that exceed baseline OSHA requirements. Calgary and Edmonton house the primary engineering centers serving Canadian unconventional and oil sands producers.
Mexico
Offshore platforms in the Gulf of Mexico and mature onshore fields in Veracruz drive demand for corrosion-resistant ESP metallurgy. The national hydrocarbons commission enforces localization requirements that favor regional service partnerships for equipment deployment. Ciudad del Carmen serves as the operational hub for offshore artificial lift services in Mexican territorial waters.
California
Thermal enhanced oil recovery projects in the San Joaquin Valley require specialized high-temperature seals and chemical-resistant pump materials. The state's air resources board imposes emissions standards that exceed federal EPA thresholds for surface equipment and power generation. Bakersfield concentrates the state's remaining active ESP service and installation capacity.
Gulf of Mexico Offshore
Deepwater platforms specify submersible systems with rigorous hazardous location certification for Class I Division 1 environments. The Bureau of Safety and Environmental Enforcement mandates redundant monitoring systems that elevate equipment specification complexity. Port Fourchon and Houma function as the primary logistics and service coordination points for offshore ESP interventions.
North America Oil and Gas Electric Submersible Pump Market Competitive Landscape
Integrated energy service conglomerates and specialized artificial lift engineering houses split the market between bundled performance contracts and equipment-centric procurement. The vendor structure tilts toward consolidation at the top tier, with mid-scale regional fabricators occupying niche service territories. Two dominant archetypes emerge: full-service providers capturing recurring diagnostics revenue and manufacturing-focused suppliers defending position through production scale. Competitive dynamics center on vertical integration into permanent magnet motor supply chains and geographic expansion through field service network density.
Among the integrated service tier, Schlumberger Limited and Baker Hughes Company exemplify the full-service archetype with extensive artificial lift portfolios. Weatherford International plc anchors the specialized engineering segment through downhole diagnostics capabilities. These three entities represent distinct strategic positions: Schlumberger's integrated energy platform, Baker Hughes's manufacturing scale, and Weatherford's service-intensive regional presence.
| Leading Market Players |
|---|
| Weatherford International plc |
| Novomet |
| Schlumberger Limited |
| Sulzer Ltd |
| Flowserve Corporation |
| Baker Hughes Company |
| Borets International Limited |
| Atlas Copco AB |
| Halliburton Company |
| Others |
Value Network & Pricing Analysis
Houston-to-Permian heavy-haul corridors carry permanent magnet motor assemblies from Oklahoma manufacturing plants to West Texas well pads, with freight costs amplifying the pricing power held by suppliers concentrated along this axis. Equipment suppliers leverage this logistics concentration to tier pricing across sealed-system premium configurations, standard induction replacements, and economy-grade single-stage units for marginal wells.
Pricing Analysis
Aftermarket service contracts now generate lifetime value exceeding original equipment sales across multi-year ESP deployments. Three-tier pricing structure across premium permanent magnet, standard induction, and economy single-stage levels reflects certification grade and power rating differentiation. Cost compression in standard induction tiers is intensifying because operators accelerate replacement cycles under EPA methane fee exposure. Independent shale operators in New Mexico exhibit highest price sensitivity, while Gulf of Mexico supermajors prioritize reliability guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for neodymium-dysprosium permanent magnet feedstock. Manufacturing concentrates in Oklahoma, Texas, and Pennsylvania, with motor assembly drawing from copper windings sourced domestically and rare earth rotors imported through limited channels. Single-source vulnerability in Chinese rare earth processing feeds into pump manufacturing margins unpredictably. Distribution runs through Houston-based service centers to Permian and Bakken field locations, with aftermarket parts flowing through Oklahoma City logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America oil and gas electric submersible pump procurement is restructuring around performance-based service contracts, where recurring diagnostics and predictive intervention revenue expands faster than hardware shipments. This service-attach dynamic elevates field engineering capabilities above manufacturing scale as the primary value capture mechanism.
For Market Incumbents: Pre-empt permanent magnet motor supply disruption by securing captive rare earth sourcing partnerships or backward integration into magnet fabrication. Lock in multi-year service contracts with Permian Basin independents before emerging ESP-as-a-Service platforms establish field presence. EPA methane enforcement timelines compress replacement windows—position sealed-system inventory ahead of regulatory deadlines. For New Entrants and Emerging Players: Cable-deployed through-tubing retrievable systems in California's thermal EOR fields represent the most penetrable entry point, where workover economics favor reduced downtime over capital efficiency. Target mid-size operators in the San Joaquin Valley lacking captive artificial lift engineering teams. Lead with remote diagnostics capabilities that incumbent field service networks have underinvested in. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oilfield service conglomerates divesting non-core artificial lift divisions to streamline capital allocation. Five-to-ten year viability hinges on permanent magnet technology migration and electrification infrastructure buildout. Monitor Permian Basin drilling permit velocity as the inflection signal—sustained horizontal completion rates drive ESP refresh demand independent of commodity price swings.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Supply Security | Captive rare earth sourcing insulates margins from China export policy shifts. |
| Performance-Based Contract Expansion | Recurring diagnostics revenue with New Mexico independents reduces equipment cyclicality. |
| Sealed System Certification Acceleration | EPA methane compliance positions inventory ahead of regulatory replacement deadlines. |
| Cable-Deployed Technology Migration | Through-tubing retrievable systems capture California EOR workover economics. |
| Field Electrification Infrastructure | Grid-connected Permian pads enable variable frequency drive integration with ESP systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA drilling productivity reports, EPA regulatory filings, FERC infrastructure data, and SEC equipment supplier disclosures. Artificial lift engineering directors, Permian Basin operations managers, Oklahoma manufacturing plant supervisors, and Houston-based aftermarket service heads provided operating data. Bottom-up well count and ESP deployment estimates triangulate against top-down supplier revenue segmentation.
Forecast inputs incorporate well completion intensity across the Permian, Bakken, and Gulf of Mexico, permanent magnet technology substitution rates, and EPA methane enforcement trajectory. Segmentation dimensions span product type, application, end user category, and deployment technology. CAGRs derive from equipment replacement cycle compression under regulatory pressure and tertiary recovery expansion in mature fields.
Practitioners should monitor rare earth export policy shifts, horizontal drilling permit volatility, and grid interconnection timelines for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Egypt Oil and Gas Midstream Market