
 Europe Drones Market | 2026-2036
Europe Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Drones Market Foresight
Direct-to-enterprise sales channels in the Europe drones sector is tilting toward integrated platform vendors. Wingcopter leverages its tilt-rotor logistics specialization to anchor pharmaceutical delivery contracts across German and Swiss air corridors. Quantum Systems sustains R&D intensity in vertical take-off fixed-wing designs, while Auterion differentiates through open-source flight-stack standardization that reduces vendor lock-in for defense and energy clients.
Europe drones encompass unmanned aerial vehicles spanning fixed-wing, multi-rotor, hybrid, and nano configurations, typically integrating lithium-polymer power systems, GNSS-RTK navigation modules, and sub-25 kg airframes designed for commercial payload delivery or sensor-based data acquisition. Fixed-wing platforms dominate long-range infrastructure inspection missions across Nordic offshore wind arrays, while multi-rotor systems capture margin pools in film production and emergency response where hover precision commands premium positioning. Hybrid architectures are gaining structural traction in agriculture monitoring, where endurance gaps between rotary agility and fixed-wing range create unmet operational requirements.
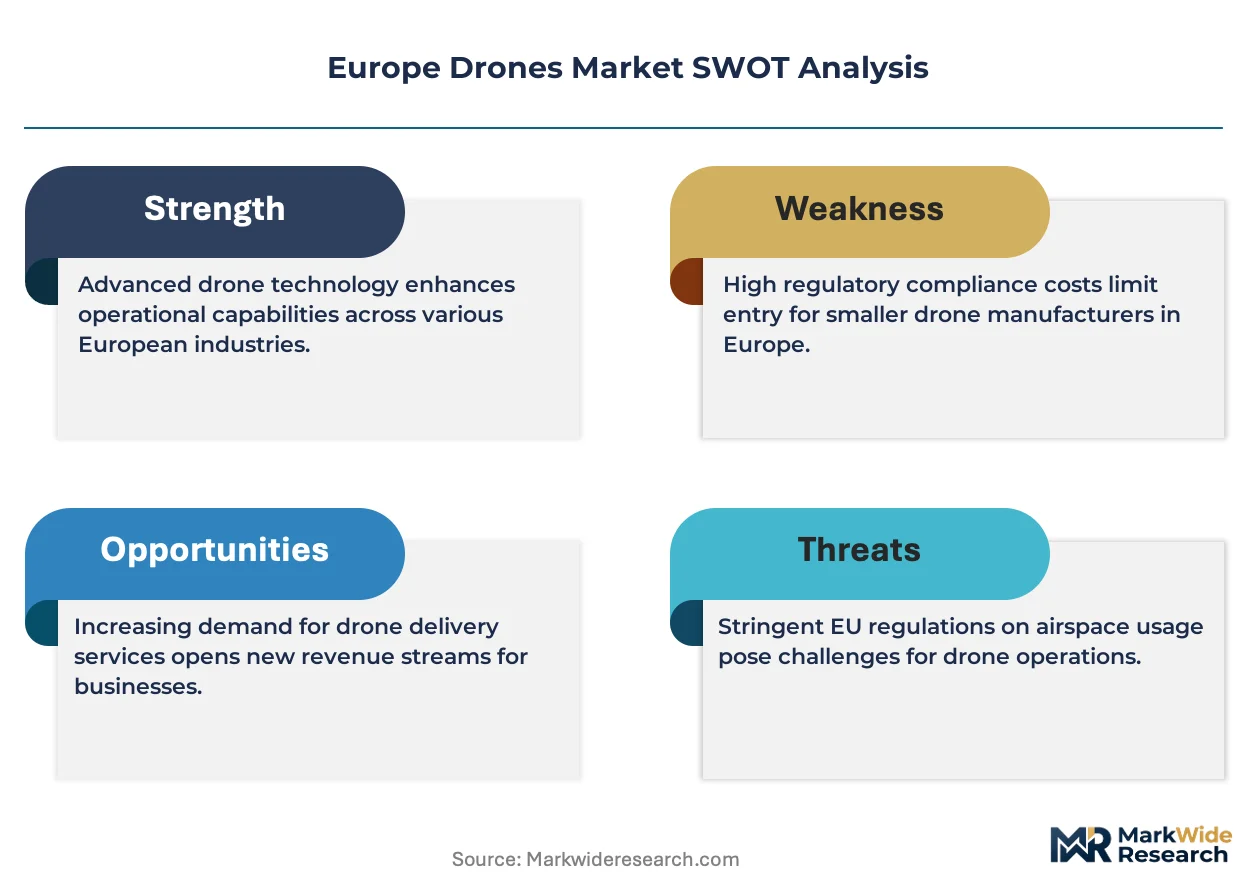
EMA and EASA frameworks govern airworthiness certification for beyond-visual-line-of-sight operations, while the EU AI Act imposes algorithmic transparency requirements on autonomous navigation systems that reshape product development roadmaps. National regulators in France and Germany enforce divergent liability standards for urban drone deployment, fragmenting compliance costs across member states. Stakeholders must monitor the interplay between EASA's forthcoming drone-as-a-service regulatory sandbox and member-state enforcement discretion to calibrate market entry sequencing.
Market Dynamics
EASA's forthcoming drone-as-a-service regulatory sandbox is compressing certification timelines while fragmenting compliance costs across member-state liability regimes. This regulatory momentum pulls capital toward integrated platform vendors capable of spanning German industrial corridors and Nordic offshore arrays.
Growth Catalysts
- EU Green Deal digital farming mandates:Precision agriculture requirements across European farmland accelerate sensor-based crop monitoring adoption. Member states allocate CAP subsidies toward variable-rate application systems.
- Beyond-visual-line-of-sight corridor proliferation:German and Swiss airspace designations enable pharmaceutical logistics networks. Industrial clusters concentrate drone operations near Frankfurt and Basel.
- Open-source flight-stack standardization:Defense and energy buyers reduce vendor lock-in through modular autonomy architectures. Platform interoperability lowers switching costs for enterprise procurement.
Market Restraints
- Lithium-polymer supply concentration:Cell production clusters in East Asia expose European assemblers to shipping volatility and raw material bottlenecks. Energy density improvements lag operational endurance requirements.
- Algorithmic transparency mandates:EU AI Act compliance adds development overhead for autonomous navigation systems. Documentation burdens extend product roadmaps.
- Multi-rotor range limitations:Rotary platforms face payload-distance tradeoffs that fixed-wing alternatives exploit in long-range infrastructure missions.
Strategic Opportunities
- Emergency response hover precision:Film production and search-and-rescue operations command premium positioning for multi-rotor agility. Municipal buyers prioritize maneuverability over endurance.
- Hybrid architecture agriculture penetration:Vertical take-off fixed-wing designs bridge rotary hover capability with fixed-wing range. French and Italian vineyard operators trial variable-geometry platforms.
- CSRD-aligned carbon accounting:Drone-based emissions monitoring services capture compliance budgets from industrial emitters. Sustainability reporting mandates expand sensor deployment scopes.
Industry Challenges
- GNSS-RTK technician scarcity:Real-time kinematic calibration requires specialized survey expertise that training pipelines have not scaled. Service providers compete for certified field engineers.
- Sub-25 kg airframe certification timelines:EASA type approval processes delay product launches by 18-24 months. Smaller manufacturers lack regulatory affairs bandwidth.
- Legacy infrastructure integration:Enterprise buyers demand API compatibility with existing SCADA and asset management systems. Custom middleware development consumes implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Drones Market |
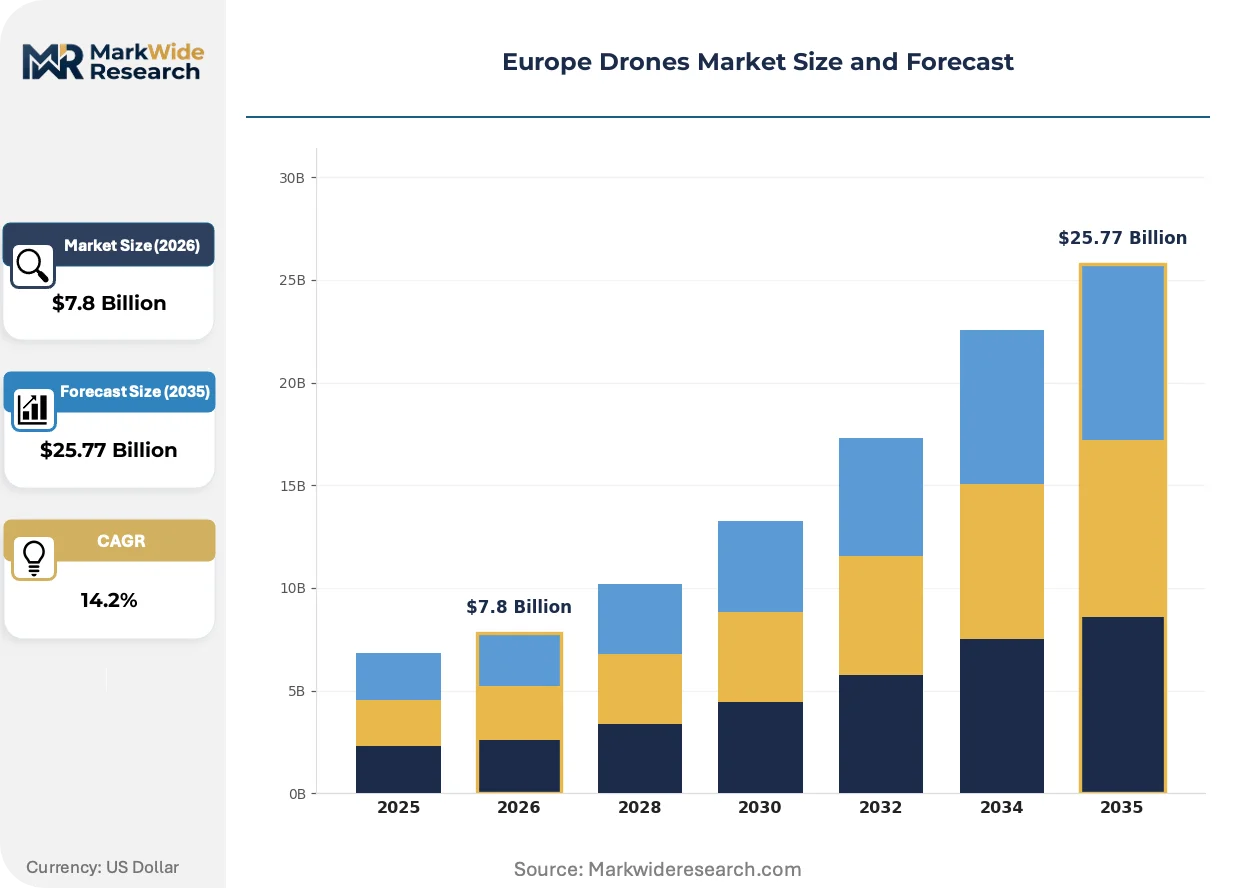
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerial Photography, Agriculture Monitoring, Search & Rescue, Infrastructure Inspection Product Type: Fixed-Wing, Multi-Rotor, Hybrid, Nano Drones End User: Military, Law Enforcement, Agriculture, Film Production Delivery Model: Software as a Service, Pre-Purchase, Subscription, Pay-Per-Use |
| Companies Covered | Wingcopter, Quantum Systems, Auterion, Atlas UAS, Threod Systems, Airlogix, Wingtra, FIXAR AERO, ABZ Innovation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Drones Market Shifts & Advancements
Autonomous navigation architectures are digitizing operational workflows across European airspace. Three developments dominate product roadmaps and capital allocation.
Edge-computing inference modules are digitizing real-time obstacle detection for low-altitude urban operations. Logistics operators in German pharmaceutical corridors deploy onboard neural processing to reduce ground-station latency. This compression of decision loops is digitizing safety-case approvals for denser flight paths.
EASA's regulatory sandbox framework is accelerating beyond-visual-line-of-sight certification pathways while preserving member-state enforcement discretion. Industrial inspection providers in Denmark and Norway leverage harmonized standards for offshore wind array surveys. The framework is forcing platform vendors to maintain dual compliance documentation for French and German liability regimes.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software-service bundles. Agricultural cooperatives in the Netherlands and Spain shift from component procurement to per-hectare data subscriptions. This concentration of purchasing authority is visible among German chemical distributors bundling drone services with crop protection products.
Europe Drones Market Segmentation
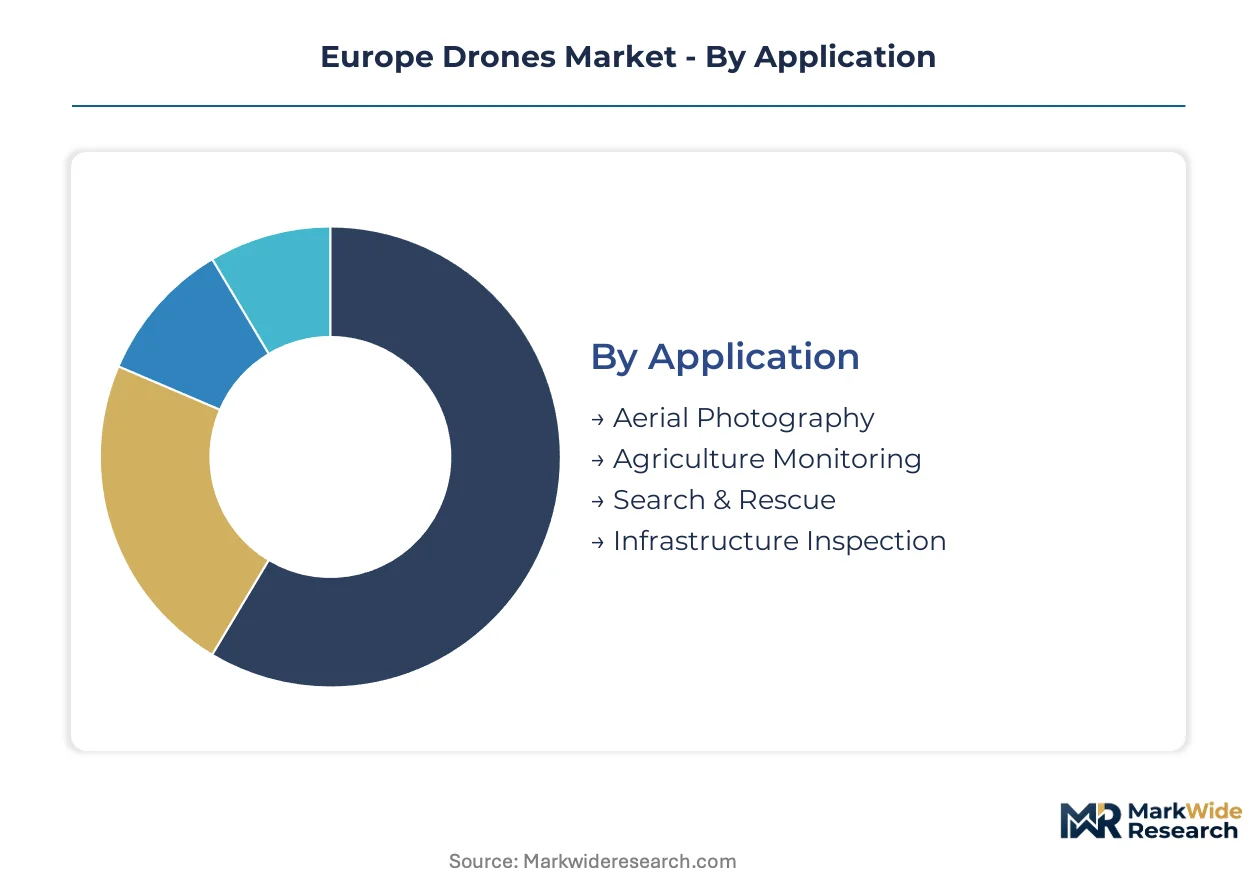
Drone deployment patterns across Europe fragment sharply by operational payload, endurance requirements, and regulatory exposure. Buyers in German industrial corridors and Nordic offshore zones prioritize fundamentally different airframe architectures and commercial terms than municipal emergency services or French vineyard operators.
Application:
Cost tiers separate recreational hobbyist deployments from enterprise-grade sensor platforms requiring EASA certification.
- Infrastructure Inspection:Long-range fixed-wing systems dominate offshore wind array surveys across Danish and Norwegian coastlines. Energy utilities in the North Sea basin commission BVLOS-certified platforms for turbine blade thermography, with EASA's regulatory sandbox compressing approval timelines for repeat corridor operators.
- Agriculture Monitoring:Variable-rate application systems integrate multispectral sensors with GNSS-RTK positioning for EU Green Deal compliance. Dutch and Spanish cooperatives shift from hardware ownership to per-hecture data subscriptions, bundling drone services with crop protection procurement.
- Search & Rescue:Thermal-equipped multi-rotor units serve alpine emergency networks in Swiss and Austrian mountain regions.
- Aerial Photography:Hover-precision platforms command premium positioning in film production clusters near Berlin and Paris.
Infrastructure inspection holds installed capacity. Agriculture monitoring is rotating up the share rankings.
Product Type:
Maturity curves diverge between established fixed-wing logistics networks and emerging hybrid architectures bridging rotary agility with endurance.
- Fixed-Wing:Long-range airframes with lithium-polymer power systems dominate pharmaceutical delivery corridors between Frankfurt and Basel. Wingcopter's tilt-rotor specialization anchors German-Swiss logistics contracts where payload-distance tradeoffs favor aerodynamic efficiency over hover capability.
- Hybrid:Vertical take-off fixed-wing designs penetrate French and Italian vineyard operations where terrain constraints prohibit runway deployment. Quantum Systems sustains R&D intensity in this segment as variable-geometry platforms bridge the endurance gap between multi-rotor precision and fixed-wing range.
- Multi-Rotor:Sub-25 kg quadcopters capture municipal emergency response budgets prioritizing maneuverability.
- Nano Drones:Palm-sized units serve confined-space industrial inspection in chemical processing facilities.
Fixed-wing platforms retain the dominant revenue share. Hybrid architectures are expanding most quickly as vineyard and corridor operators trial next-generation endurance.
End User:
Customer type determines procurement authority concentration versus fragmented purchasing across municipal and agricultural buyers.
- Military:Defense ministries in Germany and France demand open-source flight-stack standardization through Auterion's modular architectures. Vendor lock-in reduction drives procurement specifications, with interoperability requirements extending product roadmaps for autonomous navigation systems.
- Agriculture:CAP subsidy allocation across member states accelerates sensor-based crop monitoring adoption. German chemical distributors bundle drone services with agrochemical portfolios, concentrating purchasing authority among integrated platform vendors.
- Law Enforcement:Border control agencies in Mediterranean member states deploy surveillance fleets for maritime monitoring.
- Film Production:Studio complexes in London and Munich commission hover-precision platforms for aerial cinematography.
Military end users anchor platform development roadmaps. Agriculture buyers are climbing the fastest as subsidy frameworks digitize.
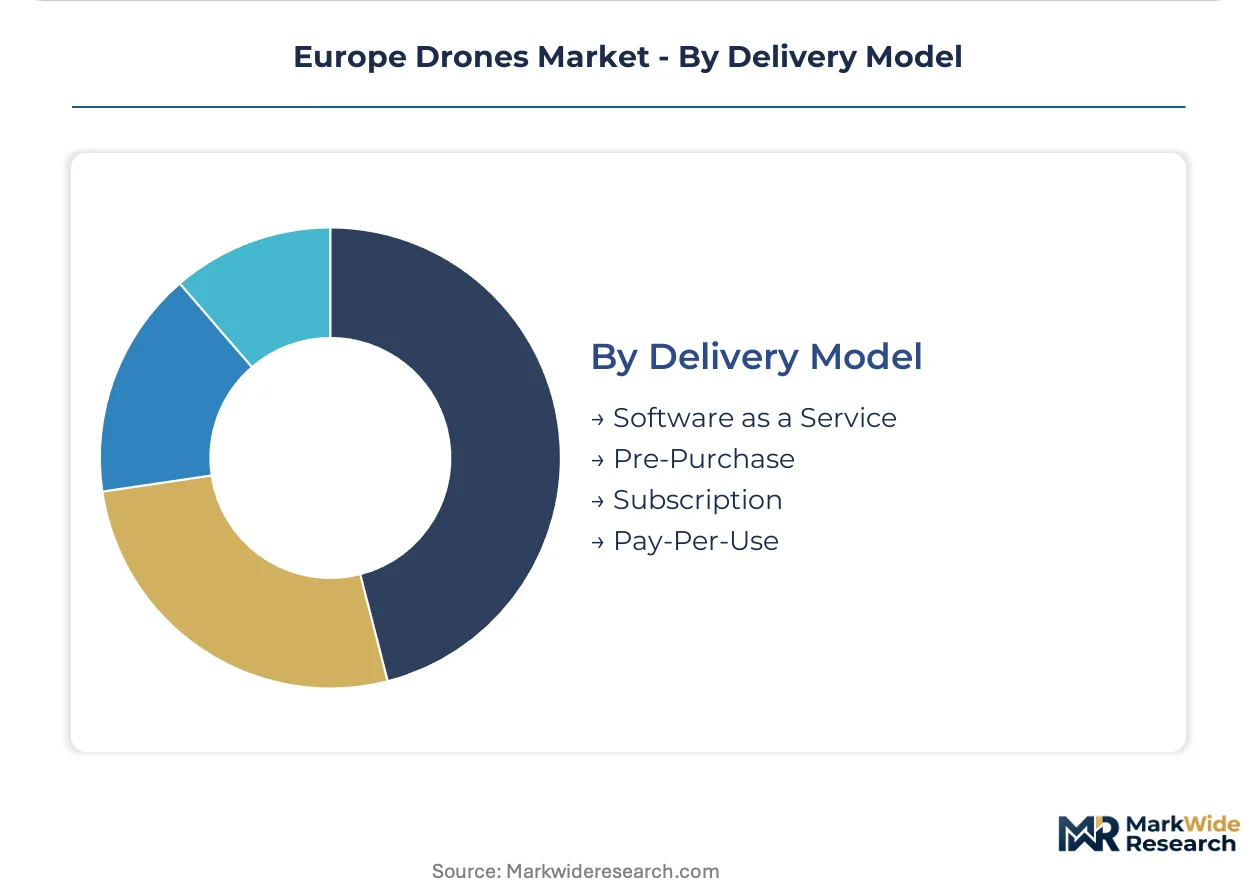
Delivery Model:
Margin structures separate capital-intensive pre-purchase deployments from recurring-revenue service arrangements.
- Software as a Service:Cloud-based mission planning and fleet management platforms capture enterprise budgets through API integration with existing SCADA systems. Legacy infrastructure compatibility demands consume implementation timelines for industrial inspection providers.
- Subscription:Per-hectare data services align agricultural cooperative spending with seasonal cash flow patterns. Dutch greenhouse operators and Spanish citrus growers prefer operational expenditure treatment over capital deployment.
- Pre-Purchase:Defense and energy buyers with dedicated flight operations teams acquire certified airframes outright.
- Pay-Per-Use:Emergency response agencies in Alpine regions access surge capacity without fleet ownership burdens.
Pre-purchase models retain the largest transaction values. Subscription and SaaS layers are gaining share fastest as procurement shifts toward integrated hardware-software-service bundles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube corridor underwrites Germany's centrality in European drone logistics, connecting Frankfurt's pharmaceutical airspace to Basel's precision manufacturing clusters.
Germany
Industrial inspection demand from offshore wind operators in the North Sea drives fixed-wing procurement. EASA's drone-as-a-service regulatory sandbox compresses certification timelines for repeat corridor operators. The Frankfurt-Rhine-Main metropolitan region concentrates tilt-rotor logistics networks serving pharmaceutical distribution.
France
Vineyard operators in Bordeaux and Champagne trial variable-geometry platforms for terrain-constrained crop monitoring. ANSM and CNIL enforce divergent liability standards for urban autonomous navigation, fragmenting compliance documentation. The Île-de-France cluster around Paris hosts film production studios commissioning hover-precision cinematography platforms.
Switzerland
Swissmedic-aligned pharmaceutical cold-chain requirements pull specialized delivery drones into the Basel-Zurich corridor. National regulators maintain permissive beyond-visual-line-of-sight designations for alpine logistics networks. The Swiss Plateau hosts precision manufacturing subcontractors supplying GNSS-RTK navigation modules.
Netherlands
Dutch greenhouse cooperatives shift procurement toward per-hectare data subscriptions aligned with seasonal cash flows. The EU Green Deal's CAP subsidy digitization accelerates sensor-based variable-rate application adoption. The Randstad conurbation concentrates cloud-based fleet management platform development for agricultural SaaS providers.
Italy
Tuscan and Piedmont vineyard operators deploy hybrid architectures where terrain prohibits fixed-wing runway deployment. National enforcement of EU AI Act algorithmic transparency mandates extends product roadmaps for autonomous navigation systems. The Emilia-Romagna industrial belt hosts subsystem suppliers for lithium-polymer power management.
Europe Drones Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors capable of spanning hardware-software-service bundles. Specialist manufacturers concentrate in German-speaking industrial corridors, while open-source flight-stack providers capture defense procurement specifications. Strategic archetypes include tilt-rotor logistics specialists, vertical take-off fixed-wing designers, and modular autonomy standardizers. Competitive moves center on EASA certification pre-positioning and API integration with legacy enterprise SCADA systems.
Within the German-specialist tier, Wingcopter GmbH and Quantum Systems GmbH exemplify contrasting endurance architectures, while Auterion AG anchors the open-source standardization vector for defense and energy buyers seeking vendor lock-in reduction.
| Leading Market Players |
|---|
| Wingcopter |
| Quantum Systems |
| Auterion |
| Atlas UAS |
| Threod Systems |
| Airlogix |
| Wingtra |
| FIXAR AERO |
| ABZ Innovation |
| Others |
Supply & Pricing Matrix
The Rhine-Main-Danube corridor's freight cost dynamics feed directly into supply concentration around German industrial clusters and downstream price differentiation between BVLOS-certified platforms and recreational-tier hardware. Lithium-polymer cell sourcing from East Asian production hubs amplifies shipping volatility into margin pressure for European assemblers, while EASA certification tiers separate enterprise procurement budgets from municipal buyer constraints.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet acquisitions from per-unit municipal transactions. Three-tier pricing stratifies across EASA-certified premium platforms, standard commercial-grade systems, and economy-tier recreational units. Certification level and after-sales service bundling drive price differentiation between German pharmaceutical logistics operators and French vineyard cooperatives. Pricing pressure stems from lithium-polymer supply bottlenecks compressing assembler margins. Municipal emergency response agencies exhibit highest price sensitivity; defense ministries demonstrate lowest sensitivity due to interoperability mandates.
Supply Chain Analysis
Contract-manufacturing concentration for GNSS-RTK modules centers on Swiss precision subcontractors and German sensor integrators. Cell production draws from China, South Korea, and Japan; carbon-fiber airframe fabrication rests on Italian and German composites specialists; semiconductor sourcing feeds from Taiwan and Netherlands distributors. Single-source vulnerability in lithium-polymer supply exposes European assemblers to raw material bottlenecks. Distribution runs through direct-to-enterprise channels for defense and energy buyers, with agricultural cooperatives accessing bundled hardware-software-service subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German chemical distributors and Dutch greenhouse cooperatives bundling drone services with crop protection procurement, fragmenting pricing authority for standalone hardware vendors.
For Market Incumbents: Entrench certification pre-positioning within EASA's regulatory sandbox to delay challenger entry timelines. Deepen backward integration into lithium-polymer power management subsystems to offset East Asian supply volatility. Anchor defense procurement specifications through open-source flight-stack standardization that raises switching costs for Auterion-aligned buyers. For New Entrants and Emerging Players: Establish a beachhead in French and Italian vineyard operations where terrain constraints favor hybrid architectures over fixed-wing incumbents. Target per-hectare data subscription models for Spanish citrus growers seeking operational expenditure treatment. Leverage API-first fleet management platforms to bypass legacy SCADA integration barriers that consume incumbent implementation budgets. For Investors and Strategic Acquirers: EASA's forthcoming drone-as-a-service regulatory sandbox reshapes the acquisition landscape toward integrated platform vendors capable of spanning hardware-software-service bundles. Long-term viability favors specialists with dual compliance documentation for French and German liability regimes. Signal to monitor: member-state enforcement discretion harmonization as indicator of regulatory consolidation timeline.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Certification Pre-Positioning | Compresses approval timelines for repeat BVLOS corridor operators in German pharmaceutical networks. |
| Open-Source Flight-Stack Standardization | Reduces vendor lock-in for defense ministries specifying modular autonomy architectures. |
| Hybrid Architecture R&D Intensification | Bridges rotary hover capability with fixed-wing range for terrain-constrained vineyard operators. |
| Per-Hectare Subscription Pivot | Aligns agricultural cooperative spending with seasonal cash flow patterns in Dutch greenhouse sectors. |
| API Integration with Legacy SCADA | Captures industrial inspection budgets from energy utilities demanding compatibility with existing asset management systems. |
Research Methodology
A spread of perspectives from EASA regulatory affairs officers, German pharmaceutical logistics operators, French vineyard cooperative managers, and Dutch greenhouse technology procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with platform engineering directors and fleet operations managers. Secondary validation drew from EASA regulatory filings, EU Green Deal CAP subsidy disbursement records, EU AI Act implementation guidance, and member-state liability regime documentation. Bottom-up segment sizing and top-down macro anchoring were triangulated for coherence.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include application type, product architecture, end-user category, and delivery model, with regulatory exposure tier as an additional industry-specific dimension. CAGRs were derived from segment-level growth trajectory synthesis. Forecast inputs incorporated BVLOS corridor proliferation timelines and CAP subsidy digitization schedules.
Macroeconomic conditions sit as an overlay; deviation in energy costs, lithium raw material availability, or trans-Eurasian shipping rates would shift the trajectory. Forecasts reflect documented assumptions around EASA sandbox implementation pace and member-state enforcement harmonization. Quarterly review of certification timeline compression indicators and supply chain bottleneck severity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone-In-A-Box Market
UAV
Fuel Cell UAV Market
UAV
Global Renewable Drones Market
UAV
Drone Leasing Market
UAV
Passenger Drones Market
UAV
Consumer Drone Market
UAV
Drone-As-A-Service Market
UAV
Aerial Smart Weapons Market
UAV
Solar Powered Drones Market
UAV
Global Drone Autopilots Market
UAV
Delivery Drones Market
UAV
Europe Drone Light Shows Market
UAV
FPV Drone Goggles Market
UAV
Bubble Drone Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Drone Roof Inspection Market