
 Europe Oral Anti-Diabetic Drug Market | 2026-2036
Europe Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oral Anti-Diabetic Drug Market Analysis
Multi-source API procurement is rebalancing toward qualified European suppliers as manufacturers reduce dependency on distant supply chains. Sanofi leverages its integrated manufacturing footprint across France and Germany to secure active pharmaceutical ingredient continuity. Novo Nordisk anchors its oral portfolio strategy through deep R&D investment in GLP-1 receptor agonist tablets. AstraZeneca competes on cardiovascular outcome differentiation, a positioning that sustains premium formulary placement in EU markets.
Oral anti-diabetic drugs comprise small-molecule pharmaceutical formulations administered perorally to lower blood glucose through mechanisms including hepatic glucose suppression, insulin secretion enhancement, or renal glucose excretion inhibition; these agents typically achieve therapeutic plasma concentrations within one to three hours post-ingestion and require bioequivalence demonstration under EMA guidelines for generic substitution. SGLT2 inhibitors now lead volume growth as cardiorenal outcome data expands reimbursable indications beyond glycemic control alone. DPP-4 inhibitors occupy a mature margin pool where patent expirations have intensified generic competition, particularly in Mediterranean markets. Homecare settings represent the fastest-growing delivery channel as self-administration protocols reduce hospital burden and align with EU digital health integration targets.
EMA's centralized marketing authorization procedure governs pan-European access, while national health technology assessment bodies in Germany, France, and England determine reimbursable price thresholds that directly shape commercial strategy. The EU Medical Device Regulation's convergence with drug-device combination products, including connected inhalers and smart pill dispensers, adds compliance layers for oral therapy packaging. REACH chemical safety obligations affect excipient sourcing and manufacturing site qualification across member states. Stakeholders must monitor how the EU Pharmaceutical Strategy's revision of exclusivity incentives interacts with biosimilar and generic entry timelines for legacy oral agents.
Market Dynamics
Cardiorenal outcome data requirements from EMA are forcing reformulation priorities across oral anti-diabetic portfolios, as glycemic efficacy alone no longer secures premium reimbursement in German, French, or English formularies.
Growth Catalysts
- SGLT2 inhibitor cardiovascular indications:Expanded reimbursable labels beyond glucose control pull hospital prescribing toward renal and heart failure protocols. EMA's evolving guidance on outcomes data accelerates this shift.
- EU Medical Device Regulation convergence:Drug-device combination approvals for connected dispensers create new product categories. Smart packaging integration aligns with digital health targets in France and Germany.
- Homecare self-administration protocols:Reduced hospital burden drives demand for patient-managed oral regimens. National health systems in the United Kingdom prioritize ambulatory diabetes management.
Market Restraints
- API supply concentration:Dependency on distant active pharmaceutical ingredient sources creates continuity risk. Multi-source procurement rebalancing toward qualified European suppliers remains incomplete.
- DPP-4 patent cliff compression:Generic entry across Mediterranean markets collapses margin pools for mature oral agents. Price erosion intensifies as substitution protocols activate.
- REACH excipient compliance burden:Chemical safety obligations for manufacturing site qualification add cost layers. Smaller formulation houses struggle with documentation requirements.
Strategic Opportunities
- Eastern European formulary expansion:Underpenetrated markets in Poland and Romania present volume growth potential. National reimbursement frameworks are modernizing toward EU-aligned assessment criteria.
- GLP-1 oral tablet development:Non-injectable peptide delivery technology converges with patient preference for peroral administration. R&D investment concentrates on bioavailability enhancement.
- EU Pharmaceutical Strategy exclusivity revisions:Incentive recalibration for legacy agents may reshape generic entry timelines. Stakeholders can position around revised data protection periods.
Industry Challenges
- Cardiovascular outcomes trial recruitment:Patient accrual for long-term safety studies delays submission timelines. EMA's pharmacovigilance requirements demand extended follow-up protocols.
- Cross-border HTA divergence:Germany's IQWiG, France's HAS, and England's NICE apply inconsistent evidence thresholds. Manufacturers face fragmented pricing negotiations across member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oral Anti-Diabetic Drug Market |
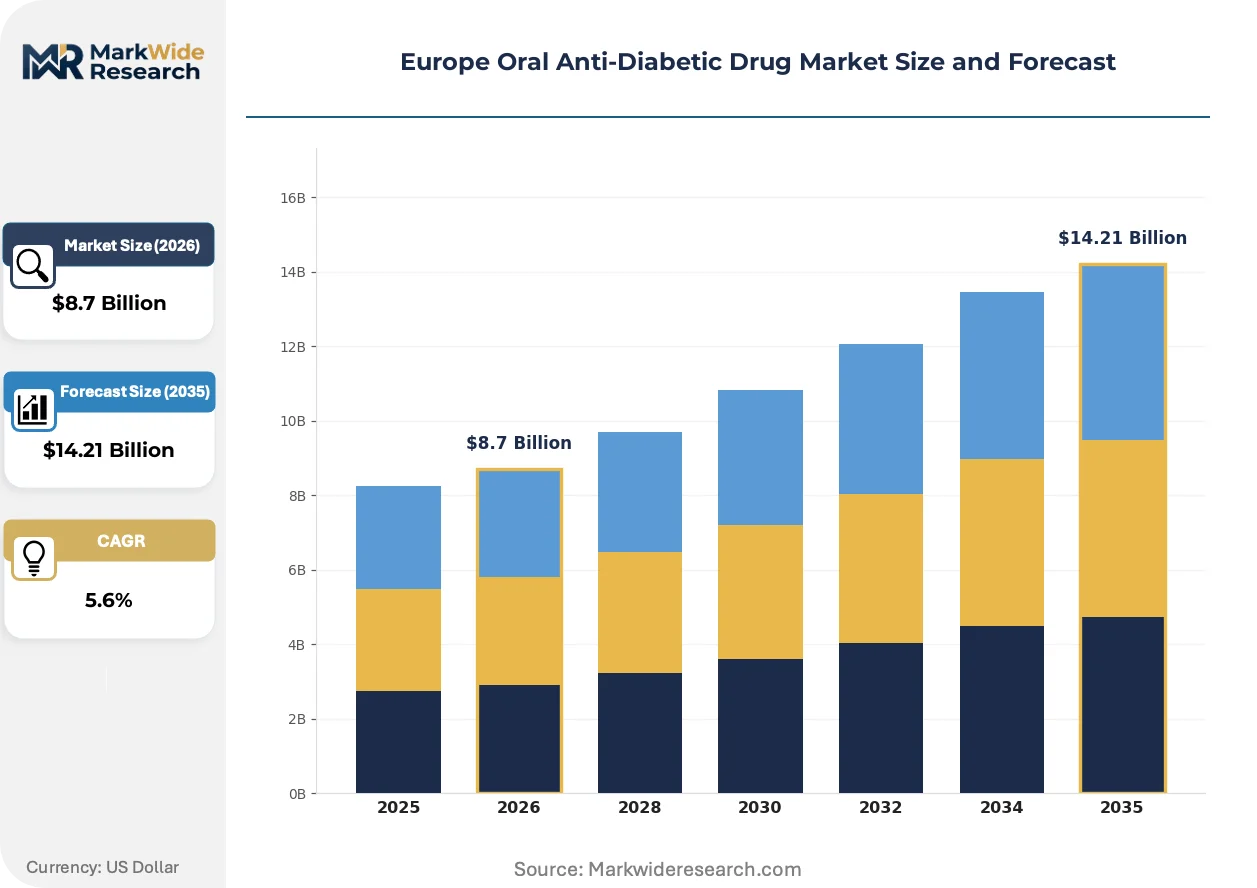
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Pharmacies, Homecare Settings Delivery Mode: Tablets, Liquids, Extended-Release, Orally Disintegrating Therapy Area: Type 2 Diabetes, Pre-diabetes, Obesity Management, Glycemic Control |
| Companies Covered | Sanofi, Eli Lilly and Company, AstraZeneca, Novo Nordisk, Boehringer Ingelheim, Merck, Johnson & Johnson, Astellas Pharma, Takeda Pharmaceuticals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oral Anti-Diabetic Drug Market Emerging Trajectories
Digital therapeutics and connected drug delivery systems are embedding into oral diabetes management, creating new value pools beyond the molecule itself. Three developments dominate strategic planning.
Smart pill dispensers with adherence monitoring are integrating into reimbursement frameworks across Northern Europe. Hospital systems in Denmark and the Netherlands pilot connected packaging for high-risk patient cohorts. This technology is integrating pharmacy benefit management with real-world outcome tracking, compressing traditional adherence program margins.
EMA's centralized marketing authorization procedure now explicitly weighs environmental risk assessments for pharmaceutical manufacturing. REACH obligations extend to supply chain due diligence for excipient sourcing. Formulators targeting German and French markets must demonstrate sustainable chemistry credentials alongside clinical efficacy.
Self-administration training programs are displacing traditional pharmacy counseling for oral anti-diabetic initiation. Retail pharmacy chains in the United Kingdom unbundle education services from product dispensing. This shift concentrates patient support investment into digital platforms rather than physical channel infrastructure.
Europe Oral Anti-Diabetic Drug Market Segmentation
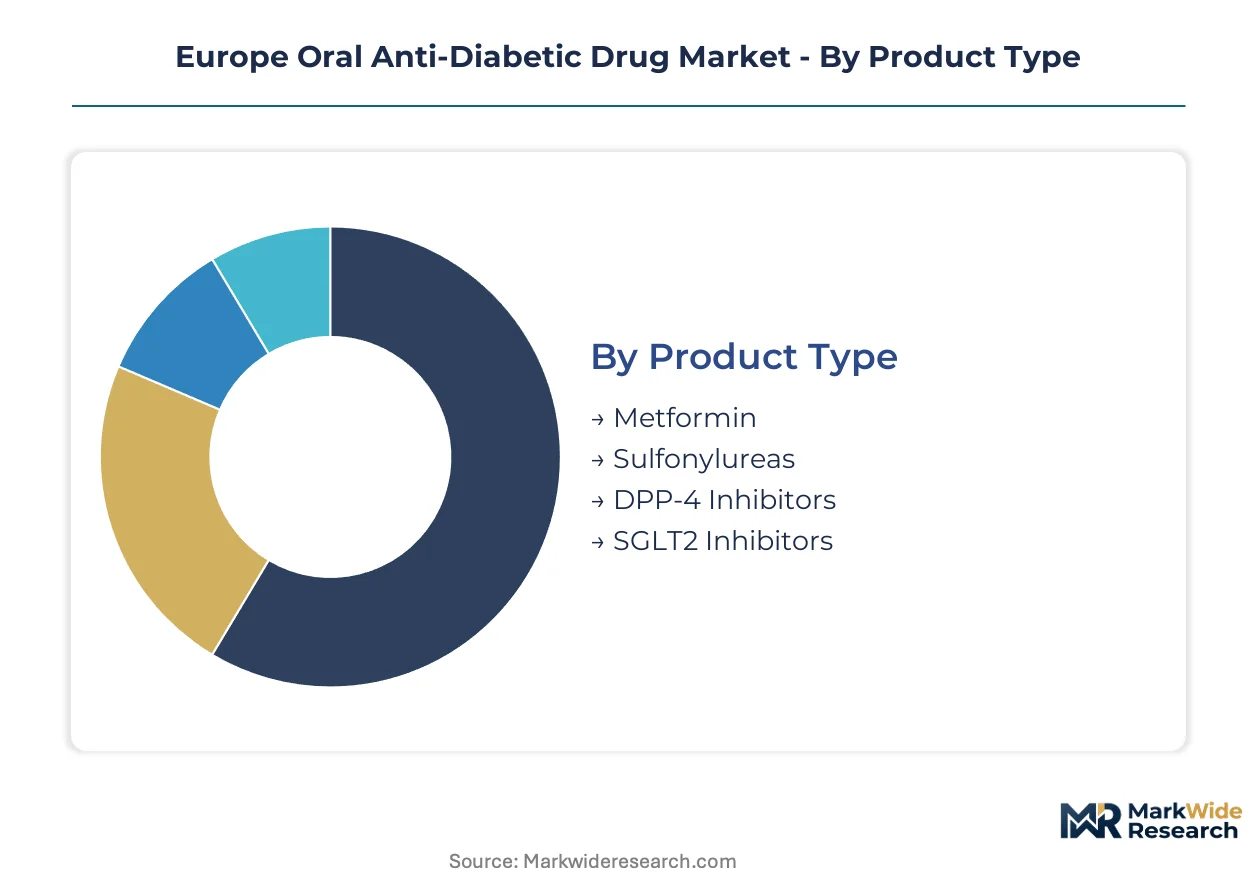
Oral anti-diabetic drug segmentation reveals distinct procurement and reimbursement patterns across European markets. Supply concentration and formulation complexity create divergent margin structures within each category.
Product Type:
Active pharmaceutical ingredient sourcing patterns concentrate manufacturing investment toward specific molecular classes with established cardiorenal outcome data.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers achieve therapeutic effect through renal glucose excretion. German and French hospital formularies prioritize these agents for heart failure protocols alongside diabetes management. EMA's evolving cardiovascular outcomes requirements favor continued R&D investment in this class.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors extend endogenous incretin activity through enzymatic blockade. Patent expirations across Mediterranean markets intensify generic substitution, compressing originator margins in Spain and Italy.
- Metformin:Biguanide compounds suppress hepatic gluconeogenesis and remain first-line therapy in United Kingdom NICE guidelines.
- Sulfonylureas:Pancreatic beta-cell insulin secretagogues occupy economy-tier positioning in Eastern European reimbursement frameworks.
SGLT2 inhibitors absorb the bulk of installed capacity; SGLT2 inhibitors are expanding most quickly.
End User:
Channel economics shift as national health systems reallocate diabetes care from institutional settings toward patient-managed environments.
- Homecare Settings:Self-administration protocols reduce hospital burden and align with United Kingdom digital health integration targets. Retail pharmacy chains unbundle education from dispensing, concentrating patient support into digital platforms.
- Hospitals:Acute care institutions integrate SGLT2 inhibitors into standard Type 2 diabetes protocols based on cardiorenal outcome data. German hospital formularies increasingly mandate dual-therapy oral regimens for high-risk cohorts.
- Clinics:Outpatient diabetes centers in France and the Netherlands pilot connected packaging for adherence monitoring.
- Pharmacies:Community dispensers face margin pressure from generic substitution protocols and unbundled counseling services.
Hospitals absorb the bulk of installed capacity; homecare settings are climbing the fastest.
Delivery Mode:
Formulation technology investments concentrate where bioequivalence demonstration under EMA guidelines creates sustainable competitive differentiation.
- Extended-Release:Modified-release matrix systems improve patient compliance through reduced dosing frequency. German and French markets favor these formulations for maintenance therapy in stable Type 2 diabetes patients.
- Tablets:Immediate-release compressed dosage forms dominate volume production. Standard tablets face commodity pricing pressure as generic entry intensifies across European markets.
- Liquids:Oral solutions serve pediatric and geriatric populations with swallowing difficulties in United Kingdom homecare protocols.
- Orally Disintegrating:Rapid-dissolve formulations address adherence challenges in elderly patient cohorts with polypharmacy regimens.
Tablets absorb the bulk of installed capacity; extended-release formulations are gaining share fastest.
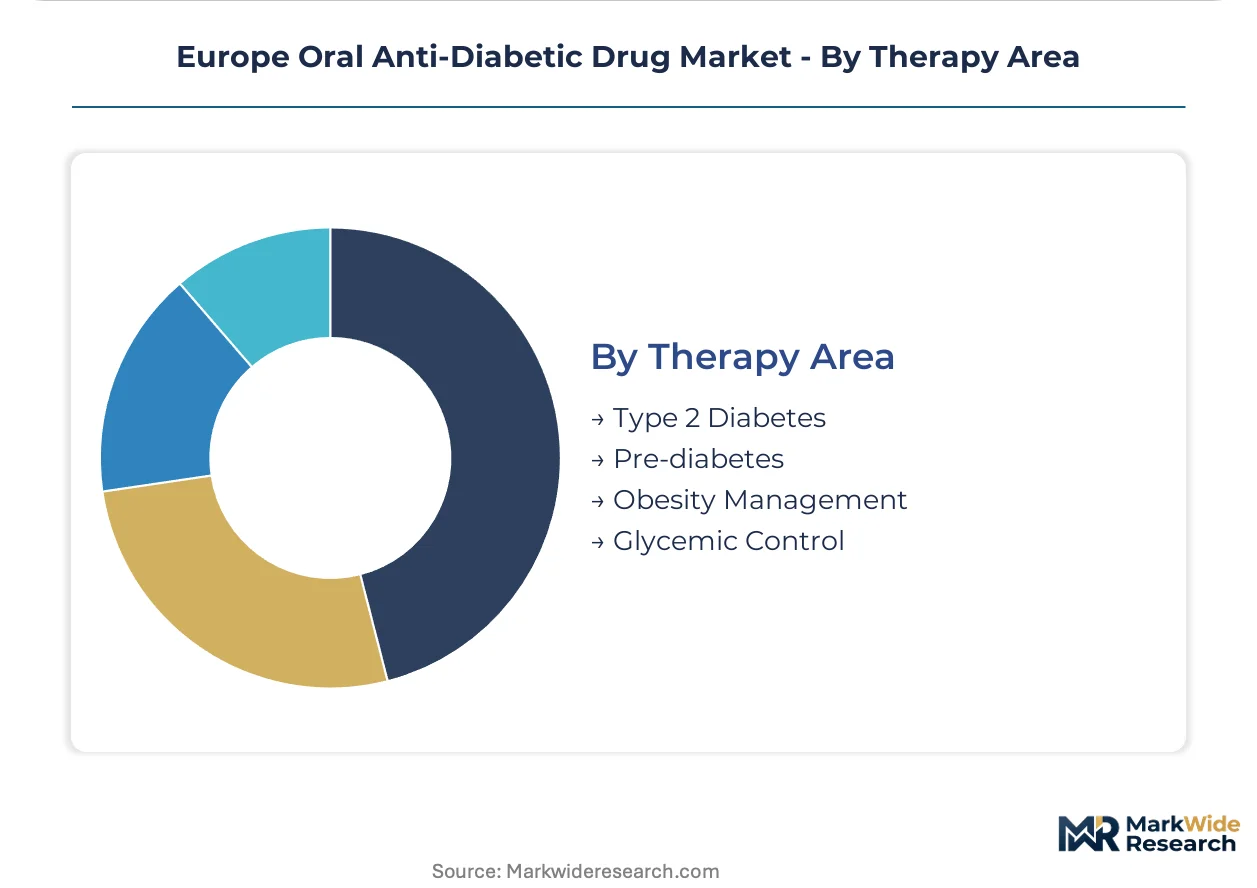
Therapy Area:
Reimbursable indication expansion reshapes commercial strategy as glycemic control alone no longer secures premium formulary placement.
- Type 2 Diabetes:Chronic metabolic disorder management drives the core volume base. German IQWiG, French HAS, and English NICE apply inconsistent evidence thresholds for novel oral agents.
- Obesity Management:Weight-loss indications for oral anti-diabetic agents create new prescriber channels beyond endocrinology. GLP-1 oral tablet development converges with patient preference for non-injectable peptide delivery.
- Pre-diabetes:Early intervention protocols in Netherlands and Denmark pilot pharmacological prevention before insulin resistance progression.
- Glycemic Control:Traditional glucose-lowering indications face margin compression as outcome-based reimbursement expands.
Type 2 diabetes absorbs the bulk of installed capacity; obesity management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in the Rhine-Ruhr and Rhône-Alpes regions anchor European oral anti-diabetic drug production. These chemical processing hubs supply formulation facilities across the continent with biguanide precursors and SGLT2 inhibitor intermediates.
Germany
Hospital formulary integration of SGLT2 inhibitors for heart failure protocols drives prescribing volume in Bavaria and North Rhine-Westphalia. IQWiG's health technology assessment mandates cardiovascular outcome data for premium reimbursement tiers. The Frankfurt-Rhine-Main pharmaceutical cluster hosts active ingredient synthesis operations for multiple oral anti-diabetic classes.
France
Dual-therapy oral regimens gain traction in Parisian hospital systems managing high-risk Type 2 diabetes cohorts. HAS evaluates cardiorenal outcome evidence when setting reimbursable price thresholds for novel agents. The Lyon-Saint-Étienne corridor concentrates formulation manufacturing capacity serving Southern European markets.
United Kingdom
NICE guidelines prioritize metformin-first protocols while expanding SGLT2 inhibitor access for renal protection indications. Digital health integration targets drive homecare self-administration adoption in Greater Manchester and Birmingham health systems. The Cambridge-London biotech corridor anchors GLP-1 oral tablet development programs.
Italy
Generic substitution protocols for DPP-4 inhibitors compress originator margins in Lombardy and Emilia-Romagna pharmacy channels. AIFA pricing negotiations reference Mediterranean market benchmarks for mature oral agents. The Milan pharmaceutical hub maintains formulation capacity for extended-release metformin supply.
Poland
Underpenetrated reimbursement frameworks in Warsaw and Kraków health regions present volume expansion potential for SGLT2 inhibitor adoption. National formularies modernize toward EU-aligned assessment criteria for cardiorenal outcome data. The Łódź chemical sector supplies excipient materials for regional formulation operations.
Europe Oral Anti-Diabetic Drug Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers reformulate around cardiorenal outcome requirements. The market structure concentrates around integrated pharmaceutical conglomerates with captive API supply and specialized biotech developers advancing peptide delivery technologies. Three archetypes prevail: legacy diabetes care incumbents with hospital channel dominance, cardiovascular-focused repositioning specialists, and oral formulation technology innovators. Competitive moves center on M&A for manufacturing capacity and strategic partnerships for bioavailability enhancement.
Within the integrated incumbent tier, Sanofi and Novo Nordisk exemplify archetypes of manufacturing footprint leverage and deep R&D commitment respectively. Sanofi's France-Germany production network secures active pharmaceutical ingredient continuity for oral portfolios. Novo Nordisk anchors non-injectable peptide development through concentrated investment in GLP-1 receptor agonist tablets. AstraZeneca occupies a differentiation-focused position where cardiovascular outcome data sustains premium formulary access across EU markets.
| Leading Market Players |
|---|
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Novo Nordisk |
| Boehringer Ingelheim |
| Merck |
| Johnson & Johnson |
| Astellas Pharma |
| Takeda Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Smart packaging integration with connected drug-device combination products is compressing traditional adherence program margins while concentrating procurement leverage among hospital systems with digital health infrastructure. EMA's Medical Device Regulation convergence simultaneously elevates compliance costs and rewards qualified European suppliers with formulary access advantages.
Pricing Analysis
Service unbundling separates patient education from product dispensing as United Kingdom retail pharmacy chains dismantle traditional counseling packages. Pricing stratifies across premium, standard, and economy tiers based on cardiovascular outcome data depth and after-sales digital adherence support. Cost compression in the DPP-4 inhibitor tier intensifies because patent expirations activate generic substitution protocols across Mediterranean markets. Hospital procurement committees demonstrate lowest price sensitivity for SGLT2 inhibitors with heart failure indications, while Eastern European national formularies exhibit highest sensitivity for sulfonylurea positioning.
Supply Chain Analysis
Dual-sourcing requirements from German and French hospital procurement committees mandate multi-supplier qualification for SGLT2 inhibitor active pharmaceutical ingredients. Manufacturing concentration centers on India, China, and Switzerland for biguanide precursors and peptide intermediates. Raw material dependencies include specialized catalysts for chiral synthesis, high-purity solvents for peptide formulation, and modified-release polymer matrices. Single-source vulnerability persists for GLP-1 receptor agonist tablet bioavailability enhancement technologies. Distribution runs through national wholesale distributors with cold-chain capabilities serving hospital pharmacies and retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EMA's evolving pharmacovigilance requirements for cardiovascular outcomes data force smaller formulation houses toward exit or acquisition.
For Market Incumbents: Anticipate margin compression in mature DPP-4 portfolios by accelerating backward integration into European API synthesis capacity. Secure captive supply of SGLT2 inhibitor intermediates through Rhine-Ruhr manufacturing footprint expansion. Counter generic substitution threats with connected packaging differentiation that hospital systems in Denmark and the Netherlands now require for reimbursement eligibility. For New Entrants and Emerging Players: Enter via underpenetrated Polish and Romanian reimbursement frameworks where national formularies modernize toward EU-aligned cardiorenal outcome criteria. Target obesity management indications for oral GLP-1 tablets where prescriber channels extend beyond endocrinology into primary care. Pursue strategic licensing partnerships with established European formulation houses to bypass IQWiG and HAS evidence threshold barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap oral formulation specialists with EMA-approved extended-release platforms given homecare self-administration protocol expansion. Long-term viability favors targets with integrated manufacturing footprints spanning France and Germany and active cardiovascular outcomes trial pipelines. Watch EMA guidance revisions on environmental risk assessments for pharmaceutical manufacturing as the inflection signal for sustainable chemistry credential premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcomes Trial Advancement | EMA's evolving guidance mandates extended follow-up protocols for SGLT2 inhibitor label expansion beyond glycemic control. |
| Backward Integration into API Synthesis | Sanofi's France-Germany production network secures active pharmaceutical ingredient continuity against distant supply chain risks. |
| Smart Packaging Integration | Connected pill dispensers with adherence monitoring integrate into Danish and Dutch hospital reimbursement frameworks. |
| Eastern European Formulary Expansion | Polish and Romanian national reimbursement frameworks modernize toward EU-aligned assessment criteria for novel oral agents. |
| GLP-1 Oral Tablet Development | Novo Nordisk anchors non-injectable peptide delivery through concentrated R&D investment in bioavailability enhancement. |
Methodological Framework
Independent corroboration across regulatory affairs leads at EMA, formulary directors in German hospital systems, and payer access specialists in French national health insurance underwrites the qualitative findings. Primary interviews with drug development executives at integrated pharmaceutical conglomerates and procurement managers at United Kingdom retail pharmacy chains combined with secondary validation from EMA centralized marketing authorization procedures, ClinicalTrials.gov cardiovascular outcomes study registries, and national formulary databases. Bottom-up prescription volume modeling and top-down market sizing triangulation across Germany, France, United Kingdom, Italy, and Poland anchor the quantitative framework.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include molecular class, end-user channel, formulation technology, and reimbursable indication expansion. CAGRs derive from patient population epidemiology, therapy line progression rates, and formulary access evolution. Forecast inputs incorporate EMA submission timelines for cardiorenal outcome label extensions and REACH chemical safety compliance cost trajectories.
Revisions become necessary when EMA pharmacovigilance guidance shifts materially, REACH obligations extend to additional excipient categories, or national health technology assessment bodies harmonize evidence thresholds across IQWiG, HAS, and NICE. Deviation in SGLT2 inhibitor cardiovascular outcomes trial readouts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Carbapenem Market