
 Obsessive-Compulsive Disorder Market | 2026-2036
Obsessive-Compulsive Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Obsessive-Compulsive Disorder Market Analytics
Psychiatrist availability is bifurcating the Obsessive-Compulsive Disorder market into markets with sufficient specialized clinicians and those facing acute shortages. Pfizer Inc. leverages its established SSRI manufacturing infrastructure to sustain formulary presence across major health systems. Eli Lilly and Company differentiates through its neuroscience R&D pipeline, while H. Lundbeck A/S anchors its position in European psychiatric markets with deep therapeutic expertise.
Obsessive-Compulsive Disorder constitutes a chronic neuropsychiatric condition characterized by intrusive thoughts and repetitive compulsive behaviors, typically managed through serotonin reuptake inhibition or structured behavioral intervention. SSRIs dominate prescription volumes as first-line pharmacological treatment, while Cognitive Behavioral Therapy commands premium reimbursement in private practice settings. The Delivery Mode dimension is fragmenting as telehealth platforms compete with traditional in-person protocols for patient retention and clinical outcomes.
The FDA regulates OCD drug approvals through its Division of Psychiatry Products, while HIPAA governs patient data flows across telehealth and hybrid delivery channels. The DEA additionally controls scheduled compounds used in treatment-resistant cases, creating compliance complexity for multi-state providers. Stakeholders must monitor how the FDA's emerging digital therapeutics framework will classify and reimburse app-based exposure therapy protocols.
Market Dynamics
The FDA's accelerated approval pathways for breakthrough mental health therapies are compressing development timelines and forcing established psychiatric drug portfolios to defend formulary positions against novel mechanism entrants.
Growth Catalysts
- Telehealth Infrastructure:HIPAA-compliant virtual care platforms are extending CBT access into rural and underserved psychiatric markets, reducing geographic barriers to specialized OCD treatment.
- EMA Orphan Designation Pathways:European regulatory incentives for treatment-resistant OCD indications are attracting neuroscience R&D investment into glutamatergic and neuroimmune modulation targets.
- German University Medical Clusters:Heidelberg, Munich and Berlin medical centers are consolidating OCD research, patient registries and specialized outpatient services into integrated care models.
Market Restraints
- Serotonin Reuptake Inhibitor Supply Concentration:Active pharmaceutical ingredient manufacturing for fluoxetine and sertraline concentrates in Indian and Chinese chemical intermediates suppliers, creating single-source vulnerability.
- Specialized Clinician Scarcity:Exposure and Response Prevention therapy requires certified behavioral therapists; training pipeline bottlenecks in the United States and United Kingdom limit service expansion regardless of patient demand.
- DEA Scheduling Friction:Ketamine and psilocybin compounds for treatment-resistant OCD face controlled substance classification barriers that fragment multi-state provider compliance and reimbursement standardization.
Strategic Opportunities
- Digital Therapeutics Reimbursement:The FDA's emerging software-as-medical-device framework for app-based exposure therapy creates precedent for prescription digital therapeutic coverage through commercial payers.
- Pediatric OCD Undertreatment:Early-onset obsessive-compulsive disorder in the United States shows significant diagnostic delay; school-based screening partnerships represent untapped channel development.
- Neuroimaging Biomarker Integration:fMRI-based treatment response predictors are converging with machine learning classification to enable personalized SSRI selection and CBT intensity calibration.
Industry Challenges
- Behavioral Therapist Training Lag:Certification requirements for Exposure and Response Prevention specialization extend 18-24 months, creating workforce expansion friction even where capital for clinic scaling is available.
- EHR Interoperability for Hybrid Care:Telehealth platforms and in-person psychiatric practices operate on disconnected documentation systems, complicating continuity of care and outcome measurement across delivery modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Obsessive-Compulsive Disorder Market |
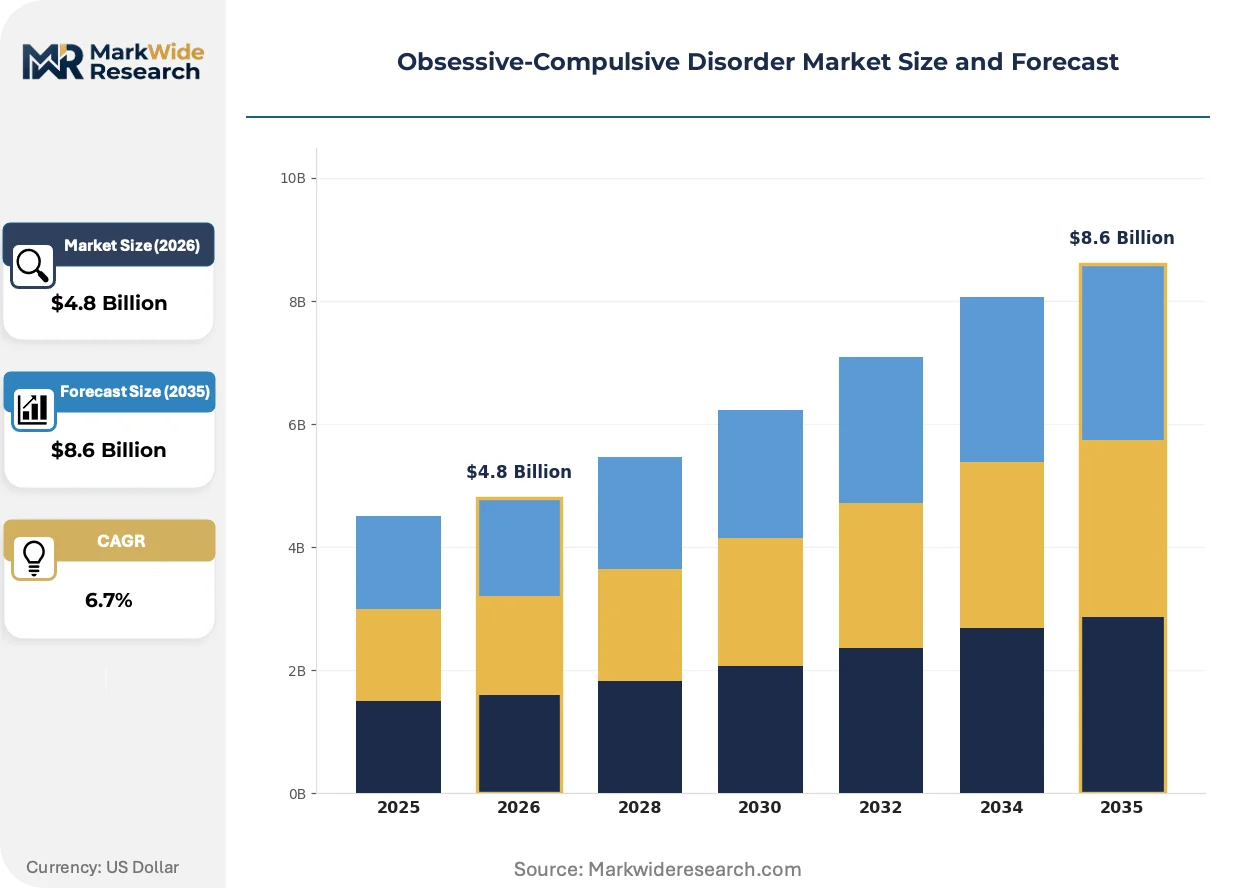
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Cognitive Behavioral Therapy, Exposure Therapy End User: Hospitals, Clinics, Private Practices, Telehealth Services Delivery Mode: In-person, Online, Hybrid, Home-based Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline Plc, H. Lundbeck A/S, Jazz Pharmaceuticals Plc, AbbVie Inc., Apotex Inc., Novartis AG, Biohaven Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Obsessive-Compulsive Disorder Market Evolving Landscape
Deep brain stimulation hardware and closed-loop neurofeedback systems are migrating from Parkinson's and epilepsy applications into psychiatric device portfolios, reframing treatment-resistant OCD as a neuromodulation addressable condition rather than strictly pharmaceutical.
Transcranial magnetic stimulation protocols optimized for cortico-striatal circuit modulation are supplanting maintenance SSRI monotherapy in academic medical center outpatient departments. Psychiatrists at Stanford and McLean Hospital are adopting accelerated theta-burst paradigms that compress treatment courses from six weeks to five days. This compression is enabling same-day consultation-to-treatment workflows that capture patients who would otherwise abandon care during traditional scheduling delays.
The FDA's draft guidance on digital therapeutics for psychiatric conditions is forcing platform developers to generate randomized controlled trial evidence equivalent to drug submissions. Software vendors including prescription digital therapeutic startups must now budget for pivotal trials and quality management systems that mirror pharmaceutical manufacturing standards. European competitors are responding by pursuing CE marking under MDR Class IIa pathways to establish regulatory precedent ahead of FDA alignment.
Self-referral through employer assistance programs is displacing traditional primary care gatekeeping for OCD diagnosis in the United States. Large self-insured employers including technology and financial services firms are contracting directly with specialized virtual CBT providers, bypassing health system networks entirely. This channel shift is most visible in California and Massachusetts where behavioral health parity enforcement and tech-sector benefits competition converge.
Obsessive-Compulsive Disorder Market Segmentation
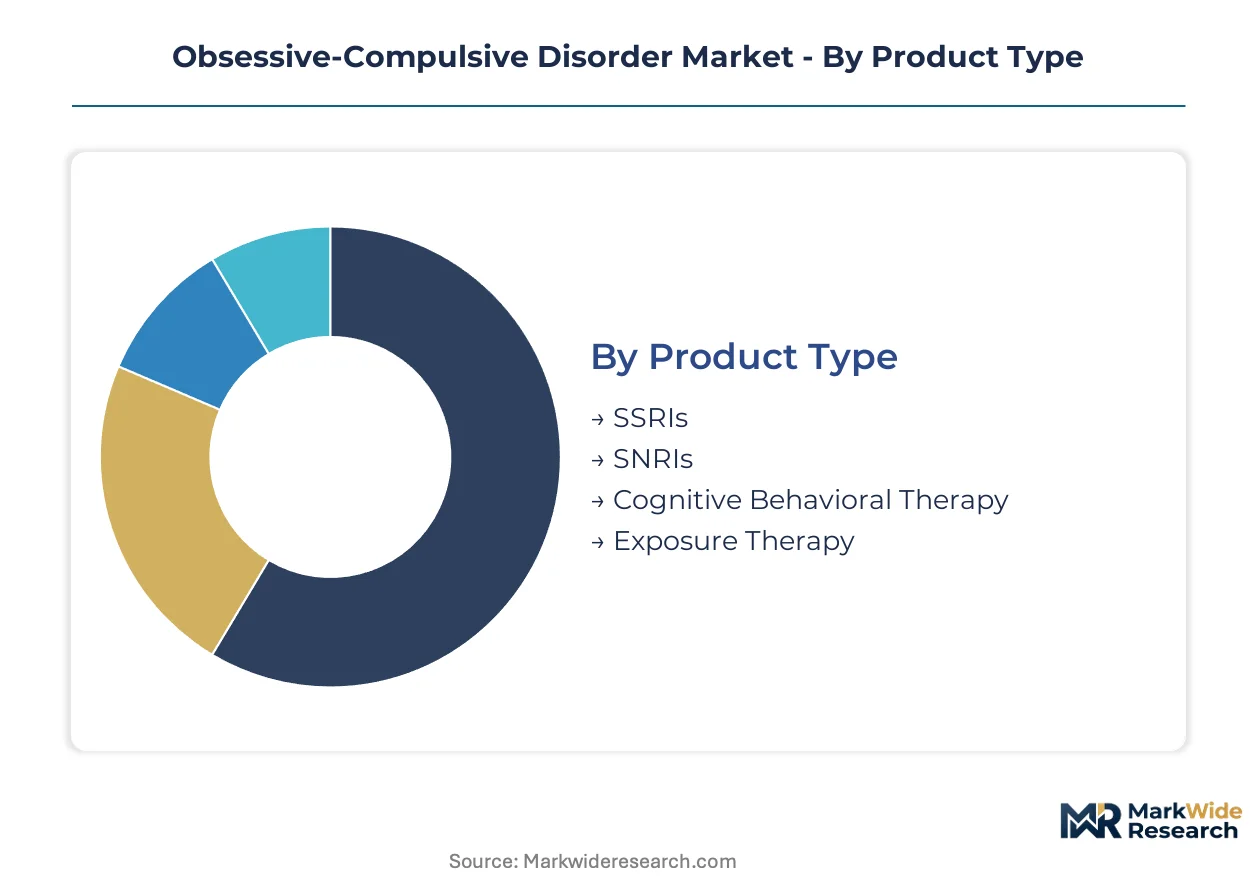
Segmentation in the Obsessive-Compulsive Disorder market reveals how reimbursement structures, clinical workforce distribution, and regulatory pathways fragment commercial opportunity. Understanding where margin pools concentrate versus where volume flows helps stakeholders allocate capital across pharmaceutical, behavioral, and technology-enabled service models.
Product Type:
Margin pools concentrate in maintenance pharmacotherapy and specialized behavioral protocols that command premium reimbursement from commercial payers.
- SSRIs:Serotonin reuptake inhibitors constitute the foundational pharmacological intervention, with fluoxetine and sertraline commanding sustained formulary placement across Medicare Part D and commercial formularies. Demand concentrates in primary care settings where physician extenders manage stable patients, though psychiatric practices capture higher per-prescription margins through brand-to-generic switching protocols.
- Cognitive Behavioral Therapy:Structured CBT protocols generate the highest per-session reimbursement in private practice and academic medical center settings, with Exposure and Response Prevention variants commanding premium rates from self-insured employers. Massachusetts and California psychiatric practices report strongest payer acceptance for intensive outpatient CBT programs.
- SNRIs:Serotonin-norepinephrine reuptake inhibitors address comorbid anxiety presentations in treatment-resistant cases, with venlafaxine and duloxetine prescribed when SSRI monotherapy fails.
- Exposure Therapy:Specialized exposure protocols require certified therapist credentialing, limiting supply expansion regardless of patient demand in rural United States markets.
SSRIs hold installed capacity. Cognitive Behavioral Therapy is rotating up the share rankings.
End User:
Volume flows toward settings that can absorb fixed costs of specialized workforce training and regulatory compliance infrastructure.
- Hospitals:Academic medical centers anchor complex case management, with Stanford and McLean Hospital operating dedicated OCD inpatient and partial hospitalization programs that attract regional referral patterns. These centers capture highest-margin cases involving comorbid psychiatric conditions requiring multidisciplinary coordination.
- Telehealth Services:Virtual CBT platforms are expanding fastest among self-insured employers in technology and financial services sectors, bypassing traditional health system networks through direct contracting arrangements. HIPAA-compliant infrastructure investments create barriers to entry that protect early movers.
- Clinics:Community mental health centers serve Medicaid populations with medication management and group CBT protocols.
- Private Practices:Solo and small-group psychiatric practices dominate maintenance SSRI prescribing in suburban United States markets.
Hospitals hold installed capacity. Telehealth Services is climbing the fastest.
Delivery Mode:
Regulatory fragmentation across state licensing boards and DEA scheduling creates margin differentiation between synchronous virtual care and in-person protocols.
- In-person:Traditional face-to-face psychiatric consultation and CBT delivery retains highest reimbursement rates from commercial payers, with university medical centers in Germany and the United States commanding premium positioning for treatment-resistant case referrals.
- Hybrid:Blended models combining initial in-person assessment with maintenance telehealth sessions are gaining fastest adoption among large multi-state psychiatric practices seeking to extend geographic reach without full licensure compliance burdens.
- Online:Fully virtual platforms face state-by-state licensing friction but capture employer-direct contract volume.
- Home-based:In-home exposure therapy for severe avoidance presentations remains limited to concierge and academic settings.
In-person holds installed capacity. Hybrid is gaining share fastest.
Age Group:
Diagnostic infrastructure and school-based screening partnerships determine where commercial investment flows across developmental stages.
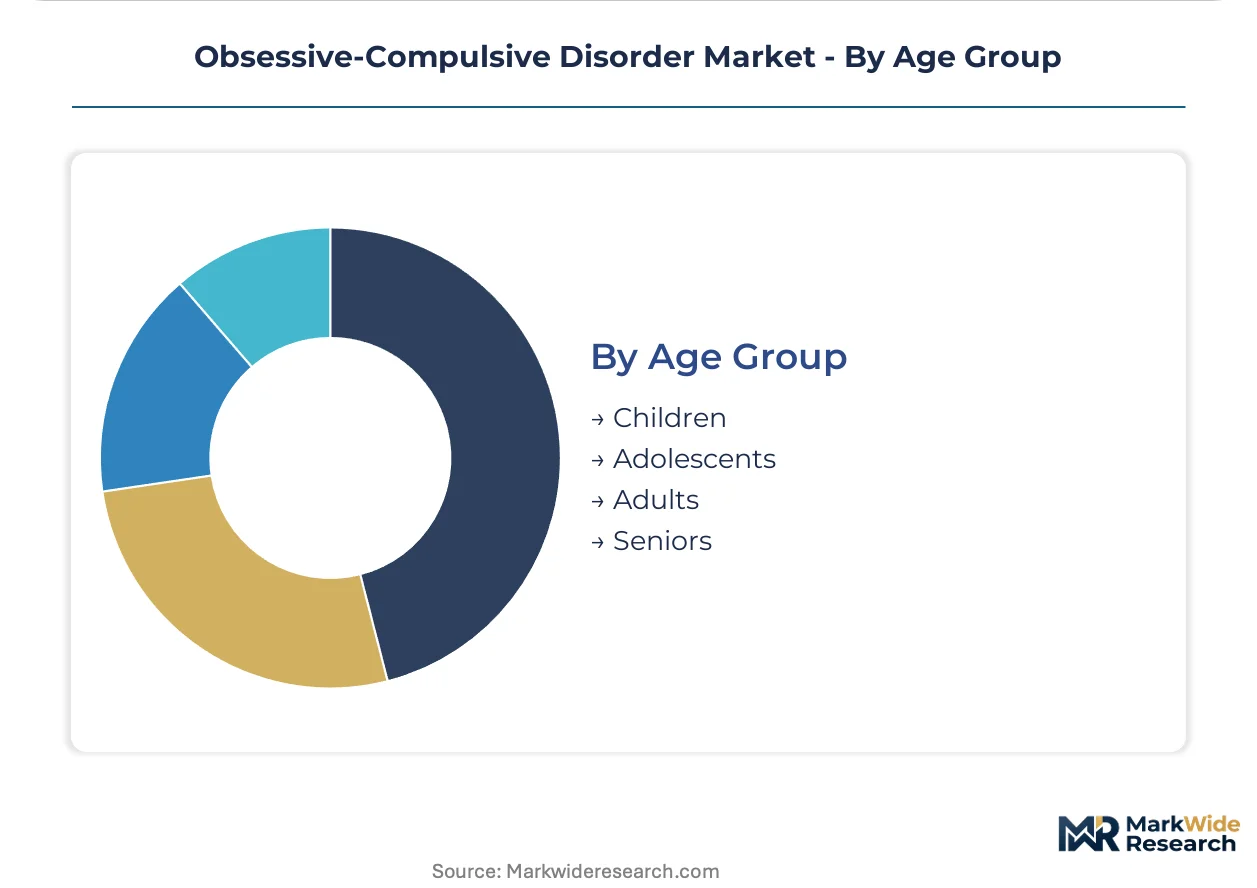
- Adults:The established diagnostic and treatment infrastructure for adult OCD generates predictable reimbursement flows, with maintenance SSRI prescribing and outpatient CBT representing the most mature commercial segment. United States psychiatric practices report strongest payer mix stability in the 25-45 age cohort.
- Children:Early-onset OCD shows significant diagnostic delay in United States school systems, creating opportunity for screening partnership models that capture cases before secondary impairment develops. Academic medical centers with pediatric psychiatry fellowship programs anchor this segment.
- Adolescents:Transitional age youth present highest treatment discontinuation risk, requiring specialized retention protocols.
- Seniors:Late-onset obsessive-compulsive symptoms often overlap with neurodegenerative presentations, complicating pure OCD service line development.
Adults hold installed capacity. Children is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for OCD treatment diverge sharply across major markets. The United States prioritizes employer-direct telehealth channels, Germany emphasizes university medical center integration, and Japan maintains psychiatrist-centric delivery despite digital platform entry.
United States
Self-insured employers in technology and financial services sectors now contract directly with virtual CBT providers, bypassing traditional health system networks entirely. FDA accelerated approval pathways for breakthrough mental health therapies compress development timelines for novel mechanism entrants. Stanford and McLean Hospital anchor dedicated OCD inpatient and partial hospitalization programs that attract regional referral patterns for complex cases.
Germany
University medical centers in Heidelberg, Munich, and Berlin consolidate OCD research, patient registries, and specialized outpatient services into integrated care models. EMA orphan designation pathways for treatment-resistant OCD indications attract neuroscience R&D investment into glutamatergic modulation targets. The Heidelberg University Hospital cluster coordinates multi-site clinical trials with standardized assessment protocols.
United Kingdom
Exposure and Response Prevention therapy certification bottlenecks limit service expansion regardless of patient demand, particularly in rural markets. National Health Service mental health transformation funding prioritizes IAPT program integration for OCD-specific pathways. The South London and Maudsley NHS Foundation Trust operates one of Europe's largest dedicated OCD treatment units.
Japan
Psychiatrist availability constraints preserve traditional in-person consultation models despite regulatory approval of digital therapeutics platforms. PMDA review timelines for psychiatric drug approvals extend longer than FDA or EMA equivalents, slowing novel entrant market access. The National Center of Neurology and Psychiatry in Kodaira anchors specialized OCD research and resident training programs.
Canada
Provincial health authority reimbursement variation creates patchwork access to intensive outpatient CBT programs across Ontario, British Columbia, and Quebec. Health Canada regulatory alignment with FDA breakthrough therapy designations accelerates priority review for treatment-resistant OCD indications. The Centre for Addiction and Mental Health in Toronto coordinates national practice guideline development and clinician training networks.
Obsessive-Compulsive Disorder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Obsessive-Compulsive Disorder market. Established pharmaceutical manufacturers with SSRI manufacturing infrastructure defend formulary positions against neuroscience R&D specialists pursuing novel mechanisms. Three archetypes dominate: large-cap diversified pharmaceutials with psychiatric portfolios, mid-cap neuroscience-focused developers, and generic manufacturers supplying volume markets. Competitive moves concentrate on M&A for pipeline access and strategic partnerships bridging pharmaceutical and digital therapeutic modalities.
Among large-cap diversified pharmaceuticals, Pfizer Inc. and Eli Lilly and Company exemplify contrasting strategic positions. Pfizer leverages established manufacturing infrastructure to sustain broad formulary presence across Medicare Part D and commercial health systems. Eli Lilly occupies a position within the neuroscience R&D specialist archetype, with its pipeline orientation reflecting investment in novel mechanism targets beyond serotonin reuptake inhibition. H. Lundbeck A/S anchors the European psychiatric market specialist tier, with its Denmark-based structure reflecting deep therapeutic expertise concentration in neuropsychiatric conditions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline Plc |
| H. Lundbeck A/S |
| Jazz Pharmaceuticals Plc |
| AbbVie Inc. |
| Apotex Inc. |
| Novartis AG |
| Biohaven Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory buffers for fluoxetine and sertraline active pharmaceutical ingredients tie pricing power directly to concentrated chemical intermediate sourcing from Indian and Chinese suppliers, creating asymmetric leverage for contract manufacturers over formulation specialists.
Pricing Analysis
Long-term offtake agreements between generic SSRI manufacturers and Indian API suppliers dominate procurement structures, with spot-market exposure limited to shortage-driven emergency sourcing. Three-tier pricing structure across premium, standard, and economy levels separates patented extended-release formulations from authorized generics and commodity-grade tablets. Pricing pressure stems from Medicare Part D rebate compression and Medicaid best-price requirements, squeezing margins on high-volume sertraline prescriptions. Self-insured employers show lowest price sensitivity for certified Exposure and Response Prevention protocols, while Medicaid programs drive hardest bargains on maintenance pharmacotherapy.
Supply Chain Analysis
Port congestion at Mumbai and Shanghai container terminals elevates inbound logistics costs for serotonergic API shipments, adding 15-20 days to standard delivery schedules for European and North American formulation plants. Active pharmaceutical ingredient manufacturing concentrates in India, China, and select Italian chemical hubs, with fluoxetine precursors drawing from Hubei province intermediates suppliers. Single-source vulnerability pervades the sertraline synthesis pathway, where one Zhejiang-based producer controls critical naphthol derivative output. Distribution runs through specialized cold-chain logistics for temperature-sensitive compounds, with regional depots in Frankfurt and Chicago serving hospital and retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires incumbent defense against digital therapeutic substitution, as FDA-cleared app-based exposure therapy protocols threaten to displace traditional CBT reimbursement models.
For Market Incumbents: Secure exclusive formulary placement for novel glutamatergic modulators through FDA breakthrough therapy designation pathways, locking out generic SSRI switching protocols. Deepen upstream control over API synthesis by acquiring Indian chemical intermediate suppliers, eliminating single-source exposure that competitors could exploit during shortage events. Reinforce certified therapist networks through academic medical center training partnerships, creating workforce scarcity that protects premium CBT reimbursement.
For New Entrants and Emerging Players: Pediatric OCD screening partnerships with United States school districts represent the most penetrable white-space target, capturing diagnostic delay cases before established psychiatric practices intervene. Employer-direct contracting for virtual CBT platforms bypasses health system gatekeeping entirely, with technology and financial services sectors showing fastest adoption velocity. Pursue CE marking under MDR Class IIa pathways for digital therapeutics to establish European regulatory precedent ahead of FDA submission.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents divesting legacy psychiatric portfolios, particularly SSRI manufacturing infrastructure with established Medicare Part D contracts. Long-term viability hinges on neuromodulation device integration, where closed-loop neurofeedback systems address treatment-resistant cases beyond pharmaceutical reach. Watch for inflection signals in pediatric digital therapeutic reimbursement decisions by major commercial payers, which would validate platform-based care models.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated FDA pathways for glutamatergic targets compress development timelines against SSRI incumbents. |
| Regulatory Approval Pathway | EMA orphan designation for treatment-resistant OCD indications attracts neuroscience R&D investment into novel mechanisms. |
| Strategic Partnership | University medical center collaborations in Germany integrate patient registries with specialized outpatient services. |
| Product Launch | Prescription digital therapeutic platforms with HIPAA-compliant infrastructure capture employer-direct contract volume. |
| Reimbursement Strategy | Commercial payer coverage for app-based exposure therapy creates precedent for software-as-medical-device billing codes. |
Research Methodology
A standing panel of psychiatric practice administrators, formulary directors at commercial payers, DEA compliance officers, and exposure therapy certification program directors provided ongoing calibration against secondary validation sources. Primary interviews with drug development executives at neuroscience-focused developers and procurement leads at Indian API manufacturers combined with FDA filing reviews, ClinicalTrials.gov registry analysis, Medicare Part D formulary databases, and EMA submission documents. Bottom-up prescription volume modeling and top-down market size triangulation anchored quantitative outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled by treatment line, delivery mode, age group, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating SSRI generic erosion rates, telehealth platform adoption trajectories, and neuromodulation device penetration assumptions. Forecast inputs included certified therapist training pipeline capacity, DEA scheduling petition timelines, and digital therapeutic reimbursement policy evolution.
Underlying assumptions cover stable FDA accelerated approval pathway access, HIPAA enforcement continuity, and API supply chain resiliency, with deviation risk concentrated in DEA rescheduling decisions for psilocybin and ketamine compounds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Schizophrenia Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Depression Treatment Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
Mental Health Market