
 Japan Pharmaceutical 3PL Market | 2026-2036
Japan Pharmaceutical 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Pharmaceutical 3PL Market Foresight
Biodegradable thermal packaging is expanding its share in cold chain pharmaceutical logistics, displacing conventional expanded polystyrene shippers across Japan's temperature-sensitive distribution networks. Nippon Express Holdings leverages its nationwide refrigerated depot network to sustain same-day delivery coverage for biologics manufacturers. Sagawa Express competes through dense last-mile routing in Osaka and Nagoya metropolitan zones. Mitsubishi Logistics anchors high-value pharmaceutical storage with seismic-resistant warehouse designs.
Pharmaceutical third-party logistics encompasses outsourced supply chain management for drug products, requiring validated temperature monitoring systems, serialized track-and-trace infrastructure, and contamination-controlled handling environments to maintain product integrity from manufacturer to patient. Cold chain logistics leads service type revenue due to Japan's expanding biologics pipeline and strict stability requirements for mRNA therapies. Warehousing for pharmaceutical manufacturers captures concentrated margin pools, as GMP-certified facilities with redundant climate control systems command premium pricing. Direct delivery from inventory management hubs is accelerating, bypassing traditional distributor layers for hospital and pharmacy networks.
PMDA enforces serialization mandates under Japan's traceability regulations, compelling 3PL providers to upgrade barcode verification infrastructure throughout distribution chains. METI's energy efficiency standards for refrigerated transport are reshaping fleet procurement toward electric and hybrid cold chain vehicles. GDP inspections by prefectural pharmaceutical regulators determine market access eligibility, creating compliance barriers for undercapitalized operators. Stakeholders must monitor how Japan's carbon neutrality roadmap for logistics will alter total cost of ownership calculations across pharmaceutical distribution networks.
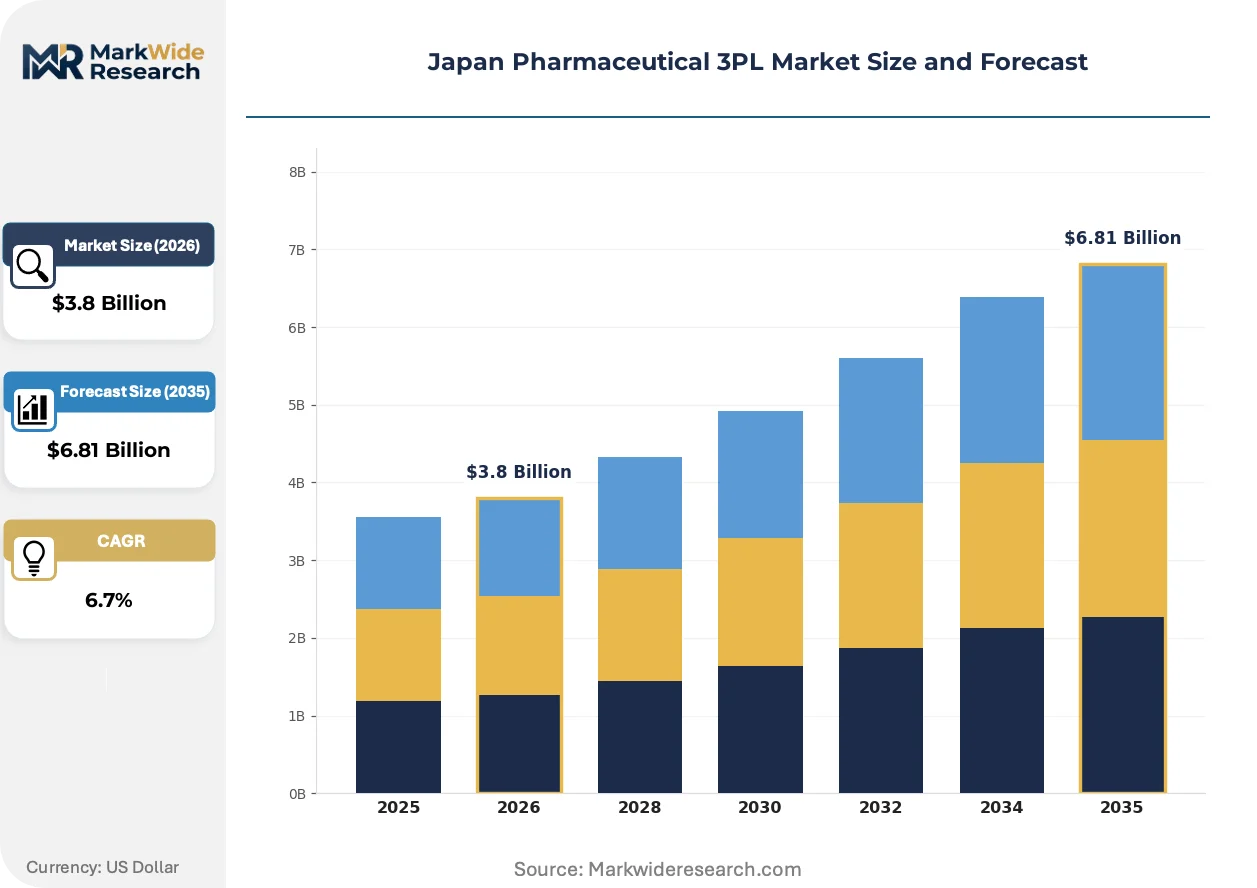
Market Dynamics
Japan's pharmaceutical 3PL sector is compressing around temperature-validated infrastructure as biologics manufacturers abandon in-house distribution networks. METI's carbon neutrality mandates for commercial transport are forcing fleet replacement decisions ahead of depreciation cycles.
Growth Catalysts
- mRNA therapy cold chain:PMDA stability guidelines for nucleic acid therapeutics require validated -70°C distribution, expanding specialized 3PL contract volumes.
- Osaka-Nagoya manufacturing corridor:Biotech production clusters in central Japan generate concentrated demand for regional hub-and-spoke logistics.
- Serialized track-and-trace infrastructure:Japan's Pharmaceutical and Medical Device Act enforcement compels manufacturers to outsource barcode verification systems to compliant 3PL operators.
Market Restraints
- Electric cold chain vehicle capex:METI emission standards require refrigerated fleet replacement with battery-electric alternatives carrying 40% higher acquisition costs versus diesel equivalents.
- Seismic engineering requirements:Japan Building Standard Law mandates base-isolated warehouse construction in high-risk zones, elevating facility development costs.
- Qualified technician scarcity:GDP-certified cold chain operations require licensed pharmacists for supervisory roles, constraining workforce scalability.
Strategic Opportunities
- Kyushu pharmaceutical cluster expansion:Fukuoka's biotech incubation zone lacks mature 3PL infrastructure, creating first-mover positioning for temperature-validated entrants.
- Biodegradable shipper convergence:Cellulose-based thermal packaging combined with IoT temperature loggers enables compliance-plus-sustainability service differentiation.
- Direct-to-pharmacy distribution:Hospital procurement centralization is bypassing traditional wholesalers, opening inventory-hub bypass channels for 3PL operators.
Industry Challenges
- Multi-site GDP certification timelines:PMDA inspection backlogs delay operational authorization for new depot openings, compressing revenue recognition windows.
- Legacy WMS integration friction:Pharmaceutical manufacturers' serialized inventory systems require custom API development for 3PL data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Pharmaceutical 3PL Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Logistics, Warehousing, Transportation, Inventory Management End User: Pharmaceutical Manufacturers, Biotech Companies, Contract Research Organizations, Distributors Delivery Mode: Cold Chain, Ambient, Direct Delivery, Cross-docking Regulatory Compliance: GMP, GDP, ISO Certification, Serialization |
| Companies Covered | Nippon Express Holdings, Suzuken Group, DHL Group, Kuehne+Nagel, Mitsubishi Logistics, LOGISTEED, Yusen Logistics, Sagawa Express, Yamato Transport, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Pharmaceutical 3PL Market Shifts & Advancements
Blockchain-enabled temperature verification is restructuring liability allocation between pharmaceutical sponsors and logistics contractors. Real-time custody documentation is displacing batch-record reconciliation.
Phase-change material thermal shippers with embedded IoT sensors are decentralizing cold chain assurance from centralized depot monitoring to individual package-level validation. Biologics manufacturers are adopting these systems for clinical trial material distribution. Point-to-point temperature accountability is compressing insurance premium differentials between 3PL tiers.
PMDA's serialization mandate under Japan's traceability regulations is forcing infrastructure upgrades across distribution networks. Barcode verification hardware must interface with national drug tracking databases. Small and mid-tier 3PL operators are consolidating to share compliance system costs.
Hospital procurement groups are consolidating vendor panels and demanding outcome-based logistics contracts with penalty clauses for temperature excursions. Traditional fee-per-shipment pricing is retreating. Kanto region academic medical centers are piloting these arrangements first.
Japan Pharmaceutical 3PL Market Segmentation
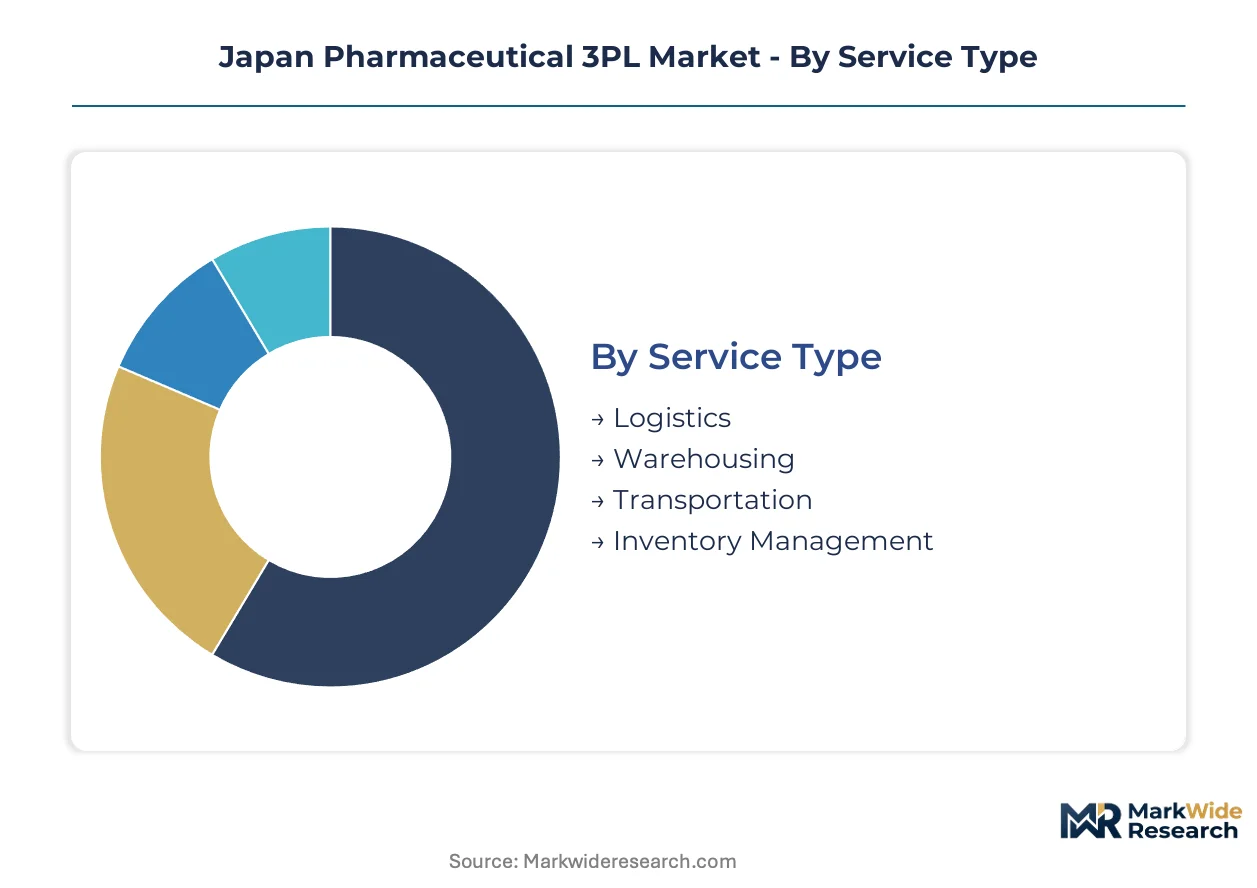
Segmentation in Japan's pharmaceutical 3PL market reveals how infrastructure investments align with regulatory tiering and therapeutic complexity. Service providers configure capabilities around GDP certification levels, temperature requirements, and end-user procurement centralization patterns.
Service Type:
Facility upgrade cycles and fleet replacement timelines concentrate investment in temperature-validated service categories, with METI carbon mandates accelerating capital deployment toward electric cold chain infrastructure.
- Logistics:Integrated supply chain orchestration combining route optimization, customs brokerage, and last-mile sequencing for time-critical biologics. Demand clusters around Greater Tokyo Area manufacturing hubs where airport access enables same-day international distribution.
- Warehousing:GMP-certified facilities with redundant climate control, seismic base isolation, and serialized inventory management systems. Pharmaceutical manufacturers in Osaka-Nagoya corridor pay premium rates for earthquake-resistant designs meeting Japan Building Standard Law.
- Transportation:Refrigerated fleet operations spanning -70°C ultra-low to controlled ambient ranges. METI emission standards are forcing accelerated diesel-to-electric conversion ahead of normal depreciation cycles.
- Inventory Management:Vendor-managed stock programs with direct-to-hospital replenishment triggers. Procurement centralization at Kanto region academic medical centers is expanding contract volumes for hub-based inventory positioning.
Warehousing sits at the top of the volume ranking, with inventory management climbing the fastest.
End User:
Customer type determines compliance depth and contract structure, with biologics producers demanding validated cold chain documentation that generic manufacturers rarely require.
- Pharmaceutical Manufacturers:Large-scale innovators outsourcing distribution of small-molecule and biologic portfolios. Serialization mandates under Japan's Pharmaceutical and Medical Device Act compel barcode verification infrastructure upgrades.
- Biotech Companies:Emerging therapeutics developers lacking captive logistics networks. mRNA therapy pipelines require -70°C validated distribution, expanding specialized 3PL contract volumes fastest.
- Contract Research Organizations:Clinical trial material logistics with patient-specific dosing and blinded shipment requirements. Phase-change material thermal shippers with embedded IoT sensors are displacing conventional monitoring approaches.
- Distributors:Traditional wholesale layers facing disintermediation as hospital procurement groups consolidate vendor panels. Direct-to-pharmacy channels are compressing their margin capture.
Pharmaceutical manufacturers anchor current revenue, while biotech companies are expanding most quickly.
Delivery Mode:
Modal selection tracks product stability requirements and point-of-care urgency, with temperature excursion liability reshaping carrier selection criteria.
- Cold Chain:Validated temperature-controlled distribution from -70°C through 2-8°C and 15-25°C ranges. PMDA stability guidelines for nucleic acid therapeutics are expanding specialized infrastructure requirements.
- Ambient:Controlled room temperature distribution for stable small-molecule formulations. Generic manufacturers in Kyushu pharmaceutical cluster rely on ambient networks for cost-sensitive volume products.
- Direct Delivery:Inventory-hub bypass eliminating traditional wholesale layers. Hospital procurement centralization is opening direct channels for 3PL operators with serialized track-and-trace capabilities.
- Cross-docking:Rapid consolidation and transfer without intermediate storage. Osaka-Nagoya manufacturing corridor generates concentrated demand for regional hub-and-spoke cross-dock facilities.
Cold chain commands the premium tier by margin, with direct delivery gaining share fastest.
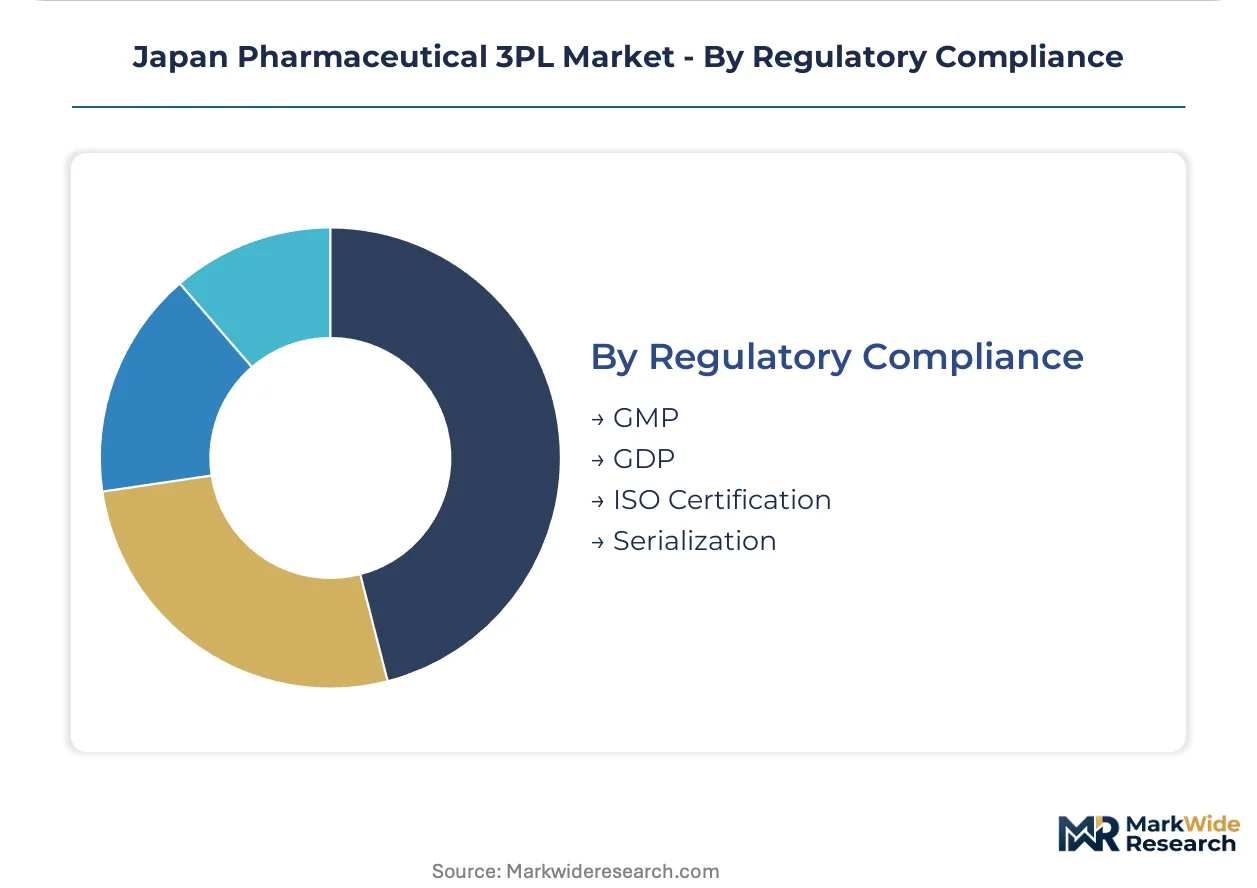
Regulatory Compliance:
Certification tier determines market access eligibility, with PMDA inspection backlogs creating operational authorization bottlenecks for new depot openings.
- GMP:Good Manufacturing Practice standards for pharmaceutical production and storage environments. Warehousing for active pharmaceutical ingredients requires GMP-certified climate control systems.
- GDP:Good Distribution Practice enforcement under Japan's revised Pharmaceutical and Medical Device Act. Prefectural pharmaceutical regulator inspections determine market access eligibility, elevating compliance barriers.
- ISO Certification:Quality management system validation for operational consistency. Small and mid-tier operators are consolidating to share ISO compliance system costs.
- Serialization:National drug tracking database integration with barcode verification hardware. Blockchain-enabled temperature verification is restructuring liability allocation between sponsors and logistics contractors.
GDP certification sits at the top of the volume ranking, with serialization climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Tokyo Area concentrates Japan's pharmaceutical 3PL infrastructure around Narita and Haneda airport access, same-day distribution networks, and dense hospital procurement clusters. METI's carbon neutrality mandates and PMDA's tightened GDP enforcement are reshaping facility investment patterns across Japan's regional logistics landscape.
Kanto Region
Tokyo's biologics manufacturing corridor generates concentrated demand for -70°C validated distribution and serialized track-and-trace infrastructure. PMDA inspection protocols determine depot authorization timelines, compressing revenue recognition for new market entrants. Chiba and Saitama prefectures host seismic-resistant warehouse clusters serving Kanto region academic medical centers.
Kansai Region
Osaka's pharmaceutical production base drives regional hub-and-spoke logistics demand, with Kyoto and Kobe forming secondary distribution nodes. Japan Building Standard Law mandates base-isolated construction in this high-seismic zone, elevating facility development costs. The Osaka-Nagoya manufacturing corridor generates cross-dock consolidation volumes for central Japan biotech clusters.
Chubu Region
Nagoya anchors automotive-to-pharma logistics diversification, with Aichi prefecture warehousing converting capacity for temperature-controlled pharmaceutical storage. METI energy efficiency standards for refrigerated transport are accelerating electric fleet procurement ahead of normal replacement cycles. GMP-certified facilities in Shizuoka serve as redundant backup for Tokyo-Osaka corridor disruptions.
Kyushu Region
Fukuoka's biotech incubation zone lacks mature 3PL infrastructure, creating positioning opportunities for temperature-validated entrants. Prefectural pharmaceutical regulators conduct GDP inspections determining market access eligibility for new operators. Generic manufacturers in Kyushu rely on ambient distribution networks for cost-sensitive volume products.
Hokkaido and Tohoku
Sapporo and Sendai operate as satellite distribution nodes with limited biologics infrastructure, primarily handling stable small-molecule formulations. Cold chain logistics providers maintain minimal presence due to dispersed demand and harsh winter transport conditions. Regional hospital networks depend on Kanto-based inventory hubs for temperature-sensitive therapeutics.
Japan Pharmaceutical 3PL Market Competitive Landscape
Global majors compete with regional champions across temperature-validated infrastructure and GDP-certified depot networks. The market structures around three tiers: integrated logistics conglomerates with nationwide cold chain coverage, pharmaceutical-specialized regional operators, and global forwarders leveraging international gateway access. Consolidation pressure intensifies as serialization mandates and METI carbon regulations elevate compliance system costs beyond mid-tier operator capacity. Dominant competitive moves include strategic partnerships for shared GDP certification costs and fleet electrification investments ahead of regulatory deadlines.
Among Japan-based integrated logistics providers, Nippon Express Holdings, Mitsubishi Logistics, and Sagawa Express exemplify contrasting strategic archetypes. Nippon Express Holdings occupies a position representing nationwide refrigerated depot scale. Mitsubishi Logistics anchors seismic-resistant pharmaceutical warehousing specialization. Sagawa Express sits within dense metropolitan last-mile routing capability. Global forwarders DHL Group and Kuehne+Nagel represent international gateway access and cross-border pharmaceutical trade facilitation.
| Leading Market Players |
|---|
| Nippon Express Holdings |
| Suzuken Group |
| DHL Group |
| Kuehne+Nagel |
| Mitsubishi Logistics |
| LOGISTEED |
| Yusen Logistics |
| Sagawa Express |
| Yamato Transport |
| Others |
Supply & Pricing Matrix
Hospital procurement centralization in Kanto region academic medical centers is compressing fee-per-shipment pricing toward outcome-based contracts with temperature excursion penalty clauses. This buyer concentration is reshaping how 3PL operators structure risk allocation across pharmaceutical distribution networks.
Pricing Analysis
Electric cold chain vehicle acquisition costs are passing through to contract rates as METI emission standards force fleet replacement ahead of normal depreciation cycles. Three-tier pricing structure across GDP-certified premium, standard cold chain, and ambient distribution levels reflects compliance depth and temperature validation rigor. Cost compression in ambient small-molecule logistics is intensifying because generic manufacturers in Kyushu prioritize unit economics over service bundling. Biotech companies demonstrate lowest price sensitivity due to -70°C mRNA stability requirements that command specialized infrastructure premiums.
Supply Chain Analysis
Direct-to-pharmacy channels from inventory management hubs are bypassing traditional wholesale layers as hospital procurement groups consolidate vendor panels. Manufacturing inputs for pharmaceutical 3PL infrastructure draw from Germany for precision refrigeration systems, China for IoT sensor components, and domestic Japanese suppliers for seismic-resistant warehouse materials. Single-source vulnerability concentrates in qualified pharmacist supervisory roles required for GDP-certified operations. Distribution runs through hub-and-spoke configurations anchored by Greater Tokyo Area airport access and Osaka-Nagoya manufacturing corridor cross-dock facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's pharmaceutical 3PL market functions as a geographic-arbitrage play where Fukuoka's biotech incubation zone offers lower facility development costs against Kanto's saturated compliance infrastructure. METI's carbon neutrality mandates create divergent capital intensity timelines across regional markets.
For Market Incumbents: Deploy shared GDP certification cost pools to neutralize PMDA inspection backlog delays that compress revenue recognition windows for new depot openings. Consolidate seismic-resistant warehouse capacity in the Osaka-Nagoya corridor where Japan Building Standard Law mandates elevate facility development costs beyond mid-tier operator capacity. Biodegradable thermal packaging convergence threatens conventional expanded polystyrene shipper margins.
For New Entrants and Emerging Players: Digital platform-enabled direct-to-pharmacy distribution routes offer lowest barrier entry against entrenched wholesale relationships. Kyushu pharmaceutical cluster expansion presents the most penetrable geography given Fukuoka's immature temperature-validated infrastructure and generic manufacturer demand for cost-sensitive ambient networks. Phase-change material thermal shippers with embedded IoT sensors provide differentiation anchor for clinical trial material logistics targeting contract research organizations.
For Investors and Strategic Acquirers: Logistics conglomerates with captive pharmaceutical divisions are the most active acquirer in this space as serialization mandates and METI carbon regulations elevate compliance system costs. Long-term viability centers on electric cold chain fleet ownership and GDP-certified depot density across Japan's regional manufacturing corridors. Blockchain-enabled temperature verification adoption rates signal inflection timing for liability restructuring between pharmaceutical sponsors and logistics contractors.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Cold Chain Fleet Conversion | METI emission standards force battery-electric refrigerated vehicle procurement ahead of depreciation cycles. |
| Seismic-Resistant Warehouse Expansion | Japan Building Standard Law mandates base-isolated construction in high-risk Kansai and Kanto zones. |
| Blockchain Temperature Verification Deployment | PMDA serialization mandates restructure liability allocation between biologics sponsors and 3PL operators. |
| Biodegradable Thermal Packaging Transition | Cellulose-based shippers with IoT sensors enable compliance-plus-sustainability service differentiation. |
| Direct-to-Pharmacy Distribution Channel | Hospital procurement centralization bypasses traditional wholesalers for serialized track-and-trace capable operators. |
Research Methodology
Multiple input streams — structured interviews with pharmaceutical logistics directors, regulatory affairs specialists at PMDA, hospital procurement managers in Kanto academic medical centers, and cold chain operations technicians — were reconciled against secondary validation from METI energy efficiency disclosures, PMDA GDP inspection records, Japan Building Standard Law compliance filings, and pharmaceutical manufacturer serialization system procurement data. Bottom-up service provider capacity assessments and top-down therapeutic demand projections were triangulated for convergence.
Historical revenue trajectories were cross-referenced against panel input from 3PL operators and biologics manufacturers to construct analytical frameworks across service type, end user category, delivery mode, and regulatory compliance tier dimensions. CAGRs were derived from segmented growth rate differentials applied across the projection horizon. Forecast inputs incorporated electric fleet replacement timelines, PMDA inspection authorization backlogs, and mRNA therapy pipeline expansion assumptions.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled temperature verification would alter the outlook for liability allocation and insurance premium structures. Forecasts reflect assumptions regarding METI carbon neutrality enforcement timing and PMDA serialization mandate compliance deadlines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Candidiasis Therapeutics Market