
 Asia-Pacific NMC Battery Pack Market | 2026-2036
Asia-Pacific NMC Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific NMC Battery Pack Market Insights
The divergence between premium high-nickel NMC packs and commodity LFP alternatives is hardening across the Asia-Pacific supply base. CATL leverages its vertical grip on cathode precursor refining to sustain cost parity across tier-one automotive OEM programs. BYD anchors its position through in-house semiconductor and cell integration, while LG Energy Solution competes on European-export certification density from its Nanjing and Nantong lines.
An NMC battery pack combines nickel-manganese-cobalt oxide cathodes with graphite or silicon-blend anodes in modular architectures rated typically from 50 Wh/kg to 300 Wh/kg depending on cell format and thermal management protocol. The chemistry serves applications demanding high energy density, fast charge acceptance, and sustained cycle life under variable thermal loads. Electric Vehicles dominates product-type revenue pools as automotive OEMs specify 811 and 622 cathode ratios for 700-kilometer-range platforms, while Grid Storage applications attract second-life NMC retired from mobility duty. Solid State technology entries from Samsung SDI and SK Innovation are repositioning structural margins toward electrolyte-innovation specialists rather than conventional pack assemblers.
China's MIIT enforces GB/T cell-to-pack dimensional and thermal-runaway standards that filter market access for imported designs, while South Korea's KATS aligns KPS battery safety codes with UN 38.3 transport protocols to secure export clearance. Japan's METI coordinates PSE and S-Mark certifications that constrain nickel-cobalt supply chain provenance declarations. Stakeholders must track how Indonesia's nickel export licensing and Australia's critical minerals partnership terms recast raw material security assumptions before committing to multi-year cathode offtake structures.
Market Dynamics
The Asia-Pacific NMC battery pack market is experiencing intense pressure from China's MIIT cell-to-pack integration mandates, which are compressing design cycles and forcing cathode suppliers to relocate refining capacity within two-hour logistics radii of Jiangsu and Guangdong assembly corridors.
Growth Catalysts
- High-nickel cathode formulations:Automotive OEMs across China, South Korea, and Japan are specifying NMC 811 and 622 ratios for 700-kilometer-range electric vehicle platforms, pulling demand toward higher energy density configurations.
- Japan's METI subsidy frameworks:Next-generation chemistry incentives are redirecting capacity investments away from legacy formulations toward solid-state electrolyte precursors and advanced thermal management architectures.
- Second-life grid storage:Retired mobility-duty NMC cells are finding secondary application in stationary energy storage, creating circular revenue streams for pack assemblers with refurbishment capabilities.
Market Restraints
- Nickel supply concentration:Indonesia's export licensing regime and processing capacity bottlenecks create raw material security vulnerabilities for cathode precursor offtake commitments spanning multi-year horizons.
- Cobalt provenance constraints:Japan's METI PSE and S-Mark certifications require exhaustive supply chain documentation that extends qualification timelines and raises compliance costs for non-integrated suppliers.
- LFP substitution threat:Lithium iron phosphate alternatives are capturing commoditized passenger vehicle segments where range requirements moderate and cost sensitivity dominates OEM sourcing decisions.
Strategic Opportunities
- Solid-state electrolyte convergence:Samsung SDI and SK Innovation entries are repositioning structural margins toward electrolyte-innovation specialists rather than conventional pack assemblers, creating white space for materials science entrants.
- India's PLI scheme for advanced chemistry cells:Production-linked incentive frameworks are attracting cathode and cell manufacturing investments into Gujarat and Tamil Nadu corridors previously dependent on imported packs.
- European-export certification density:South Korea's KATS alignment with UN 38.3 transport protocols enables Nanjing and Nantong production lines to serve dual domestic and export markets without redundant testing regimes.
Industry Challenges
- Thermal runaway engineering talent scarcity:Cell-to-pack integration requires specialized expertise in multi-physics simulation and propagation containment that outpaces regional university pipeline output.
- GB/T certification timeline compression:China's MIIT dimensional and safety standards are evolving faster than validation cycles, forcing design teams to speculative-engineer against draft requirements.
- Legacy semiconductor integration:Pack assemblers must reconcile silicon-carbide power electronics from disparate automotive OEM programs with proprietary battery management system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific NMC Battery Pack Market |
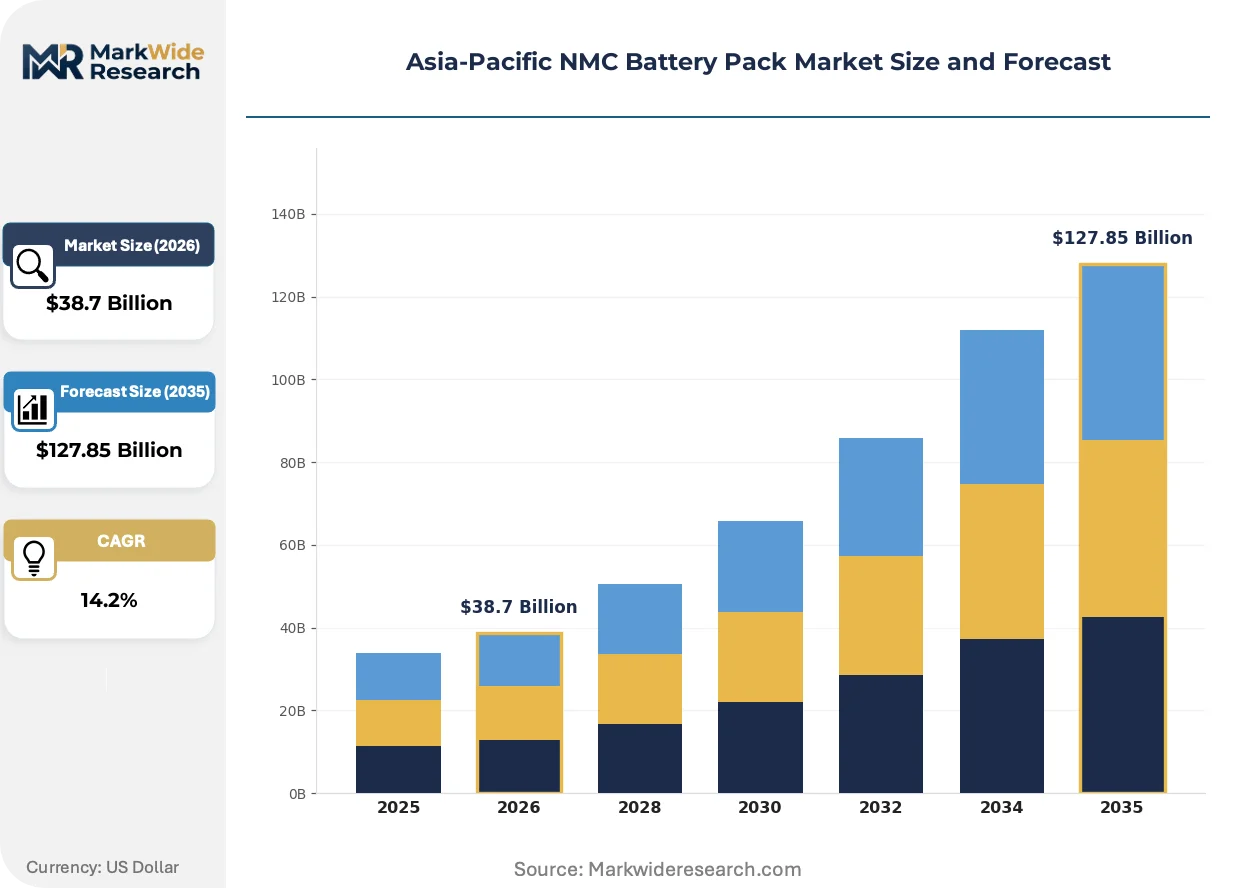
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment End User: Automotive OEMs, Electronics Manufacturers, Energy Providers, Manufacturing Companies Technology: Lithium-ion, Solid State, Flow Batteries, Lead-acid Application: Grid Storage, Portable Devices, Automotive, Marine |
| Companies Covered | Contemporary Amperex Technology Co Ltd (CATL), BYD Company Ltd, LG Energy Solution Ltd, Samsung SDI Co Ltd, SK Innovation Co Ltd, Panasonic Holdings Corporation, Gotion High-Tech Co Ltd, EVE Energy Co Ltd, GS Yuasa International Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific NMC Battery Pack Market Trends and Innovations
Electrolyte chemistry and thermal architecture are converging to redefine competitive boundaries, with solid-state entries and cell-to-pack structural integration displacing conventional modular approaches across the Asia-Pacific supply base.
Cell-to-pack structural battery architecture is modularizing traditional module-and-pack hierarchies into single integrated assemblies. Automotive OEMs in China and South Korea are adopting these designs for 2025-model-year platforms to recover volume and mass previously lost to redundant housings and interconnects. The technology is modularizing supplier relationships as cathode refiners, thermal interface material specialists, and pack assemblers merge competencies into unified engineering teams.
China's MIIT enforcement of GB/T cell-to-pack dimensional and thermal-runaway standards is filtering market access for imported designs that cannot demonstrate propagation containment within 5-minute alert windows. Domestic suppliers with in-house fire-suppression IP and local testing relationships are securing preferential qualification slots. The policy most affects European and Japanese pack entrants targeting China's premium electric vehicle segment, forcing joint venture structures or technology licensing to circumvent technical barriers.
Fleet operators and energy storage developers are consolidating procurement around vertically integrated suppliers capable of spanning precursor refining through pack assembly. This concentration is compressing qualification cycles for second-tier cathode material vendors and elevating long-term offtake agreements over spot market transactions. The behavioral shift is most visible in China's Jiangsu corridor, where provincial industrial policy incentivizes cathode-to-pack clustering within bonded logistics zones.
Asia-Pacific NMC Battery Pack Market Segmentation
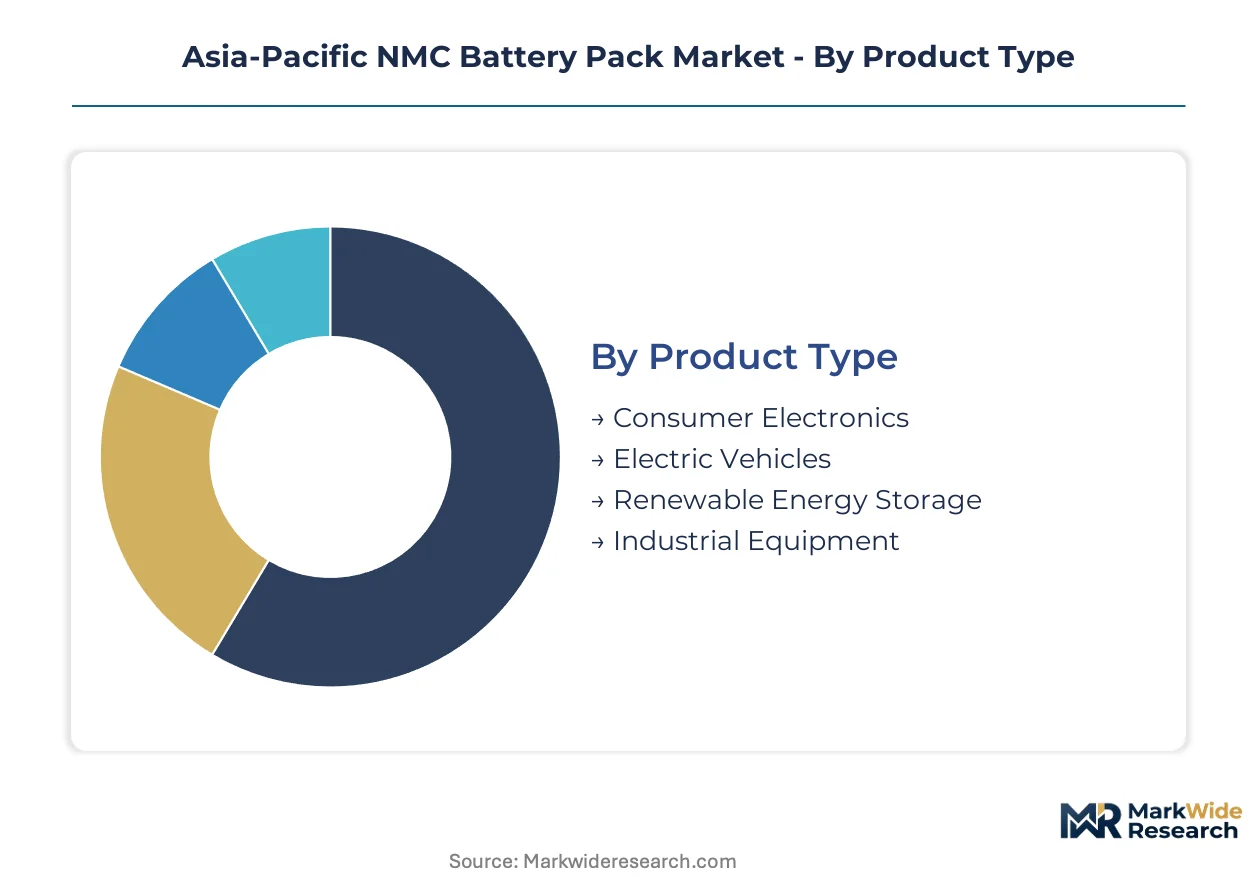
NMC pack procurement diverges sharply across application voltage classes and duty-cycle intensity, with automotive platforms demanding fundamentally different thermal architectures than stationary storage installations. Segmentation clarity enables suppliers to match cathode formulation, cell format, and battery management system complexity to specific performance envelopes without over-engineering cost structures.
Product Type:
Capital deployment for NMC pack manufacturing scales directly with energy density requirements and thermal management sophistication, creating tiered investment thresholds across application categories.
- Electric Vehicles:High-nickel cathode formulations in prismatic or pouch configurations dominate this segment, with pack architectures integrating cell-to-pack structural designs and active liquid cooling. Jiangsu and Guangdong manufacturing corridors concentrate capacity investments here as China's MIIT enforces GB/T dimensional standards that favor domestic assembly scale.
- Consumer Electronics:Cylindrical 21700 and 18650 formats with moderate nickel ratios serve smartphones, laptops, and power tools where volumetric energy density competes against lithium iron phosphate alternatives. South Korean and Japanese electronics OEMs anchor procurement through established qualification relationships with tier-one cell suppliers.
- Renewable Energy Storage:Second-life NMC retired from mobility duty finds secondary application in stationary installations, reducing upfront cathode material costs while extending asset utilization.
- Industrial Equipment:Forklifts, warehouse robotics, and heavy machinery deploy ruggedized pack designs prioritizing cycle life over energy density in controlled temperature environments.
Electric Vehicles absorbs the bulk of installed capacity; Renewable Energy Storage is expanding most quickly.
End User:
Procurement authority concentrates with entities possessing in-house battery management system development capabilities and multi-year platform visibility.
- Automotive OEMs:Volume commitments spanning 700-kilometer-range platforms drive cathode precursor offtake structures, with BYD and tier-one Chinese manufacturers leveraging backward integration into semiconductor and cell production to compress supplier margins.
- Energy Providers:Grid-scale storage developers favor second-life NMC for frequency regulation and peak shaving, creating circular revenue streams through refurbishment capabilities rather than virgin cathode procurement.
- Electronics Manufacturers:Consumer device assemblers specify standardized cylindrical formats with established UN 38.3 transport certification density to accelerate global logistics clearance.
- Manufacturing Companies:Industrial automation and material handling operations source ruggedized packs through equipment OEM channels rather than direct cell procurement.
Automotive OEMs command the dominant share of cathode refining capacity allocation; Energy Providers are gaining procurement velocity fastest.
Technology:
Electrolyte chemistry selection determines margin accrual patterns, with solid-state entries repositioning value capture toward materials science specialists.
- Lithium-ion:Conventional liquid electrolyte NMC configurations with graphite or silicon-blend anodes retain near-term volume dominance across automotive and consumer applications, supported by established precursor refining infrastructure in China and South Korea.
- Solid State:Samsung SDI and SK Innovation development programs target sulfide and oxide electrolyte architectures that eliminate thermal runaway propagation risks while enabling higher nickel cathode loading, though manufacturing scale remains constrained by dry-room processing requirements.
- Flow Batteries:Vanadium and zinc-bromine chemistries compete for multi-hour grid storage durations where NMC cycling economics deteriorate, capturing utility-scale installations outside mobility-adjacent procurement relationships.
- Lead-acid:Legacy chemistry persists in starter-lighting-ignition applications and cost-sensitive industrial equipment where energy density requirements remain minimal.
Lithium-ion retains overwhelming capacity share; Solid State is climbing the fastest toward commercial qualification thresholds.
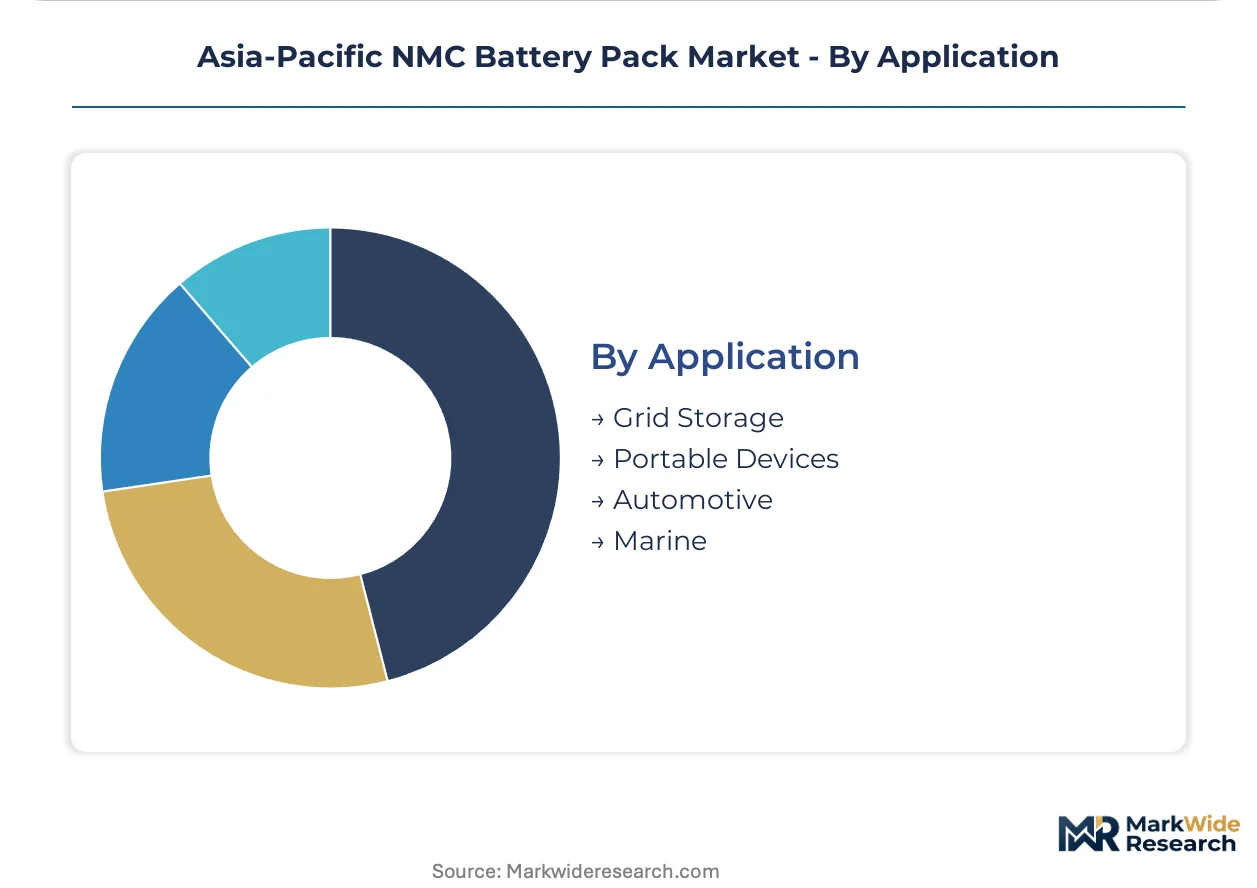
Application:
Deployment environment dictates thermal management protocol selection and safety certification pathway complexity.
- Automotive:Passenger and commercial vehicle platforms specify 811 and 622 cathode ratios with cell-to-pack integration, requiring GB/T or UN 38.3 certification density for market access across China and export corridors.
- Grid Storage:Utility-scale and behind-the-meter installations utilize refurbished NMC modules from retired electric vehicle packs, with Japan's METI subsidy frameworks supporting next-generation chemistry transitions in stationary applications.
- Portable Devices:Power tools, drones, and medical equipment demand cylindrical formats with rapid charge acceptance and moderate cycle life under variable thermal loads.
- Marine:Electric outboards and harbor vessels require IP67+ ingress protection and salt corrosion resistance that elevates pack housing costs above terrestrial equivalents.
Automotive anchors cathode material demand; Grid Storage is gaining share fastest through second-life circularity models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Guangdong manufacturing corridors anchor Asia-Pacific NMC battery pack capacity, with cathode refiners and pack assemblers clustering within two-hour logistics radii to meet China's MIIT cell-to-pack integration mandates.
China
Automotive OEMs specify NMC 811 and 622 cathode ratios for 700-kilometer-range electric vehicle platforms. China's MIIT enforces GB/T dimensional and thermal-runaway standards that filter market access for imported designs. Jiangsu and Guangdong corridors concentrate precursor refining and pack assembly within bonded logistics zones.
South Korea
Export-oriented cell manufacturers align production with European automotive qualification requirements. KATS battery safety codes harmonize with UN 38.3 transport protocols to secure dual-market clearance. Nanjing and Nantong production lines serve domestic and export markets through unified testing regimes.
Japan
METI subsidy frameworks redirect capacity investments toward solid-state electrolyte precursors and advanced thermal management architectures. PSE and S-Mark certifications constrain nickel-cobalt supply chain provenance declarations. Kanto and Kansai industrial belts host next-generation chemistry development programs.
India
Production-linked incentive schemes for advanced chemistry cells attract cathode and cell manufacturing investments into Gujarat and Tamil Nadu corridors. State-level industrial policies target mobility and stationary storage applications. Domestic procurement previously dependent on imported packs shifts toward local assembly scale.
Indonesia
Nickel export licensing regimes and processing capacity bottlenecks create raw material security vulnerabilities for regional cathode precursor offtake commitments. Sulawesi and Halmahera mining belts feed hydrometallurgical refining investments. Downstream integration policies aim to capture value beyond raw ore shipment.
Asia-Pacific NMC Battery Pack Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cathode formulation sophistication and certification density. The vendor base organizes into three tiers: integrated refiners with precursor-to-pack control, cell-specialists dependent on external cathode supply, and pack-assemblers sourcing cells from multiple origins. Dominant competitive moves include backward integration into cathode refining and strategic partnerships for solid-state electrolyte access.
Within the integrated refiner tier, Contemporary Amperex Technology Co Ltd and BYD Company Ltd exemplify archetypes combining captive cathode production with automotive OEM relationships. LG Energy Solution Ltd anchors the export-specialist position. These three structures represent distinct strategic postures: full vertical control, semiconductor-cell integration, and dual-market certification density.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co Ltd (CATL) |
| BYD Company Ltd |
| LG Energy Solution Ltd |
| Samsung SDI Co Ltd |
| SK Innovation Co Ltd |
| Panasonic Holdings Corporation |
| Gotion High-Tech Co Ltd |
| EVE Energy Co Ltd |
| GS Yuasa International Ltd |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement of NMC 811 and 622 cathode formulations for 700-kilometer-range platforms is compressing supplier margins and forcing pack assemblers to absorb thermal management engineering costs that previously flowed to tier-two vendors. This demand-side specification tightening concentrates pricing power with cathode refiners possessing in-house precursor capacity, while marginalizing pure-play pack integrators.
Pricing Analysis
Energy-density-per-kilogram throughput anchors value-based pricing for high-nickel NMC packs serving premium electric vehicle platforms. Three-tier pricing structure across premium, standard, and economy levels separates GB/T-certified cell-to-pack designs from modular legacy architectures and second-life refurbished units. Cost compression in the standard tier is intensifying because LFP alternatives capture commoditized passenger vehicle segments. Fleet operators and grid storage developers exhibit highest price sensitivity, while luxury automotive OEMs prioritize certification density over unit cost.
Supply Chain Analysis
Freight costs from Indonesian nickel processing hubs to Jiangsu and Guangdong cathode refiners have become a decisive factor in total landed precursor economics. Raw material supply concentrates in Indonesia, Australia, and Chile for nickel, lithium, and cobalt respectively. Cathode precursor production draws from hydrometallurgical refining capacity concentrated in China and South Korea. Single-source vulnerability around Indonesia's export licensing regime threatens multi-year offtake commitments. Distribution runs through bonded logistics zones in Jiangsu and Guangdong corridors serving domestic automotive OEMs and European export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack integration mandates and solid-state electrolyte transitions are forcing a consolidation play that will eliminate pack assemblers lacking cathode refining partnerships or fire-suppression IP.
For Market Incumbents: Acquire thermal runaway containment engineering teams and GB/T certification relationships to defend against solid-state entrants repositioning margins toward materials science specialists. Secure captive nickel offtake from Indonesian hydrometallurgical investments before export licensing tightens further. For New Entrants and Emerging Players: Capture second-life grid storage refurbishment contracts in India's Gujarat and Tamil Nadu corridors, where PLI schemes reduce import dependency and create local assembly scale. Target European-export certification density as the most penetrable wedge, leveraging South Korea's KATS-UN 38.3 alignment to bypass redundant testing regimes. For Investors and Strategic Acquirers: The window for entry favors electrolyte-innovation specialists with dry-room processing capabilities and sulfide or oxide electrolyte IP. Long-term viability hinges on solid-state manufacturing scale rather than conventional pack assembly. Watch Samsung SDI and SK Innovation commercial qualification timelines as the inflection signal for margin repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Refining | Captures nickel sulfate and cobalt hydroxide margins previously flowing to Chinese refiners. |
| GB/T Cell-to-Pack Certification Investment | Secures preferential qualification slots under China's MIIT dimensional and thermal-runaway standards. |
| Solid-State Electrolyte Partnership | Positions for margin capture as Samsung SDI and SK Innovation displace liquid electrolyte architectures. |
| Second-Life Refurbishment Capability Buildout | Creates circular revenue streams from retired mobility-duty NMC cells in grid storage applications. |
| Indonesian Nickel Processing Joint Venture | Hedges raw material security vulnerabilities from export licensing and processing bottlenecks. |
Research Methodology
Document review covered customs trade data, MIIT GB/T standard filings, METI subsidy framework disclosures, and UN 38.3 transport protocol updates, complemented by interviews with cathode refinery operations directors, automotive OEM platform engineers, and grid storage procurement leads at Indian and South Korean energy utilities. Secondary validation drew from IEA battery supply chain tracking, Indonesian mining export license registries, and bonded logistics zone investment filings. Bottom-up cell and pack production estimates were triangulated against top-down cathode material consumption figures.
Historical capacity deployment patterns were cross-referenced against panel input from precursor refining executives and battery management system architects to construct the projection framework. Segmentation dimensions modeled include cathode formulation ratio, cell format geometry, thermal management protocol, application voltage class, and regional regulatory cluster. CAGRs were derived from supply-demand balance analysis across the modeling period, incorporating Indonesia's nickel export policy trajectory and solid-state electrolyte manufacturing readiness curves.
The model holds under continued enforcement of China's MIIT cell-to-pack standards and stable Indonesian nickel export licensing; deviation in solid-state commercialization timelines or raw material trade restrictions would shift capacity investment patterns. Forecasts reflect documented assumptions about cathode chemistry transition rates and thermal engineering talent pipeline output. Stakeholders should weight assumptions against their own operating context and qualification cycle exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Primary Cells Market
Batteries
Printable Battery Market
Batteries
South America Rechargeable Battery Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Zinc Carbon Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Alkaline Battery Market
Batteries
Deep Cycle Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Rear Rack Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Power-Sports Batteries Market