
 HEV Li-Ion Battery Market | 2026-2036
HEV Li-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
HEV Li-Ion Battery Market Insights
South Korean cathode material producers is broadening precursor supply networks across Indonesian nickel processing zones. Panasonic Corporation leverages vertical integration into cylindrical cell formats for Japanese OEM hybrid platforms. LG Chem sustains R&D intensity across NMC cathode variants optimized for partial electrification duty cycles. Samsung SDI anchors European premium passenger vehicle programs with prismatic module architectures.
HEV Li-Ion Batteries are rechargeable electrochemical cells employing lithium-ion chemistry with nominal voltages typically ranging from 3.2V to 3.7V per cell, engineered for high-cycle durability under shallow depth-of-discharge conditions characteristic of hybrid electric vehicle operation. Their primary industrial purpose is to buffer kinetic energy recovery, deliver torque-fill during internal combustion engine transient response, and enable engine-off coasting without full plug-in dependency. Prismatic formats dominate OEM assembly line integration for passenger vehicle applications where space packaging constraints favor rigid rectangular geometries. NMC cathode chemistry captures margin concentration in premium hybrid architectures where energy density trade-offs justify cobalt-bearing material costs against LFP alternatives.
Japan's METI enforces battery recycling accountability through revised resource circulation mandates affecting cell producers and vehicle assemblers jointly. South Korea's KATS administers KC certification standards for lithium-ion cell safety testing protocols that gate domestic market access. China's SAMR coordinates GB standards alignment with MIIT new energy vehicle regulatory frameworks. Stakeholders must monitor how divergent national recycling obligations reshape cross-border cell procurement strategies and localized joint venture requirements.
Market Dynamics
Japanese OEM hybrid platform commitments are compressing cylindrical cell procurement timelines while Korean cathode suppliers accelerate Indonesian nickel backward integration to secure precursor supply chains.
Growth Catalysts
- MIIT dual carbon mandates:China's NEV credit system penalizes ICE-only powertrains and forces automakers to electrify fleet mixes, expanding HEV battery procurement volumes.
- East Asian cell manufacturing clusters:Concentrated production across Japanese, South Korean, and coastal Chinese provinces generates scale economies and technical learning curves that reduce unit costs.
- Shallow depth-of-discharge engineering:NMC cathode variants optimized for high-cycle durability under partial charge conditions extend battery service life and reduce replacement frequency.
Market Restraints
- Cobalt price volatility:NMC chemistry dependency on Congolese and Indonesian cobalt concentrate exposes cell producers to raw material cost swings that compress margin stability.
- Prismatic format supply concentration:Korean and Japanese cell giants dominate rigid rectangular cell output, limiting second-tier pack assemblers' supplier diversification options.
- GB standards misalignment:Divergent Chinese SAMR certification protocols versus Japanese JIS testing regimes create cross-border product validation friction and duplicate engineering costs.
Strategic Opportunities
- Indonesian nickel processing zones:Korean cathode material producers are establishing precursor refining capacity in Southeast Asian mining corridors to bypass Chinese intermediate dominance.
- European premium passenger programs:Prismatic module architectures from Korean suppliers are penetrating German and Swedish OEM hybrid lineups previously served by cylindrical formats.
- METI resource circulation mandates:Japan's revised battery recycling accountability rules create closed-loop material recovery infrastructure that lowers virgin mineral dependency.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell producers face recruitment bottlenecks for solid-state interface specialists and thermal management simulation experts.
- KC certification timeline compression:South Korea's KATS safety testing protocols demand extended validation cycles that delay new chemistry commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HEV Li-Ion Battery Market |
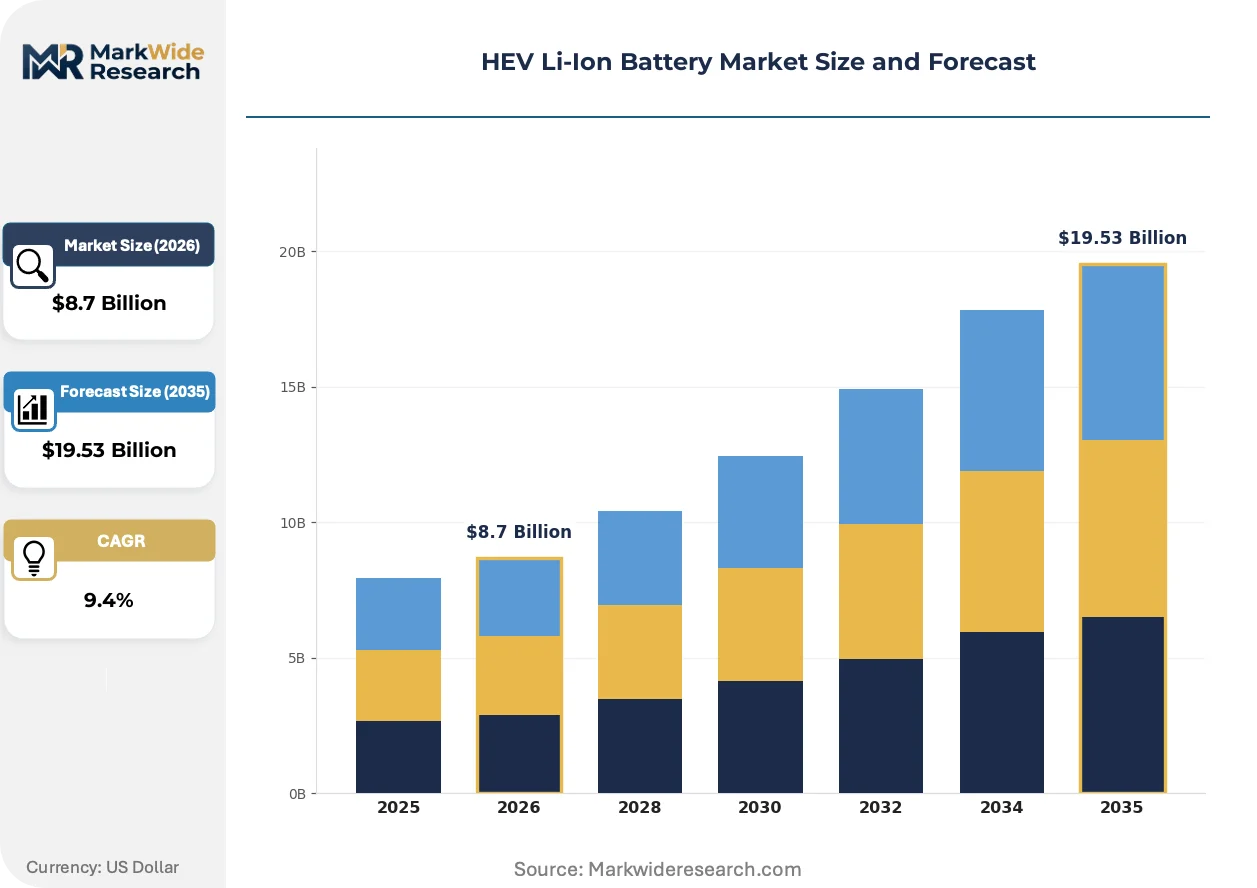
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Modular Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes Technology: LFP, NMC, LCO, NCA End User: OEMs, Aftermarket, Fleet Operators, Repair Services |
| Companies Covered | Panasonic Corporation, LG Chem, Contemporary Amperex Technology Co., Limited (CATL), BYD Company Limited, Samsung SDI, GS Yuasa Corporation, Toshiba Corporation, SK Innovation, A123 Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HEV Li-Ion Battery Market Trends and Innovations
Hybrid battery architectures are converging toward modular prismatic formats while regulatory frameworks harden around mineral provenance and end-of-life accountability.
Solid-state electrolyte research is integrating ceramic-polymer composite separators into pilot production lines. Japanese OEMs are validating these configurations for next-generation hybrid platforms with 48V electrical architectures. This integration is compressing liquid electrolyte cell development timelines and forcing incumbent producers to accelerate solid-state roadmaps.
EU battery passport requirements under the CSRD are mandating digital traceability for cobalt, lithium, and nickel inputs. Cell producers must deploy blockchain-verified chain-of-custody systems to maintain European market access. Premium hybrid vehicle programs face the steepest compliance costs as OEMs demand batch-level material provenance documentation.
Fleet procurement departments are consolidating cell supply agreements under multi-year framework contracts with price-volume corridors. Tier-1 automotive suppliers are displacing spot-market purchasing with captive sourcing arrangements tied to specific vehicle platform lifecycles. This pattern concentrates most visibly in German and Japanese OEM hybrid program planning cycles.
HEV Li-Ion Battery Market Segmentation
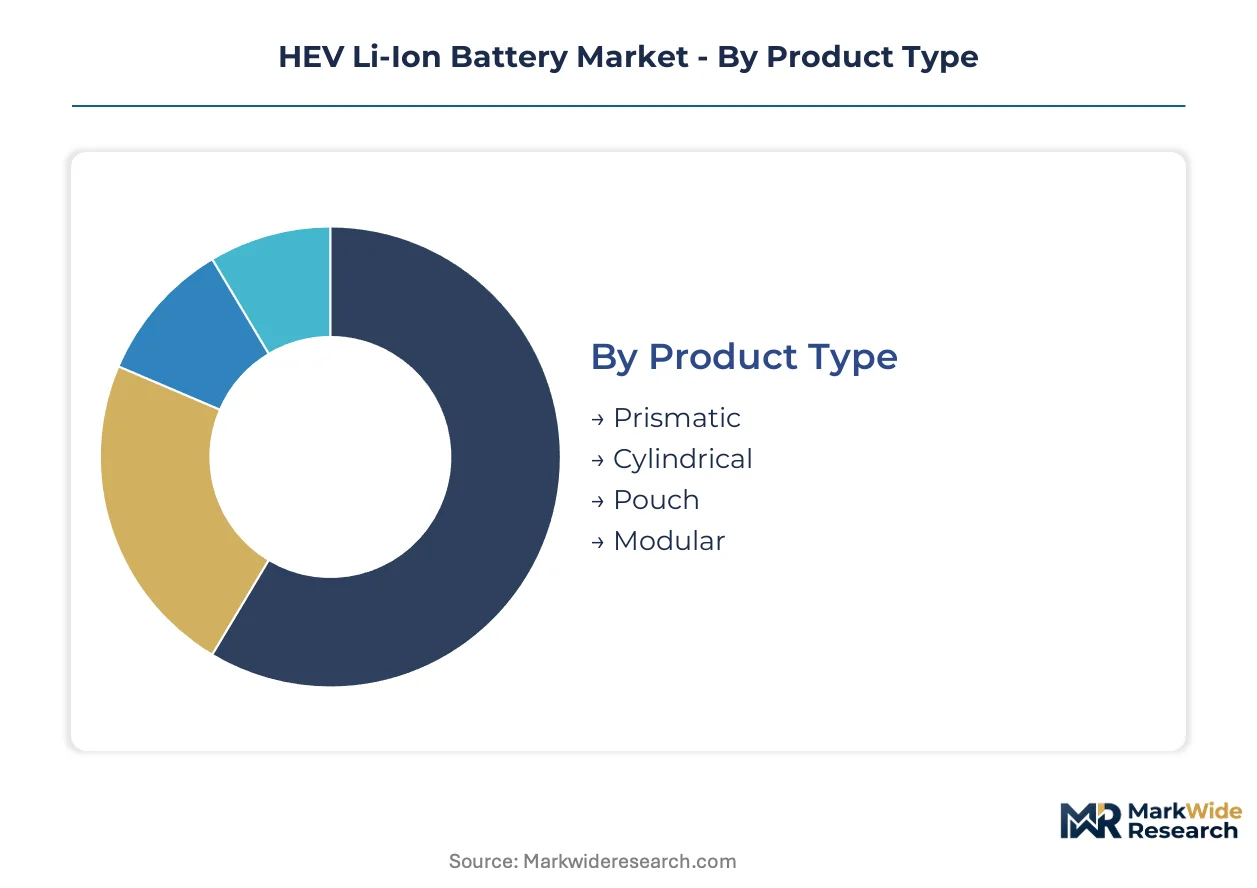
Cell format selection determines pack assembly complexity and thermal management architecture for hybrid platforms. Chemistry choice balances cycle durability against mineral cost exposure. End-user procurement patterns split between captive OEM supply agreements and fragmented aftermarket replacement demand.
Product Type:
Packaging geometry dictates manufacturing equipment requirements and vehicle integration pathways.
- Prismatic:Rigid rectangular aluminum housings enable direct module stacking with minimal void space. Japanese and Korean OEM passenger vehicle programs specify prismatic formats for underfloor battery packaging where structural rigidity matters.
- Cylindrical:Rolled electrode jellyrolls in metal cans deliver consistent thermal dissipation and automated winding throughput. Toyota and Honda hybrid platforms source cylindrical cells from Panasonic for engine-bay mounting where vibration tolerance is critical.
- Pouch:Laminated polymer-aluminum foil enclosures minimize dead weight but require compression frames for cell-to-cell structural integrity.
- Modular:Pre-integrated cell-to-pack assemblies reduce OEM assembly line complexity and enable platform-standardized procurement.
Prismatic leads on scale; modular leads on momentum.
Application:
Vehicle class determines duty cycle severity and replacement frequency economics.
- Passenger Vehicles:Shallow depth-of-discharge profiles under 20% maximize NMC cathode cycle life across 150,000-mile service intervals. East Asian OEM hybrid fleets concentrate procurement volumes here.
- Commercial Vehicles:High-cycling urban delivery routes stress thermal management systems and accelerate capacity fade.
- Two-Wheelers:Cost-optimized LFP configurations dominate Asian scooter electrification where pack volume constraints are less severe.
- E-Bikes:Small-format pouch cells from Chinese suppliers serve European and North American micromobility replacement markets.
Passenger vehicles lead on scale; two-wheelers lead on momentum.
Technology:
Cathode chemistry selection trades energy density against mineral security and thermal stability.
- LFP:Iron phosphate cathodes eliminate cobalt dependency and deliver superior thermal runaway resistance. Chinese cell producers deploy LFP aggressively in price-sensitive hybrid applications where energy density penalties are acceptable.
- NMC:Nickel-manganese-cobalt layered oxides optimize volumetric energy density for premium hybrid architectures with limited packaging volume.
- LCO:Lithium cobalt oxide retains niche positioning in legacy hybrid platforms where cathode material switching costs exceed redesign investment.
- NCA:Nickel-cobalt-aluminum chemistries from Korean suppliers target high-discharge-rate applications in performance-oriented hybrid powertrains.
NMC leads on scale; LFP leads on momentum.
End User:
Procurement authority concentration shapes contract structure and pricing leverage.
- OEMs:Vehicle assemblers negotiate multi-year framework agreements with volume corridors and price escalation caps tied to nickel and cobalt index movements.
- Aftermarket:Independent distributors source replacement packs through spot-market channels with limited warranty backing.
- Fleet Operators:Consolidated commercial vehicle buyers demand guaranteed residual value and second-life repurposing terms.
- Repair Services:Authorized dealer networks handle warranty cell replacements under OEM-directed service protocols.
OEMs lead on scale; fleet operators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell producers are migrating manufacturing capacity toward jurisdictions with streamlined certification protocols and mineral processing incentives, exploiting regulatory-arbitrage gaps between recycling-mandate regimes and greenfield investment subsidy programs.
China
CATL and BYD anchor cylindrical and prismatic cell output for domestic OEM hybrid platforms under MIIT dual carbon mandates. SAMR coordinates GB standards alignment with NEV credit systems that penalize ICE-only powertrains. Yangtze River Delta clusters around Shanghai and Suzhou concentrate cathode precursor refining and module assembly operations serving Toyota and Honda joint ventures.
Japan
Panasonic and GS Yuasa supply cylindrical formats for Toyota and Honda hybrid fleets with shallow depth-of-discharge engineering optimized for 150,000-mile service intervals. METI enforces battery recycling accountability through revised resource circulation mandates affecting cell producers and vehicle assemblers jointly. Kanto region manufacturing corridors spanning Tokyo and Kanagawa prefectures host captive cathode material production and closed-loop recovery infrastructure.
South Korea
LG Chem and Samsung SDI sustain R&D intensity across NMC cathode variants for partial electrification duty cycles in premium hybrid architectures. KATS administers KC certification standards for lithium-ion cell safety testing protocols that gate domestic market access. Busan-Ulsan coastal industrial zones concentrate electrode coating and electrolyte formulation capacity with backward integration into Indonesian nickel precursor networks.
Germany
BMW and Mercedes-Benz hybrid programs source prismatic module architectures from Korean suppliers previously dependent on cylindrical formats. EU battery passport requirements under CSRD mandate digital traceability for cobalt, lithium, and nickel inputs through blockchain-verified chain-of-custody systems. Bavaria and Baden-Württemberg automotive clusters coordinate pack assembly integration with engine manufacturing facilities at Ingolstadt and Stuttgart.
United States
GM and Ford hybrid truck platforms drive cylindrical cell procurement from Korean and Japanese producers under IRA domestic content incentives. EPA tailpipe standards and California CARB mandates compress ICE-only powertrain viability across light-duty fleets. Michigan and Tennessee battery assembly plants coordinate with Indiana and Kentucky powertrain manufacturing corridors for regional supply chain density.
HEV Li-Ion Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state electrolyte development and Indonesian nickel backward integration. The market structures around three player tiers: Japanese incumbents with cylindrical format dominance, Korean specialists in prismatic NMC architectures, and Chinese scale producers leveraging LFP cost positions. Competitive moves concentrate on precursor supply chain captive arrangements and multi-year OEM framework agreements with price-volume corridors.
Within the established producer tier, Panasonic Corporation and LG Chem exemplify divergent format strategies—cylindrical versus prismatic—while CATL represents the scale-driven LFP alternative. Samsung SDI occupies a position bridging Korean cathode technology with European premium vehicle program penetration. These anchors illustrate how geographic origin and format specialization stratify competitive positioning without requiring proprietary technology claims.
| Leading Market Players |
|---|
| Panasonic Corporation |
| LG Chem |
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Limited |
| Samsung SDI |
| GS Yuasa Corporation |
| Toshiba Corporation |
| SK Innovation |
| A123 Systems |
| Others |
Pricing and Supply Chain Analysis
Electrochemical engineering talent scarcity in the Busan-Ulsan coastal corridor widens labor-cost spreads between premium NMC cathode producers and standard LFP assemblers, compressing mid-tier pricing corridors as Korean cell giants capture margin concentration through captive precursor networks.
Pricing Analysis
Distributor margins on cylindrical cell replacement packs run 12-18 points above direct-to-OEM contract rates for prismatic module assemblies. Three-tier pricing structure across premium NMC, standard LFP, and economy-grade LCO configurations separates OEM framework agreements from aftermarket spot purchasing. Cost compression in the cylindrical segment is intensifying because Panasonic's vertical integration into Japanese OEM supply chains eliminates intermediate markup layers. Fleet operators exhibit the highest price sensitivity due to guaranteed residual value clauses, while European premium passenger programs show lowest sensitivity to per-kWh escalation.
Supply Chain Analysis
KC certification from South Korea's KATS and JIS testing protocols from Japan's METI gate market access for cell producers, forcing duplicate validation cycles that extend lead times for cross-border procurement. Geographic supply concentration centers on China, South Korea, and Japan, with Yangtze River Delta and Kanto region clusters hosting cathode precursor refining and module assembly. Raw material dependencies draw from Indonesian nickel concentrate, Congolese cobalt, and Australian spodumene. Single-source vulnerability in prismatic aluminum housing supply creates bottlenecks for second-tier pack assemblers. Distribution runs through captive OEM supply agreements with multi-year framework contracts displacing spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by MIIT dual carbon mandates that lock in decade-long procurement visibility for East Asian cell producers.
For Market Incumbents: Deepen backward integration into Indonesian nickel processing zones to bypass Chinese intermediate dominance and defend margin stability against cobalt price volatility. Accelerate solid-state electrolyte R&D to compress liquid-cell development timelines as Japanese OEMs validate ceramic-polymer configurations. METI resource circulation mandates create closed-loop recovery infrastructure that lowers virgin mineral dependency and raises barriers for non-integrated competitors. For New Entrants and Emerging Players: Aftermarket repair services represent the most penetrable buyer archetype, with independent distributors currently sourcing through fragmented spot-market channels lacking warranty backing. Target European e-bike micromobility replacement demand with small-format pouch cell configurations where Chinese suppliers dominate but service infrastructure remains underdeveloped. Pursue white-label pack assembly partnerships with fleet operators seeking guaranteed residual value terms as a go-to-market angle. For Investors and Strategic Acquirers: Korean cathode material specialists with Indonesian precursor refining assets are the most active acquirer in this space, consolidating backward integration capabilities ahead of EU battery passport requirements. Long-term viability rests on mineral provenance traceability infrastructure and closed-loop recycling economics. Acquisition targets should demonstrate captive nickel supply agreements and KC or JIS certification pathways. Monitor solid-state pilot production announcements from Japanese OEMs as the inflection indicator for chemistry transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Indonesian Nickel Precursor Integration | Korean cathode producers bypass Chinese intermediate dominance through Busan-Ulsan corridor investments. |
| Solid-State Electrolyte Pilot Production | Panasonic validates ceramic-polymer configurations for Toyota's next-generation 48V hybrid platforms. |
| EU Battery Passport Compliance | Blockchain-verified chain-of-custody systems become mandatory for German and Swedish OEM market access. |
| Prismatic Module Architecture Expansion | LG Chem and Samsung SDI displace cylindrical formats in BMW and Mercedes-Benz hybrid lineups. |
| METI Closed-Loop Recovery Infrastructure | Japan's revised resource circulation mandates lower virgin cobalt dependency for Kanto region producers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, cathode material R&D directors, and aftermarket distributors with secondary validation from MIIT NEV credit filings, METI resource circulation policy documents, KATS KC certification registries, and vehicle production databases. Bottom-up cell shipment estimates by format and chemistry triangulated against top-down OEM electrification commitment disclosures.
Segment-weighting approaches applied differential growth coefficients across prismatic, cylindrical, pouch, and modular formats, with NMC, LFP, LCO, and NCA chemistries modeled separately. Vehicle class segmentation captured passenger, commercial, two-wheeler, and e-bike duty cycle variations. CAGRs were derived from production capacity expansion timelines and OEM platform lifecycle commitments across the projection horizon. Forecast inputs incorporated nickel and cobalt price index movements, certification protocol alignment progress, and solid-state technology readiness levels.
Underlying measurement precision varies by segment; OEM captive supply agreements carry tighter precision than aftermarket replacement demand due to contract visibility. Forecasts reflect assumptions regarding MIIT dual carbon mandate enforcement continuity, Indonesian nickel processing capacity ramp schedules, and Korean-Japanese certification protocol harmonization. A model refresh is warranted upon material change in solid-state electrolyte commercialization timelines or EU battery passport implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market