
 Taiwan Lithium-Ion Battery Market | 2026-2036
Taiwan Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Lithium-Ion Battery Market Insights
Taiwan's net-zero emissions commitment by 2050 is rebalancing procurement criteria across the battery value chain. E-One Moli Energy leverages its cylindrical cell specialization to anchor supply agreements with high-performance tool makers. Dynapack International sustains its position through backward integration into pack assembly for consumer electronics brands. CATL competes aggressively on cost in the energy storage segment while navigating local content expectations.
Lithium-ion batteries store electrochemical energy through reversible intercalation of lithium ions between layered oxide cathodes and graphitic anodes, typically operating at nominal voltages of 3.2–3.7 V with energy densities reaching 250–300 Wh/kg for premium cells. Their primary purpose is to provide rechargeable power for portable electronics, electric mobility, and grid-scale storage systems. Cylindrical formats dominate the power tool and consumer electronics sectors where thermal management and mechanical durability command premium positioning. Polymer cells lead in mobile devices due to form-factor flexibility, while the automotive segment is gravitating toward prismatic architectures for pack-level volumetric efficiency. Li-NMC chemistry occupies the highest-margin tier for electric vehicle applications, whereas Li-Cobalt retains share in compact consumer electronics where energy density outweighs cost sensitivity.
The Bureau of Energy under the Ministry of Economic Affairs enforces storage system safety standards that shape product certification requirements for domestic deployment. The Environmental Protection Administration administers battery recycling mandates under extended producer responsibility frameworks that alter cost structures for manufacturers. BIS-aligned testing protocols for cell imports create compliance barriers that favor localized production investments. Stakeholders must monitor how carbon accounting rules and recycling quotas reshape supplier qualification criteria before committing to capacity expansion.
Market Dynamics
Taiwan's lithium-ion battery sector is being reconfigured by the Ministry of Economic Affairs' carbon accounting mandates, which are forcing pack assemblers to document embodied emissions across cathode precursor sourcing. This regulatory pressure is compressing margins for importers while favoring domestic cell producers with verified supply chains.
Growth Catalysts
- EU Green Deal carbon border adjustments:Taiwanese exporters to European markets must certify battery carbon intensity, creating pull for low-emission cell production.
- Semiconductor-battery integration:Hsinchu Science Park fabs are co-locating energy storage systems to manage power quality for advanced lithography tools.
- Tool makers:Cordless power equipment manufacturers are specifying cylindrical high-discharge cells for brushless motor platforms.
Market Restraints
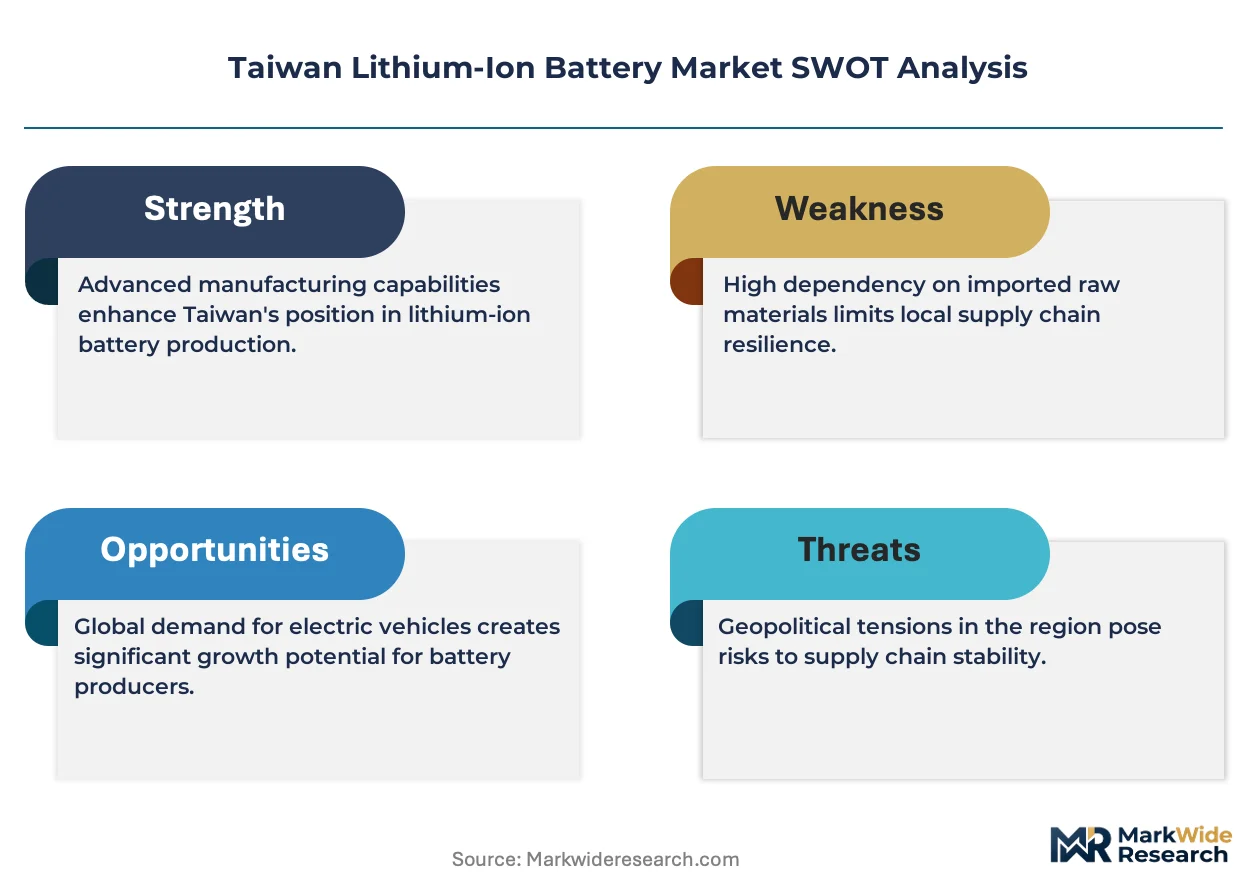
- Cathode active material concentration:Over 80% of global NMC precursor refining sits in Chinese industrial zones, exposing Taiwanese cell makers to supply disruption.
- Extended producer responsibility costs:The Environmental Protection Administration's recycling mandates impose per-kilogram fees that elevate pack-level cost structures.
- Solid-state substitution timeline:Oxide-based solid electrolyte cells threaten conventional liquid electrolyte architectures in premium mobility segments.
Strategic Opportunities
- Energy storage systems:Grid-scale deployments for Taiwan Power Company frequency regulation tenders represent underpenetrated volume.
- Marine electrification:Kaohsiung Port's shore power mandates are creating demand for maritime-certified battery systems.
- AI-driven cell sorting:Machine vision classification of formation cycle data is enabling premium tier extraction from production variance.
Industry Challenges
- Electrolyte formulation chemists:Talent scarcity in high-voltage additive design is constraining local R&D throughput.
- UN 38.3 certification timelines:International air transport testing delays are extending product launch cycles for export-bound packs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Lithium-Ion Battery Market |
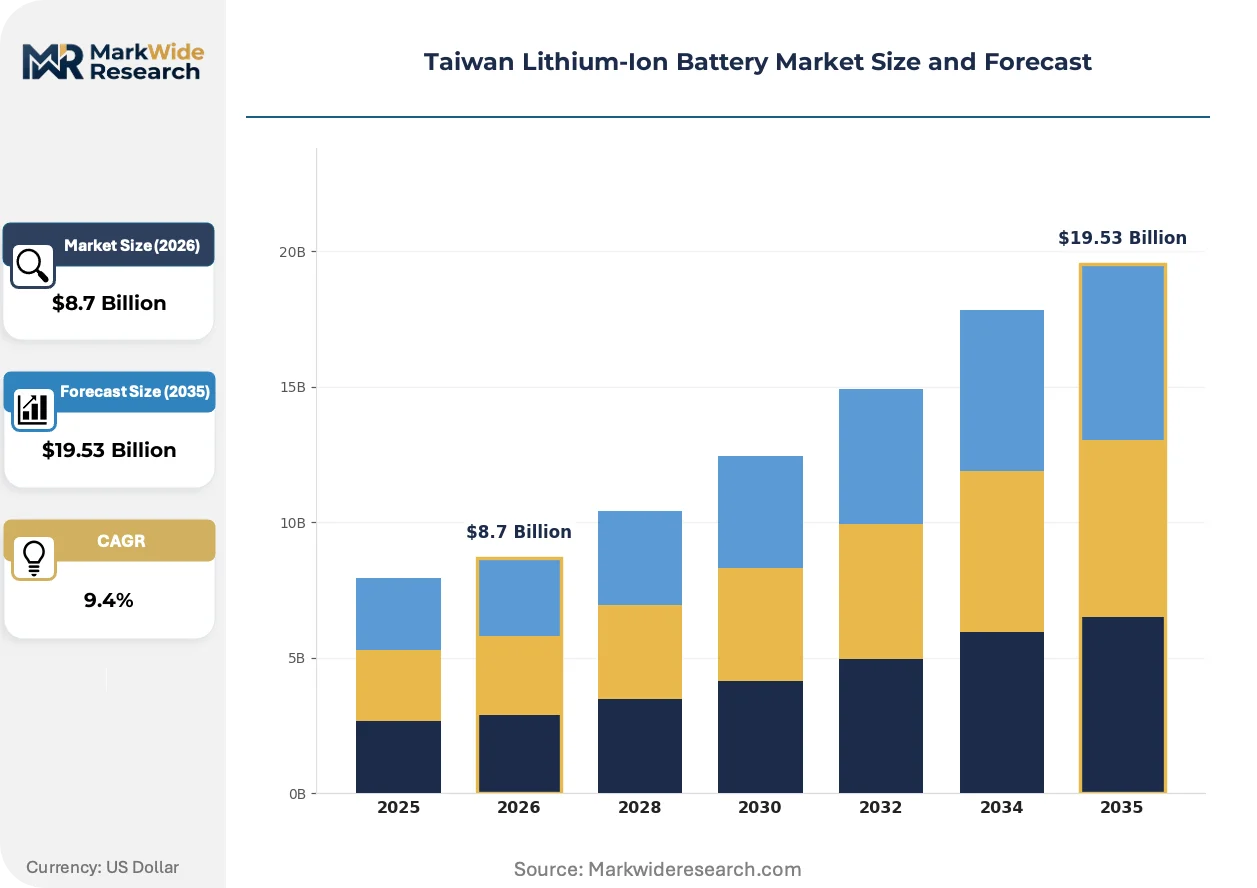
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Prismatic, Polymer, Other End User: Consumer Electronics, Automotive, Industrial, Energy Storage Application: Mobile Devices, Electric Vehicles, Uninterruptible Power Supply, Power Tools Technology: Li-NMC, Li-Graphene, Li-Cobalt, Others |
| Companies Covered | E-One Moli Energy (Molicel), Dynapack International, Kung Long Batteries, Amita Technologies, Simplo Technology, LG Energy Solution, CATL, Panasonic Corporation, BYD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Lithium-Ion Battery Market Trends and Innovations
Solid-state and silicon-anode chemistries are absorbing capital and engineering attention across Taiwanese cell producers, while regulatory pressure on carbon transparency is reshaping how supply chains are documented and audited.
Silicon-graphite composite anodes are absorbing volume share in high-energy applications by enabling 400 Wh/kg cell-level targets. Electric motorcycle assemblers in Taichung are qualifying these materials for 2026 platform launches. The technology is absorbing margin pressure from cobalt price volatility by reducing cathode loading requirements.
The Bureau of Energy's revised fire safety standards for stationary storage are mandating gas detection and suppression systems in containerized installations. Industrial integrators must now source certified battery management systems from approved vendors. Large-scale solar-plus-storage projects in Tainan are absorbing compliance costs through longer depreciation schedules.
Direct procurement from cell makers is displacing distributor intermediaries among electronics original equipment manufacturers. Brand customers are establishing technical qualification teams to audit formation data directly. This pattern is most visible in notebook computer supply chains, where pack assemblers face margin compression from backward integration by device brands.
Taiwan Lithium-Ion Battery Market Segmentation
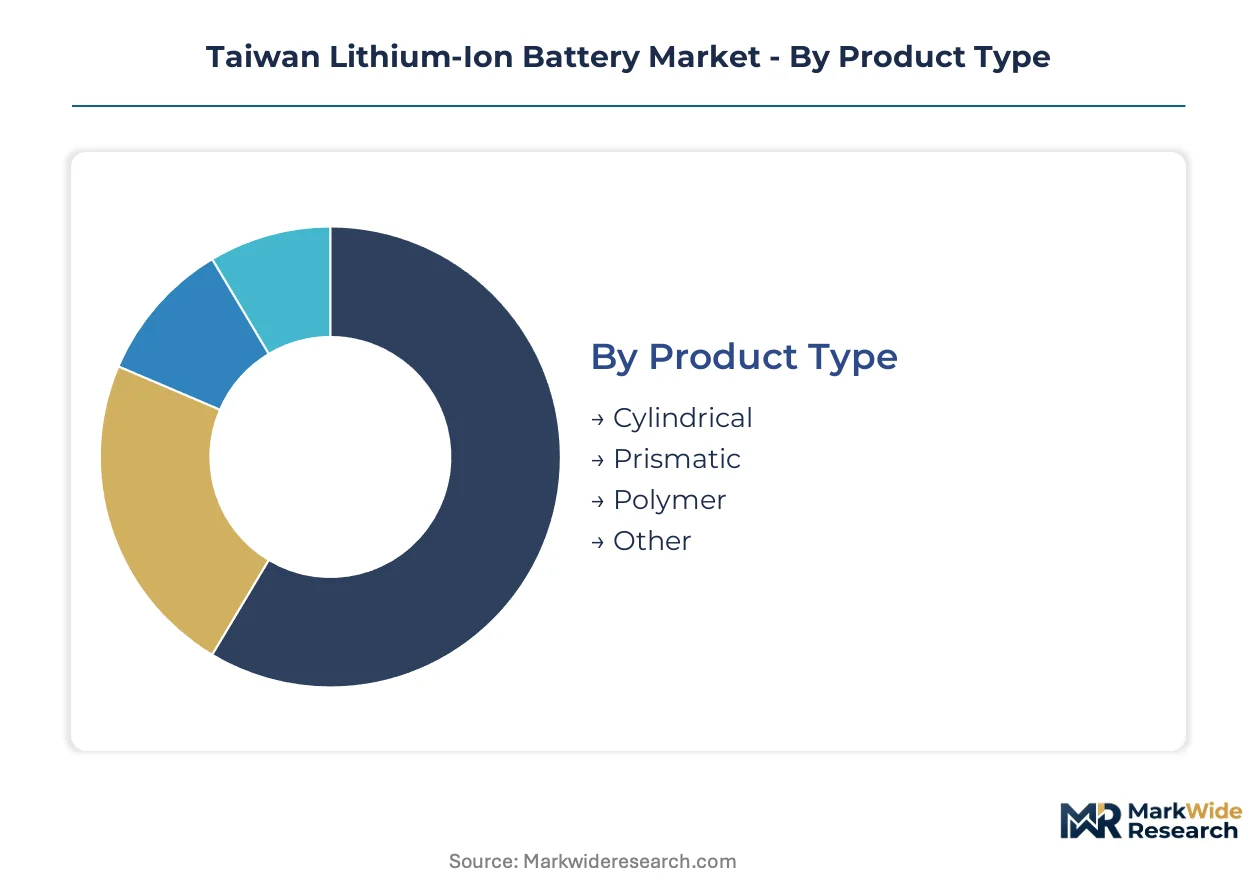
Equipment refresh cycles and platform upgrades across Taiwan's electronics and automotive sectors create divergent demand profiles for each battery format. Procurement teams weight energy density, thermal stability, and pack integration complexity differently depending on end-use specifications.
Product Type:
Replacement timelines for existing equipment fleets favor formats with established recycling infrastructure and proven manufacturing yields.
- Cylindrical:Rolled electrode architectures deliver superior mechanical integrity and thermal runaway containment. Power tool manufacturers in central Taiwan specify 18650 and 21700 formats for brushless motor platforms requiring sustained 20A discharge rates.
- Prismatic:Flat wound or stacked electrode configurations maximize volumetric packing efficiency at module level. Electric vehicle pack assemblers in Miaoli County favor aluminum-housed prismatic cells for structural integration into floor pans.
- Polymer:Laminated foil pouch construction enables sub-3mm thickness profiles for ultra-slim device integration.
- Other:Coin cells and specialty formats serve medical and IoT sensor applications with constrained footprint requirements.
Cylindrical sits at the top of the volume ranking, with Prismatic climbing the fastest.
End User:
Cost-to-performance thresholds vary sharply across buyer categories, with procurement authority residing at different organizational levels.
- Consumer Electronics:Brand OEMs negotiate direct cell supply agreements to capture margin from pack assembly. Notebook computer manufacturers in New Taipei City are backward integrating into battery management system firmware development.
- Automotive:Domestic assemblers qualify cell suppliers against UN ECE R100 and local fire safety protocols. Electric bus procurement by municipal transport authorities in Taichung and Kaohsiung is absorbing high-volume cylindrical and prismatic supply.
- Industrial:Forklift and automated guided vehicle fleets require cycle-life warranties exceeding 3,000 deep discharges.
- Energy Storage:Taiwan Power Company frequency regulation tenders specify 15-year performance guarantees and local service presence.
Consumer Electronics commands the largest revenue pool, though Energy Storage is expanding most quickly.
Application:
Platform-specific form factors and discharge profiles fragment procurement across unrelated supply chains.
- Mobile Devices:Polymer pouch cells dominate smartphone and tablet integration where thickness below 5mm is mandatory. Hsinchu-based semiconductor firms are co-developing battery management ICs with tier-one pack assemblers.
- Electric Vehicles:Module-to-pack architectures prioritize gravimetric density and crashworthiness validation. Gogoro's battery swapping network in Taipei and Taoyuan creates standardized cell format demand distinct from automotive OEM specifications.
- Uninterruptible Power Supply:Data center operators specify 15-minute backup duration with 10-year calendar life.
- Power Tools:High-rate cylindrical cells enable cordless equipment matching corded performance.
Mobile Devices leads in unit volume, with Electric Vehicles gaining share fastest.
Technology:
Cathode chemistry selection trades energy density against material cost volatility and safety certification complexity.
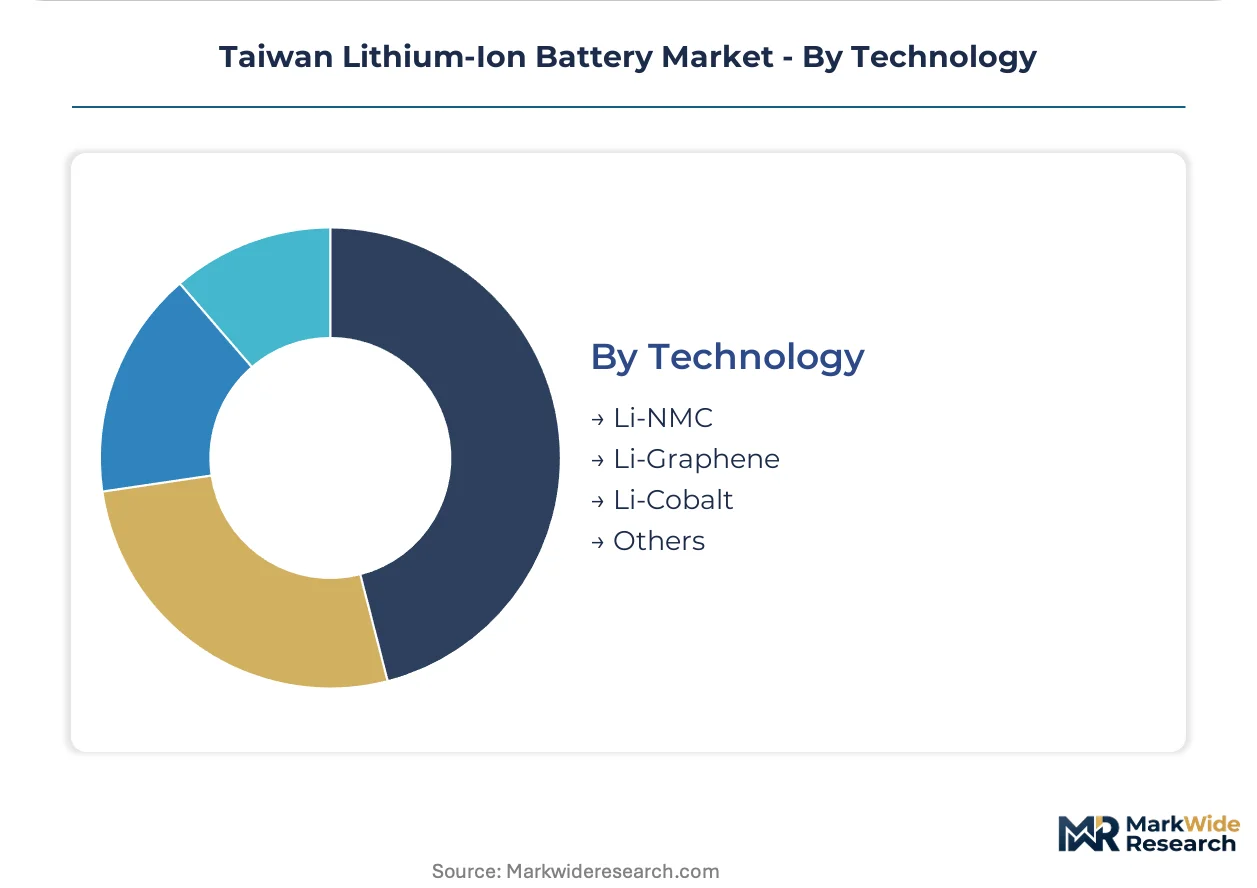
- Li-NMC:Nickel-manganese-cobalt layered oxides balance specific capacity and thermal stability across 3.6V nominal operation. Automotive cell producers in Taiwan are qualifying NMC 811 variants for 300 Wh/kg pack-level targets.
- Li-Cobalt:Lithium cobalt oxide cathodes maximize volumetric energy density for premium consumer electronics. Smartphone brands specify Li-Co cells where device thickness constraints override cobalt price sensitivity.
- Li-Graphene:Conductive additive enhancements aim to reduce DC internal resistance for high-rate applications.
- Others:Lithium iron phosphate and emerging sodium-ion formulations serve cost-sensitive stationary storage segments.
Li-NMC occupies the dominant position by value, with Li-Graphene advancing most rapidly in specialty applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's battery engineering talent concentrates in Hsinchu and Taoyuan, where semiconductor fabrication expertise migrates into cell design and battery management system development. This technical workforce anchors the island's specialized position in high-performance cylindrical cells and precision pack assembly.
Northern Taiwan
Hsinchu Science Park fabs drive demand for uninterruptible power systems and precision energy storage. The Bureau of Energy enforces fire safety standards for stationary installations co-located with semiconductor manufacturing. Taoyuan's aerospace supply chain is qualifying aviation-certified cells for electric vertical takeoff aircraft development programs.
Central Taiwan
Taichung's electric motorcycle assemblers absorb high-rate cylindrical cells for 2026 platform launches. The Environmental Protection Administration's extended producer responsibility framework imposes per-kilogram recycling fees on battery packs sold into this segment. Changhua's industrial machinery cluster sources automated guided vehicle battery systems with 3,000-cycle warranties.
Southern Taiwan
Kaohsiung Port's shore power mandates create demand for maritime-certified energy storage systems. Taiwan Power Company frequency regulation tenders specify 15-year performance guarantees that favor established service providers. Tainan's solar-plus-storage projects absorb compliance costs for revised gas detection and suppression standards through extended depreciation schedules.
China
Mainland cathode active material refiners supply over 80% of global NMC precursor output, exposing Taiwanese cell makers to concentrated supply risk. MIIT dual carbon goals and GB standards shape cross-strait component trade flows. CATL competes aggressively on cost in Taiwan's energy storage segment while navigating local content expectations.
Japan
Panasonic and Japanese materials suppliers maintain technical relationships with Taiwanese pack assemblers through component licensing and formation equipment supply. METI battery safety standards influence Taiwan's UN 38.3 certification alignment for export-bound products. Tokyo-based trading houses intermediate specialty electrolyte additive shipments to Hsinchu cell producers.
Taiwan Lithium-Ion Battery Market Competitive Landscape
Capital-heavy cell producers compete with asset-light pack designers across Taiwan's battery value chain. The market structure separates cylindrical specialists serving power tool OEMs from polymer pouch integrators focused on consumer electronics brands. Three archetypes dominate: domestic cell manufacturers with backward integration into formation, foreign cell makers competing on scale, and pure-play pack assemblers sourcing cells from multiple origins. Competitive moves center on direct procurement relationships with device brands and qualification for Taiwan Power Company utility tenders.
Among domestic cell producers, E-One Moli Energy anchors the cylindrical specialization tier, while Dynapack International exemplifies the integrated pack assembly model. CATL represents the foreign scale competitor archetype in energy storage applications. These three occupy positions that illustrate how technical focus, vertical scope, and geographic origin segment competitive space in Taiwan's lithium-ion battery market.
| Leading Market Players |
|---|
| E-One Moli Energy (Molicel) |
| Dynapack International |
| Kung Long Batteries |
| Amita Technologies |
| Simplo Technology |
| LG Energy Solution |
| CATL |
| Panasonic Corporation |
| BYD |
| Others |
Pricing and Supply Chain Analysis
The Environmental Protection Administration's extended producer responsibility framework gates qualified supply and premium-tier pricing access, as only pack assemblers absorbing certified recycling costs can bid for municipal electric bus tenders. Buyers now screen suppliers through carbon intensity documentation mandated by the Bureau of Energy, bifurcating the market between verified low-emission cell producers commanding price premiums and importers facing margin compression.
Pricing Analysis
Cell-plus-packaging bundled contracts dominate utility-scale procurement, while unbundled spot transactions persist in consumer electronics spot markets. Price differentiation hinges on Bureau of Energy fire safety certification tier and cathode chemistry grade, with NMC 811 cells commanding premiums over LFP alternatives. Cost compression in standard-tier cylindrical cells is intensifying because CATL's aggressive energy storage pricing forces domestic producers to absorb recycling fees without pass-through. Industrial forklift fleets exhibit highest price sensitivity due to total-cost-of-ownership calculations, whereas semiconductor fabs show lowest sensitivity given power quality requirements.
Supply Chain Analysis
Dual-sourcing requirements from Taiwan Power Company tenders force pack assemblers to qualify cell suppliers across at least two countries, typically drawing from South Korean and Japanese producers alongside domestic options. Raw material dependencies center on Chinese NMC precursor refiners, Australian spodumene concentrate, and Japanese electrolyte additive specialists. Single-source vulnerability concentrates in cathode active material supply, where over four-fifths of global refining capacity sits in mainland industrial zones. Distribution runs through direct technical qualification relationships with electronics OEMs, displacing traditional distributor intermediaries in notebook and power tool segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's lithium-ion battery sector reads as a late-cycle quality story, with procurement teams at Gogoro and domestic automotive assemblers shifting specifications toward premium-tier cells with verified carbon accounting and extended cycle warranties.
For Market Incumbents: Lock in formation capacity expansion in Miaoli County to defend against solid-state substitution threats in premium mobility segments. Prioritize Bureau of Energy certification investment for gas detection-integrated battery management systems, as Taiwan Power Company frequency regulation tenders now mandate approved vendor lists. Deepen backward integration into cathode precursor partnerships with South Korean refiners to reduce Chinese supply concentration exposure. For New Entrants and Emerging Players: Marine-certified system integrators represent an underserved buyer archetype with limited incumbent coverage. Kaohsiung Port shore power mandates create immediate demand for salt-resistant enclosures and maritime-grade thermal management, with qualification pathways less crowded than automotive or consumer electronics segments. Pursue joint development agreements with Taichung electric motorcycle assemblers seeking silicon-anode qualification for 2026 platform launches. For Investors and Strategic Acquirers: Roll-up economics work for precision pack assemblers with semiconductor-adjacent battery management system capabilities because Hsinchu Science Park fabs demand co-located energy storage with customized power quality specifications. Five-to-ten year viability favors specialists with captive formation lines and direct OEM technical relationships over pure trading intermediaries. Watch Taiwan Power Company tender award patterns as the inflection signal for grid-scale storage demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Anode Qualification Program | Taichung electric motorcycle assemblers target 400 Wh/kg cell density for 2026 platforms. |
| Maritime Certification Pathway | Kaohsiung Port shore power mandates absorb certified systems from qualified integrators. |
| Carbon Accounting Documentation System | Bureau of Energy mandates force supply chain transparency for EU Green Deal export compliance. |
| Direct OEM Technical Qualification | New Taipei notebook manufacturers bypass distributors to audit formation data directly. |
| Frequency Regulation Tender Positioning | Taiwan Power Company 15-year performance guarantees favor established service presence. |
Research Methodology
Coverage spans Taiwan's northern, central, and southern industrial clusters, with primary inputs from each region triangulated against secondary validation. Interviews with cell formation engineers, pack assembly procurement leads, Bureau of Energy safety certification officers, and Taiwan Power Company grid planning specialists combined with customs trade data, Ministry of Economic Affairs production statistics, UN 38.3 certification records, and semiconductor fab energy storage RFP documents. Bottom-up cell production estimates and top-down end-use consumption models were cross-referenced for convergence.
Rate-of-change decomposition across the analysis window separates volume growth from value mix shift, with CAGRs derived from segment-level production capacity buildout and replacement cycle timing. Segmentation dimensions modeled include cell format, cathode chemistry, end-use sector, and regional manufacturing cluster. Industry-specific forecast inputs incorporate Taiwan Power Company tender pipeline visibility and electric motorcycle platform launch schedules from Taichung assemblers.
Underlying measurement precision varies by segment; cylindrical cell production carries tighter precision than emerging solid-state pilot volumes. Forecasts reflect assumptions on cathode material price trajectories, recycling fee pass-through rates, and EU carbon border adjustment implementation timing. Deviation in Chinese NMC precursor export licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
UAV Lithium Battery Market