
 Lithium Ion Energy Accumulator Market | 2026-2036
Lithium Ion Energy Accumulator Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Energy Accumulator Market Foresight
Subscription-based battery health monitoring and software-defined capacity management is consolidating around the cell as a serviceable asset rather than a commodity component. Contemporary Amperex Technology Co., Limited anchors its position through vertical integration into cathode precursor production. LG Energy Solution leverages long-term offtake contracts with premium automotive OEMs to sustain margin visibility. Samsung SDI competes on cylindrical cell specialization for performance electric vehicles.
A lithium ion energy accumulator is an electrochemical storage device utilizing intercalated lithium compounds in the cathode and a graphite or silicon-composite anode, typically operating at nominal voltages of 3.2–3.7 V with energy densities reaching 250–300 Wh/kg for nickel-rich formulations, designed to reversibly store and discharge electrical energy for portable, vehicular, and grid-scale applications. Prismatic formats dominate automotive pack integration due to space efficiency and thermal management compatibility, while cylindrical cells retain cost advantages in high-volume consumer and tool applications. Lithium iron phosphate chemistry is capturing share in energy storage and commercial vehicle segments where cycle life and thermal stability outweigh energy density requirements.
China's MIIT enforces GB standards for cell safety and recycling traceability, while the EU's Battery Regulation mandates carbon footprint declarations and recycled content quotas that reshape import competitiveness. The US IRA production credits are localizing cathode and cell manufacturing away from concentrated Asian supply nodes. Stakeholders must monitor how divergent carbon accounting rules across Beijing, Brussels, and Washington create compliance fragmentation that favors regionally embedded producers.
Market Dynamics
Automotive OEMs are consolidating cell procurement around long-term offtake contracts with tier-one suppliers, compressing spot-market liquidity and embedding battery suppliers deeper into vehicle platform development cycles.
Growth Catalysts
- IRA Production Credits:The US Inflation Reduction Act is localizing cathode active material and cell assembly capacity through domestic content bonuses, pulling investment away from concentrated Asian supply nodes.
- EU Battery Regulation:Mandatory carbon footprint declarations and recycled content quotas are creating compliant demand pools that favor producers with verified supply chain traceability.
- Solid-state pilot lines:Toyota and Samsung SDI are scaling sulfide-based electrolyte production, with automotive qualification timelines compressing from five years toward three.
Market Restraints
- Cathode precursor concentration:Over 70% of refined cobalt and nickel sulfate processing sits in Chinese Jiangsu and Fujian corridors, exposing non-Chinese cell makers to concentrate risk.
- Silicon anode swelling:Volume expansion during lithiation cycles above 300% degrades cell longevity, limiting silicon-composite anodes to sub-10% blend ratios in commercial automotive cells.
- F-Gas Regulation friction:The EU's phasedown of hydrofluorocarbon coolants used in cell dry rooms is forcing capital-intensive retooling of thermal management infrastructure.
Strategic Opportunities
- India PLI scheme:The country's production-linked incentive for advanced chemistry cells offers 18% capex support for gigafactory investments, with demand concentrated in Tamil Nadu and Gujarat manufacturing corridors.
- Second-life stationary storage:Retired automotive packs with 70-80% state-of-health are repurposing for grid-scale frequency regulation, creating new revenue streams for OEMs with battery management system data access.
- Vehicle-to-grid integration:Bidirectional charging hardware and utility rate structures are converging in California and Germany, enabling EV fleets to monetize grid services.
Industry Challenges
- Dry electrode coating scale-up:Solvent-free electrode manufacturing reduces energy and capex but requires requalification of 500+ process parameters, stretching engineering talent pools at cell makers.
- GB standard compliance timelines:China's MIIT safety certification for new cell formats demands 12-18 month validation cycles, delaying platform launches for foreign entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Energy Accumulator Market |
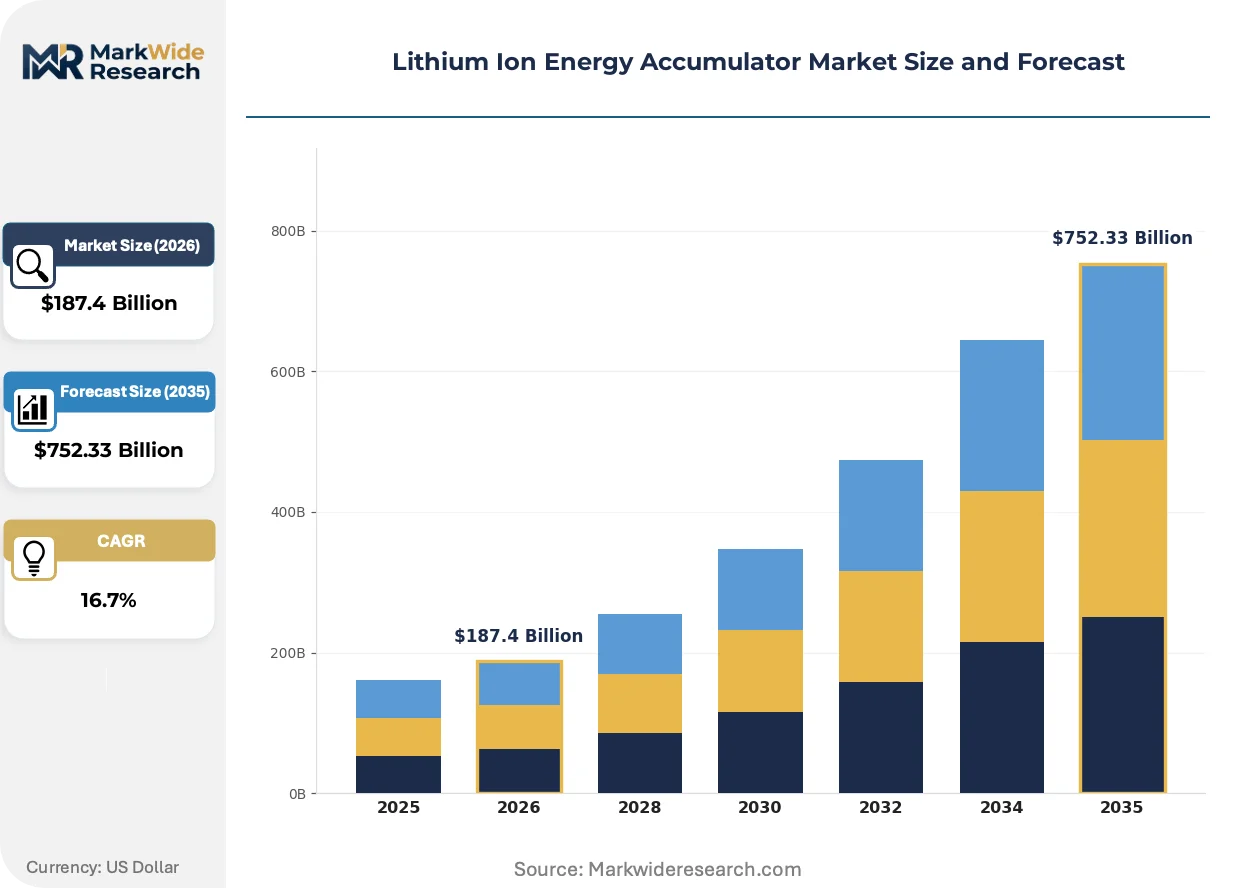
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $752.33 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Coin End User: Consumer Electronics, Automotive, Energy Storage, Industrial Applications Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Technology: Lithium Cobalt Oxide, Lithium Iron Phosphate, Lithium Manganese Oxide, Lithium Nickel Cobalt Aluminum Oxide |
| Companies Covered | Contemporary Amperex Technology Co., Limited, LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, BYD Company, Asahi Kasei, Toshiba Corporation, Hitachi, CATL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Energy Accumulator Market Shifts & Advancements
Cell chemistry and pack architecture are diverging across end-use verticals, with nickel-rich formulations for premium passenger vehicles, lithium iron phosphate for commercial and storage applications, and sodium-ion emerging as a cost floor for two-wheelers and entry vehicles.
Sodium-ion chemistry is consolidating as a viable alternative for price-sensitive mobility and stationary applications where energy density requirements sit below 160 Wh/kg. CATL and BYD are scaling layered oxide cathode production for the two-wheeler and entry automotive segments in China. This chemistry is compressing the addressable market for low-nickel lithium-ion cells by 15-20% in volume terms.
REACH substance restrictions on nickel compounds are forcing European cell makers to accelerate cobalt-free high-voltage spinel and manganese-rich layered oxide development. The industrial consequence is a bifurcation in cathode precursor sourcing, with EU-bound cells requiring segregated supply chains from Asian production. Passenger EV platforms targeting the EU market are responding by dual-sourcing NMC and LFP variants to hedge regulatory exposure.
Fleet operators and energy storage developers are unbundling cell procurement from pack integration and battery management system provision. This pattern concentrates purchasing power among asset owners with 10+ GWh deployment pipelines, compressing margins for pure-play cell suppliers without software or integration capabilities. The shift is most visible in Texas and California, where independent power producers are issuing direct cell tenders to Chinese and Korean manufacturers, bypassing traditional tier-one pack integrators.
Lithium Ion Energy Accumulator Market Segmentation
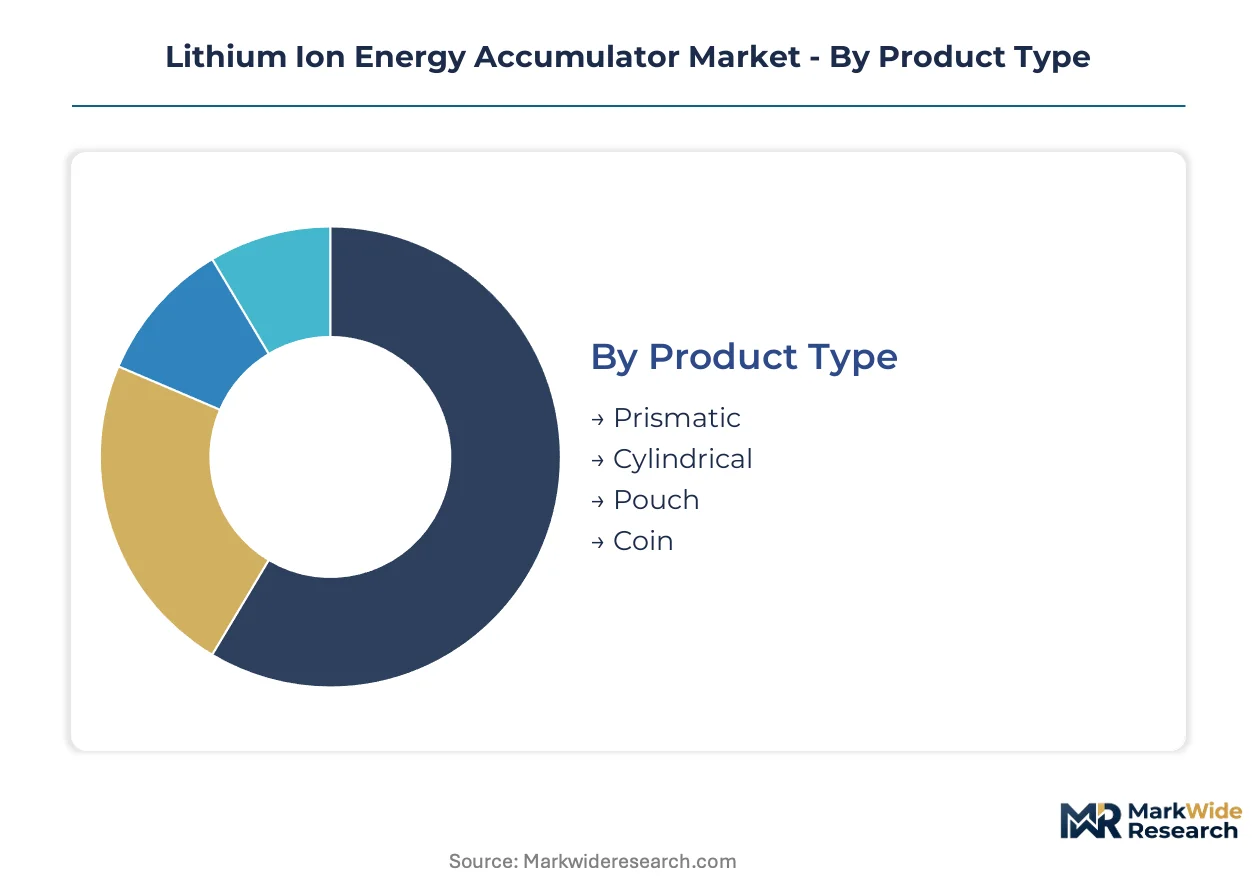
Cell format and chemistry choices directly determine pack integration complexity, thermal management requirements, and supply chain exposure for energy storage deployments. Procurement patterns across automotive OEMs and grid-scale developers are fragmenting around divergent performance specifications and regional regulatory compliance.
Product Type:
Physical cell architecture dictates manufacturing equipment, pack design flexibility, and automation pathways across volume tiers.
- Prismatic:Rectangular aluminum-cased cells with stacked electrode layers enable high volumetric efficiency in automotive pack architectures. Demand concentrates in Germany's emerging cell assembly clusters and China's Jiangsu manufacturing corridor, driven by space-constrained passenger EV platforms requiring direct cell-to-pack integration.
- Cylindrical:Rolled jellyroll construction in standardized diameters (18650, 21700, 4680) delivers manufacturing scale economies and consistent thermal behavior. South Korea's battery belt and Tesla's Nevada operations anchor high-volume production, with format dominance in power tools and premium electric vehicles where cylindrical specialization supports performance positioning.
- Pouch:Flexible polymer-foil packaging allows custom aspect ratios and high packing density for space-optimized consumer devices and commercial vehicle modules.
- Coin:Compact disc-shaped cells serve low-drain wearable electronics and medical implant applications where footprint minimization outweighs energy density requirements.
Mature deployment sits with Cylindrical formats in consumer and tool applications. Newer deployment is concentrated in Prismatic cells for automotive direct integration.
End User:
Application-specific duty cycles, safety certification requirements, and total cost of ownership calculations reshape procurement specifications across verticals.
- Automotive:High-cycle-life cells with automotive-grade safety validation support 8-year/100,000-mile warranty obligations. Long-term offtake contracts with tier-one suppliers are compressing spot-market liquidity and embedding battery suppliers deeper into vehicle platform development cycles across passenger and commercial vehicle segments.
- Energy Storage:Grid-scale and behind-the-meter installations prioritize cycle life, thermal stability, and capital cost per kWh over gravimetric energy density. Independent power producers in Texas and California are issuing direct cell tenders to Chinese and Korean manufacturers, bypassing traditional tier-one pack integrators.
- Consumer Electronics:Smartphones, laptops, and wearables drive demand for highest energy density in compact footprints with thin-profile pouch and prismatic formats.
- Industrial Applications:Forklifts, mining equipment, and marine propulsion require ruggedized pack enclosures and extended operational temperature ranges.
Automotive procurement commands the steepest expansion trajectory as electric vehicle manufacturers scale orders for high-capacity cells. Energy Storage deployment is climbing fastest among asset owners with 10+ GWh deployment pipelines.
Capacity:
Energy content per cell determines series-parallel configuration complexity and management system overhead in large-format installations.
- High Capacity:Cells exceeding 100 Ah reduce interconnect complexity and assembly labor in grid-scale containerized storage and commercial electric vehicles. China's NMPA certification timelines and dual carbon goals are tightening cell validation and carbon intensity benchmarks for high-capacity imports.
- Ultra High Capacity:Next-generation formats above 300 Ah target direct cell-to-pack architectures eliminating module-level components. Solid-state pilot lines at Toyota and Samsung SDI are scaling sulfide-based electrolyte production with automotive qualification timelines compressing toward three years.
- Medium Capacity:Standardized 50-100 Ah cells balance manufacturing flexibility across automotive and stationary applications with established supply chains.
- Low Capacity:Sub-50 Ah cells dominate consumer electronics and power tools where rapid charge capability and form factor versatility outweigh single-cell energy content.
Mature deployment sits with Medium Capacity cells serving dual automotive and industrial applications. Newer deployment is concentrated in Ultra High Capacity formats for simplified pack architectures.
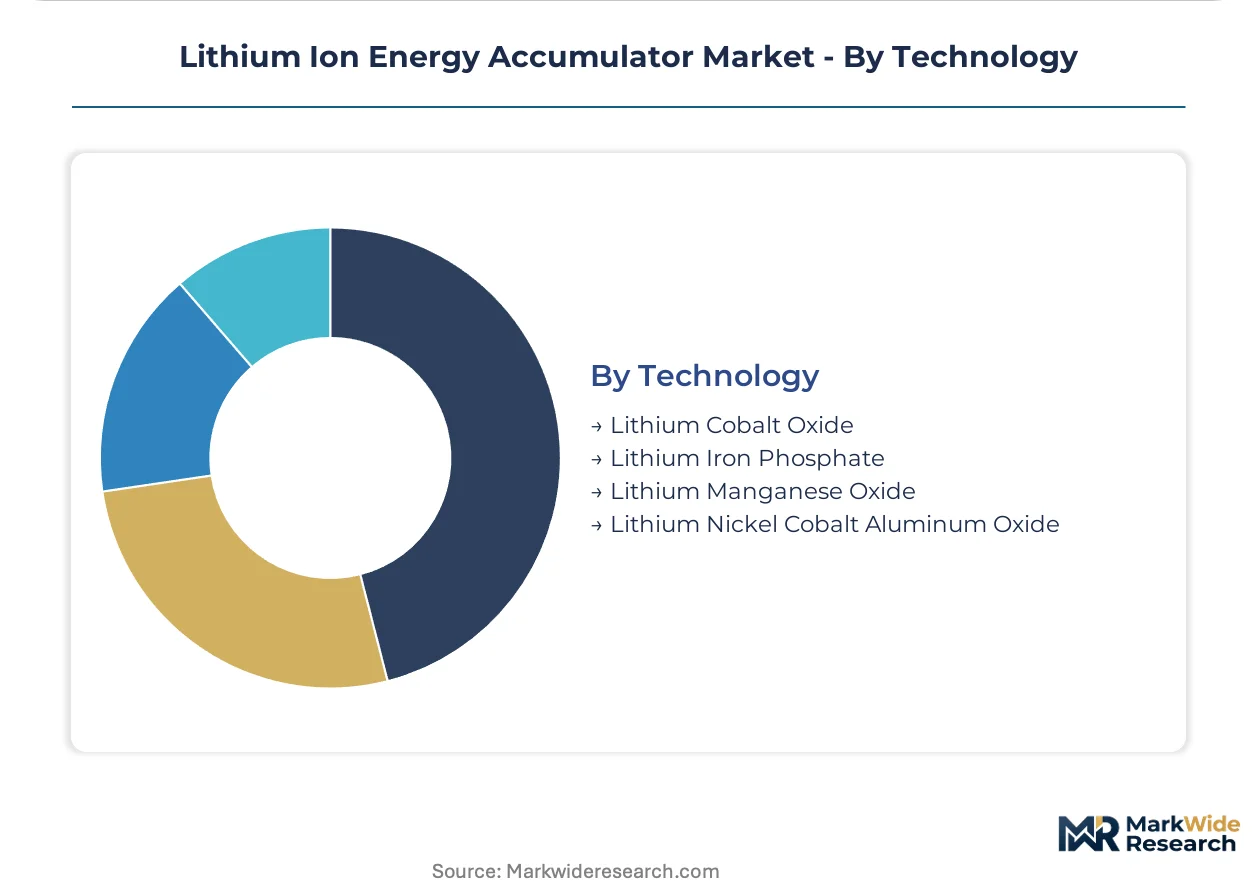
Technology:
Cathode chemistry selection trades energy density, cycle life, thermal stability, and supply chain exposure against end-use performance requirements.
- Lithium Iron Phosphate:Olivine-structured cathodes deliver 3,000-6,000 cycle life and superior thermal runaway resistance at lower energy density. Demand is capturing share in energy storage and commercial vehicle segments where cycle life and thermal stability outweigh energy density requirements, with CATL and BYD scaling production for China domestic and export markets.
- Lithium Nickel Cobalt Aluminum Oxide:Ni-rich layered oxides achieve 250-300 Wh/kg for premium passenger electric vehicles requiring maximum range. The US IRA production credits are localizing cathode active material and cell assembly capacity through domestic content bonuses, pulling investment away from concentrated Asian supply nodes.
- Lithium Cobalt Oxide:High-voltage layered oxides maximize volumetric energy density for premium smartphones and laptops where cobalt cost exposure is acceptable.
- Lithium Manganese Oxide:Spinel-structured cathodes offer cost positioning and safety margins for power tools and entry electric two-wheelers with moderate cycle life requirements.
Mature deployment sits with Lithium Cobalt Oxide in consumer electronics. Newer deployment is concentrated in Lithium Iron Phosphate for grid storage and commercial transport applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Fujian provinces anchor cell manufacturing capacity, with South Korea's battery belt and Germany's emerging assembly clusters completing the dominant production geography. Regulatory divergence across Beijing, Brussels, and Washington fragments compliance requirements. Local content rules and carbon accounting standards reshape investment flows.
China
Electric vehicle manufacturers scale orders for high-capacity cells through domestic supply chains. MIIT enforces GB standards for cell safety and recycling traceability, while NMPA certification demands 12-18 month validation cycles. Jiangsu and Fujian manufacturing corridors concentrate over 70% of refined cobalt and nickel sulfate processing.
South Korea
Premium automotive OEMs execute long-term offtake contracts with tier-one suppliers. MFDS oversight aligns with international battery safety protocols for export markets. The battery belt spanning Ulsan and Gwangju anchors cylindrical cell specialization for performance electric vehicles.
Germany
Passenger EV platforms dual-source NMC and LFP variants to hedge EU regulatory exposure. The EU Battery Regulation mandates carbon footprint declarations and recycled content quotas. Emerging cell assembly clusters in Lower Saxony and Baden-Württemberg attract IRA-influenced supplier relocation.
United States
Independent power producers issue direct cell tenders to Asian manufacturers, bypassing traditional pack integrators. IRA production credits localize cathode active material and cell assembly capacity through domestic content bonuses. Texas and California utility rate structures converge on bidirectional charging for fleet grid services.
India
Tamil Nadu and Gujarat manufacturing corridors attract 18% capex support under the PLI scheme for advanced chemistry cells. CEA grid integration standards shape procurement specifications for stationary storage developers. Asset owners with 10+ GWh deployment pipelines concentrate purchasing power in direct manufacturer negotiations.
Lithium Ion Energy Accumulator Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across cathode chemistry and pack integration tiers. The structure consolidates around three to five vertically integrated cell makers with captive precursor supply, while modular pack integrators compete on software-defined battery management. Strategic archetypes span cathode precursor controllers, cylindrical specialists, and prismatic automotive integrators. Dominant competitive moves include backward integration into mining and refining, plus geographic capacity relocation to capture regional content bonuses.
Within the vertically integrated tier, Contemporary Amperex Technology Co., Limited anchors Chinese production scale, while LG Energy Solution occupies a position among Korean manufacturers with premium automotive positioning. Samsung SDI exemplifies the cylindrical specialization archetype for performance applications. These three represent distinct strategic postures on chemistry selection, format focus, and customer segment targeting.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| BYD Company |
| Asahi Kasei |
| Toshiba Corporation |
| Hitachi |
| CATL |
| Others |
Supply & Pricing Matrix
Dry electrode coating scale-up simultaneously compresses manufacturing energy intensity and concentrates equipment procurement leverage among cell makers with proven solvent-free process parameters. This production-method transition reshapes cost economics by eliminating N-methyl-2-pyrrolidone solvent recovery systems while embedding supply risk in the limited pool of qualified coating equipment vendors.
Pricing Analysis
Long-term offtake contracts with automotive OEMs anchor pricing to guaranteed volume throughput rather than spot commodity indices. Pricing stratifies across automotive-grade, industrial-certified, and consumer-tier quality levels with differentiation driven by cycle life validation and carbon footprint certification. Cost compression in energy storage tiers is intensifying because independent power producers with 10 GWh-plus pipelines wield direct tender leverage. Fleet operators exhibit highest price sensitivity, while premium passenger EV platforms prioritize energy density over per-kWh cost.
Supply Chain Analysis
Cathode precursor supply rests on Chinese Jiangsu and Fujian corridors for refined cobalt and nickel sulfate, South Korean battery belt operations for high-purity lithium hydroxide, and Australian spodumene concentrate for upstream feedstock. Cell makers draw from graphite anode feedstock, separator membranes, and electrolyte salt as critical component inputs. Single-source vulnerability concentrates in sulfide-based solid-state electrolyte pilot lines where Toyota and Samsung SDI dominate qualified production. Distribution runs through tier-one pack integrators for automotive OEMs, with direct manufacturer relationships emerging for grid-scale storage developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cathode active material refining capacity bottlenecks in non-Chinese geographies prop pricing power for producers with captive precursor supply or IRA-compliant domestic content qualifications.
For Market Incumbents: Anchor margin visibility through backward integration into cathode precursor production and long-term offtake contracts with premium automotive OEMs. Sodium-ion chemistry emergence threatens 15-20% volume displacement in entry mobility segments. Priority levers include cylindrical format specialization for performance EVs and software-defined battery management systems that unbundle hardware from recurring service revenue. For New Entrants and Emerging Players: Enter via India's PLI scheme corridors in Tamil Nadu and Gujarat where 18% capex support reduces gigafactory entry barriers. Second-life stationary storage offers the most penetrable white-space, with retired automotive packs at 70-80% state-of-health repurposing for grid frequency regulation. Target direct cell procurement relationships with independent power producers in Texas and California bypassing traditional pack integrators. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated cell makers with captive cathode precursor supply given IRA domestic content bonus catalysts. Long-term viability favors producers with proven solid-state pilot line scale-up and automotive qualification timelines compressing toward three years. Acquisition target archetype: mid-cap specialists with dry electrode coating process validation and tier-one automotive safety certification. Signal to watch: GB standard compliance timeline acceleration for foreign entrants as MIIT streamlines NMPA validation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Production | Captive cobalt and nickel sulfate supply secures margin visibility under IRA domestic content rules. |
| Dry Electrode Coating Scale-Up | Solvent-free manufacturing reduces energy capex but requires requalification of 500-plus process parameters. |
| Long-Term Offtake Contract Execution | Premium automotive OEM partnerships embed suppliers deeper into vehicle platform development cycles. |
| Second-Life Stationary Storage Deployment | Retired automotive packs with 70-80% state-of-health create new revenue streams for OEMs with BMS data access. |
| Solid-State Pilot Line Qualification | Sulfide-based electrolyte production at Toyota and Samsung SDI compresses automotive qualification timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cell manufacturing executives, cathode precursor procurement leads, automotive platform engineers, grid-scale storage developers, and battery management system software architects combined with MIIT GB standard documentation, EU Battery Regulation impact assessments, and US IRA credit guidance. EIA electricity storage deployment databases, IEA critical mineral supply reports, and SEC 10-K filings from listed cell makers provided volume and value triangulation against bottom-up capacity buildout tracking.
Segment-level modeling ran at chemistry-technology-format granularity across the projection horizon. The analytical framework derived CAGRs from cell production capacity expansion trajectories, electric vehicle platform launch schedules, and grid-scale storage procurement pipelines. Chemistry splits incorporated LFP penetration curves for commercial transport, NMC 811 adoption in premium passenger EVs, and sodium-ion displacement floors for two-wheeler segments. Regional production clusters modeled IRA credit capture rates, EU carbon border adjustment exposure, and China dual carbon goal compliance costs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under solid-state electrolyte breakthrough acceleration or cathode precursor supply disruption scenarios. Assumptions reflect announced gigafactory commissioning schedules, offtake contract execution rates, and regulatory timeline adherence. EV fleet electrification policy shifts, F-Gas Regulation coolant phase-down enforcement, and GB standard foreign entrant certification delays warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
China SLI Battery Market