
 Europe Machine Vision Systems Market | 2026-2036
Europe Machine Vision Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Machine Vision Systems Market Foresight
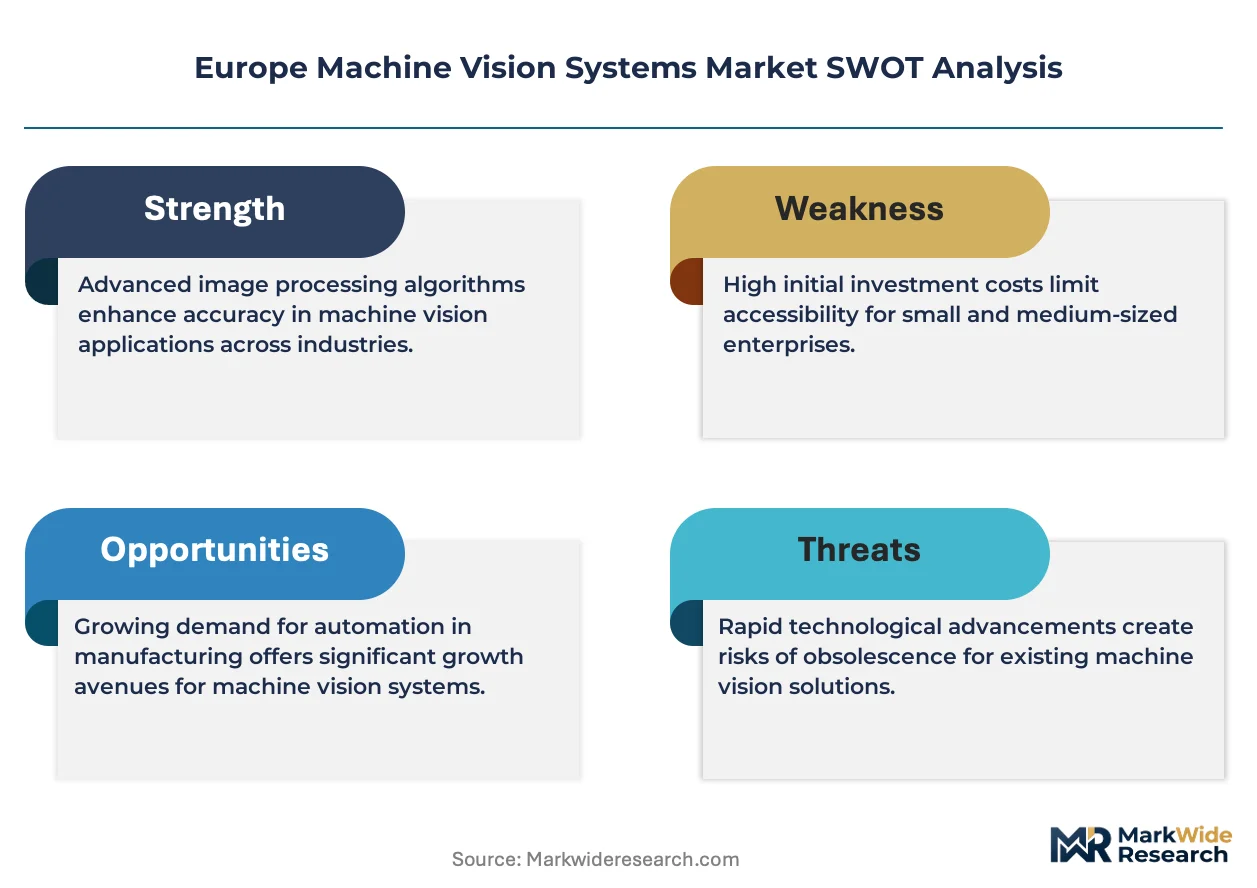
The capability gap between vertically integrated platform providers and component specialists is redrawing competitive boundaries across the Europe Machine Vision Systems landscape. Basler AG leverages its captive sensor design and German manufacturing footprint to dominate high-resolution camera supply for automotive tier ones. Cognex Corporation anchors its position through deep software libraries and application engineering density across Western European electronics hubs. IDS Imaging Development Systems GmbH competes on modular hardware architectures that let mid-size integrators customize without full platform commitments.
Europe machine vision systems encompass integrated hardware-software platforms that capture, process, and analyze visual data to automate inspection, guidance, and measurement tasks in industrial environments. These systems typically operate at frame rates exceeding 100 fps with resolutions from 1 to 25 megapixels, using CMOS sensors paired with LED or structured-light illumination to detect defects at micron-level precision in production lines. Cameras and sensors constitute the revenue core, though margin pools increasingly shift toward embedded software and AI-enabled analytics layers. 3D vision and smart camera segments are expanding fastest as robotics applications in automotive and electronics manufacturing require depth perception and edge-based decision-making without external PC tethering.
The EU AI Act and CE marking under the MDR impose conformity requirements that filter out uncertified vision systems from pharmaceutical and medical device production lines. REACH and RoHS constraints further shape component sourcing, restricting certain sensor coatings and cable sheathing materials that fail hazardous substance thresholds. ECHA substance evaluations and evolving F-Gas Regulation limits on cooling in high-performance computing clusters will force stakeholders to reassess thermal management architectures and supply chain chemistry through the forecast window.
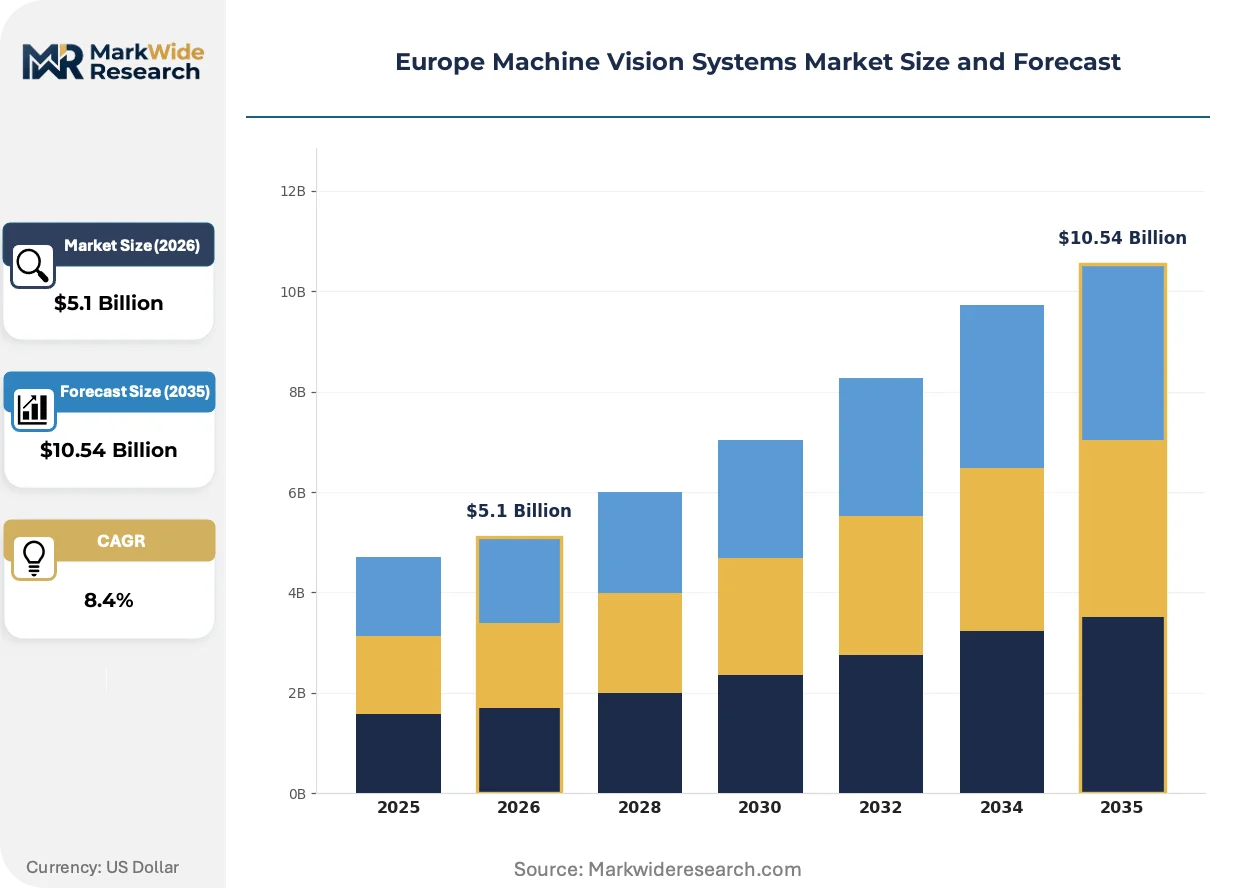
Market Dynamics
The EU AI Act's conformity requirements are filtering uncertified vision systems from pharmaceutical and medical device production lines, compressing vendor margins while accelerating consolidation around certified platform providers.
Growth Catalysts
- Automotive Robotics Integration:German and French manufacturers deploy 3D vision-guided systems for weld inspection and assembly verification, absorbing high-resolution camera output at scale.
- MDR CE Marking Mandate:Medical device manufacturers must validate inspection traceability, pulling certified machine vision into cleanroom environments across the Netherlands and Switzerland.
- Precision Engineering Cluster Density:Germany's industrial corridor concentrates demand for micron-level defect detection, creating procurement pull for CMOS sensors and structured-light modules.
Market Restraints
- Sensor Supply Concentration:CMOS image sensor fabrication concentrates in Asian foundries, exposing European integrators to lead-time volatility and currency fluctuation risk.
- REACH Chemical Restrictions:ECHA substance evaluations limit certain cable sheathing compounds and sensor coating materials, forcing reformulation of legacy hardware designs.
- High-Performance Cooling Constraints:Evolving F-Gas Regulation limits on thermal management fluids restrict edge-computing vision system architectures in high-throughput applications.
Strategic Opportunities
- Eastern European Manufacturing Uplift:Polish and Czech automotive electronics plants remain underpenetrated by 3D vision systems, offering first-mover positioning for integrators with localized service networks.
- AI-Enabled Edge Analytics:Convergence of embedded GPU acceleration and neural network optimization enables on-camera defect classification without external PC tethering.
- CSRD Reporting Alignment:Corporate Sustainability Reporting Directive disclosure requirements create demand for vision-based production monitoring to validate resource efficiency and waste reduction claims.
Industry Challenges
- Multidisciplinary Talent Scarcity:Integration projects require simultaneous expertise in optical physics, Python-based machine learning pipelines, and IEC 62443 cybersecurity standards.
- Legacy System Interoperability:Brownfield manufacturing environments run proprietary PLC protocols that resist seamless integration with modern GigE Vision and USB3 Vision camera interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Machine Vision Systems Market |
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Sensors, Frame Grabbers, Lighting Systems Application: Quality Control, Robotics, Identification, Measurement End User: Automotive, Electronics, Food & Beverage, Pharmaceuticals Technology: 2D Vision, 3D Vision, Smart Cameras, Laser Profiling |
| Companies Covered | IDS Imaging Development Systems GmbH, Keyence Corporation, Basler AG, Teledyne DALSA, Omron Corporation, SICK AG, MVTec Software GmbH, Baumer, Cognex Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Machine Vision Systems Market Shifts & Advancements
Computational architectures and conformity frameworks are actively compressing the hardware-software boundary, embedding intelligence at the point of image capture while regulatory pressure elevates traceability requirements.
Time-of-flight and structured-light 3D sensing is supplanting stereo vision in automotive body-in-white inspection. Tier one suppliers in Stuttgart and Wolfsburg adopt these modules for sub-millimeter gap-and-flush measurement. The shift compresses integration complexity while demanding higher thermal tolerance from embedded processors.
REACH substance restrictions and RoHS hazardous substance limits are forcing sensor manufacturers to reformulate die-attach materials and cable jacket compounds. Industrial camera vendors face extended qualification timelines for new hardware revisions. Medical device producers in Ireland and Denmark accelerate supplier audits to preempt compliance gaps.
After-sales service unbundling is fragmenting traditional platform sales. Mid-size integrators in Northern Italy and the Nordic region now procure cameras, lenses, and software licenses through separate channels rather than bundled system contracts. This pattern concentrates margin pressure on full-stack vendors while elevating specialist component suppliers.
Europe Machine Vision Systems Market Segmentation
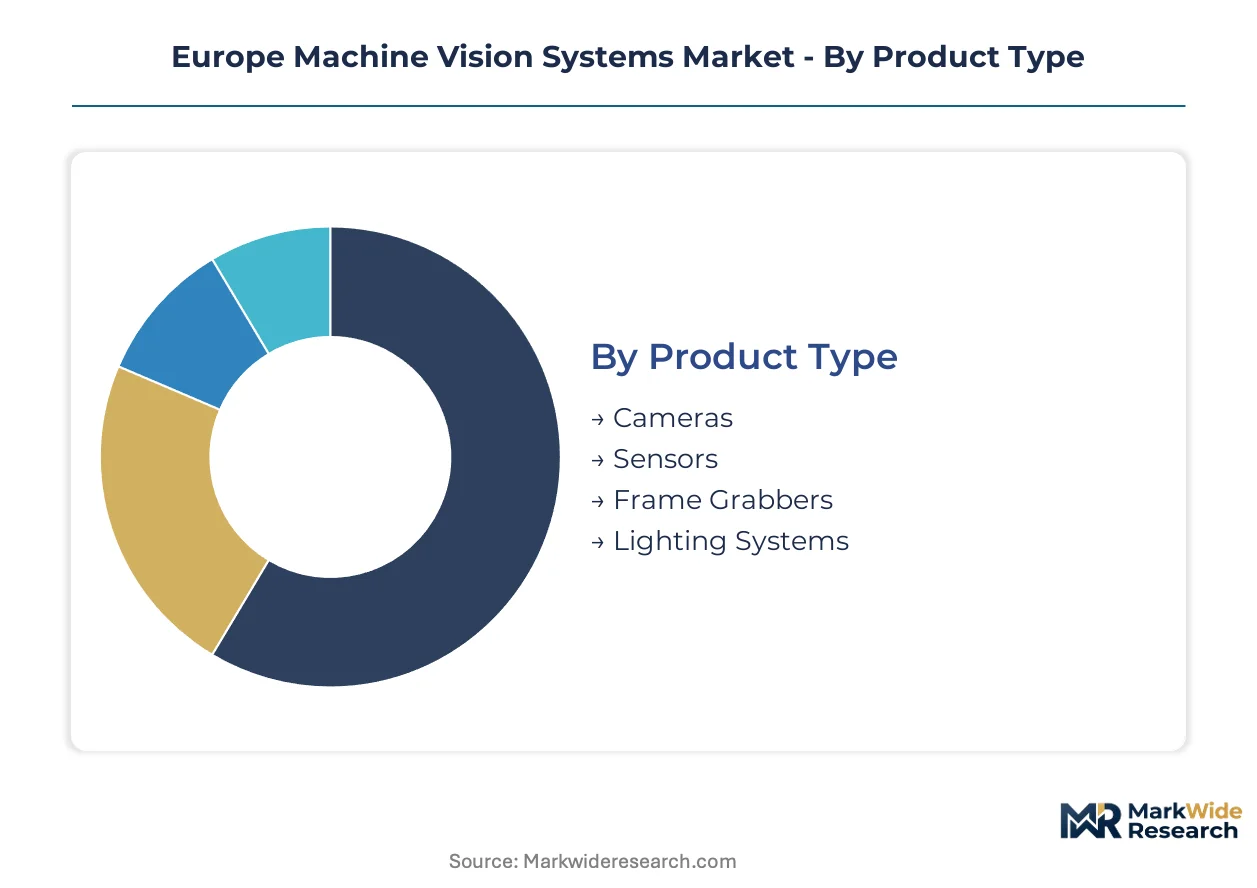
Machine vision segmentation in Europe reflects divergent compliance burdens and performance thresholds across industrial verticals. Product and technology choices cascade into certification requirements under the EU AI Act and MDR, creating procurement patterns that favor explainable, traceable system architectures.
Product Type:
REACH substance restrictions and RoHS hazardous substance limits differentiate component categories by reformulation burden and qualification timeline.
- Cameras:CMOS-based devices operating at 100-500 fps with resolutions spanning 1-25 megapixels constitute the revenue core. German automotive tier ones in Stuttgart and Wolfsburg absorb high-resolution GigE Vision and USB3 Vision units for body-in-white inspection, driven by sub-millimeter gap-and-flush measurement requirements.
- Sensors:Image sensors with captive design capabilities command premium positioning through supply security. Basler AG leverages in-house sensor development to bypass Asian foundry lead-time volatility that constrains European integrators dependent on external CMOS supply.
- Frame Grabbers:PCIe-based acquisition cards bridge high-bandwidth camera interfaces to host processors in multi-camera inspection stations.
- Lighting Systems:LED arrays and structured-light modules with RoHS-compliant housing materials face extended ECHA qualification cycles.
Cameras handle the majority of throughput; sensors are gaining share fastest through vertical integration strategies.
Application:
Cost tier stratification separates premium robotics integration from standardized quality control deployments.
- Quality Control:Surface defect detection and dimensional verification at micron-level precision dominates pharmaceutical cleanrooms in Ireland and Denmark. MDR CE marking mandates pull certified systems into medical device production lines where traceability documentation is non-negotiable.
- Robotics:3D vision-guided systems for weld inspection and assembly verification absorb the fastest-growing capital allocation. French and German manufacturers deploy these modules for depth-perception tasks that eliminate external PC tethering.
- Identification:Barcode and OCR systems for track-and-trace compliance in food and beverage packaging lines.
- Measurement:Metrology-grade sub-pixel accuracy systems for precision engineering clusters.
Quality control maintains the installed base; robotics is climbing the fastest on new project wins.
End User:
Customer type determines the severity of conformity requirements and the depth of application engineering support demanded.
- Automotive:Body-in-white inspection and powertrain assembly verification consume the highest camera density per production line. German manufacturers accelerate 3D vision deployment ahead of EU AI Act enforcement timelines for high-risk AI systems.
- Electronics:PCB inspection and semiconductor packaging verification in Dutch and Swiss facilities require cleanroom-compatible hardware with REACH-compliant cable sheathing.
- Food & Beverage:Hygienic design requirements and F-Gas Regulation constraints on cooling limit edge-computing architectures.
- Pharmaceuticals:MDR traceability mandates and EMA inspection protocols elevate software validation burdens above other verticals.
Automotive commands the largest procurement volumes; pharmaceuticals is expanding most quickly on compliance-driven replacement cycles.
Technology:
Maturity curves separate established 2D architectures from emerging 3D and edge-AI modalities.
- 2D Vision:Area-scan and line-scan configurations with established GigE Vision interoperability dominate legacy installations. Brownfield manufacturing environments in Northern Italy rely on these systems despite proprietary PLC protocol friction.
- 3D Vision:Time-of-flight and structured-light modules displace stereo vision in automotive gap-and-flush measurement. Thermal tolerance demands from embedded processors compress integration complexity while extending hardware qualification timelines.
- Smart Cameras:Edge-based decision-making with embedded GPU acceleration eliminates external PC dependency for mid-size integrators.
- Laser Profiling:Triangulation-based height measurement for high-speed production monitoring.
2D vision retains the installed base dominance; 3D vision shows the steepest expansion trajectory on robotics integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's machine vision trade flows reflect a structural deficit in CMOS sensor fabrication against surplus positions in camera assembly and software development. Import dependency on Asian foundries for image sensors contrasts with export strength in high-resolution GigE Vision units and embedded analytics platforms.
Germany
Automotive body-in-white inspection and powertrain assembly verification absorb the densest camera deployment per production line in Europe. The EU AI Act's high-risk system classification accelerates certification timelines for Stuttgart and Wolfsburg facilities. Precision engineering clusters along the Baden-Württemberg industrial corridor concentrate procurement for micron-level defect detection systems.
France
Robotics integration for weld inspection and gap-and-flush measurement drives 3D vision capital allocation among tier one suppliers. REACH substance restrictions under ECHA oversight force reformulation of cable sheathing compounds in legacy hardware designs. The Auvergne-Rhône-Alpes manufacturing belt anchors deployment of structured-light modules for automotive assembly verification.
Netherlands
Semiconductor packaging and PCB inspection facilities demand cleanroom-compatible hardware with RoHS-compliant materials. MDR CE marking mandates pull certified vision systems into medical device production lines across Eindhoven. Philips legacy ecosystems and ASML supplier networks concentrate application engineering expertise in the Brabant region.
Switzerland
Swissmedic regulatory protocols and MDR traceability requirements elevate software validation burdens above neighboring markets. Precision metrology and pharmaceutical cleanroom applications dominate procurement in Basel and Zurich clusters. Medical device manufacturers accelerate supplier audits to preempt compliance gaps under evolving EMA inspection standards.
Poland
Automotive electronics plants in the Silesian and Greater Poland voivodeships remain underpenetrated by 3D vision systems relative to German benchmarks. EU structural funds and automotive OEM supplier migration create first-mover positioning for integrators building localized service networks. Warsaw and Krakow emerging as secondary hubs for vision system integration support.
Europe Machine Vision Systems Market Competitive Landscape
Concentration sits with vertically integrated camera specialists and deep-software platform providers that control captive sensor supply or application engineering density. The vendor base stratifies across three tiers: full-stack platform vendors bundling hardware-software-service contracts, modular component suppliers enabling mid-size integrator customization, and regional system integrators with localized deployment capabilities. Consolidation pressure intensifies as REACH compliance costs and EU AI Act certification requirements filter out sub-scale competitors. M&A activity targets software libraries and embedded AI acceleration IP; strategic partnerships link Asian sensor foundries with European camera assemblers to secure supply.
Within the German industrial optics cluster, Basler AG and SICK AG exemplify vertically integrated archetypes with captive manufacturing footprints, while Cognex Corporation anchors the deep-software platform tier through application engineering density across Western European electronics hubs. IDS Imaging Development Systems GmbH occupies a modular specialist position that lets mid-size integrators customize without full platform commitments. These three patterns—captive manufacturing, software-centric platforming, and modular openness—capture the competitive structure reshaping procurement relationships.
| Leading Market Players |
|---|
| IDS Imaging Development Systems GmbH |
| Keyence Corporation |
| Basler AG |
| Teledyne DALSA |
| Omron Corporation |
| SICK AG |
| MVTec Software GmbH |
| Baumer |
| Cognex Corporation |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with Asian foundries lock in CMOS sensor supply for German camera assemblers while fixing unit costs against euro-yen volatility. This contract structure bundles volume commitments with price visibility, compressing margin risk for European integrators exposed to REACH reformulation cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under the EU AI Act and MDR CE marking tiers separate premium explainable systems from standard inspection hardware, while volume scale drives economy-tier procurement for high-volume automotive lines. Cost compression in the economy tier is intensifying because after-sales service unbundling lets mid-size integrators source components through separate channels. Tier one automotive manufacturers show lowest price sensitivity; mid-size electronics integrators in Northern Italy exhibit highest sensitivity to per-unit camera costs.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port complexes expose European camera assemblers to container availability swings on Asia-Europe trade lanes. CMOS image sensor fabrication concentrates in Taiwan, South Korea, and Japan, while camera assembly and embedded software development center on Germany and Switzerland. European integrators draw from Asian foundries for sensors, German optics clusters for lenses, and RoHS-compliant cable suppliers in Eastern Europe. Single-source vulnerability in 12-inch wafer capacity represents the dominant structural risk. Distribution runs through authorized integrator networks and direct OEM contracts rather than commodity wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification creates a regulatory inflection that will filter uncertified vendors from pharmaceutical and automotive production lines, compressing competitive windows for platform providers.
For Market Incumbents: Secure captive sensor supply through backward integration or long-term foundry partnerships to bypass Asian lead-time volatility threatening German automotive tier ones. Deepen application engineering density in Swiss pharmaceutical clusters where MDR traceability mandates elevate switching costs. Lock in certification investment ahead of EU AI Act enforcement timelines to filter emerging competitors from high-margin medical device inspection contracts. For New Entrants and Emerging Players: Lead with modular hardware architectures targeting Polish and Czech automotive electronics plants where 3D vision penetration lags German benchmarks by significant margins. Build localized service networks in Warsaw and Krakow to capture EU structural fund inflows. Position against bundled platform vendors by unbundling camera, software, and maintenance procurement for mid-size integrators seeking customization without full-stack commitments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-centric platform providers with embedded AI acceleration IP and subscription-based analytics layers. Long-term viability across the projection horizon rests on regulatory certification moats rather than hardware scale alone. Acquisition targets should show EU AI Act conformity progress and cleanroom-compatible product lines. Watch for ECHA substance evaluation announcements that could force hardware redesigns and consolidation pressure on sub-scale component vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Preemptive conformity spending locks out uncertified competitors from Stuttgart automotive lines. |
| Backward Integration into Sensor Design | In-house CMOS development insulates Basler AG and SICK AG from Asian foundry lead-time volatility. |
| Localized Service Network Expansion | Polish and Czech automotive electronics plants remain underpenetrated relative to German benchmarks. |
| Embedded AI Acceleration Acquisition | On-camera neural network processing eliminates external PC dependency for mid-size integrators. |
| REACH-Compliant Material Reformulation | RoHS-compliant cable sheathing and die-attach materials preempt ECHA qualification timeline extensions. |
Research Methodology
Desk research of ECHA substance evaluation databases, EU AI Act draft implementing acts, and MDR technical documentation standards preceded structured interviews with automotive tier one procurement directors, pharmaceutical cleanroom engineering leads, machine vision system integrators, and EMA regulatory affairs specialists. Primary fieldwork across Stuttgart, Wolfsburg, Eindhoven, and Basel clusters combined with secondary validation against SEC filings of listed component vendors and trade flow data from Eurostat. Bottom-up unit economics triangulated against top-down market sizing across camera, sensor, and software revenue pools.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects and regulatory compliance cost pass-through. Segmentation dimensions modeled include product architecture, application vertical, end-user industry, technology modality, and regional regulatory cluster. CAGRs derive from installed base growth rates and replacement cycle compression under MDR and EU AI Act timelines. Forecast inputs incorporate automotive production forecasts for German body-in-white lines and semiconductor packaging capacity expansion in Dutch Brabant region.
Forecasts assume regulatory continuity in EU AI Act implementation and MDR CE marking protocols; material policy shifts would require re-modeling of certification timeline assumptions and compliance cost burdens. Specific risk factors include ECHA substance restriction expansions, F-Gas Regulation cooling limits on edge computing architectures, and Asian foundry capacity constraints. Practitioners should keep alternative scenarios live as REACH reformulation cycles and EU AI Act enforcement granularity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Phosphor Screen Scanner Market
Imaging
Wide Field Imaging Devices Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Europe CT Market
Imaging
Video Capture Card Market
Imaging
Medical X-Ray Detectors Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Mobile Imaging Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Computational Photography Market
Imaging
Microscope Digital Cameras Market
Imaging
Handheld Retinal Scanners Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Global Digital Photo Frame Market
Imaging
Smart Camera Market