
 Europe Military Unmanned Vehicles Market | 2026-2036
Europe Military Unmanned Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Military Unmanned Vehicles Market Foresight
Multi-source procurement for unmanned vehicle subsystems is expanding across European defense ministries. Rheinmetall AG leverages its domestic manufacturing base to anchor ground system supply chains for the Bundeswehr. Leonardo S.p.A. competes through specialized unmanned aerial platforms designed for Mediterranean operational environments. BAE Systems plc sustains long-term integration contracts with the UK Ministry of Defence for autonomous combat support programs.
Europe Military Unmanned Vehicles comprise robotic platforms operating across air, ground, and maritime domains without onboard human pilots, typically integrating sensor payloads exceeding 50 kilograms and satellite communication links for beyond-line-of-sight command. These systems perform intelligence collection, force protection, and precision strike coordination for state military operators. Remotely Piloted Aircraft still occupies the dominant value share due to established ISR program budgets in France and Italy. Unmanned Ground Systems represent the fastest-expanding category as Baltic and Eastern European states prioritize mine-clearing and logistics automation. AI-Driven Navigation concentrates margin pools where national security clearances restrict vendor participation to Thales Group and QinetiQ.
The EU AI Act imposes risk-classification requirements on autonomous targeting algorithms, compelling manufacturers to document human oversight protocols before platform deployment. EDA coordination frameworks harmonize interoperability standards for cross-border NATO unmanned operations, while national regulators in Germany and France maintain separate military AI ethics review boards. Procurement officers must weigh Brussels compliance timelines against accelerated national rearmament schedules when qualifying new unmanned vehicle suppliers.
Market Dynamics
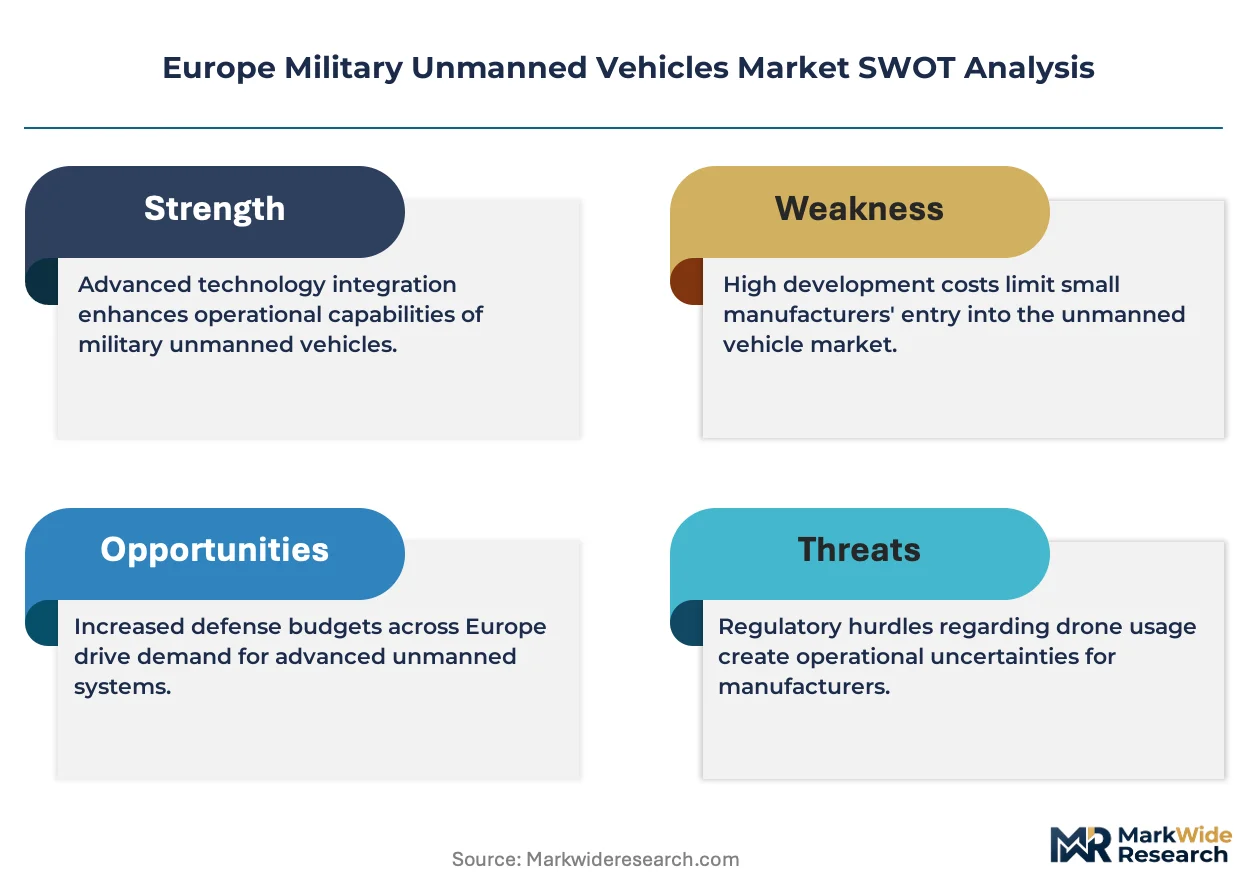
The EU AI Act is forcing defense contractors to re-architect autonomous targeting systems around documented human-in-the-loop protocols, compressing development timelines while elevating compliance costs for unmanned vehicle programs across NATO Europe.
Growth Catalysts
- Baltic Mine-Clearing Mandates:Estonia, Latvia, and Lithuania are accelerating unmanned ground vehicle acquisitions for explosive ordnance disposal along their eastern borders.
- REACH Compliance for Sensor Materials:Restrictions on hazardous substances in electronic components are driving substitution toward gallium nitride-based radar arrays with superior thermal performance.
- Beyond-Line-of-Sight Satcom:NATO's IRIS² constellation deployment enables encrypted command links for unmanned platforms operating in contested electromagnetic environments.
Market Restraints
- Gallium Supply Concentration:China controls approximately 90% of global gallium refining capacity, creating input vulnerability for European semiconductor fabrication.
- Dual-Use Export Control Friction:Germany's KBA and France's ANSM maintain divergent interpretations of EU dual-use regulations, fragmenting cross-border component flows.
- Swarm Coordination Limitations:Current mesh networking protocols fail above 50-unit formations, capping operational scalability for distributed unmanned systems.
Strategic Opportunities
- Polish Unmanned Maritime Gap:Poland's naval modernization program lacks indigenous underwater vehicle capacity, opening procurement windows for foreign platform integrators.
- Swarm-AI Convergence:Federated learning architectures combined with edge computing enable decentralized threat assessment without continuous uplink dependency.
- EDA Cross-Border Maintenance:The European Defence Agency's pooled logistics framework creates shared service infrastructure for unmanned fleet sustainment.
Industry Challenges
- AI Ethics Certification Bottlenecks:Germany's military AI ethics review board and France's parallel national process impose redundant validation stages on algorithm deployment.
- Legacy C2 Integration Complexity:NATO's STANAG 4586 interoperability standard requires extensive middleware development to connect autonomous platforms with 1990s-era command systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Military Unmanned Vehicles Market |
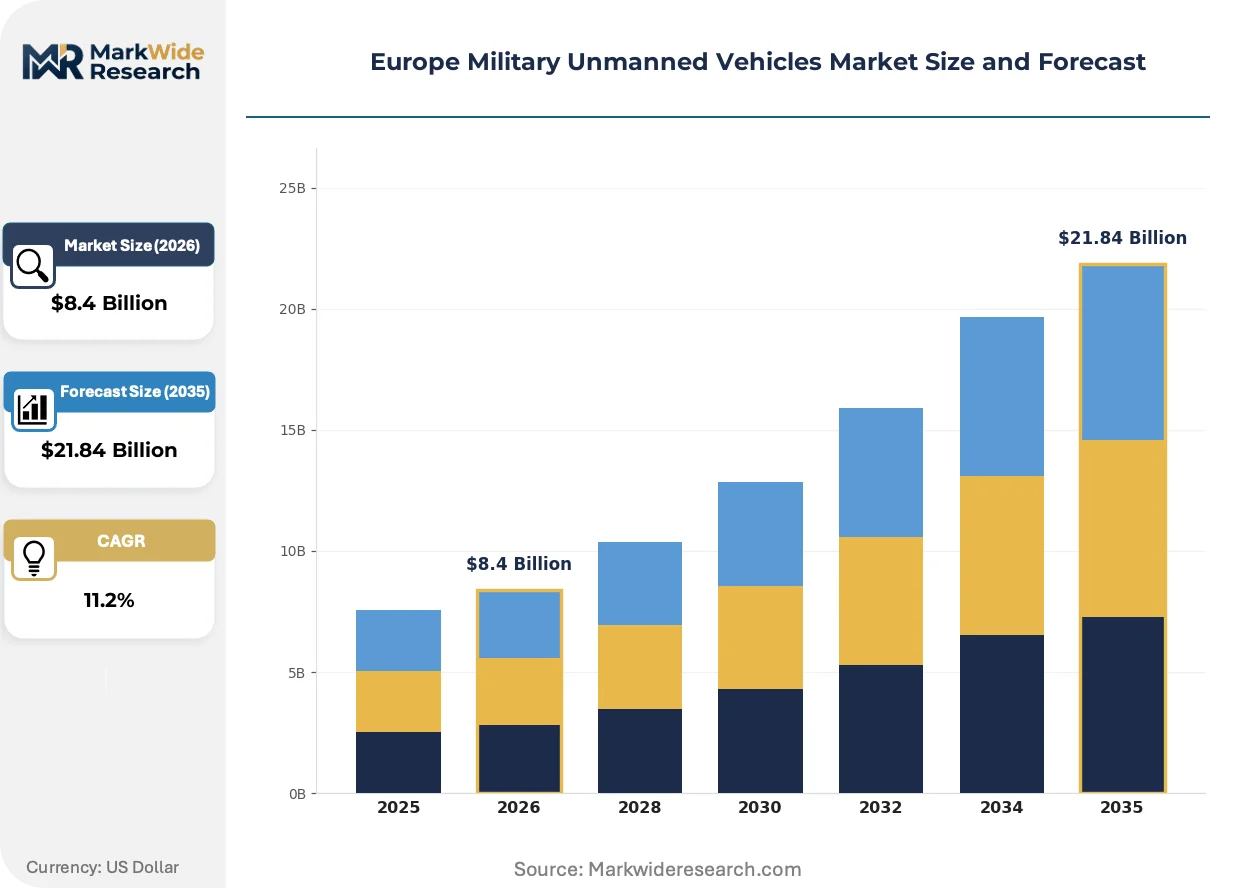
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $21.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Remotely Piloted Aircraft, Unmanned Ground Systems, Autonomous Underwater Vehicles, Tactical Drones End User: Armed Forces, Defense Contractors, Government Agencies, Research Institutions Application: Surveillance, Reconnaissance, Search and Rescue, Combat Support Technology: AI-Driven Navigation, Sensor Fusion, Communication Systems, Autonomous Operations |
| Companies Covered | Thales Group, BAE Systems plc, Leonardo S.p.A., Rheinmetall AG, Saab AB, Airbus SE, Milrem Robotics, Kongsberg Gruppen, QinetiQ, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Military Unmanned Vehicles Market Shifts & Advancements
Autonomous navigation architectures are electrifying platform design priorities across European defense procurement, displacing legacy teleoperation dependencies while compressing operator-to-vehicle ratios in fielded systems.
Hybrid-electric propulsion is electrifying endurance parameters for tactical unmanned aerial platforms. The Bundeswehr's KZO and LUNA program offices are specifying battery-dominant powertrains for 8-hour mission profiles. This electrification is compressing logistics tail requirements and enabling forward deployment without aviation fuel resupply chains.
The EU AI Act's risk-classification framework for autonomous weapon systems is mandating algorithmic transparency documentation before platform certification. Defense ministries in France and Italy are requiring vendors to submit decision-audit trails for targeting software. Remotely piloted aircraft programs face extended qualification timelines as manufacturers implement human-oversight verification protocols.
Swedish and Finnish defense procurement offices are consolidating unmanned vehicle acquisitions through framework agreements rather than individual tenders. This buyer concentration is displacing fragmented national purchasing and forcing suppliers to commit to multi-year availability guarantees. The model is most visible in Nordic-Baltic cooperative procurement for ground-based counter-UAS systems.
Europe Military Unmanned Vehicles Market Segmentation
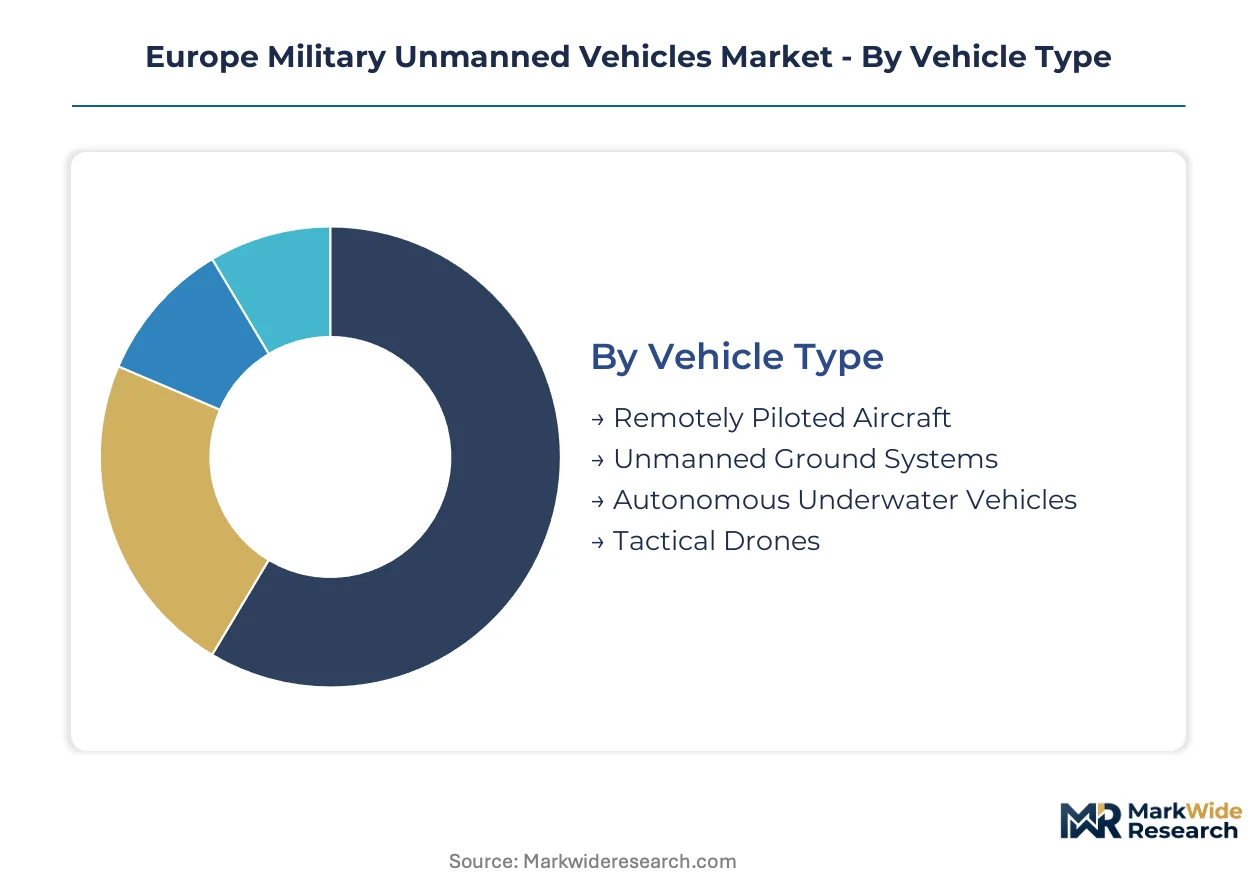
Segmentation in Europe Military Unmanned Vehicles reveals how procurement priorities diverge across NATO member states. Vehicle type classifications determine budget allocation between aerial dominance and ground force modernization. Technology segmentation increasingly shapes vendor qualification under EU AI Act compliance frameworks.
Vehicle Type:
Integration depth varies sharply across vehicle categories, with some platforms operating as standalone mission systems while others embed as force-multiplier subsystems within combined arms formations.
- Remotely Piloted Aircraft:These fixed-wing and rotary platforms carry electro-optical and signals intelligence payloads exceeding 50 kilograms for persistent ISR coverage. French and Italian defense ministries anchor procurement volumes through established program offices at DGA and Segredifesa. Budget concentration here reflects legacy investment paths and proven beyond-line-of-sight satellite link architectures.
- Unmanned Ground Systems:Robotic platforms for logistics transport, mine clearance, and perimeter security operate through teleoperation or supervised autonomy. Baltic states—Estonia, Latvia, and Lithuania—prioritize explosive ordnance disposal variants for eastern border fortification. NATO's IRIS² constellation expansion enables encrypted command links for these ground assets in contested electromagnetic environments.
- Autonomous Underwater Vehicles:Subsurface platforms for mine countermeasures and seabed infrastructure inspection deploy from surface vessels or coastal stations.
- Tactical Drones:Short-range rotary and fixed-wing systems for platoon-level reconnaissance operate below 150 meters altitude with limited endurance.
Volume placements concentrate in Remotely Piloted Aircraft; the faster expansion belongs to Unmanned Ground Systems.
End User:
Customer type segmentation tracks procurement authority concentration versus distributed acquisition patterns across European defense structures.
- Armed Forces:National military services in Germany, France, and the United Kingdom wield centralized procurement authority for platform-level acquisitions. Bundeswehr program offices specify technical requirements through BAAINBw, while UK Strategic Command consolidates unmanned system roadmaps across service branches. Budget scale here determines vendor qualification timelines and certification investment thresholds.
- Defense Contractors:Prime integrators and subsystem suppliers purchase unmanned platforms for technology demonstration, training, and foreign military sales support. Rheinmetall AG and Leonardo S.p.A. maintain internal fleets for customer validation and iterative design refinement. Procurement flexibility allows rapid prototyping outside formal government tender cycles.
- Government Agencies:Border guard services, coast guards, and national gendarmerie forces acquire dual-use platforms adapted from military specifications.
- Research Institutions:Universities and defense research establishments source experimental platforms for algorithm development and operational concept validation.
Platform volumes flow predominantly to Armed Forces; steepest expansion trajectory sits with Defense Contractors building demonstration capabilities.
Application:
Mission purpose segmentation distinguishes intelligence-gathering systems from those designed for direct force application or humanitarian support roles.
- Surveillance:Persistent wide-area motion imagery and electronic intelligence collection dominate fleet utilization hours. French Harfang and British Watchkeeper programs exemplify dedicated surveillance architectures with multi-sensor fusion. Demand concentrates where territorial monitoring requirements exceed manned aviation endurance limits.
- Reconnaissance:Target identification and battle damage assessment missions require maneuverable platforms with high-resolution payload packages. German KZO and LUNA systems integrate laser designators for precision strike coordination. Operational tempo here drives sensor refresh cycles and platform attrition replacement rates.
- Search and Rescue:Platforms equipped with thermal imaging and emergency beacon detection support disaster response and personnel recovery.
- Combat Support:Ammunition resupply, electronic warfare, and loitering munition delivery extend unmanned utility into contested airspace.
Surveillance claims the dominant placement volume; Combat Support is climbing the fastest as rules of engagement evolve.
Technology:
Technology segmentation maps capability layers from foundational navigation to mission-level autonomy, with regulatory scrutiny intensifying at higher automation tiers.
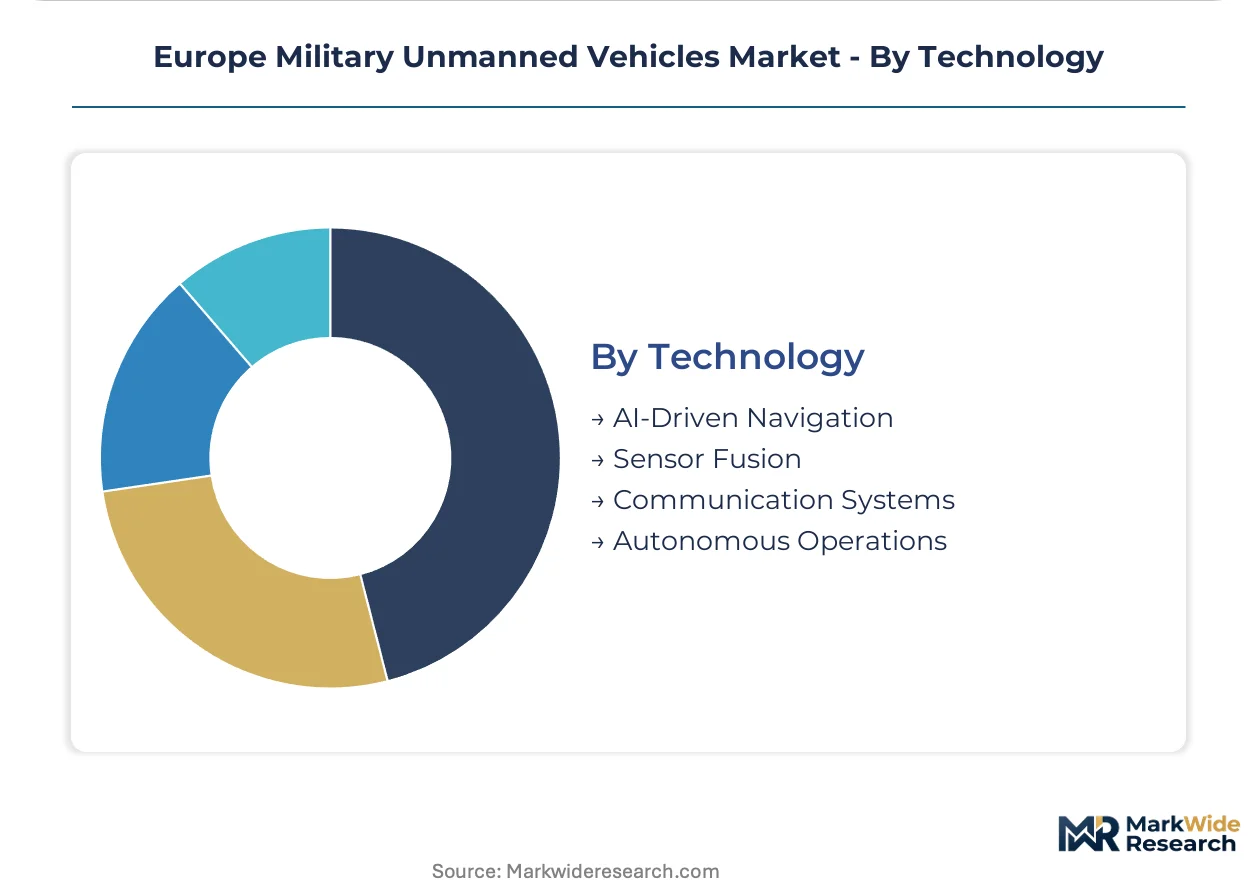
- AI-Driven Navigation:Machine learning-based path planning and obstacle avoidance reduce operator workload while enabling operations in GPS-denied environments. Thales Group and QinetiQ hold restricted access to national security-cleared algorithm development for European defense customers. EU AI Act risk classification imposes documentation burdens on targeting software integration.
- Sensor Fusion:Multi-spectral payload integration combines electro-optical, infrared, and synthetic aperture radar outputs into unified tactical pictures. Gallium nitride array adoption accelerates under REACH compliance pressure for hazardous substance reduction. Thermal performance gains justify substitution costs for prime integrators.
- Communication Systems:Beyond-line-of-sight datalinks and mesh networking protocols enable distributed command architectures.
- Autonomous Operations:Supervised and fully autonomous mission execution modes reduce human-in-the-loop dependency for predictable task sets.
Sensor Fusion attracts the dominant placement volume; AI-Driven Navigation is gaining share fastest as ethics certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium refining concentration in China shapes European semiconductor supply security for unmanned vehicle sensor arrays. Defense procurement offices from Tallinn to Paris navigate this dependency while accelerating domestic platform integration.
Germany
Bundeswehr program offices at BAAINBw drive unmanned ground system acquisitions for Baltic deployment scenarios. The KBA maintains divergent dual-use export interpretations that fragment cross-border component flows with French suppliers. Rheinmetall AG anchors industrial capacity in Düsseldorf, securing Bundeswehr logistics automation contracts.
France
DGA program offices prioritize persistent ISR coverage through established Harfang and Patroller fleets for Sahel and Eastern European operations. ANSM maintains parallel military AI ethics review processes that extend algorithm certification timelines beyond Brussels compliance schedules. Thales Group concentrates cleared algorithm development in the Paris-Saclay cluster.
United Kingdom
UK Strategic Command consolidates unmanned system roadmaps across service branches with Watchkeeper and Protector programs anchoring procurement volume. The national military AI ethics framework imposes documentation burdens on targeting software integration. BAE Systems plc sustains integration contracts from its Lancashire engineering base.
Poland
Naval modernization programs expose an indigenous underwater vehicle capacity gap that foreign platform integrators target. The national defense ministry accelerates procurement timelines outside EU coordination frameworks. Baltic Sea port infrastructure in Gdynia and Gdańsk supports unmanned maritime system testing.
Sweden
Försvarsmakten consolidates acquisitions through framework agreements with Finland for Nordic-Baltic cooperative procurement. The Swedish Defence Materiel Administration prioritizes ground-based counter-UAS systems for archipelago defense. Saab AB anchors sensor fusion development in Linköping.
Europe Military Unmanned Vehicles Market Competitive Landscape
Global majors compete with regional champions across certification and national security clearance dimensions. The vendor base stratifies between prime integrators holding long-term ministry contracts and mid-tier specialists capturing subsystem niches. Three archetypes dominate: cleared algorithm developers with restricted national access, platform integrators with established program office relationships, and component suppliers leveraging dual-use technology transfer. Competitive positioning depends on securing EDA interoperability certifications and navigating redundant national ethics review processes.
Among France-based defense conglomerates, Thales Group exemplifies the cleared algorithm developer archetype with restricted national security access. Leonardo S.p.A. represents Italian platform specialization for Mediterranean operational environments. Rheinmetall AG anchors German ground system manufacturing capacity for Bundeswehr logistics programs. These three occupy positions defined by national procurement anchoring rather than cross-border market contestability.
| Leading Market Players |
|---|
| Thales Group |
| BAE Systems plc |
| Leonardo S.p.A. |
| Rheinmetall AG |
| Saab AB |
| Airbus SE |
| Milrem Robotics |
| Kongsberg Gruppen |
| QinetiQ |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU AI Act-compliant platforms and legacy teleoperated systems manifests in both procurement premiums and supplier qualification timelines. Defense ministries in France and Germany pay substantial uplifts for algorithm-audited unmanned ground vehicles while relegating non-compliant systems to training fleets. This bifurcation concentrates margin pools with Thales Group and QinetiQ while compressing pricing power for component suppliers lacking security clearances.
Pricing Analysis
Warranty bundling separates full-life-cycle contracts from bare platform sales across European defense procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with AI-ethics-audited command systems commanding substantial premiums over teleoperated alternatives. Price differentiation hinges on REACH-compliant sensor materials and national security clearance tiers for algorithm developers. Cost compression in standard-tier ground systems is intensifying because Baltic states prioritize mine-clearing volume over advanced autonomy. Government agencies exhibit highest price sensitivity; armed forces program offices show lowest sensitivity due to multi-year budget commitments.
Supply Chain Analysis
Gallium nitride wafer supply rests on Chinese refining dominance and Taiwanese semiconductor fabrication capacity. European unmanned vehicle production draws from German precision optics, French radar arrays, and Italian composite airframes. Single-source vulnerability concentrates in rare earth processing and encrypted satellite communication modules. Distribution runs through prime integrator-direct ministry relationships with limited aftermarket channel development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into gallium nitride sensor fabrication and captive algorithm development capabilities is becoming the decisive competitive moat as EU AI Act compliance timelines compress. Players securing upstream control over semiconductor inputs and cleared AI engineering talent will capture margin expansion unavailable to assembly-focused competitors.
For Market Incumbents: Deepen security-cleared algorithm development partnerships with French ANSM and German military AI ethics boards before competitor qualification windows close. Expand in-house gallium nitride array production to offset Chinese supply concentration. Incumbents must anchor Bundeswehr and DGA program office relationships through multi-year availability guarantees as Nordic-Baltic cooperative procurement consolidates buyer power. For New Entrants and Emerging Players: Launch via Polish naval modernization channels for unmanned underwater vehicle integration opportunities outside established Franco-German supply chains. Poland's indigenous capacity gap in maritime platforms offers the most penetrable entry vector for foreign platform integrators. Target EDA interoperability certification as the essential qualification threshold for cross-border NATO procurement eligibility. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier sensor fusion specialists given REACH compliance acceleration and gallium nitride substitution mandates. Long-term viability favors acquisition targets holding dual-use technology transfer licenses and established relationships with BAAINBw or UK Strategic Command. Watch IRIS² constellation deployment schedules as the critical inflection indicator for beyond-line-of-sight command link demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| AI Ethics Certification Investment | ANSM and German military AI board compliance unlocks French and German program office access. |
| Gallium Nitride Backward Integration | Captive sensor array production insulates margins from Chinese refining concentration risks. |
| EDA Interoperability Certification | STANAG 4586 compliance enables cross-border NATO unmanned fleet operations and pooled logistics. |
| Nordic-Baltic Framework Agreement Entry | Swedish-Finnish cooperative procurement consolidation demands multi-year availability commitments. |
| IRIS² Satellite Link Integration | NATO encrypted constellation connectivity differentiates platforms for contested electromagnetic environments. |
Research Methodology
Independent corroboration across defense procurement officers at BAAINBw and DGA, prime integrator program managers at Rheinmetall and Leonardo, and EDA coordination staff underwrites the qualitative findings. Primary fieldwork encompassed structured interviews with Bundeswehr capability development leads, French AI ethics review board administrators, and UK Strategic Command unmanned systems directors. Secondary validation drew from EU defense procurement databases, NATO STANAG documentation, and national military AI governance frameworks. Bottom-up platform deployment estimates and top-down defense budget allocation analysis were cross-referenced for triangulation.
Comparable historical procurement cycles from the KZO and Harfang program offices anchored the forecast window against projected rearmament timelines. The analytical framework modeled vehicle type, end user authority concentration, mission application, and technology automation tier across the projection horizon. CAGRs were derived from defense budget trajectory analysis and platform replacement rate assumptions. Forecast inputs incorporated EU AI Act implementation schedules and IRIS² constellation deployment phases.
Regulatory delay, gallium supply disruption, and swarm coordination protocol limitations are the dominant revision risks for unmanned vehicle deployment timelines. Forecasts reflect documented assumptions regarding NATO interoperability harmonization and national ethics review process convergence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Autonomous Aircraft Software Market