
 Drone-In-A-Box Solutions Market | 2026-2036
Drone-In-A-Box Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Drone-In-A-Box Solutions Market Analysis
The performance gap between premium autonomous docking systems and commodity drone enclosures is broadening. Airobotics anchors the high end with fully integrated robotic swapping and weather-hardened shelters. Percepto competes through AI-driven analytics layered atop its hardware stack. Easy Aerial occupies the mid-market with rapid-deploy trailer systems for defense and public safety clients.
Drone-in-a-box solutions combine self-contained landing stations with automated battery exchange or charging, enabling repeated unmanned missions without human intervention. Typical enclosures integrate climate control, precision landing aids, and secure communications to sustain 24/7 operational readiness across remote infrastructure sites. Multi-rotor configurations dominate current deployments due to vertical takeoff flexibility and lower site preparation costs, while hybrid platforms are gaining traction where extended range and payload capacity outweigh acquisition premiums. Cloud-based deployment models concentrate margin pools through recurring software subscriptions and over-the-air fleet updates.
FAA Part 107 waivers and EASA specific-category certifications shape product roadmaps by mandating detect-and-avoid and command-link redundancy for beyond-visual-line-of-sight operations. Australia's CASA remote aircraft licensing framework and ISO 21384-3 unmanned aircraft system standards further constrain design choices for vendors targeting multi-jurisdiction sales. Stakeholders must track which regulators relax altitude and operational-volume restrictions first, as those markets will absorb disproportionate early deployment scale.
Market Dynamics
The drone-in-a-box market pivots on regulatory clearance velocity for beyond-visual-line-of-sight operations, with FAA and EASA waiver processing timelines determining fleet deployment schedules for utility and energy infrastructure operators.
Growth Catalysts
- BVLOS regulatory frameworks:FAA Part 107 waivers and EASA specific-category certifications enable automated inspection missions over pipelines and transmission corridors without human observers.
- Cloud-based fleet orchestration:Remote software platforms allow centralized control of distributed docking stations across solar farms and wind installations, reducing per-site labor overhead.
- Utility asset digitization:North American grid operators deploy autonomous systems to map vegetation encroachment and thermal anomalies on high-voltage lines.
Market Restraints
- Detect-and-avoid hardware costs:Mandatory onboard radar and optical sensors for BVLOS compliance add substantial unit costs to multi-rotor platforms.
- Precision component supply concentration:High-grade gimbal motors and solid-state lidar modules concentrate among Japanese and German component suppliers, creating single-source vulnerabilities.
- Weather-hardening requirements:Extended operational temperature ranges and IP-rated sealing specifications for desert and arctic deployments inflate enclosure manufacturing complexity.
Strategic Opportunities
- Defense rapid-deploy contracts:Trailer-mounted systems with minimal site preparation requirements address expeditionary force needs for perimeter surveillance and convoy route reconnaissance.
- EU Green Deal alignment:Renewable energy inspection mandates under the European Commission's sustainable finance taxonomy create procurement pull for automated solar and offshore wind monitoring.
- 5G network slicing integration:Ultra-reliable low-latency communication channels enable real-time video analytics and command-link redundancy without dedicated radio hardware.
Industry Challenges
- Embedded systems engineering scarcity:Firmware developers with simultaneous expertise in flight control algorithms and industrial IoT security protocols command premium compensation and extended recruitment cycles.
- Multi-jurisdiction certification complexity:Vendors targeting simultaneous FAA, EASA, and CASA approvals face divergent test documentation standards and conflicting airworthiness interpretation.
- Legacy SCADA integration friction:Docking station telemetry protocols require custom middleware development to interface with decades-old utility control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone-In-A-Box Solutions Market |
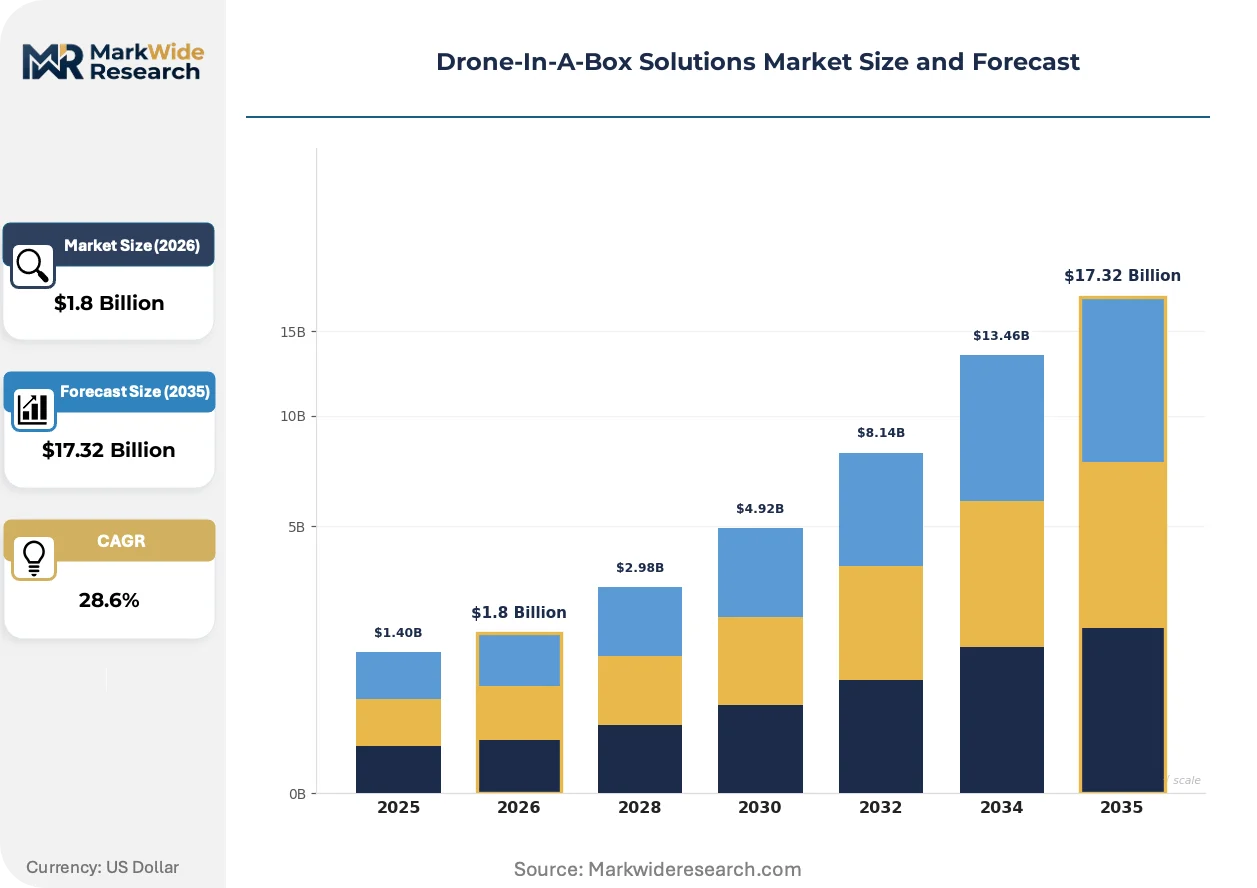
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multi-Rotor Drones, Hybrid Drones, Nano Drones Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Agriculture, Logistics, Infrastructure, Surveillance Application: Delivery Services, Mapping & Surveying, Emergency Response, Inspection |
| Companies Covered | Airobotics, American Robotics, Percepto, Azur Drones, Easy Aerial, Asylon, Atlas Dynamics, Antwork, H3 Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone-In-A-Box Solutions Market Emerging Trajectories
Autonomous docking hardware is converging with edge computing and predictive maintenance software, compressing the traditional separation between physical infrastructure inspection and digital asset management platforms.
Robotic battery swapping mechanisms are unifying charging logistics with payload reconfiguration capabilities. Mining conglomerates in Western Australia adopt these systems for continuous volumetric surveying of open-pit operations. The technology is unifying previously separate maintenance schedules for aircraft and ground infrastructure into single automated workflows.
EASA's specific-category certification pathway for unmanned aircraft systems is accelerating product roadmaps for vendors seeking European utility contracts. The framework mandates command-link redundancy and contingency management systems that exceed prior voluntary standards. German transmission grid operators now require these certifications as baseline procurement criteria.
Energy sector buyers are consolidating vendor relationships through multi-year fleet-as-a-service agreements rather than capital equipment purchases. This restructures cash flows for docking station manufacturers toward recurring software and maintenance revenue. The shift is most pronounced among Texas and California independent power producers managing distributed renewable portfolios.
Drone-In-A-Box Solutions Market Segmentation
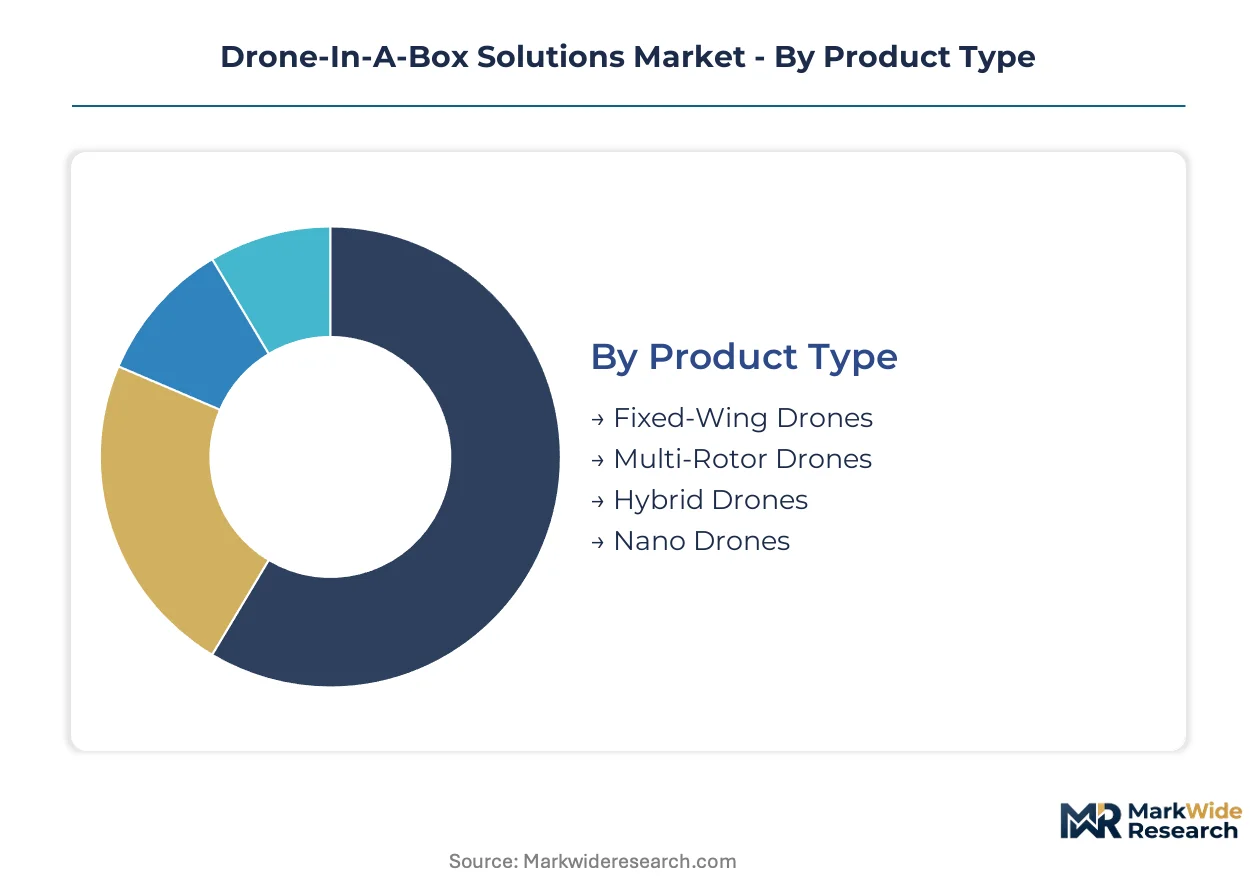
Drone-in-a-box solutions fragment across four critical dimensions that determine integration complexity and procurement economics. Product architecture dictates whether systems operate as standalone units or embed into broader industrial IoT frameworks. Deployment models and end-user verticals further stratify the vendor landscape by technical requirements and regulatory exposure.
Product Type:
Integration depth varies sharply across aerial platforms, with some configurations functioning as autonomous nodes and others requiring constant ground-station oversight.
- Multi-Rotor Drones:Vertical takeoff capability eliminates runway infrastructure, making these the default choice for congested utility substations and urban surveillance posts. Texas and California grid operators specify multi-rotor systems for vegetation encroachment monitoring along transmission corridors where landing zones are nonexistent. FAA Part 107 waiver compliance costs concentrate procurement attention on platforms with proven detect-and-avoid sensor integration.
- Hybrid Drones:Fixed-wing endurance combined with VTOL flexibility addresses extended-range pipeline inspection and offshore wind farm monitoring. Western Australian mining operations deploy hybrid platforms for continuous volumetric surveying of open-pit sites where battery swapping stations sit kilometers from survey targets. The mechanical complexity of tilt-rotor or tail-sitter configurations elevates maintenance scheduling requirements.
- Fixed-Wing Drones:Catapult or runway-dependent systems dominate agricultural mapping at scale across the US Midwest and Ukrainian grain belts.
- Nano Drones:Sub-250g platforms bypass certain regulatory thresholds for indoor industrial inspection and confined-space emergency response.
Volume placements concentrate in Multi-Rotor Drones; the faster expansion belongs to Hybrid Drones.
Deployment Model:
Cost tiering separates capital-intensive edge installations from recurring software subscriptions that restructure manufacturer cash flows.
- Cloud-Based:Centralized fleet orchestration platforms enable single-operator control of distributed docking stations across solar farms and wind installations. German transmission grid operators mandate cloud telemetry integration for real-time thermal anomaly alerts on high-voltage lines. EASA specific-category certification requirements for command-link redundancy accelerate procurement of systems with redundant cloud connectivity.
- Edge Computing:Onboard processing reduces latency for time-critical applications and addresses data sovereignty constraints in defense and critical infrastructure sectors. Australian mining conglomerates favor edge deployments where satellite backhaul costs or site connectivity limitations preclude continuous cloud uplink. The hardware premium for GPU-equipped docking stations compresses total cost of ownership where bandwidth pricing dominates operational economics.
- On-Premises:Air-gapped installations serve military and nuclear facility perimeter surveillance with zero external data exposure.
- Hybrid:Selective cloud burst for analytics while retaining local command-and-control satisfies dual-use infrastructure operators.
Procurement volumes cluster in Cloud-Based deployments; edge configurations are climbing the fastest as latency-sensitive applications multiply.
End User:
Application maturity and margin capture potential diverge sharply across verticals with distinct regulatory exposure and operational tempo requirements.
- Infrastructure:Electric utility vegetation management and thermal inspection generate the most predictable recurring revenue streams for docking station operators. North American grid operators under FERC reliability mandates deploy autonomous systems for continuous asset condition monitoring. The sector's procurement standardization around fleet-as-a-service agreements restructures vendor economics toward software and maintenance revenue.
- Surveillance:Defense rapid-deploy contracts and border security applications command premium pricing for trailer-mounted systems with minimal site preparation. US Department of Defense expeditionary force requirements for perimeter surveillance and convoy route reconnaissance specify hardened shelters with robotic battery swapping. Multi-jurisdiction certification complexity constrains vendor participation in NATO-aligned procurement.
- Agriculture:Precision crop monitoring and livestock management drive seasonal deployment patterns with lower utilization rates.
- Logistics:Last-mile delivery trials remain constrained by urban airspace congestion and payload limitations relative to ground alternatives.
Revenue concentration sits with Infrastructure; Surveillance represents the steepest expansion trajectory as defense budgets reorient toward autonomous systems.
Application:
Customer type and operational intensity determine whether deployments achieve 24/7 readiness or remain intermittent project-based engagements.
- Inspection:Automated structural assessment of bridges, power lines, and industrial facilities generates the highest flight-hour accumulation per deployed station. German TSOs now require EASA specific-category certification as baseline procurement criteria for transmission corridor monitoring. The application unifies previously separate maintenance schedules for aircraft and ground infrastructure into single automated workflows.
- Emergency Response:Wildfire monitoring, flood assessment, and disaster reconnaissance demand rapid activation protocols with weather-hardened shelters. Australian emergency services integrate drone-in-a-box networks with existing dispatch systems for automated first-response deployment. Seasonal demand spikes and unpredictable activation frequency complicate fleet sizing economics.
- Mapping & Surveying:Mining and construction volumetrics require precise georeferencing and repeat-pass accuracy for change detection.
- Delivery Services:Regulatory constraints on beyond-visual-line-of-sight operations over populated areas limit commercial scale.
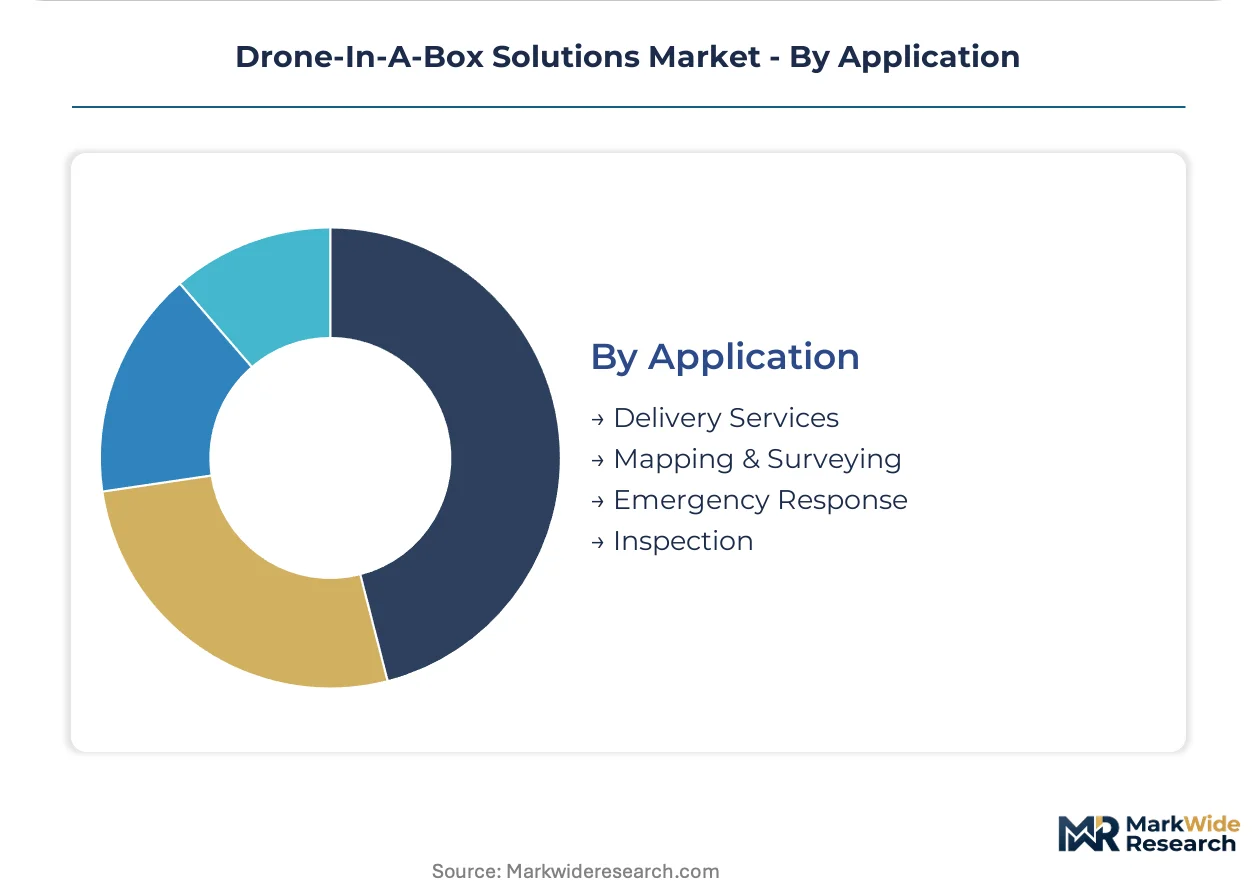
Station deployments concentrate in Inspection; Emergency Response is gaining share fastest as climate-related event frequency rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American utility deployment, where grid operators under FERC reliability mandates drive automated inspection procurement. German transmission system operators in Bavaria and North Rhine-Westphalia set certification benchmarks through EASA specific-category requirements. Western Australian mining corridors concentrate hybrid platform adoption for continuous volumetric surveying.
United States
Texas and California independent power producers deploy fleet-as-a-service agreements across distributed renewable portfolios. FAA Part 107 waivers for beyond-visual-line-of-sight operations determine deployment velocity along transmission corridors. Houston and Dallas-Fort Worth clusters concentrate procurement attention for vegetation encroachment monitoring systems.
Germany
Bavarian and North Rhine-Westphalian transmission grid operators mandate EASA specific-category certification as baseline procurement criteria. The EU Green Deal's sustainable finance taxonomy creates procurement pull for automated solar and offshore wind monitoring. Stuttgart and Munich industrial corridors anchor robotic battery swapping mechanism development.
Australia
Western Australian mining conglomerates adopt hybrid platforms for continuous volumetric surveying of open-pit operations. CASA remote aircraft licensing frameworks constrain design choices for multi-jurisdiction vendors. The Pilbara region concentrates deployment scale where satellite backhaul costs favor edge computing configurations.
France
Paris-based grid operators integrate drone-in-a-box networks with existing dispatch systems for automated first-response deployment. EASA specific-category certification pathways accelerate product roadmaps for European utility contracts. The Île-de-France region concentrates surveillance procurement for defense rapid-deploy contracts.
United Arab Emirates
Dubai and Abu Dhabi perimeter surveillance requirements drive hardened shelter procurement with minimal site preparation specifications. Desert deployment conditions inflate weather-hardening requirements for extended operational temperature ranges. NEOM development corridors concentrate next-generation 5G network slicing integration trials.
Drone-In-A-Box Solutions Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and certification compliance capabilities. The vendor landscape fragments into three functional tiers: fully integrated robotic swapping systems, AI-analytics layered hardware stacks, and rapid-deploy trailer configurations for expeditionary applications. Dominant competitive moves include multi-year fleet-as-a-service agreement restructuring and EASA specific-category certification acceleration.
Within the premium integration tier, Airobotics and Percepto exemplify divergent strategic positioning around hardware-software bundling. Airobotics anchors the high end through Israeli-developed fully integrated systems. Percepto occupies the analytics-layered segment through Tel Aviv-based AI-driven fleet orchestration. Easy Aerial represents the mid-market rapid-deploy configuration through Brooklyn-based trailer systems for defense and public safety verticals.
| Leading Market Players |
|---|
| Airobotics |
| American Robotics |
| Percepto |
| Azur Drones |
| Easy Aerial |
| Asylon |
| Atlas Dynamics |
| Antwork |
| H3 Dynamics |
| Others |
Supply Flow & Price Mechanics
Fleet-as-a-service procurement mandates from Texas and California independent power producers are compressing capital equipment margins while forcing docking station manufacturers toward recurring software revenue streams. This demand-side restructuring concentrates pricing power with buyers who bundle multi-year maintenance contracts into procurement specifications.
Pricing Analysis
Value-based pricing anchored to operational uptime guarantees dominates premium-tier procurement from German transmission system operators. Three-tier pricing structure across premium, standard, and economy levels separates EASA specific-category certified systems from FAA Part 107 waiver-compliant configurations and uncertified commodity enclosures. Pricing pressure stems from detect-and-avoid sensor cost inflation mandated by BVLOS regulatory frameworks. Utility infrastructure buyers exhibit lowest price sensitivity due to FERC reliability mandates, while agricultural operators demand economy-tier solutions with minimal software bundling.
Supply Chain Analysis
Single-source vulnerability sits with Japanese suppliers of high-grade gimbal motors and German manufacturers of solid-state lidar modules. Component sourcing draws from Taiwan for precision semiconductors, South Korea for advanced battery cells, and Switzerland for industrial-grade climate control systems. Raw material dependencies include rare-earth magnets for rotor assemblies, carbon fiber composites for airframe structures, and specialized aluminum alloys for weather-hardened shelters. Tariff exposure on Chinese-manufactured electronics creates margin volatility for mid-market vendors. Distribution runs through direct OEM relationships with utility operators and defense integrators rather than traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA specific-category certification requirements function as a cost-of-compliance moat, elevating barrier-to-entry thresholds that protect incumbent vendors with existing European utility relationships.
For Market Incumbents: Acquire embedded systems engineering capabilities with simultaneous flight control and industrial IoT security expertise. Consolidate robotic battery swapping IP through targeted specialist acquisitions before defense rapid-deploy contracts consolidate procurement. Counter emerging AI-native entrants by deepening firmware integration with legacy SCADA telemetry protocols that utility operators cannot easily replace. For New Entrants and Emerging Players: Begin with trailer-mounted rapid-deploy configurations for Australian mining and Middle Eastern perimeter surveillance where site preparation requirements are minimal. Target edge computing deployments in Western Australian Pilbara operations where satellite backhaul costs preclude cloud-based alternatives. Pursue CASA remote aircraft licensing as a beachhead certification that enables multi-jurisdiction expansion pathways. For Investors and Strategic Acquirers: The window for entry favors vertically integrated hardware-software stacks with existing EASA specific-category approvals. Long-term viability hinges on recurring revenue ratios above fifty percent through fleet-as-a-service contract structures. Monitor FAA Part 107 waiver processing velocity as the critical inflection signal for North American deployment scale acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Specific-Category Certification Acceleration | German TSO procurement mandates now require this certification as baseline qualification criteria. |
| Robotic Battery Swapping Mechanism Development | Western Australian mining operations adopt these systems for continuous open-pit volumetric surveying workflows. |
| Fleet-as-a-Service Agreement Restructuring | Texas and California IPPs now consolidate vendor relationships through multi-year software-centric contracts. |
| Edge Computing Configuration Expansion | Pilbara region deployments favor GPU-equipped docking stations where bandwidth pricing dominates economics. |
| Defense Rapid-Deploy Trailer Systems | US Department of Defense expeditionary requirements specify hardened shelters with minimal site preparation. |
Methodological Framework
Multi-period observation of FAA Part 107 waiver processing timelines, EASA certification pathway evolution, and fleet-as-a-service contract proliferation anchored the trend analysis, supplemented by interviews with utility planning officers, drone-in-a-box product managers, defense procurement specialists, and industrial IoT integration engineers. Secondary validation drew from FAA regulatory filings, EASA unmanned aircraft system documentation, FERC reliability mandate records, and CASA remote licensing frameworks. Bottom-up deployment estimates across transmission corridor, mining, and defense applications were triangulated against top-down market sizing from docking station manufacturer revenue disclosures.
Input-output matrices modeled drone platform configurations against deployment model segments and end-user verticals across the projection horizon. Segmentation dimensions included product architecture tiers, cloud versus edge computing topologies, infrastructure versus surveillance versus agriculture end-uses, and inspection versus emergency response application intensity. CAGRs were derived from deployment velocity assumptions tied to regulatory clearance timelines and buyer consolidation patterns. Forecast inputs incorporated BVLOS framework adoption curves and robotic battery swapping mechanism penetration rates in mining operations.
Regulatory processing delays, detect-and-avoid hardware cost inflation, and precision component supply disruptions are the dominant revision risks that could compress or extend deployment timelines. Forecasts reflect documented assumptions about waiver approval velocity and buyer procurement standardization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Drone Jamming System Market
Unmanned Systems
Military Robotics Market