
 Multi-Foil Rotors Market | 2026-2036
Multi-Foil Rotors Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Foil Rotors Market Foresight
Asset-light leasing models for high-speed rotating equipment are rewriting competitive entry barriers in the turbomachinery sector. Calnetix Technologies leverages its magnetic bearing heritage to extend into oil-free foil bearing systems for industrial compressors. Rolls-Royce anchors its position through captive R&D on advanced rotor dynamics for next-generation aero-engines. Honeywell Aerospace competes via vertical integration into precision foil manufacturing for turbine auxiliary systems.
Multi-foil rotors are self-acting hydrodynamic or aerodynamic bearing assemblies comprising stacked compliant metal foils that generate pressure films to support high-speed shafts without lubricating oil, operating at surface speeds exceeding 100 m/s in gas turbines and turboexpanders. Radial foil configurations dominate current aerospace installations due to their maturity in handling combined radial and thrust loads under thermal transients. Mixed flow designs represent the fastest-growing product category as industrial OEMs seek compact solutions for turbochargers and microturbines. Hydrodynamic technology leads installed base volumes while aerodynamic variants capture expanding margin pools in cryogenic and high-temperature applications.
FAA airworthiness directives and EPA New Source Performance Standards jointly constrain material selection and lifecycle emissions for rotating machinery in commercial aviation and stationary power. EASA certification requirements for oil-free bearing systems in European aerospace supply chains create parallel compliance obligations for component suppliers. SKF navigates these frameworks through dedicated certification laboratories in Germany and Sweden. Stakeholders must monitor evolving ISO 1940 balance quality grades and their interaction with emerging thermal management requirements in electrified propulsion architectures.
Market Dynamics
The transition from oil-lubricated to oil-free bearing architectures in aerospace propulsion and industrial turbomachinery is compressing qualification timelines and forcing simultaneous material science and manufacturing process investments across the supply base.
Growth Catalysts
- FAA Airworthiness Directives:Tightening emissions standards for auxiliary power units are mandating oil-free bearing retrofits in existing aircraft fleets, accelerating replacement demand across North American MRO networks.
- Electrified propulsion architectures:Hybrid-electric and turboelectric aircraft designs require foil-bearing systems capable of operating across wider thermal envelopes, pulling advanced multi-foil configurations into development programs.
- Precision manufacturing clusters:Concentrated tooling and metrology capabilities in Germany and Japan enable sub-micron foil forming tolerances essential for high-speed rotor stability.
Market Restraints
- Inconel and cobalt-chrome price volatility:Aerospace-grade superalloy feedstock costs fluctuate with mining output from Central African and Russian sources, squeezing margin predictability for precision stampers.
- Single-source foil forming equipment:Specialized electrochemical machining and photochemical etching systems concentrate among German and Swiss machine tool builders, creating supply bottleneck vulnerability.
- Thrust load capacity ceilings:Current generation bump-type foil geometries face hard limits above 50 kN specific load, constraining adoption in heavy industrial gas turbines.
Strategic Opportunities
- Cryogenic turboexpander applications:LNG liquefaction and hydrogen liquefaction plants in the United States and Qatar present untapped demand for aerodynamic foil bearings operating below minus 150 degrees Celsius.
- EU Green Deal industrial decarbonization incentives:Carbon border adjustment mechanisms and clean technology deployment funding favor oil-free turbomachinery in European process industries.
- Additive manufacturing convergence:Laser powder bed fusion of Inconel 718 is enabling integrated rotor-bearing structures with internal cooling channels impossible through conventional sheet metal stacking.
Industry Challenges
- Rotor dynamics simulation talent scarcity:Specialized competency in foil bearing stiffness and damping modeling concentrates among a limited cohort of academic programs and national laboratories.
- Extended EASA certification timelines:Novel oil-free bearing architectures face 18-36 month validation cycles for European aerospace qualification, compressing development-to-revenue windows.
- Legacy system integration friction:Retrofit of foil bearings into existing turbomachinery housings requires custom adapter designs that fragment engineering resources and delay fleet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Foil Rotors Market |
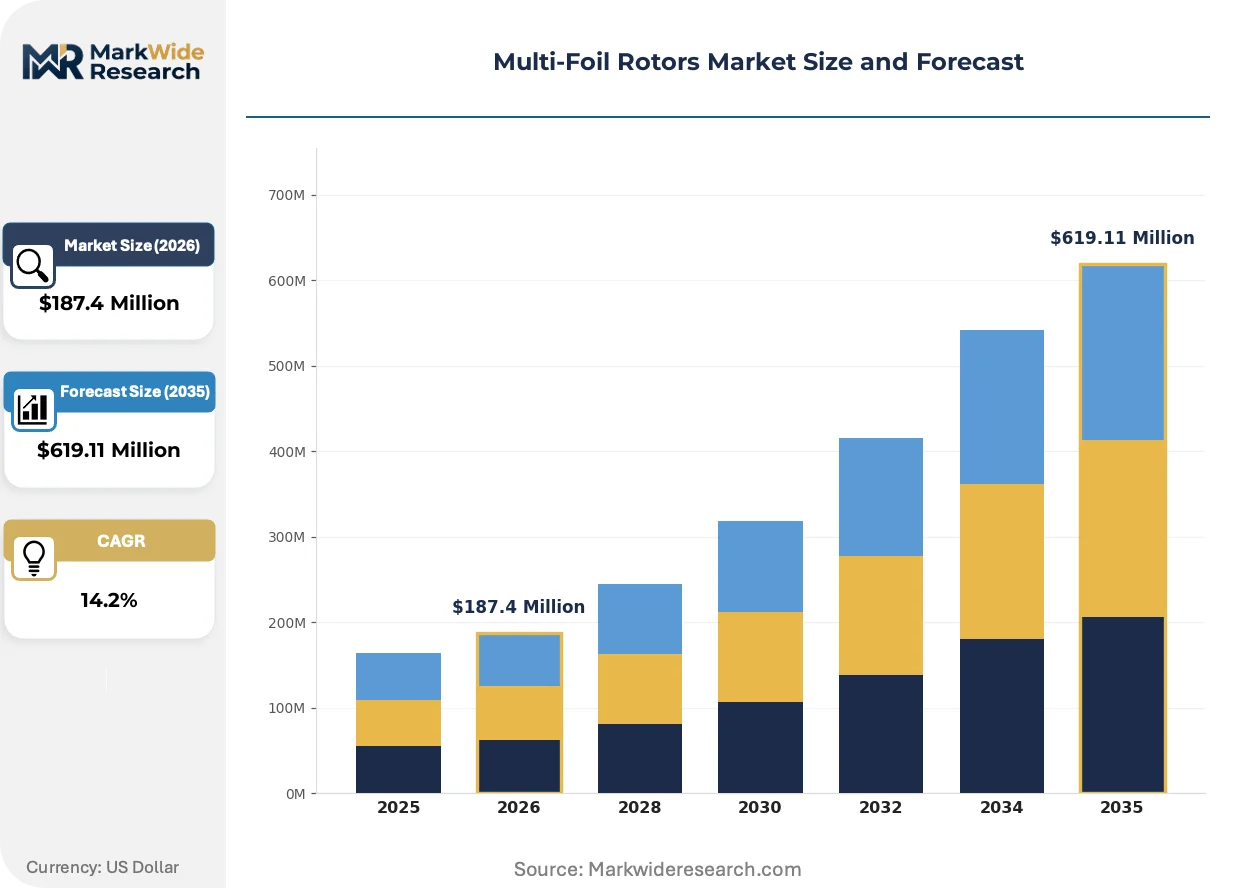
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial, Radial, Mixed Flow, Others Application: Aerospace, Industrial, Marine, Automotive End User: Manufacturers, Research Institutions, Service Providers, OEMs Technology: Hydrodynamic, Aerodynamic, Electromechanical, Thermal |
| Companies Covered | Calnetix Technologies, Capstone Green Energy, Doosan Enerbility, Honeywell Aerospace, Mitsubishi Heavy Industries, Mohawk Innovative Technology, Parker Aerospace, Rolls-Royce, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Foil Rotors Market Shifts & Advancements
Active development across three vectors is compressing traditional bearing procurement cycles and redefining performance benchmarks for high-speed rotating equipment.
Compliant metal foam structures are replacing conventional bump foils as the elastic foundation in next-generation radial bearings. Aerospace OEMs in the United States and France are qualifying these configurations for turbine auxiliary systems operating above 80,000 RPM. The technology is rendering obsolete the discrete bump-strip manufacturing steps that previously dominated foil bearing production.
EPA New Source Performance Standards for stationary gas turbines are tightening allowable lubricant emissions in power generation and oil & gas applications. This regulatory pressure is accelerating foil bearing adoption in new-build compressor trains and forcing incumbent oil-lubricated system suppliers to develop hybrid transition architectures. Industrial end-users in Texas and Louisiana are prioritizing oil-free bids in RFP evaluation criteria.
Power-by-the-hour contracting for rotating equipment is migrating from civil aviation into industrial turbomachinery. Asset operators in chemical processing and LNG are unbundling capital expenditure from operational risk, favoring suppliers with captive bearing manufacturing and field service networks. This shift concentrates procurement authority among integrated OEMs and compresses margins for component-only vendors.
Multi-Foil Rotors Market Segmentation
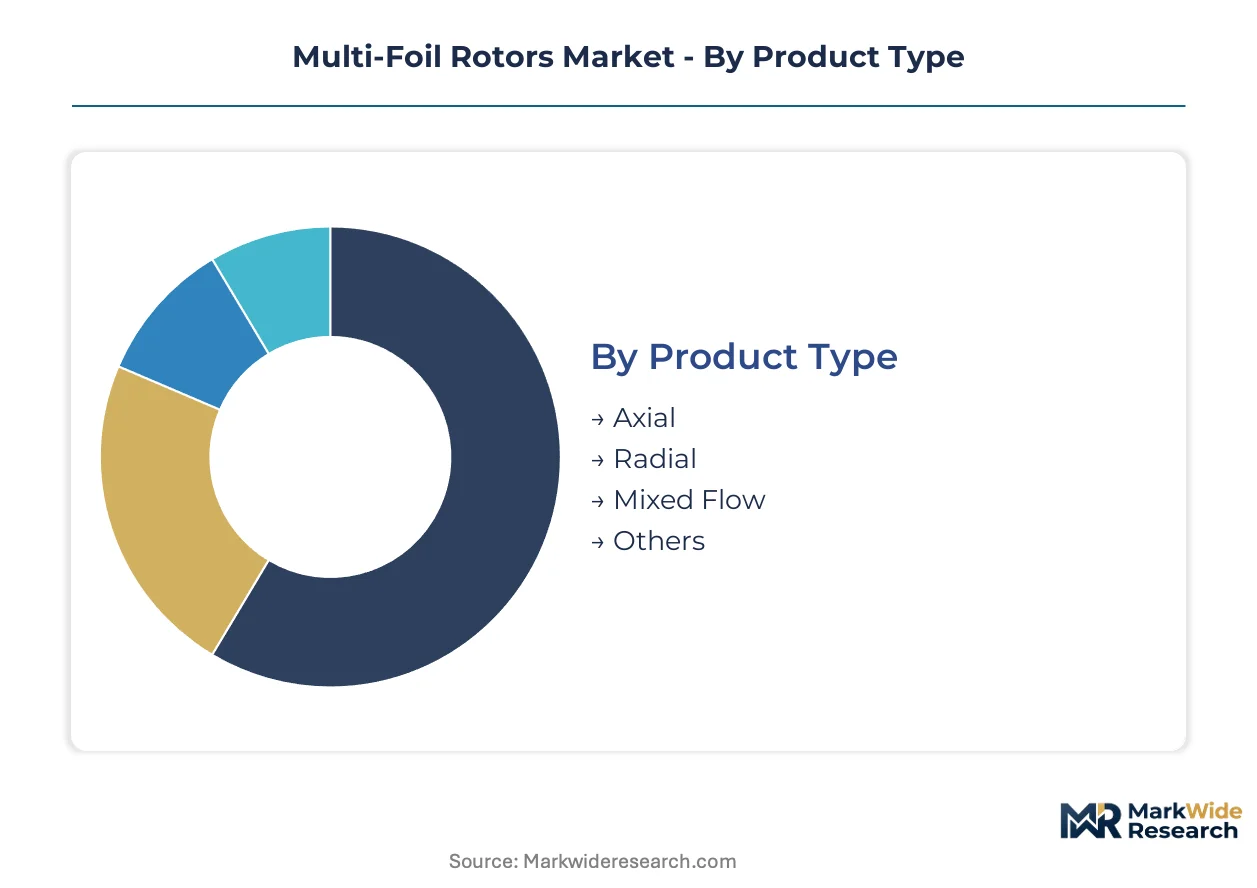
Multi-foil rotor procurement cycles vary dramatically by application criticality and certification burden. Aerospace programs demand 18-36 month qualification timelines while industrial retrofits compress sourcing to 6-12 weeks. Understanding these velocity differentials enables suppliers to align inventory and engineering resources against segment-specific revenue recognition patterns.
Product Type:
Radial configurations turn inventory slowest due to aerospace qualification rigor, while mixed flow designs cycle fastest as industrial OEMs iterate compressor architectures quarterly.
- Radial:Compliant bump-foil stacks arranged circumferentially around the shaft handle combined radial and thrust loads under thermal transients. Demand concentrates in United States and France where turbine auxiliary power unit manufacturers face FAA airworthiness mandates for oil-free bearing retrofits.
- Mixed Flow:Hybrid geometries integrating axial and radial flow paths achieve compact footprints for turbochargers and microturbines. German and Japanese precision manufacturing clusters are pulling these configurations into high-volume industrial compressor programs seeking space-constrained solutions.
- Axial:Tapered land and step designs manage thrust loads in cryogenic turboexpanders.
- Others:Specialized geometries for magnetic bearing hybrid systems and custom industrial applications.
Radial anchors the volume base while mixed flow gains share at the steepest rate.
Application:
Margin profiles diverge sharply: aerospace commands premium pricing for certified configurations, marine sits at cost-plus contracting, and automotive remains speculative pending electric turbocharger commercialization.
- Aerospace:Environmental control systems and auxiliary power units in commercial and defense aircraft. FAA emissions standards for APUs are mandating oil-free bearing architectures across United States-based MRO networks.
- Industrial:Compressor trains, turboexpanders, and process gas machinery in chemical and LNG facilities. EPA New Source Performance Standards are tightening lubricant emissions limits for stationary gas turbines in Texas and Louisiana.
- Marine:Naval propulsion and auxiliary systems requiring corrosion-resistant foil materials.
- Automotive:Electric turbochargers and range-extender microturbines in development-phase powertrains.
Industrial generates the heaviest shipment volumes while aerospace captures the widest margin spreads.
End User:
Procurement authority concentrates differently across the value chain: OEMs specify architectures, manufacturers execute foil forming, and service providers manage retrofit installation risk.
- OEMs:Original equipment manufacturers of turbomachinery and aircraft propulsion systems. United States and European aerospace primes are captive-sourcing foil bearing systems to protect rotor dynamics intellectual property.
- Manufacturers:Precision metal forming specialists producing bump foils, top foils, and bearing sleeves. Japanese and German tooling clusters enable sub-micron forming tolerances essential for high-speed stability.
- Service Providers:MRO networks and field service organizations managing bearing retrofits and overhaul.
- Research Institutions:National laboratories and university programs advancing foil bearing modeling and materials science.
OEMs dominate specification authority while manufacturers absorb the steepest capacity investment requirements.
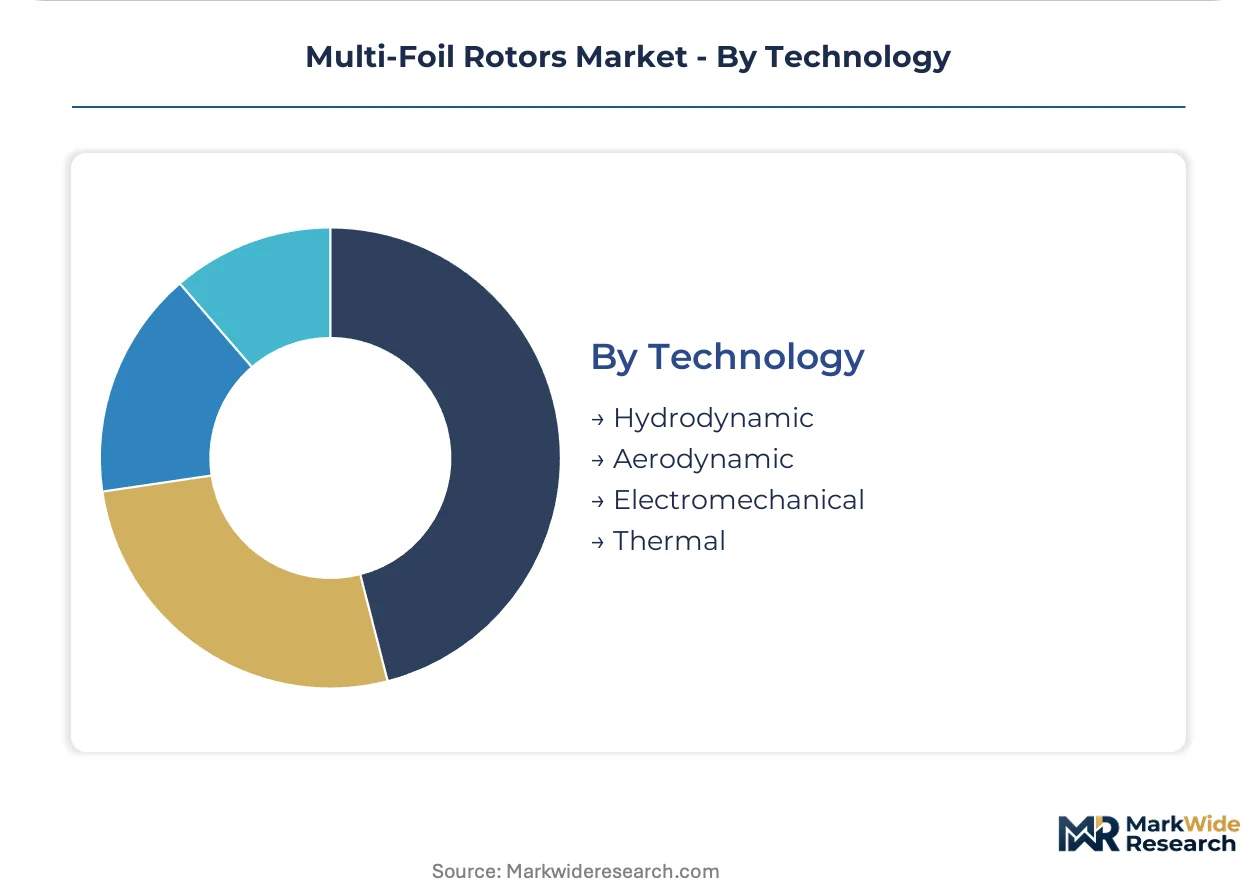
Technology:
Technology selection tracks operating environment severity: hydrodynamic variants dominate ambient-temperature industrial bases, aerodynamic configurations penetrate cryogenic and high-temperature extremes, and electromechanical hybrids address active vibration control needs.
- Hydrodynamic:Self-acting pressure films generated by shaft rotation without external pressurization systems. Installed base volumes concentrate in industrial compressor applications across United States Gulf Coast petrochemical corridors.
- Aerodynamic:Gas-lubricated bearings operating above 100 m/s surface speeds in high-temperature or cryogenic regimes. LNG liquefaction facilities in Qatar and hydrogen liquefaction plants in the United States are qualifying these for minus 150 degrees Celsius service.
- Electromechanical:Hybrid architectures combining foil bearings with active magnetic bearing elements for vibration suppression.
- Thermal:Foil configurations engineered for extreme thermal gradients in turbine hot sections.
Hydrodynamic retains the broadest installed base while aerodynamic climbs the fastest on liquefaction energy infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese precision manufacturing clusters, while US Gulf Coast demand absorbs margin compression from volatile superalloy feedstock costs.
United States
FAA airworthiness directives for auxiliary power unit emissions are mandating oil-free bearing retrofits across commercial MRO networks. EPA New Source Performance Standards tighten lubricant emissions limits for stationary gas turbines. Houston and Beaumont anchor industrial compressor demand from petrochemical corridor expansions.
Germany
EASA certification requirements for oil-free bearing systems pull advanced multi-foil configurations into European aerospace supply chains. EU Green Deal industrial decarbonization incentives favor oil-free turbomachinery in process industries. Stuttgart and Munich precision tooling clusters enable sub-micron foil forming tolerances for high-speed stability.
Japan
METI technology roadmaps for hydrogen liquefaction infrastructure drive aerodynamic foil bearing qualification for cryogenic service. JIS standards govern precision metal forming specifications for turbomachinery components. Nagoya and Osaka manufacturing belts concentrate electrochemical machining capabilities for bump-foil production.
France
ANSM aerospace quality frameworks align with EASA oil-free bearing validation protocols for turbine auxiliary systems. The country's national aerospace regulator enforces parallel compliance obligations for component suppliers. Toulouse and Paris-Saclay clusters host captive R&D programs on advanced rotor dynamics.
United Kingdom
Rolls-Royce anchors next-generation aero-engine development programs requiring foil-bearing systems for hybrid-electric architectures. The national aerospace regulator maintains certification reciprocity with EASA for European supply chain integration. Derby and Bristol defense-aerospace corridors concentrate turbomachinery specification authority.
Multi-Foil Rotors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, absorbing tooling investment risk without capturing full lifecycle value. The vendor base organizes around three archetypes: aerospace primes with captive bearing divisions, precision metal formers supplying foil stacks, and magnetic bearing heritage firms extending into oil-free architectures. Consolidation pressure runs highest among mid-scale stampers facing Inconel price volatility. Dominant competitive moves include backward integration into foil forming capacity and strategic partnerships with cryogenic liquefaction project developers.
Among US-based platform integrators, Honeywell Aerospace and Rolls-Royce occupy positions that exemplify system-tier control over specification and certification timelines. Calnetix Technologies represents the magnetic-to-foil extension archetype, leveraging electromechanical heritage into compliant bearing architectures. SKF anchors the European component specialist tier with dedicated certification laboratories addressing EASA validation requirements.
| Leading Market Players |
|---|
| Calnetix Technologies |
| Capstone Green Energy |
| Doosan Enerbility |
| Honeywell Aerospace |
| Mitsubishi Heavy Industries |
| Mohawk Innovative Technology |
| Parker Aerospace |
| Rolls-Royce |
| SKF |
| Others |
Supply & Pricing Matrix
Inconel and cobalt-chrome price volatility from Central African and Russian mining sources compresses margin predictability across precision stamping tiers while simultaneously forcing buyers toward long-term offtake contracts and captive foil forming investments that reshape supply chain geography.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for multi-foil rotor stacks, with spreads widening between aerospace-certified premium tiers and uncertified industrial economy tiers based on EASA validation status and volume scale. Price differentiation stems from sub-micron forming tolerance capabilities and bundled field service networks. Cost compression in the industrial mid-tier is intensifying because EPA emissions mandates are accelerating retrofit demand without matching supply expansion. MRO networks in the United States exhibit the highest price sensitivity due to fleet-wide retrofit budget constraints, while LNG project developers in Qatar demonstrate the lowest sensitivity given project finance structures.
Supply Chain Analysis
Extended payment terms from German and Swiss machine tool builders to precision metal formers in Japan and Germany are financing electrochemical machining capacity expansion for bump-foil production. Raw material dependencies draw from Inconel 718 feedstock, cobalt-chrome superalloys, and specialized photochemical etching chemistries. Single-source vulnerability concentrates in electrochemical machining systems from German and Swiss builders. Distribution runs through captive OEM supply chains for aerospace applications and independent distributors for industrial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multi-foil rotors market sits in early-cycle recovery as FAA airworthiness directives for auxiliary power unit emissions drive replacement demand across North American commercial fleets.
For Market Incumbents: Pre-empt margin erosion from Inconel price volatility by securing backward integration into foil forming capacity in Stuttgart or Nagoya tooling clusters. Accelerate EASA certification laboratory investment to compress 18-36 month validation timelines before emerging magnetic-to-foil entrants replicate SKF's European infrastructure. Lock in long-term offtake agreements with LNG liquefaction developers in Qatar and the United States to anchor cryogenic aerodynamic bearing revenue visibility. For New Entrants and Emerging Players: Pursue cryogenic turboexpander applications in United States hydrogen liquefaction infrastructure as the most penetrable white-space segment, where METI roadmaps and DOE funding are qualifying aerodynamic configurations without entrenched incumbent relationships. Target industrial compressor retrofit programs in Texas and Louisiana petrochemical corridors through power-by-the-hour contracting models that unbundle capital expenditure from operational risk. Lead with additive manufacturing capabilities for integrated rotor-bearing structures as the primary go-to-market differentiator against conventional sheet metal stampers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision metal formers with captive electrochemical machining capacity and active EASA certification pipelines. Long-term viability over the next decade hinges on exposure to electrified propulsion architectures in hybrid-electric aircraft development programs. Acquisition targets should demonstrate proven rotor dynamics simulation competency and established relationships with cryogenic liquefaction project developers. The signal to watch is FAA issuance of additional airworthiness directives mandating oil-free bearing retrofits beyond auxiliary power units into environmental control systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Forming | Captures margin from Inconel volatility and secures sub-micron tolerance capacity in German precision clusters. |
| EASA Certification Laboratory Investment | Compresses validation timelines for European aerospace supply chain qualification against 18-36 month benchmarks. |
| Cryogenic Application Partnership | Locks in LNG and hydrogen liquefaction demand in Qatar and United States energy infrastructure buildouts. |
| Additive Manufacturing Capability | Enables integrated rotor-bearing geometries with internal cooling channels impossible through conventional stacking. |
| Power-by-the-Hour Contracting | Migrates aviation service models into industrial turbomachinery to unbundle capital risk from operational expenditure. |
Research Methodology
A standing panel of turbomachinery OEM procurement directors, precision metal forming plant managers, MRO network engineering leads, and cryogenic liquefaction project developers provided ongoing calibration across the primary research phase. Secondary validation drew from FAA airworthiness directive filings, EPA New Source Performance Standards documentation, EASA certification bulletins, and SEC 10-K disclosures from listed aerospace suppliers. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning product configuration, application criticality, end-user procurement authority, and technology operating envelope. CAGRs were derived from installed base replacement cycles and new-build penetration assumptions. Industry-specific inputs incorporated FAA emissions mandate implementation timelines and METI hydrogen infrastructure deployment roadmaps.
Macroeconomic conditions sit as an overlay; deviation in superalloy commodity prices, mining supply disruptions, or aerospace production rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology qualification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market