
 Aircraft Hose Fittings Market | 2026-2036
Aircraft Hose Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Hose Fittings Market Analysis
Aerospace aftermarket distribution is reconfiguring as OEM-direct channels and authorized distributor networks consolidate procurement for commercial and defense operators. Parker Hannifin Corp leverages its vertically integrated fluid systems portfolio to control specification-setting across multiple airframe programs. Eaton Corporation anchors military and civil hydraulic fitting demand through long-term platform contracts. TECALEMIT AEROSPACE GROUP specializes in fuel system adapters and nozzles for European and Middle Eastern operator bases.
Aircraft hose fittings are precision-machined connectors designed to join flexible hose assemblies to rigid tubing, pumps, valves, and actuators in fluid conveyance systems, typically manufactured from aerospace-grade aluminum alloys, stainless steel, or titanium with elastomeric seals rated for operating pressures exceeding 3,000 psi and temperature extremes from -65°F to 450°F. Their primary purpose is to maintain leak-free integrity across fuel, hydraulic, and pneumatic circuits during vibration, thermal cycling, and pressure surge conditions encountered in flight. Stainless steel fittings command the largest material share due to corrosion resistance requirements in salt-air environments and extended service intervals. Fuel Systems applications generate the highest value per unit given fire-resistant specification tiers and mandatory traceability documentation. Aftermarket Suppliers represent the fastest-growing end-user channel as fleet age profiles lengthen and MRO providers stock critical hose fitting SKUs for line-replaceable unit turnaround.
FAA airworthiness directives and EASA certification specifications govern material flammability, fatigue life, and traceability for aircraft hose fittings installed on Part 25 transport category aircraft. EPA REACH compliance and EU RoHS substance restrictions additionally constrain cadmium plating and hexavalent chromium surface treatments, pushing suppliers toward zinc-nickel and ion-vapor deposited aluminum alternatives. Stakeholders must monitor evolving sustainable aviation fuel compatibility standards, as alternative hydrocarbon blends may degrade legacy elastomeric seal compounds and trigger retrofit cycles across installed hose fitting populations.
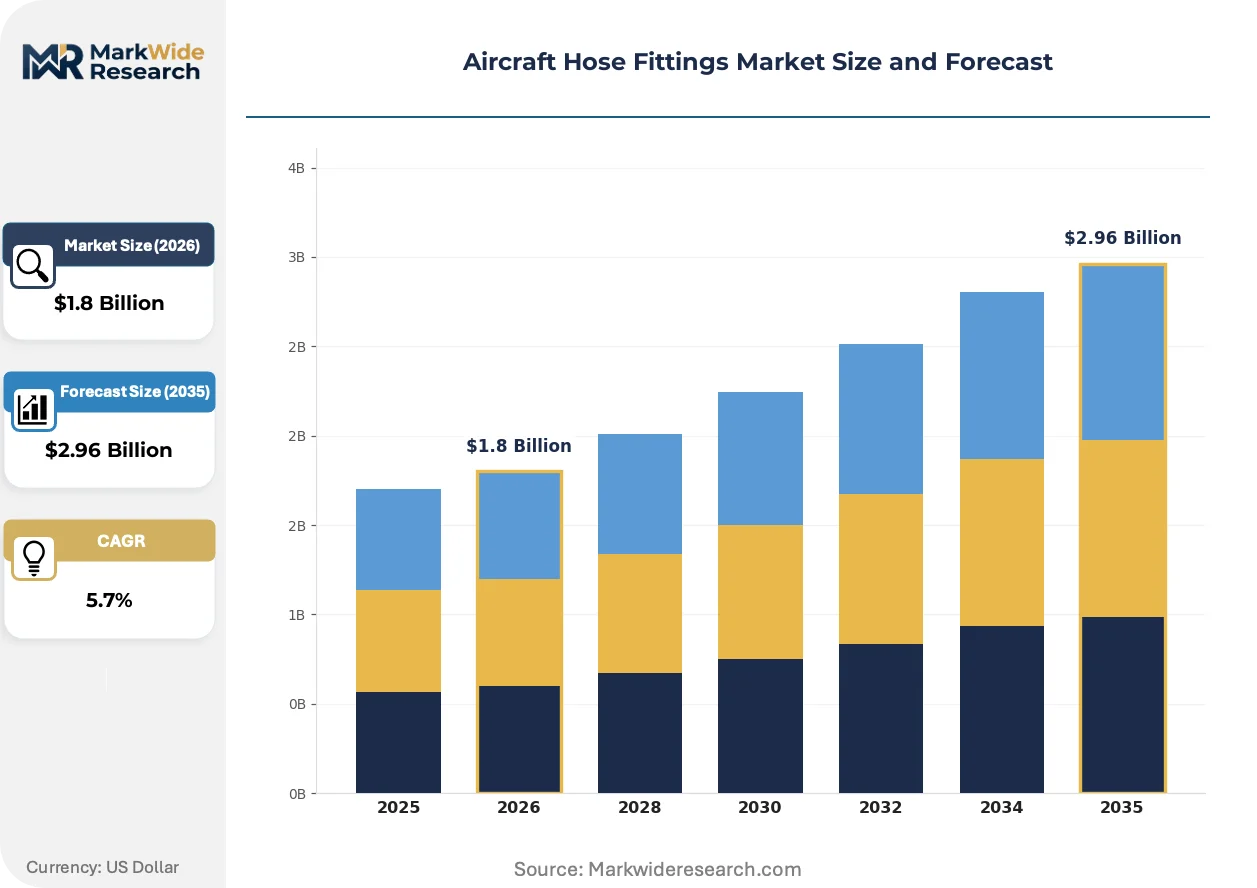
Market Dynamics
FAA and EASA fire-resistance mandates are compressing supplier qualification timelines while OEMs consolidate approved vendor lists for next-generation narrow-body programs. This regulatory tightening concentrates procurement authority among vertically integrated fluid systems specialists.
Growth Catalysts
- SAF Compatibility Retrofits:Sustainable aviation fuel formulations degrade legacy elastomeric seals in installed hose fitting populations, triggering replacement cycles across aging commercial fleets.
- Narrow-Body Production Surge:Boeing and Airbus ramp assembly rates for single-aisle platforms, expanding OEM hose fitting procurement for initial provisioning and line-fit installations.
- REACH Phase-Out Deadlines:EU restrictions on hexavalent chromium surface treatments accelerate supplier transitions to zinc-nickel and ion-vapor deposited aluminum alternatives.
Market Restraints
- Titanium Input Volatility:Aerospace-grade titanium sponge pricing fluctuates with Russian supply disruptions, pressuring margin structures for high-pressure fitting manufacturers.
- Dual-Source Consolidation:Tier-1 airframers reduce approved supplier pools from three to two vendors per platform, elevating concentration risk for excluded specialty fitting producers.
- Cadmium Plating Sunset:EPA and ECHA parallel bans on cadmium surface treatments force immediate capital retooling for legacy military specification product lines.
Strategic Opportunities
- Additive Manufacturing Qualification:Laser powder bed fusion of titanium hose fitting bodies collapses lead times for low-volume AOG replacement parts, opening aftermarket service contracts.
- Middle East MRO Expansion:Emirates, Etihad, and Saudia establish captive heavy maintenance facilities in Dubai and Jeddah, localizing hose fitting inventory for wide-body fleets.
- Digital Thread Traceability:Blockchain-enabled material certification meets EASA Specification 100-14 documentation requirements, differentiating premium suppliers in aftermarket bidding.
Industry Challenges
- NDT Technician Scarcity:Fluorescent penetrant inspection and eddy current testing for fatigue-cracked stainless steel fittings face qualified personnel shortages at FAA-certified repair stations.
- Platform-Specific Qualification Burden:Each airframe program demands unique hose fitting testing protocols, fragmenting engineering resources across Boeing 737 MAX, Airbus A320neo, and COMAC C919 specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Hose Fittings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fittings, Couplings, Adapters, Nozzles Material: Aluminum, Stainless Steel, Titanium, Rubber Application: Fuel Systems, Hydraulic Systems, Pneumatic Systems, Engine Components End User: Aerospace Manufacturers, Maintenance Providers, Military Operators, Aftermarket Suppliers |
| Companies Covered | Titeflex, SHV, Parker Hannifin Corp, Specialty Hose Corporation, Delafield Corporation, Eaton Corporation, Hy-Lok USA, Inc., Precision Hose Technology, Inc., TECALEMIT AEROSPACE GROUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Hose Fittings Market Emerging Trajectories
Material science advances and digital certification protocols are restructuring how hose fitting suppliers demonstrate airworthiness. These developments compress traditional qualification timelines while elevating performance thresholds.
Titanium-aluminide intermetallic coatings are collapsing the weight penalty of corrosion-resistant stainless steel fittings in salt-air operating environments. Regional carriers operating coastal routes in Southeast Asia adopt these surface treatments to extend replacement intervals. The technology is collapsing the traditional trade-off between material density and environmental durability that has dominated fitting specification for three decades.
EASA Specification 100-14 documentation requirements for fire-resistant fluid system components now mandate electronic record retention for the full service life of each installed fitting. MRO providers in Germany and France invest in cloud-based material traceability platforms to satisfy audit protocols. Fuel system applications face the steepest compliance burden given fire-resistant specification tiers and mandatory lot-number tracking.
Airline procurement departments consolidate hose fitting purchases through integrated supply agreements that bundle hydraulic, fuel, and pneumatic components under single-source contracts. Lufthansa Technik and ST Engineering negotiate multi-year vendor-managed inventory programs, displacing spot-buy aftermarket channels. This concentration is most pronounced in North American and European flag carrier fleets with centralized technical purchasing authority.
Aircraft Hose Fittings Market Segmentation
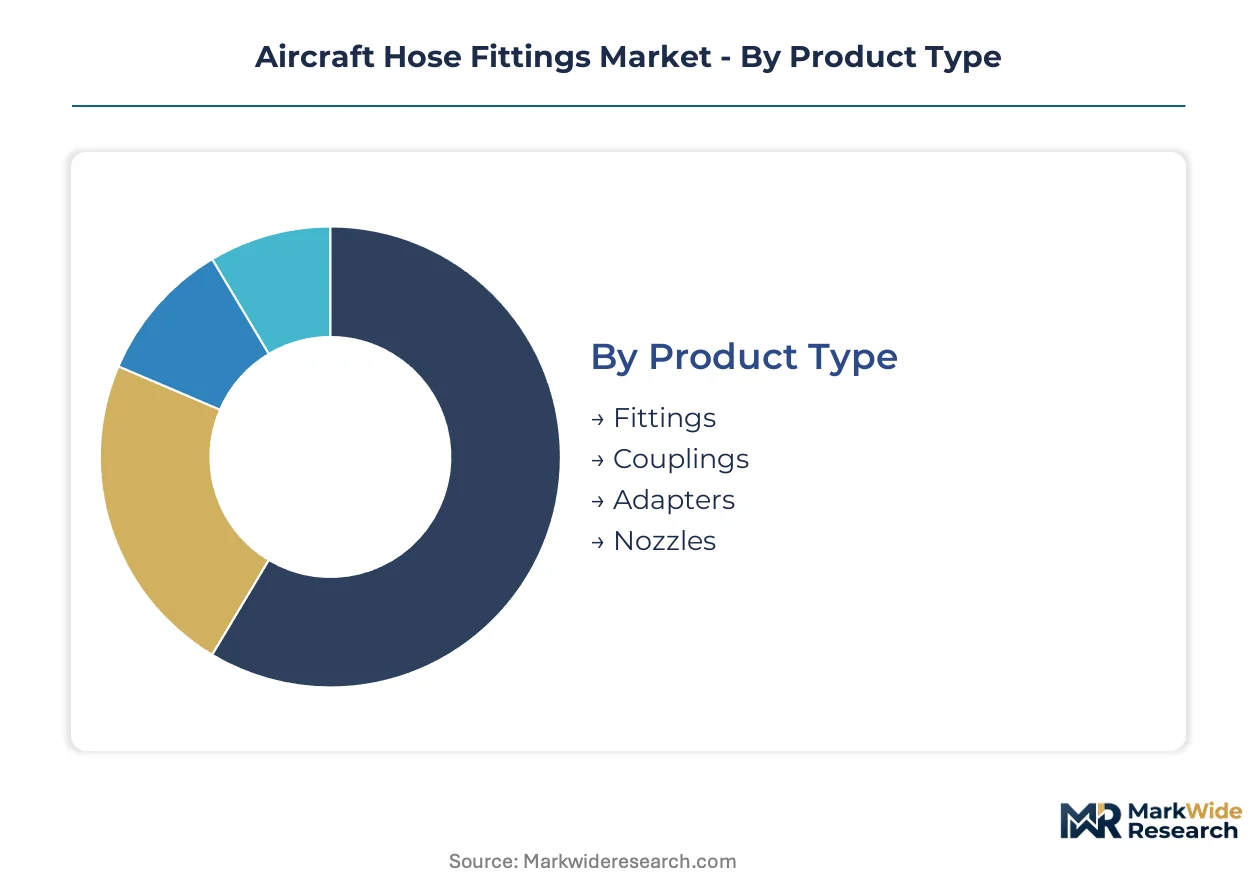
Segmentation in aircraft hose fittings reveals how specification tiers, material science, and regulatory pathways fragment procurement across commercial and defense aviation. Each dimension carries distinct qualification burdens and margin structures that reshape supplier positioning.
Product Type:
Mature connector categories dominate installed bases while emerging nozzle designs capture next-generation platform specifications.
- Fittings:Precision-machined threaded connectors joining hose assemblies to rigid tubing, pumps, and actuators. Parker Hannifin and Eaton control specification-setting for Boeing and Airbus narrow-body programs through captive fluid systems integration.
- Couplings:Quick-disconnect mechanisms enabling rapid line-replaceable unit swaps during AOG scenarios. MRO providers in Germany and France stock standardized coupling SKUs to compress turnaround times for Lufthansa and Air France-KLM fleets.
- Adapters:Transition fittings bridging incompatible thread standards and port configurations across legacy and modern airframe generations.
- Nozzles:Engineered fuel and pneumatic discharge terminals with fire-resistant specification tiers for tank venting and ground servicing operations.
Fittings retain volume leadership; nozzles hold the steepest expansion curve as next-generation narrow-body programs specify integrated fuel system architectures.
Material:
Cost tier stratification separates commodity aluminum from premium titanium, with mid-grade stainless steel capturing the widest specification range.
- Stainless Steel:Corrosion-resistant alloys dominating salt-air operating environments and extended service interval requirements. Coastal carriers in Southeast Asia specify 316-grade stainless for regional turboprop fleets exposed to marine atmospheric conditions.
- Titanium:High strength-to-density ratio alloys for weight-critical applications in high-pressure hydraulic circuits. Russian supply disruptions for aerospace-grade sponge have compressed margin structures and accelerated qualification of Japanese and Chinese alternative sources.
- Aluminum:Lightweight 6061-T6 and 7075-T6 alloys for low-pressure pneumatic systems and non-structural fuel line connections.
- Rubber:Elastomeric seal compounds and overmolded fitting interfaces facing degradation risks from sustainable aviation fuel compatibility testing.
Stainless steel commands the broadest specification footprint; titanium is climbing the fastest as weight reduction targets intensify across single-aisle platform refresh cycles.
Application:
Application segmentation tracks fluid system criticality, with fuel and hydraulic circuits carrying the most stringent fire-resistance and fatigue-life mandates.
- Fuel Systems:Fire-resistant specification tiers with mandatory traceability documentation per EASA Specification 100-14. FAA airworthiness directives govern material flammability for transport category aircraft fuel line connections.
- Hydraulic Systems:High-pressure circuits exceeding 3,000 psi operating pressures for flight control actuation and landing gear extension. Military operators specify titanium-bodied hydraulic fittings for fighter aircraft subject to extreme thermal cycling.
- Pneumatic Systems:Bleed air and environmental control system connections operating at moderate pressures and temperatures.
- Engine Components:Specialized fittings for lubrication, fuel delivery, and accessory drive systems within turbine powerplant envelopes.
Fuel Systems anchor value per unit; Engine Components are gaining share fastest as propulsion system refresh cycles accelerate across aging commercial fleets.
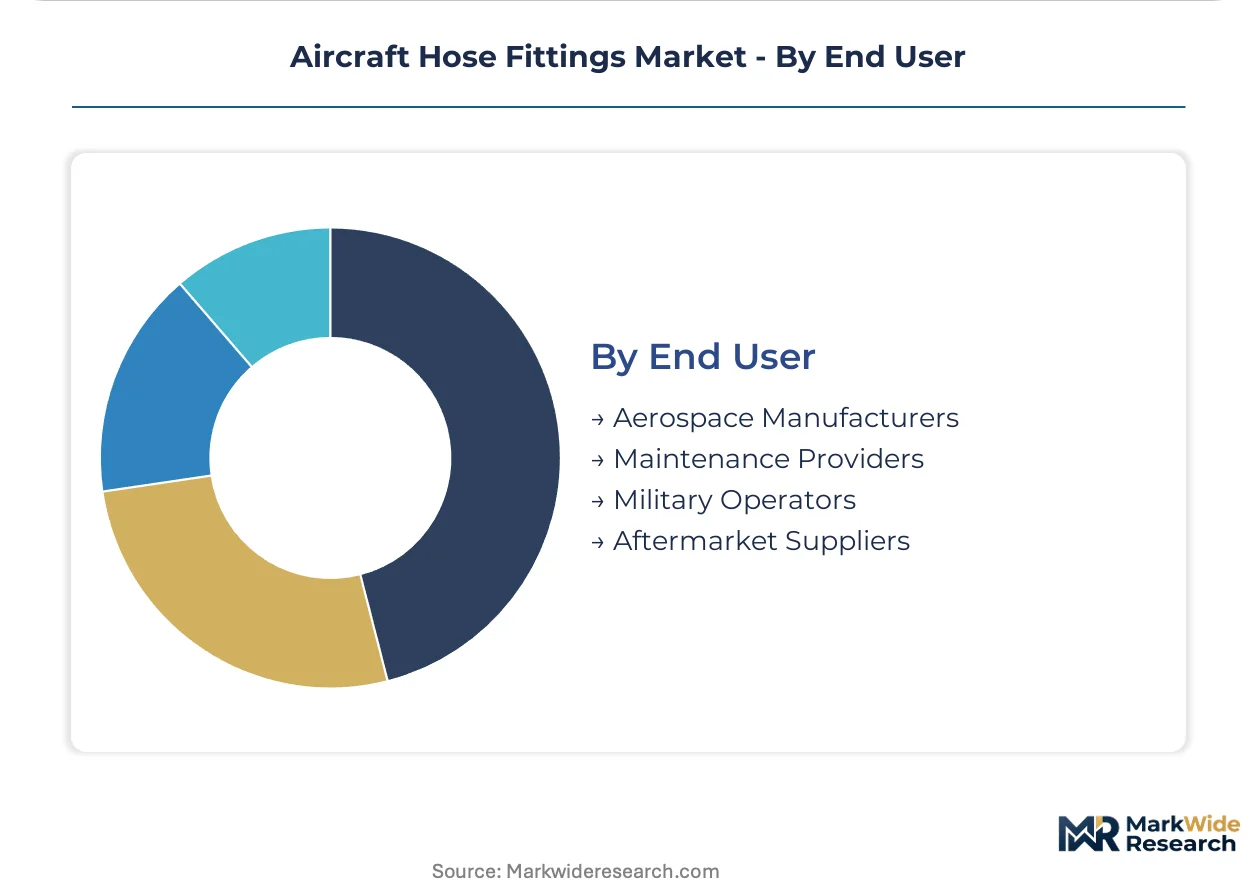
End User:
Customer type segmentation concentrates procurement authority among vertically integrated OEMs and consolidating aftermarket distributors.
- Aftermarket Suppliers:Independent distributors and MRO providers stocking critical hose fitting SKUs for line-replaceable unit turnaround. ST Engineering and Lufthansa Technik negotiate vendor-managed inventory programs displacing spot-buy channels.
- Aerospace Manufacturers:Boeing, Airbus, and COMAC specifying initial provisioning and line-fit installations for new production aircraft. OEM-direct procurement is tightening approved vendor lists from three to two suppliers per platform.
- Maintenance Providers:FAA-certified repair stations facing qualified NDT technician scarcity for fluorescent penetrant inspection of fatigue-cracked stainless steel fittings.
- Military Operators:Defense agencies specifying MIL-SPEC product lines subject to cadmium plating sunset mandates from EPA and ECHA parallel bans.
Aftermarket Suppliers are expanding most quickly as fleet age profiles lengthen; Aerospace Manufacturers retain specification authority for new platform introductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives and EASA certification specifications are tightening fire-resistance mandates across major aviation jurisdictions. Procurement authority concentrates where OEM final assembly lines and MRO heavy maintenance facilities cluster.
United States
Boeing's 737 MAX production surge in Renton, Washington drives OEM hose fitting demand for initial provisioning. FAA mandates on fire-resistant materials compress supplier qualification timelines for transport category aircraft. The Greater Seattle aerospace corridor anchors fluid systems integration, with Parker Hannifin and Eaton controlling specification-setting for narrow-body programs.
Germany
Lufthansa Technik's vendor-managed inventory programs consolidate aftermarket procurement for European flag carrier fleets. EASA Specification 100-14 documentation requirements mandate electronic record retention for installed fittings. The Hamburg MRO cluster localizes hose fitting inventory for wide-body heavy maintenance, displacing spot-buy channels.
France
Airbus A320neo final assembly in Toulouse generates line-fit hose fitting demand for hydraulic and fuel systems. REACH phase-out deadlines on hexavalent chromium surface treatments accelerate supplier transitions to zinc-nickel alternatives. The Toulouse-Blagnac aerospace zone hosts Tier-1 fluid systems specialists serving both commercial and defense platforms.
China
COMAC C919 production ramp drives domestic hose fitting qualification for indigenous narrow-body programs. The country's national aviation regulator imposes parallel certification protocols mirroring FAA and EASA fire-resistance standards. The Yangtze River Delta aerospace cluster in Shanghai concentrates MRO investment from ST Engineering and local maintenance providers.
United Arab Emirates
Emirates and Etihad captive heavy maintenance facilities in Dubai localize hose fitting inventory for wide-body fleets. The General Civil Aviation Authority enforces fire-resistant specification tiers for fuel system components operating in high-temperature desert environments. Dubai South's aviation district anchors aftermarket distribution hubs serving Middle Eastern and African operator bases.
Aircraft Hose Fittings Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated fluid systems specialists and authorized distributor networks. Tier-1 airframers have reduced approved supplier pools from three to two vendors per platform, elevating concentration risk for excluded producers. Two strategic archetypes dominate: specification-setting OEM integrators and aftermarket-focused MRO distributors. Competitive moves center on backward integration into captive seal compound production and geographic expansion into Middle Eastern MRO hubs.
Among diversified industrial conglomerates, Parker Hannifin Corp and Eaton Corporation occupy positions as specification anchors for Boeing and Airbus narrow-body programs. TECALEMIT AEROSPACE GROUP exemplifies the specialized fuel systems adapter segment serving European and Middle Eastern operator bases. These three represent distinct competitive vectors: integrated fluid systems control, multi-platform hydraulic specification authority, and regional fuel system specialization.
| Leading Market Players |
|---|
| Titeflex |
| SHV |
| Parker Hannifin Corp |
| Specialty Hose Corporation |
| Delafield Corporation |
| Eaton Corporation |
| Hy-Lok USA, Inc. |
| Precision Hose Technology, Inc. |
| TECALEMIT AEROSPACE GROUP |
| Others |
Supply Flow & Price Mechanics
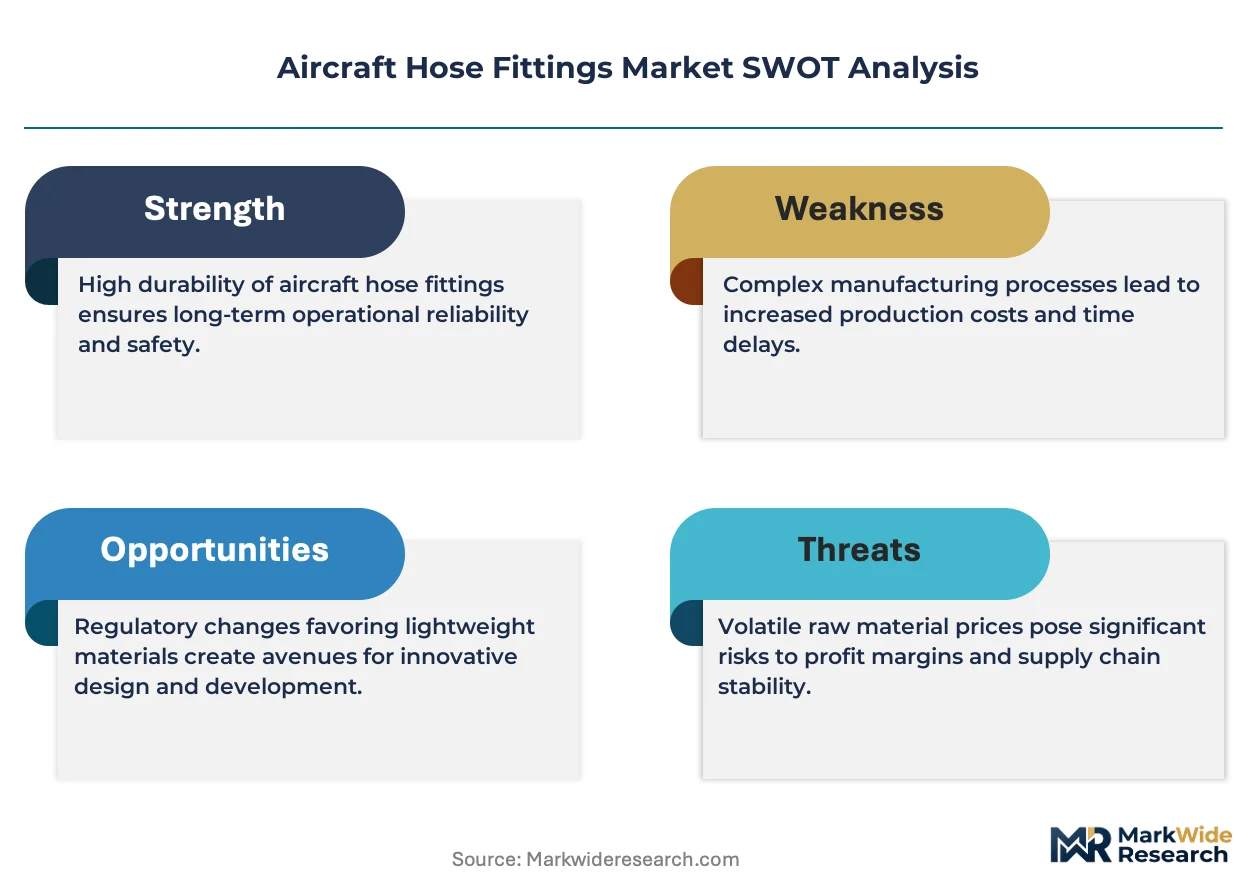
Titanium sponge supply disruptions from Russian sources compress margin structures for high-pressure fitting manufacturers while simultaneously widening price spreads between stainless steel commodity grades and aerospace-certified titanium alloys. This input volatility forces procurement officers at Boeing and Airbus to consolidate approved vendor lists, concentrating pricing power among vertically integrated fluid systems specialists who control captive seal compound production.
Pricing Analysis
Certification level creates the primary spread across the Aircraft Hose Fittings Market, with EASA Specification 100-14 compliant fuel system components commanding substantial premiums over standard hydraulic grades. The dominant structure runs contract-based long-term offtake agreements bundling hydraulic, fuel, and pneumatic components under single-source contracts negotiated by Lufthansa Technik and ST Engineering. Price differentiation hinges on fire-resistant specification tiers and mandatory traceability documentation, with fuel system applications showing least price sensitivity due to regulatory non-negotiability while low-pressure pneumatic fittings face acute cost compression from spot-buy aftermarket channels.
Supply Chain Analysis
ITAR and EAR export controls restrict flows of aerospace-grade titanium processing technology and precision machining equipment to qualified suppliers in the United States, Germany, and Japan. Raw material sourcing draws from Russian and Chinese sponge producers, Japanese mill product converters, and domestic aluminum alloy suppliers in the Pacific Northwest. Single-source vulnerability concentrates around aerospace-grade titanium sponge from disrupted Russian supply chains. Distribution runs through OEM-direct channels and authorized distributor networks consolidating procurement for commercial and defense operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Hose Fittings Market rewards suppliers who control scarce NDT technician pipelines and proprietary seal compound formulations, as qualified fluorescent penetrant inspection personnel shortages at FAA-certified repair stations create bottlenecks for stainless steel fitting validation.
For Market Incumbents: Pre-empt SAF compatibility retrofit cycles by qualifying alternative elastomeric seal compounds before sustainable aviation fuel mandates trigger fleet-wide replacement demand. Secure backward integration into captive titanium sponge sourcing through Japanese alternative suppliers to offset Russian supply disruption risks. Anchor specification-setting authority for next-generation narrow-body programs through long-term platform contracts with Boeing and Airbus. For New Entrants and Emerging Players: Middle Eastern MRO underpenetration offers white-space expansion as Emirates, Etihad, and Saudia establish captive heavy maintenance facilities in Dubai and Jeddah requiring localized hose fitting inventory. Target additive manufacturing qualification for low-volume AOG replacement parts, collapsing lead times that incumbent machined-product suppliers cannot match. Pursue vendor-managed inventory contracts with regional carriers operating coastal routes in Southeast Asia where titanium-aluminide coating adoption is accelerating. For Investors and Strategic Acquirers: Specialized fuel systems adapter producers with EASA Specification 100-14 documentation capabilities and established Middle Eastern operator relationships represent the most defensible acquisition archetype in this consolidating supplier landscape. Long-term viability rests on regulatory compliance moats rather than manufacturing scale advantages. Watch for inflection signals in sustainable aviation fuel blend mandates that would trigger accelerated retrofit cycles across installed hose fitting populations.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Compatibility Qualification | Pre-emptive seal compound testing with ASTM D4054 fuel blends secures retrofit contract positioning ahead of mandate deadlines. |
| Additive Manufacturing Certification | Laser powder bed fusion qualification for titanium hose fitting bodies collapses AOG lead times and opens aftermarket service contracts. |
| Blockchain Traceability Implementation | Cloud-based material certification platforms satisfy EASA Specification 100-14 audit protocols and differentiate premium suppliers. |
| Middle East MRO Localization | Dubai and Jeddah heavy maintenance facility partnerships capture wide-body fleet inventory demand from Emirates and Etihad. |
| Cadmium Plating Transition | Zinc-nickel and ion-vapor deposited aluminum surface treatment retooling maintains military specification product line viability. |
Methodological Framework
A spread of perspectives from fluid systems engineers at Boeing and Airbus, procurement directors at Lufthansa Technik and ST Engineering, NDT technicians at FAA-certified repair stations, and regulatory affairs specialists at EASA converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA airworthiness directives, EASA certification specifications, EPA REACH compliance filings, and customs trade data for aerospace-grade titanium sponge flows. Bottom-up build-ups from platform-specific hose fitting content per aircraft and top-down triangulation against OEM procurement disclosures anchored volume estimates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling across product type, material grade, application criticality, and end-user channel. The forecast incorporated narrow-body production rates at Renton and Toulouse, fleet age profiles driving aftermarket intensity, and regulatory phase-out timelines for hexavalent chromium surface treatments. CAGRs derived from fitted trend extrapolation adjusted for platform-specific qualification burdens and supplier consolidation effects.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed fluid systems entrants or accelerated SAF mandate timelines would shift outcomes. Material shifts in aerospace-grade titanium sponge supply geography or EASA documentation requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market