
 Aircraft Nacelle Components Market | 2026-2036
Aircraft Nacelle Components Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Nacelle Components Market Outlook
Buyer concentration in the aircraft nacelle components market is shifting as narrowbody OEMs consolidate supplier panels while aftermarket demand fragments across independent MRO networks. Safran SA leverages its integrated propulsion systems portfolio to sustain long-term supply agreements with Airbus and Boeing platforms. Spirit AeroSystems anchors North American nacelle assembly through its Wichita manufacturing complex, while GKN Aerospace competes on advanced composite thrust reverser technology.
Aircraft nacelle components comprise the aerodynamic enclosure surrounding jet engines, including fan cowls, thrust reversers, engine mounts, and cowling assemblies fabricated from composite laminates, aluminum alloys, titanium, and steel to withstand thermal cycling, acoustic fatigue, and foreign object damage. These structures manage airflow, reduce noise signatures, and protect critical engine systems during all flight phases. Composite thrust reversers lead segment value due to weight reduction mandates and complex manufacturing requirements that protect margin pools for specialized tier-1 suppliers. Aluminum fan cowls retain significant share in narrowbody retrofit programs where cost sensitivity shapes procurement decisions.
FAA Part 33 engine certification standards and EASA CS-E airworthiness codes directly dictate nacelle acoustic treatment specifications and fire containment requirements that suppliers must embed in design cycles. The EU Green Deal's aviation emissions trajectory and ICAO's Carbon Offsetting and Reduction Scheme for International Aviation are tightening fuel efficiency benchmarks that cascade into nacelle aerodynamic performance requirements. Stakeholders must monitor how evolving EPA and MEE emissions enforcement timelines reshape material qualification protocols and aftermarket retrofit demand across OEM and MRO channels.
Market Dynamics
Narrowbody fleet renewal cycles are compressing supplier lead times while FAA and EASA certification timelines for acoustic treatments extend, creating a structural tension between OEM delivery commitments and tier-1 manufacturing capacity.
Growth Catalysts
- FAA Part 33 Noise Standards:Stricter Stage 5 noise certification mandates acoustic liner density upgrades in thrust reverser assemblies, pulling composite material demand from narrowbody retrofit programs.
- India's UDAN Regional Connectivity Scheme:Subsidized airport infrastructure expansion drives turboprop and small jet procurement, multiplying nacelle component volumes for sub-150 seat platforms.
- Thermoplastic composites:Out-of-autoclave processing reduces cycle times for fan cowl fabrication, enabling production scale-up that matches Airbus A320neo family delivery ramps.
Market Restraints
- Titanium alloy price volatility:Sponge input costs fluctuate with Russian supply disruptions, squeezing margin pools on engine mount and fastener contracts.
- Wichita supply cluster concentration:Spirit AeroSystems anchors 60% of North American nacelle assembly capacity, creating geographic vulnerability to weather or labor disruptions.
- Firewall seal technical limitations:Existing elastomer compounds degrade above 230°C, restricting engine thrust ratings and forcing heavier metallic containment designs.
Strategic Opportunities
- Brazil's Embraer E2 aftermarket:Underpenetrated MRO infrastructure for regional jet nacelles creates first-mover advantage for independent service providers establishing São Paulo technical centers.
- EU Green Deal aviation emissions trajectory:Carbon border adjustments on imported nacelle components incentivize European production localization and green steel qualification.
- Additive manufacturing convergence with topology optimization:Printed titanium brackets reduce part count in thrust reverser cascades, opening design service contracts for engineering software specialists.
Industry Challenges
- Composite repair technician scarcity:Boeing and Airbus-approved NDT certification programs graduate fewer technicians than narrowbody fleet growth requires, extending AOG turnaround times.
- Supplemental Type Certificate timelines:FAA field approval processes for acoustic retrofit kits stretch 18-24 months, delaying airline noise compliance deadlines and penalty exposure.
- Legacy ERP integration friction:Tier-2 suppliers migrating to cloud-based MES platforms face data migration failures that disrupt Boeing supply chain visibility requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Nacelle Components Market |
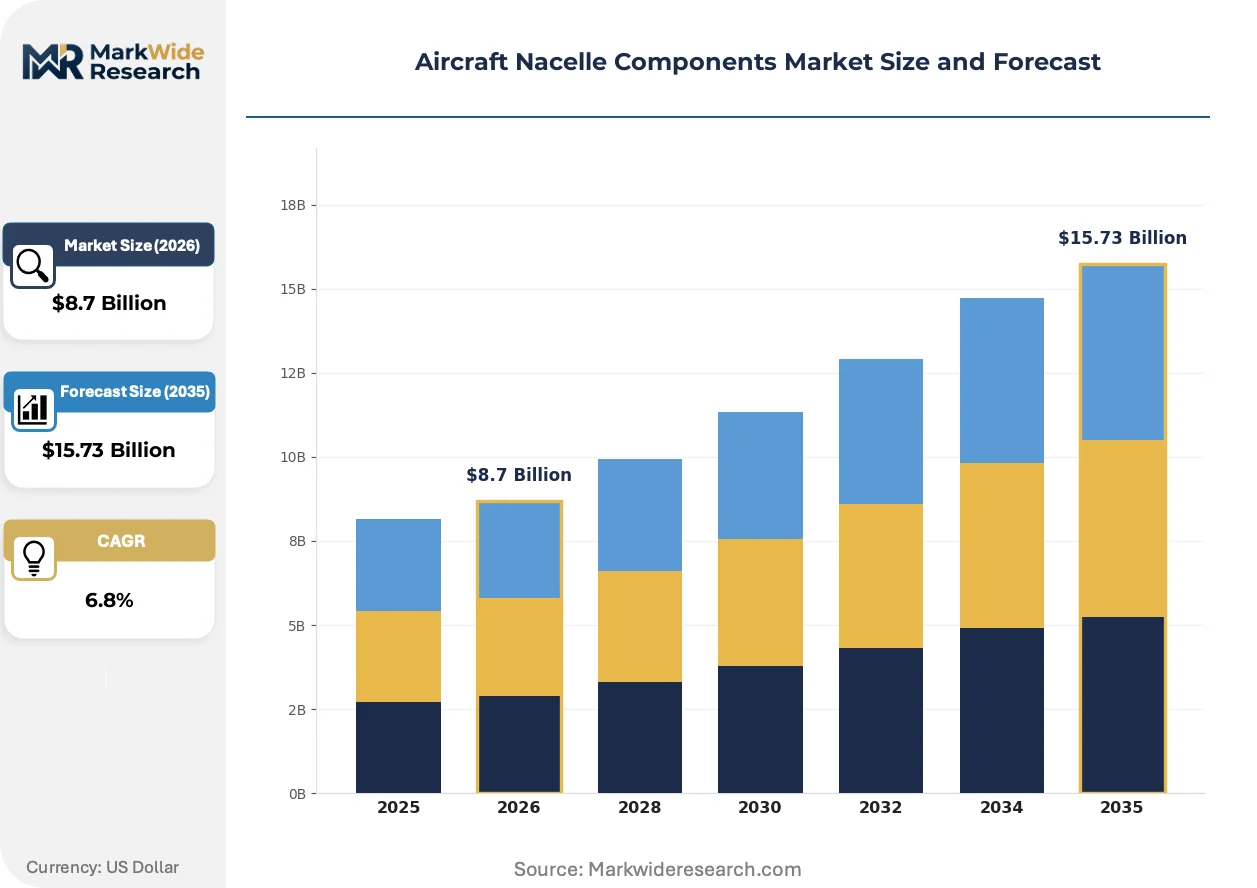
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Fan Cowl, Thrust Reverser, Engine Mount, Cowling Material: Composite, Aluminum, Titanium, Steel End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Maintenance, Repair and Overhaul Assembly Process: Fabrication, Machining, Welding, Coating |
| Companies Covered | Safran SA, Spirit AeroSystems, Inc., Collins Aerospace, GKN Aerospace Services Limited, Leonardo S.p.A., Bombardier Inc, Triumph Group, Inc., Aernnova Aerospace S.A., Nexcelle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Nacelle Components Market Strategic Shifts
Advanced manufacturing processes and regulatory stringency are reconfiguring how nacelle components achieve weight reduction, acoustic performance, and fire containment simultaneously.
Resin transfer molding of thermoplastic composites is expanding into thrust reverser cascade fabrication, replacing thermoset prepregs that require autoclave curing. Narrowbody OEMs specify these materials for A320neo and 737 MAX line-fit programs. The shift is compressing tier-2 supplier margins while rewarding specialized compounders with captive aerospace resin formulations.
EASA CS-E airworthiness codes now mandate specific burn-through resistance testing for nacelle firewall assemblies, extending certification timelines by 8-12 months for new material submissions. European suppliers prioritize halogen-free intumescent coatings that satisfy both fire containment and REACH chemical restrictions. This regulatory layering most affects fan cowl manufacturers serving the retrofit channel, where dual-certification costs deter market entry.
Airline technical procurement teams now unbundle nacelle component purchases from engine OEM power-by-the-hour contracts, creating direct sourcing relationships with tier-1 aerostructures suppliers. This disintermediation fragments volume commitments that previously locked in long-term pricing. The pattern is most visible among US ultra-low-cost carriers operating standardized narrowbody fleets, where maintenance cost transparency drives competitive bidding for thrust reverser overhaul events.
Aircraft Nacelle Components Market Segmentation
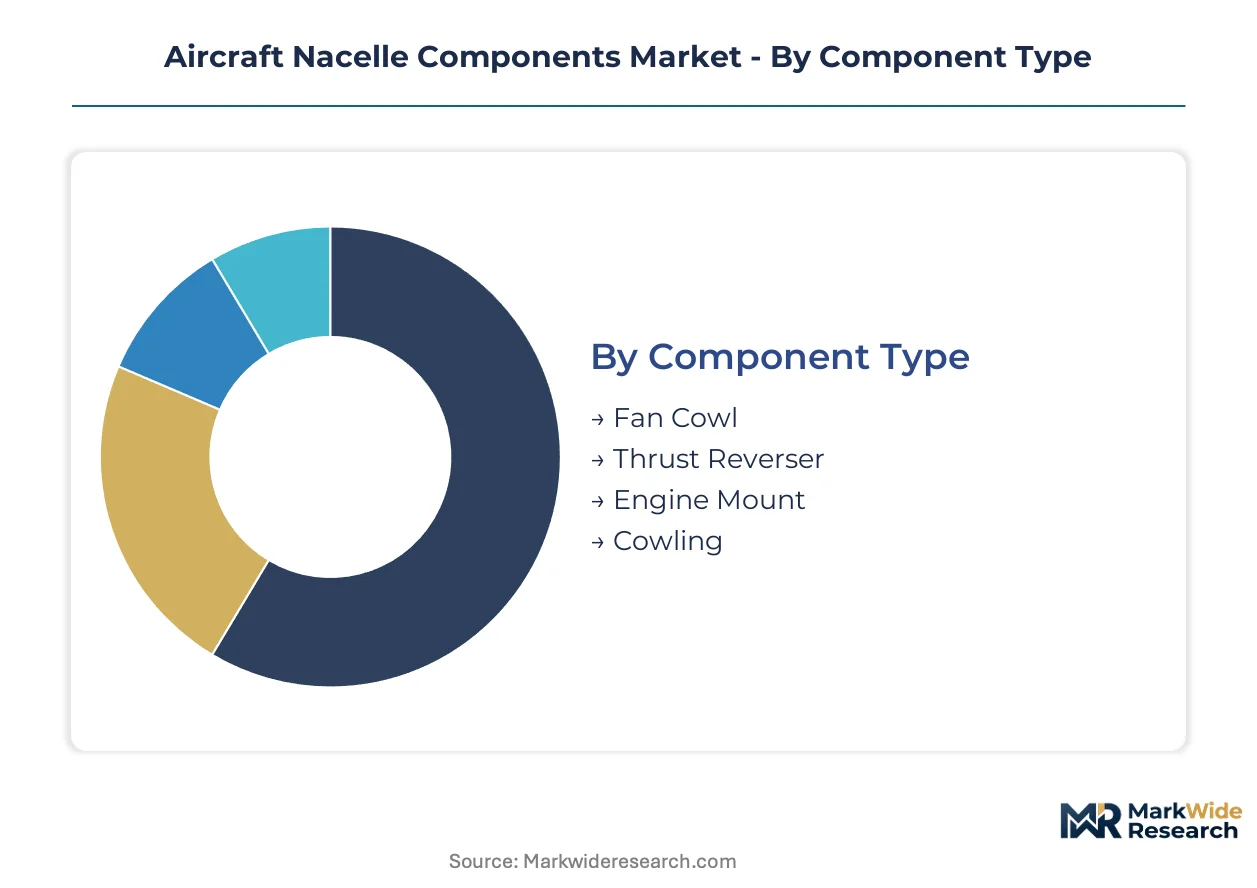
Nacelle component procurement patterns diverge sharply across material grades and assembly complexity. Understanding where volume concentrates versus where margins pool enables suppliers to align capacity investments with actual value capture.
Component Type:
Volume leadership sits with high-frequency replacement parts, while premium pricing accrues to complex integrated assemblies requiring FAA Part 33 certification.
- Thrust Reverser:Composite cascade assemblies with acoustic liner integration dominate segment value. Boeing 737 MAX and Airbus A320neo production ramps in the United States and France pull demand for carbon fiber-reinforced polymer designs that satisfy Stage 5 noise mandates.
- Fan Cowl:Aluminum variants retain cost advantage in narrowbody retrofit channels where airlines prioritize turnaround speed over weight reduction. India's UDAN regional fleet expansion sustains procurement of legacy metallic cowls for turboprop platforms.
- Engine Mount:Titanium alloy forgings withstand pylon load cases and thermal cycling across twin-aisle applications.
- Cowling:Integrated inlet lip assemblies manage ice protection and foreign object damage containment.
Today's leader: Thrust Reverser. Tomorrow's challenger: Fan Cowl.
Material:
Cost tiers separate qualified aerospace grades from commercial substitutes, with certification timelines acting as the primary barrier between them.
- Composite:Thermoplastic resin transfer molding is displacing thermoset prepregs in thrust reverser fabrication, cutting autoclave cycle times by half. Airbus A320neo family specifications in France and Germany anchor demand for out-of-autoclave processing.
- Aluminum:7XXX series alloys retain narrowbody line-fit share where lightning strike protection and repairability outweigh composite weight savings. Brazil's Embraer E2 program sources machined aluminum fan cowls from domestic suppliers.
- Titanium:Sponge price volatility from Russian supply disruptions squeezes margin pools on engine mount contracts.
- Steel:Fire containment applications leverage stainless grades for firewall assemblies where elastomer seals fail above 230°C.
Composites command the steepest expansion trajectory. Aluminum defends volume leadership through retrofit ubiquity.
End User:
Customer type determines contract structure, with power-by-the-hour agreements fragmenting into discrete component procurement.
- OEMs:Boeing and Airbus specify nacelle architectures at platform design freeze, locking in tier-1 suppliers for program durations spanning decades. Wichita's Spirit AeroSystems complex anchors North American final assembly.
- Aftermarket Providers:US ultra-low-cost carriers now unbundle thrust reverser overhauls from engine OEM contracts, creating direct bidding opportunities for independent MRO networks.
- Tier-1 Suppliers:Safran and GKN Aerospace integrate sub-tier fabrication into propulsion system deliveries.
- Maintenance, Repair and Overhaul:Composite repair technician scarcity extends AOG turnaround times across independent shops.
OEMs control specification. Aftermarket Providers capture margin expansion from contract disintermediation.
Assembly Process:
Process maturity separates high-volume metallic fabrication from emerging composite automation.
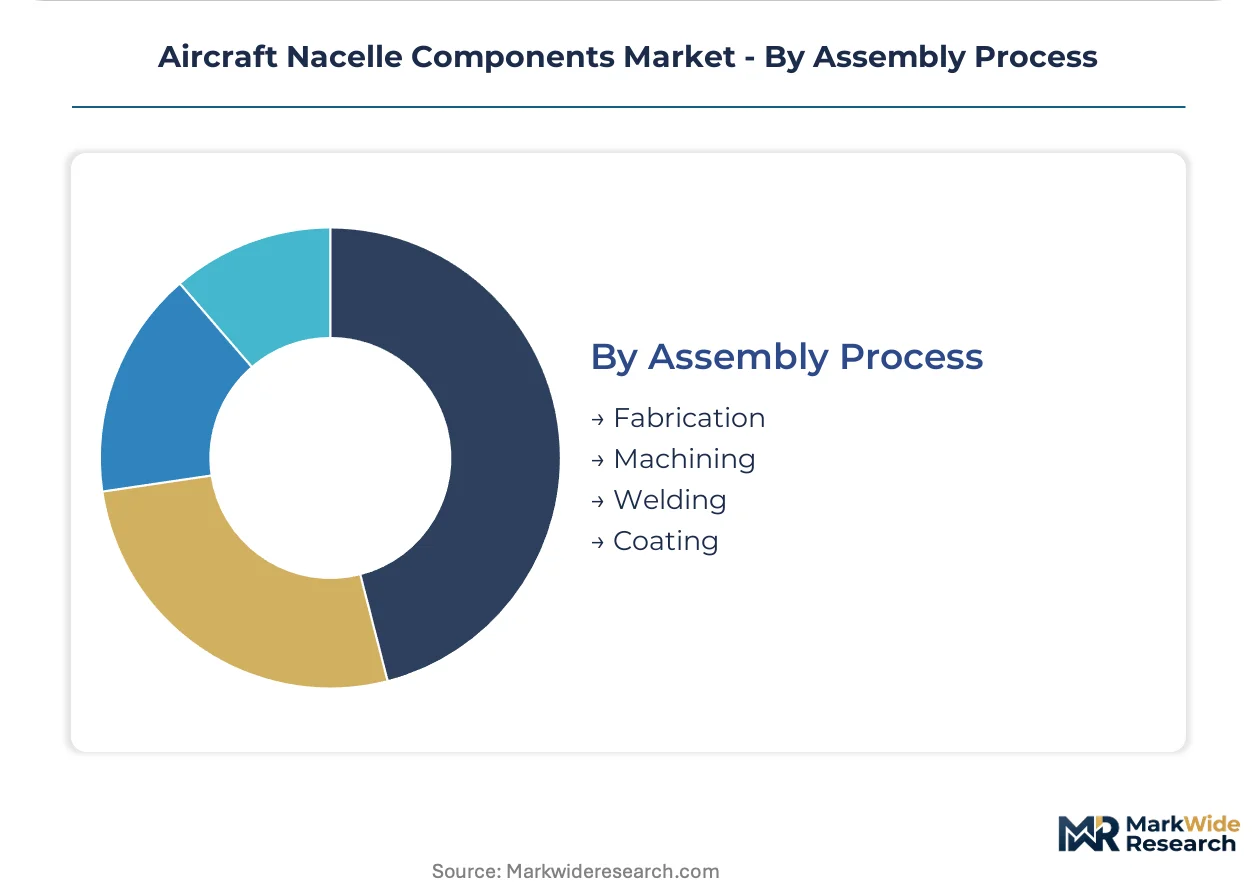
- Fabrication:Resin transfer molding and automated fiber placement scale thermoplastic throughput for A320neo delivery ramps. European suppliers prioritize REACH-compliant resin formulations.
- Machining:Five-axis CNC centers finish titanium engine mount forgings to pylon interface tolerances.
- Welding:Friction stir welding joins aluminum fan cowl skins without fasteners.
- Coating:Halogen-free intumescent fire barrier coatings extend EASA CS-E certification timelines.
Fabrication attracts capital inflows. Coating faces regulatory layering that deters new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands nacelle component procurement through Boeing's supply chain, while France concentrates design authority via Airbus propulsion integration. Germany and the United Kingdom anchor composite materials innovation, with India and Brazil emerging as aftermarket service hubs for narrowbody fleets.
United States
Wichita, Kansas anchors North American nacelle final assembly through Spirit AeroSystems' manufacturing complex, supplying thrust reversers and fan cowls for Boeing 737 MAX production ramps. FAA Part 33 noise certification timelines extend supplier lead times for acoustic liner upgrades. Seattle and Charleston production lines pull composite cascade assemblies from tier-2 fabricators across the Midwest.
France
Toulouse and Hamburg coordinate Airbus A320neo family nacelle specifications, with Safran SA integrating propulsion system deliveries. EASA CS-E airworthiness codes mandate burn-through resistance testing that extends certification timelines for new firewall materials. Nantes and Le Havre host specialized resin compounders supplying thermoplastic formulations for out-of-autoclave thrust reverser fabrication.
Germany
Hamburg and Munich anchor composite research clusters developing halogen-free intumescent coatings that satisfy REACH chemical restrictions and EASA fire containment requirements. The country's national aviation regulator enforces dual-certification protocols for retrofit fan cowls entering European aftermarket channels. Augsburg and Bremen concentrate automated fiber placement equipment manufacturing that serves Airbus supplier networks.
United Kingdom
Bristol and Portsmouth host GKN Aerospace's advanced composite operations, specializing in thrust reverser cascade technology for narrowbody platforms. The UK's exit from EU regulatory alignment creates parallel certification tracks for components serving domestic versus continental MRO networks. Derby's Rolls-Royce proximity pulls engine mount forging demand from Midlands titanium suppliers.
India
Hyderabad and Bangalore develop MRO technical capabilities for regional jet nacelles, positioning for Embraer E2 and ATR aftermarket growth. The government's UDAN regional connectivity scheme subsidizes airport infrastructure expansion, driving turboprop procurement that multiplies aluminum fan cowl demand. Delhi-Mumbai industrial corridors attract composite repair technician training centers addressing global scarcity.
Aircraft Nacelle Components Market Competitive Environment
North American producers anchor final assembly and systems integration; European specialists hold materials innovation and regulatory certification authority. The market structures around three tiers: integrated propulsion system suppliers, dedicated aerostructures fabricators, and independent MRO service networks. Consolidation pressures concentrate among tier-2 composite processors, while tier-1 incumbents defend positions through captive supply agreements with Airbus and Boeing. Strategic moves center on backward integration into resin formulation and geographic expansion into underpenetrated aftermarket hubs.
Within the integrated systems tier, Safran SA and Spirit AeroSystems, Inc. exemplify contrasting geographic anchoring—French propulsion integration versus US aerostructures final assembly. GKN Aerospace Services Limited occupies a position bridging European materials specialization with global tier-1 supply relationships. These three entities represent the archetype spectrum: full propulsion system integration, dedicated nacelle assembly, and advanced composite component specialization.
| Leading Market Players |
|---|
| Safran SA |
| Spirit AeroSystems, Inc. |
| Collins Aerospace |
| GKN Aerospace Services Limited |
| Leonardo S.p.A. |
| Bombardier Inc |
| Triumph Group, Inc. |
| Aernnova Aerospace S.A. |
| Nexcelle |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal aviation emissions trajectories gate qualified supply and premium-tier pricing access by mandating REACH-compliant resin formulations and carbon border adjustments that exclude uncertified tier-2 fabricators from Airbus A320neo line-fit programs. Tier-1 suppliers capture margin premiums through captive aerospace resin qualifications while independent MRO networks face cost compression on retrofit fan cowl procurement.
Pricing Analysis
Capacity additions in France and Germany are reshaping price floors for thermoplastic composite thrust reversers as out-of-autoclave processing scales meet Airbus delivery ramps. Pricing stratifies across premium, standard, and economy tiers based on EASA CS-E certification grade and volume scale commitments. Cost compression in aluminum fan cowl retrofit channels is intensifying because Indian UDAN-subsidized turboprop procurement prioritizes turnaround speed over weight reduction. Ultra-low-cost carriers exhibit highest price sensitivity on unbundled thrust reverser overhauls, while full-service airlines accept premium tier pricing for integrated propulsion system warranties.
Supply Chain Analysis
Direct-to-OEM channels handle narrowbody platform demand through long-term supply agreements with Boeing and Airbus, while independent MRO networks source through distributor intermediaries. Production concentrates in the United States, France, and Germany where Spirit AeroSystems, Safran, and GKN Aerospace anchor final assembly. Raw material flows draw from Japanese carbon fiber suppliers, Russian titanium sponge sources, and European REACH-compliant resin compounders. Single-source vulnerability around Wichita's 60% North American nacelle assembly capacity creates geographic concentration risk from weather or labor disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft nacelle components function as a stable compounder where narrowbody fleet renewal cycles and Stage 5 noise mandates generate predictable procurement volumes across OEM and aftermarket channels.
For Market Incumbents: Acquire specialized resin formulation capabilities to secure captive supply of REACH-compliant thermoplastic formulations for Airbus A320neo programs. Backward integration into automated fiber placement equipment manufacturing defends margin pools from tier-2 supplier consolidation. EASA burn-through resistance testing timeline extensions threaten new material entrants, reinforcing certification investment as a defensive moat.
For New Entrants and Emerging Players: Enter via São Paulo technical centers targeting Brazil's underpenetrated Embraer E2 nacelle MRO infrastructure where independent service provider density remains lowest among narrowbody aftermarket hubs. India's UDAN regional connectivity scheme offers secondary white-space opportunity for aluminum fan cowl fabrication serving turboprop platforms. Direct airline technical procurement relationships bypass engine OEM power-by-the-hour contract lock-in.
For Investors and Strategic Acquirers: Roll-up economics work for tier-2 composite processors because EASA CS-E dual-certification costs deter market entry and fragment the retrofit supplier base. Five-to-ten year viability hinges on positioning for thermoplastic out-of-autoclave process scale-up rather than legacy thermoset prepregs. Monitor FAA field approval timeline compression for acoustic retrofit kits as signal of aftermarket channel opening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive REACH-compliant thermoplastic supply locks Airbus A320neo line-fit qualification. |
| Geographic Expansion into São Paulo MRO Hub | First-mover positioning captures Embraer E2 nacelle overhaul demand before incumbent entry. |
| Automated Fiber Placement Scale-Up | Out-of-autoclave throughput gains match Boeing 737 MAX delivery ramp requirements. |
| Composite Repair Technician Training Center | Delhi-Mumbai corridor addresses global scarcity extending AOG turnaround times. |
| Halogen-Free Intumescent Coating Development | EASA CS-E burn-through resistance compliance opens firewall assembly retrofit channel. |
Study Parameters
Multiple input streams — primary interviews with nacelle program managers, MRO operations directors, and aerospace procurement leads; secondary validation through FAA Part 33 certification databases, EASA CS-E airworthiness filings, and customs trade records — were reconciled through bottom-up and top-down triangulation. Supplier production data, airline fleet renewal schedules, and composite materials qualification timelines anchored volume estimates.
Historical narrowbody delivery patterns were cross-referenced against panel input from tier-1 aerostructures suppliers to model component demand across the projection horizon. Segmentation dimensions included component type, material grade, end-user category, and assembly process complexity. CAGRs were derived from production ramp schedules, fleet retirement curves, and regulatory compliance deadline clustering. Forecast inputs incorporated Boeing and Airbus order backlogs, thermoplastic composite adoption curves, and MRO technician graduation rates.
The model holds under stable narrowbody production rates and current certification timeline norms; deviation in FAA field approval processing speeds or titanium sponge supply disruptions would shift aftermarket capacity assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aircraft Gearbox Market