
 Aerospace Nuts Market | 2026-2036
Aerospace Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Nuts Market Analysis
Asset-light leasing structures for specialized forging equipment is reconfiguring capital deployment across tier-two and tier-three fastener suppliers. LISI Aerospace leverages captive titanium processing in France to sustain margin control on aerospace-grade lock nuts. Precision Castparts Corp. anchors its position through backward integration into superalloy melt operations for engine-attached hardware. TriMas Aerospace differentiates via dedicated production cells serving rotorcraft OEMs with lower minimum order quantities.
Aerospace nuts are internally threaded fasteners manufactured to precise torque specifications, typically from titanium alloys, A286 superalloy, or 2024-T4 aluminum bar stock via cold heading and thread rolling processes. These components secure primary structural joints, engine mounts, and control surface attachments under cyclic vibration and thermal stress. Hex nuts and lock nuts together command the largest share of unit volume, though titanium material grades capture disproportionate value given their deployment in engine compartments and landing gear assemblies. Commercial aviation applications generate the dominant revenue stream, while spacecraft programs represent the fastest-growing segment as launch cadence intensifies.
FAA airworthiness directives and EASA Part 21 design certification rules mandate full lot traceability and mechanical testing for flight-critical fasteners. AS9100 quality standards and NAS/ASTM dimensional specifications further constrain supplier qualification timelines, creating structural barriers for new entrants. Stakeholders must monitor evolving EPA and REACH restrictions on hexavalent chromium plating processes used for corrosion protection. The interplay between OEM consolidation in final assembly and regulatory burden on component certification will determine which suppliers secure long-term platform positions.
Market Dynamics
Commercial aviation OEMs are consolidating fastener procurement under platform-specific master service agreements, concentrating volume among suppliers with captive titanium melt capacity and AS9100 certification across multiple production sites.
Growth Catalysts
- FAA Airworthiness Directives:Tightened material traceability mandates for flight-critical hardware are disqualifying uncertified suppliers and expanding contract volumes for qualified tier-one manufacturers.
- Titanium alloy substitution:Narrow-body and wide-body programs are specifying Ti-6Al-4V nuts for engine mounts and landing gear to achieve weight reduction targets.
- Launch cadence acceleration:Reusable rocket programs in the United States and China are multiplying spacecraft fastener demand beyond traditional satellite procurement cycles.
Market Restraints
- Titanium sponge supply concentration:Over half of aerospace-grade titanium feedstock originates from Russian and Ukrainian producers, exposing the supply chain to geopolitical disruption.
- AS9100 certification timelines:New entrants face 18-24 month qualification periods before securing OEM-approved supplier status.
- Hexavalent chromium restrictions:EPA and REACH regulations on cadmium and chromate conversion coatings are forcing costly process requalification for corrosion protection.
Strategic Opportunities
- Urban air mobility platforms:eVTOL manufacturers in the United States require specialized lightweight lock nuts with lower minimum order quantities than traditional aviation programs.
- India defense localization:Indigenization mandates under the Make in India initiative are creating openings for joint ventures with domestic forging operations.
- Additive manufacturing convergence:Hybrid production combining cold heading with selective laser melting enables complex internal geometries for torque-limiting features.
Industry Challenges
- Metallurgical technician scarcity:Qualified personnel for titanium alloy heat treatment and mechanical testing are concentrated among retiring workforces in France and the United States.
- Legacy ERP integration:Full lot traceability requirements are forcing mid-tier suppliers to replace paper-based quality systems with integrated MES platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Nuts Market |
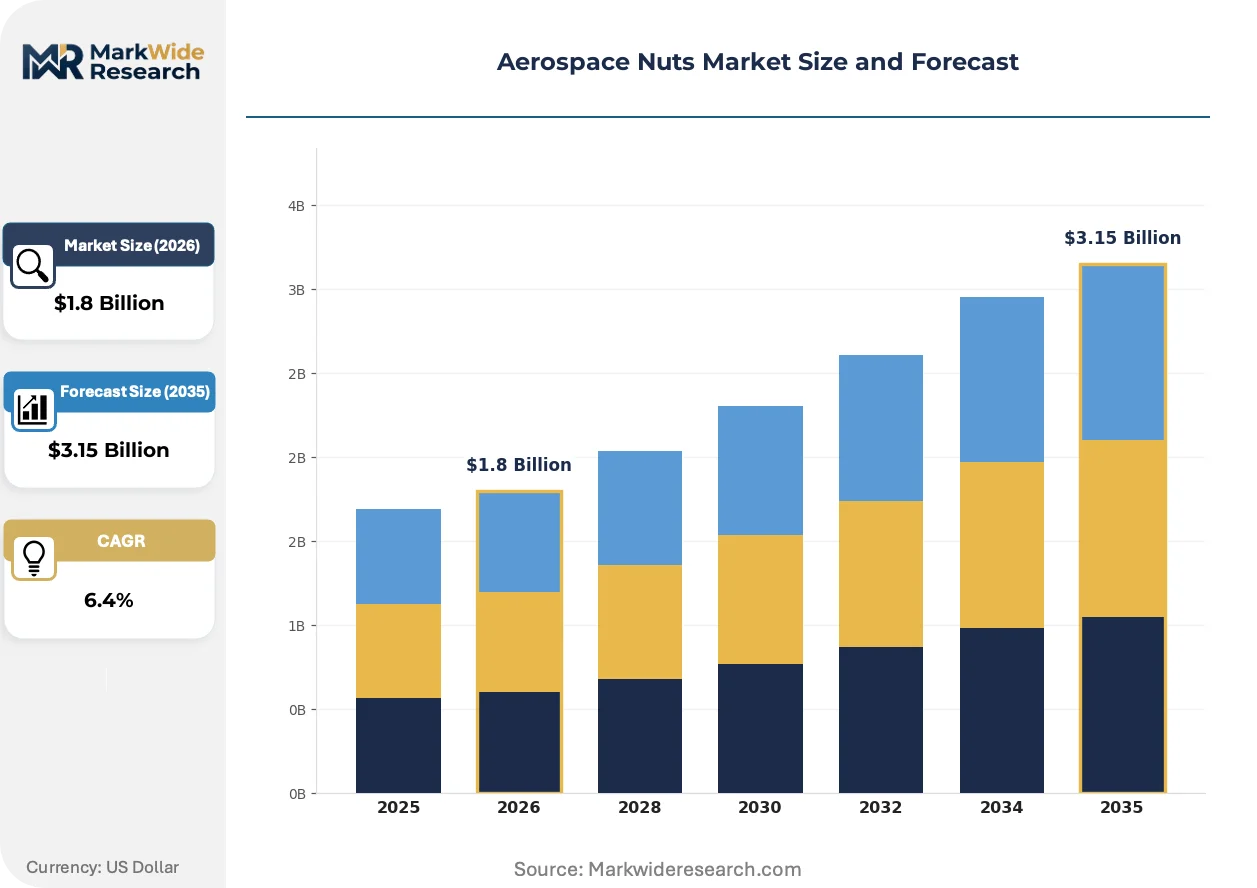
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hex Nuts, Lock Nuts, Wing Nuts, Cap Nuts Material: Aluminum, Titanium, Steel, Brass Application: Commercial Aviation, Military Aircraft, Spacecraft, Rotorcraft Standard: ISO, ASME, NAS, ASTM |
| Companies Covered | LISI Aerospace, Arconic Inc., Precision Castparts Corp., TriMas Aerospace, Howmet Aerospace Inc., National Aerospace Fasteners Corp., B&B Specialties Inc., Stanley Black & Decker, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Nuts Market Emerging Trajectories
Material science advances and digital quality systems are compressing development cycles for aerospace-grade fasteners while regulatory pressure on surface treatments accelerates process substitution.
Additive manufacturing of near-net-shape titanium preforms is collapsing lead times for complex lock nut geometries previously requiring multi-step machining. Spacecraft OEMs in the United States are qualifying these parts for non-structural applications within 12-month cycles. The technology is collapsing the traditional barrier between prototype and production tooling investment.
REACH authorization requirements for hexavalent chromium compounds are compelling European suppliers to transition to trivalent chrome and zinc-nickel plating systems. Surface treatment houses in France and Germany are absorbing six-figure requalification costs per OEM platform. Engine-attached hardware categories face the most compressed transition timelines due to thermal performance specifications.
Long-term pricing agreements indexed to titanium sponge commodity benchmarks are displacing spot purchasing for high-volume commercial aviation programs. Tier-one distributors in the United States are consolidating inventory positions under vendor-managed stock arrangements. Rotorcraft OEMs remain the holdout segment, continuing project-based procurement with shorter commitment horizons.
Aerospace Nuts Market Segmentation
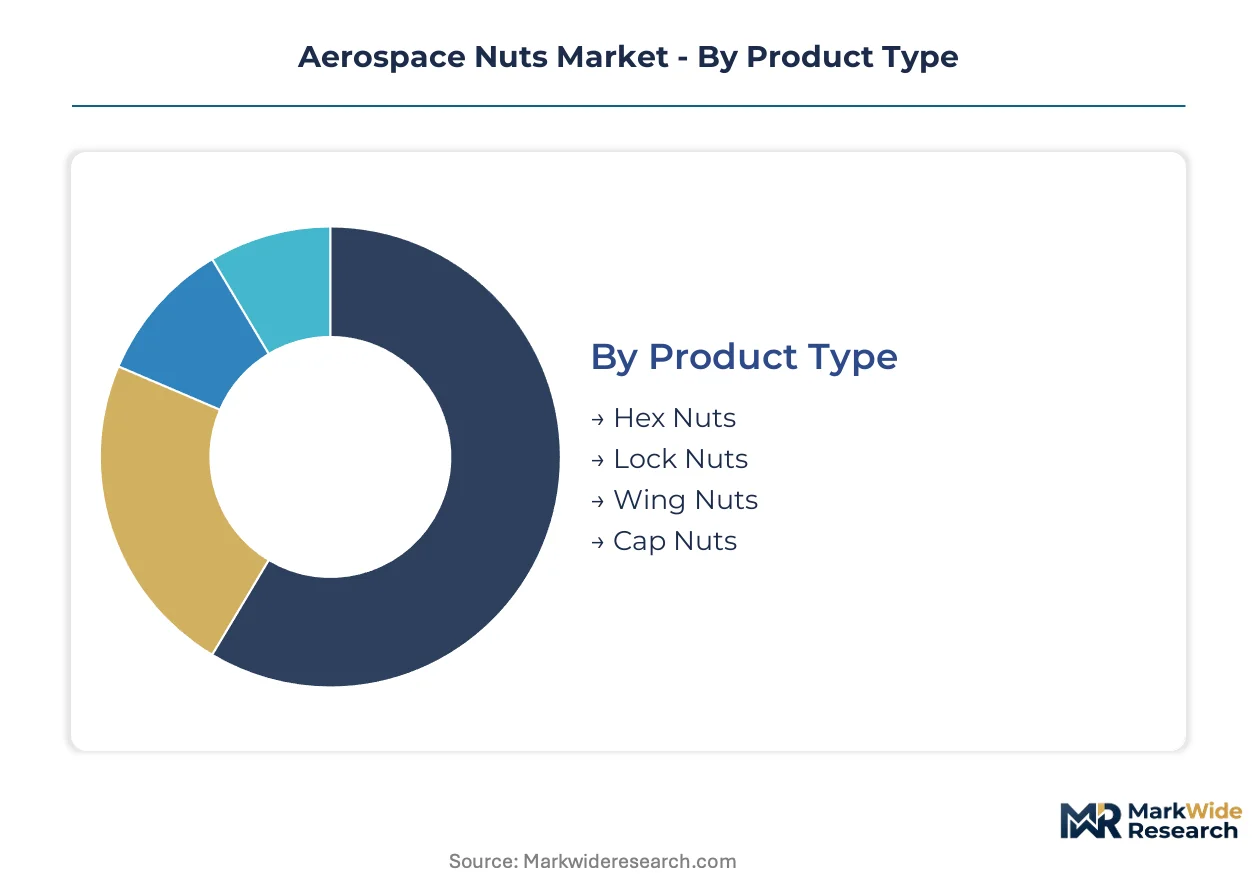
Aerospace nut procurement splits across multiple technical dimensions that determine qualification pathways and margin structures. OEM specification sheets simultaneously filter by material grade, fastener geometry, and airworthiness standard, creating intersecting demand clusters rather than isolated segments.
Product Type:
Fastener geometry dictates installation torque requirements and vibration resistance profiles across airframe assemblies.
- Hex Nuts:Six-sided standard fasteners manufactured to NAS/ASME torque specifications secure primary structural joints in fuselage and wing assemblies. Commercial aviation final assembly lines in the United States and France consume the largest contract volumes for Ti-6Al-4V and A286 variants under multi-year platform agreements.
- Lock Nuts:Prevailing torque designs with nylon inserts or all-metal deformation features prevent loosening under cyclic vibration in engine mounts and landing gear. LISI Aerospace's captive titanium processing in France targets this category for margin control on aerospace-grade specifications.
- Wing Nuts:Tool-free hand-tightening designs serve inspection panels and maintenance access points with lower torque requirements.
- Cap Nuts:Domed heads protect exposed threads on control surface linkages and external hardware from environmental corrosion.
Hex nuts command the established base. The steepest expansion runs through lock nuts as engine-attached hardware specifications tighten.
Material:
Alloy selection traces directly to weight reduction targets and thermal operating environments in specific aircraft zones.
- Titanium:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades deliver strength-to-weight ratios critical for engine compartments and landing gear assemblies. Narrow-body and wide-body programs in the United States specify these alloys aggressively for fuel efficiency compliance.
- Aluminum:2024-T4 and 7075-T6 bar stock via cold heading produces lightweight fasteners for secondary structures and interior applications. Chinese final assembly lines for commercial narrow-body aircraft drive regional procurement concentration.
- Steel:A286 superalloy and precipitation-hardened grades withstand extreme thermal stress in exhaust-adjacent hardware.
- Brass:Corrosion-resistant compositions serve electrical bonding and instrumentation mounting with lower mechanical load requirements.
Titanium anchors the value concentration. Aluminum is climbing the fastest as Chinese production scales.
Application:
End-use programs impose distinct certification timelines, volume profiles, and technical risk tolerances on suppliers.
- Commercial Aviation:Narrow-body and wide-body aircraft production generates the dominant revenue stream through multi-year master service agreements. Boeing and Airbus final assembly lines in the United States, France, and China operate at full capacity with consolidated procurement under platform-specific contracts.
- Spacecraft:Reusable rocket programs in the United States and China multiply fastener demand beyond traditional satellite procurement cycles. Additive manufacturing qualification for titanium lock nuts is collapsing 12-month development timelines in this segment.
- Military Aircraft:Defense procurement cycles in India under Make in India indigenization mandates are creating joint venture openings with domestic forging operations.
- Rotorcraft:Lower volume requirements and specialized torque specifications sustain project-based procurement with shorter commitment horizons than fixed-wing programs.
Commercial aviation commands the established base. Spacecraft is gaining share fastest as launch cadence intensifies.
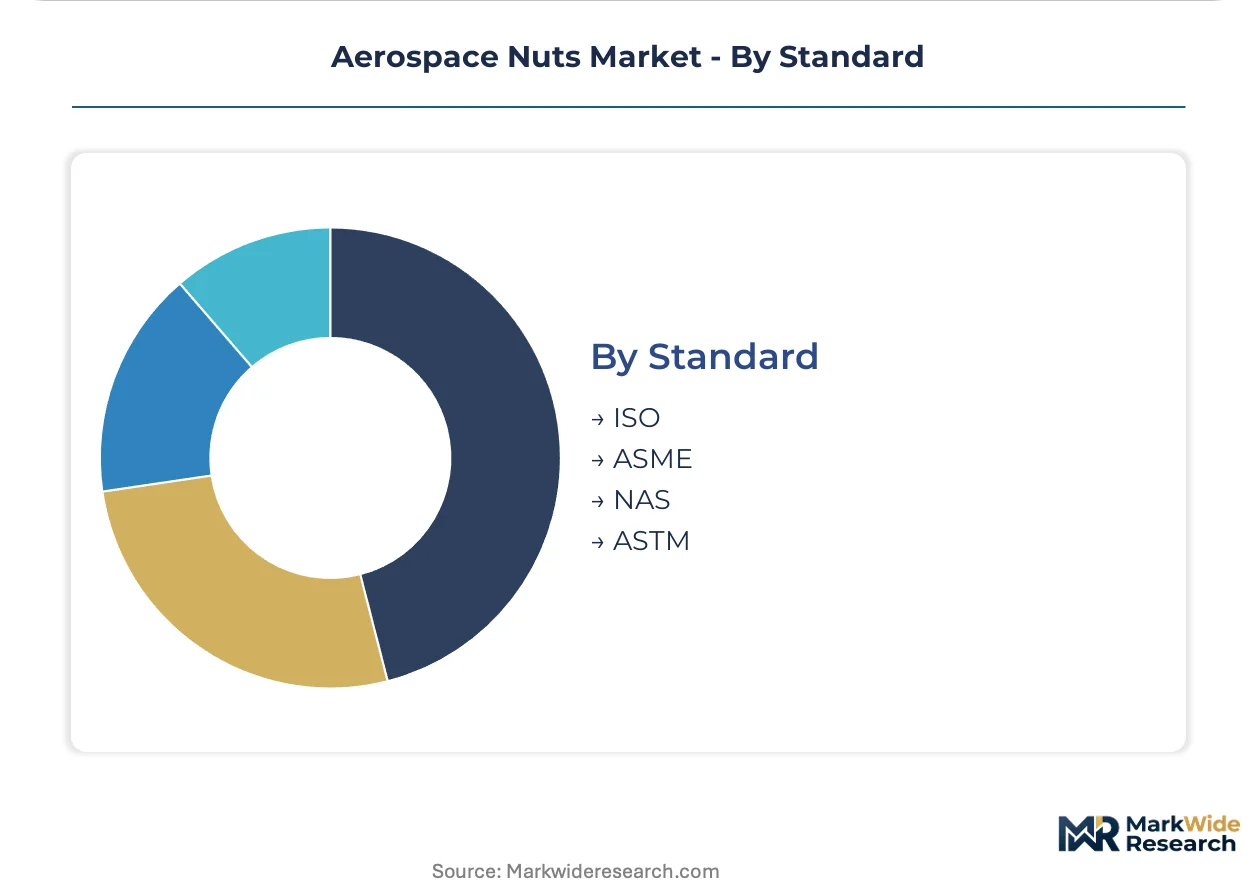
Standard:
Certification frameworks determine supplier qualification barriers and geographic market access.
- NAS:National Aerospace Standards dimensional specifications govern flight-critical hardware for United States defense and commercial programs. AS9100 quality system certification across multiple production sites is mandatory for tier-one supplier status.
- ASME:American Society of Mechanical Engineers codes anchor commercial aviation procurement in North American supply chains.
- ASTM:Material testing protocols provide baseline mechanical property verification across international supplier bases.
- ISO:International Organization for Standardization frameworks facilitate cross-border qualification for European and Asia-Pacific OEMs.
NAS specifications command the established base. ISO is expanding most quickly as supplier bases internationalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in aerospace fasteners track final assembly line locations, with the United States, France, and China running structural deficits in titanium hardware that suppliers in Japan and Germany offset through specialized forging exports.
United States
Boeing's 737 MAX and 787 production lines in Washington and South Carolina drive concentrated procurement of Ti-6Al-4V lock nuts for engine mounts and landing gear assemblies. FAA airworthiness directives mandate AS9100 certification and full lot traceability, disqualifying uncertified foreign suppliers from flight-critical contracts. The Seattle-Tacoma aerospace cluster hosts tier-one fastener distributors operating vendor-managed inventory programs for narrow-body programs.
France
Airbus final assembly in Toulouse and Saint-Nazaire generates premium-tier demand for A286 superalloy and titanium fasteners across A320 and A350 platforms. EASA Part 21 design certification rules enforce material traceability standards matching FAA stringency. LISI Aerospace's captive titanium processing operations in the Rhône-Alpes region supply lock nuts directly to engine OEMs, bypassing spot market volatility.
China
COMAC C919 narrow-body production in Shanghai and ARJ21 regional jet assembly in Xi'an scale procurement of 2024-T4 aluminum and titanium fasteners for domestic aviation programs. MIIT national standards and GB certification frameworks are converging toward AS9100 equivalence to qualify suppliers for international contracts. The Yangtze River Delta cluster concentrates cold-heading capacity serving both commercial aviation and spacecraft programs.
Japan
Mitsubishi Heavy Industries and Subaru Corporation aerospace divisions in Aichi and Gifu prefectures import specialized titanium lock nuts for regional jet and defense programs. METI industrial policy supports domestic superalloy forging capacity to reduce dependency on foreign fastener sources. The Nagoya aerospace corridor maintains technical partnerships with US and European tier-one suppliers for heat-resistant engine hardware.
India
Indigenization mandates under the Make in India initiative redirect fastener procurement toward joint ventures with domestic forging operations for Tejas fighter and Dhruv helicopter programs. DGFT import substitution rules and BIS quality certifications create qualification pathways for foreign suppliers establishing local production. The Bangalore-Hyderabad defense manufacturing corridor hosts emerging tier-two suppliers targeting rotorcraft and unmanned aerial system hardware.
Aerospace Nuts Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in forging, heat treatment, and surface finishing. The supplier base concentrates among AS9100-certified manufacturers with captive titanium melt capacity or backward integration into superalloy operations. Three archetypes dominate: vertically integrated majors controlling raw material through final fastener, specialized forging houses serving single OEM platforms, and precision distributors managing vendor-managed inventory for maintenance operations. Competitive positioning hinges on multi-site certification coverage and long-term pricing agreements indexed to titanium sponge benchmarks.
Among French and US-based integrated suppliers, LISI Aerospace, Precision Castparts Corp., and TriMas Aerospace exemplify divergent strategic postures. LISI Aerospace represents the captive-processing archetype through in-house titanium operations. Precision Castparts Corp. anchors the superalloy-integrated tier with upstream melt capacity. TriMas Aerospace occupies the specialized-cell position serving rotorcraft OEMs with flexible order quantities. Each structure reflects distinct risk allocation between material price exposure and customer concentration.
| Leading Market Players |
|---|
| LISI Aerospace |
| Arconic Inc. |
| Precision Castparts Corp. |
| TriMas Aerospace |
| Howmet Aerospace Inc. |
| National Aerospace Fasteners Corp. |
| B&B Specialties Inc. |
| Stanley Black & Decker |
| Alcoa Corporation |
| Others |
Supply Flow & Price Mechanics
Russian and Ukrainian titanium sponge concentration feeds directly into margin capture by tier-one fastener manufacturers with captive melt capacity. Long-term pricing agreements indexed to commodity benchmarks now displace spot purchasing for high-volume commercial aviation programs, concentrating pricing power among AS9100-certified suppliers with multi-site coverage.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across commercial aviation platforms. Three-tier pricing structure across premium, standard, and economy levels separates flight-critical titanium hardware from aluminum secondary fasteners and brass instrumentation mounts. Cost compression in standard-grade aluminum nuts is intensifying because Chinese COMAC production scales procurement volumes. Rotorcraft OEMs exhibit highest price sensitivity due to project-based procurement with shorter commitment horizons, while engine-attached titanium hardware commands lowest sensitivity given thermal performance specifications.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for aerospace fastener distributors. Production gravity centers on France, the United States, and China for final assembly line proximity, with Japan and Germany offsetting structural deficits through specialized forging exports. Raw material dependencies rest on titanium sponge, A286 superalloy bar stock, and 2024-T4 aluminum feedstock. Single-source vulnerability in Russian-origin titanium sponge exposes the supply chain to geopolitical disruption. Distribution runs through vendor-managed inventory programs operated by tier-one distributors in the Seattle-Tacoma and Toulouse aerospace clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing of titanium preforms threatens traditional cold-heading economics for complex lock nut geometries, forcing incumbents to defend process-based moats against 12-month qualification cycles.
For Market Incumbents: Harden AS9100 certification coverage across multiple production sites to disqualify emerging additive competitors from flight-critical contracts. Deepen backward integration into titanium sponge processing to offset commodity price volatility from Russian supply concentration. Lock in decade-long platform agreements with Boeing and Airbus before eVTOL manufacturers establish alternative supplier relationships. For New Entrants and Emerging Players: Build out specialized production cells serving urban air mobility OEMs with lower minimum order quantities than traditional aviation programs. Target India's Make in India defense localization as the most penetrable geography, where DGFT import substitution rules create joint venture pathways for foreign forging operations. Lead with additive manufacturing qualification for titanium lock nuts in spacecraft applications, where 12-month development timelines collapse traditional barriers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive titanium melt capacity and existing AS9100 certification across multiple sites. Long-term viability hinges on securing platform positions before OEM consolidation hardens supplier rosters. Watch for FAA airworthiness directive acceleration as the inflection signal indicating expanded contract volumes for qualified tier-one manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Titanium Processing Investment | LISI Aerospace's Rhône-Alpes operations demonstrate margin control through in-house sponge-to-fastener production. |
| AS9100 Multi-Site Certification Expansion | FAA and EASA traceability mandates disqualify uncertified suppliers from Boeing and Airbus platform agreements. |
| Additive Manufacturing Qualification | SpaceX and Blue Origin programs are collapsing 12-month development timelines for titanium lock nut geometries. |
| India Joint Venture Formation | Make in India indigenization mandates redirect Tejas fighter procurement toward domestic forging partnerships. |
| Long-Term Pricing Agreement Indexation | TriMas Aerospace and Precision Castparts anchor revenue stability through titanium sponge benchmark contracts. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with tier-one procurement officers at Boeing and Airbus, fastener quality directors, titanium sponge traders, and EASA certification auditors; and secondary validation through FAA airworthiness directive filings, EASA Part 21 design certification records, SEC 10-K disclosures from listed suppliers, and customs trade data on titanium sponge import flows. Bottom-up segment sizing triangulated against top-down aerospace production forecasts.
Forecast inputs span material grade substitution rates, platform-specific fastener counts per aircraft, and regulatory qualification timeline compression. Segmentation dimensions modeled include product geometry, alloy composition, end-use program type, and certification standard across the projection horizon. CAGRs derived from production volume trajectories at final assembly lines in the United States, France, and China, cross-referenced with titanium alloy specification shifts in engine mount and landing gear applications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing specialists or Chinese state-backed titanium processors would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market