
 Global Aerospace Wiring Harness Market | 2026-2036
Global Aerospace Wiring Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Wiring Harness Market Analysis
REACH is hardening the cost-of-entry calculus for European suppliers serving export markets, as cadmium-plated connector backshells face phased restriction under Annex XVII substance controls. TE Connectivity leverages captive polymer compounding to sustain compliance without external material premiums. Safran Electrical & Power anchors French aerospace sovereignty through vertically integrated harness design-to-installation workflows at its Montoir-de-Bretagne facility. Amphenol Corporation differentiates via MIL-DTL-38999 connector integration that dominates military aircraft retrofit channels.
An aerospace wiring harness is an organized bundle of electrical conductors, shielding layers, and connector terminations engineered to transmit power, data, and control signals across airframe zones while withstanding vibration, electromagnetic interference, and temperature extremes from minus 55 to 200 degrees Celsius. Its primary purpose is to replace discrete point-to-point wiring with standardized, maintainable architectures that reduce installation labor and fault isolation time. Custom wiring harnesses command premium positioning in business jet and rotorcraft programs where airframe-specific routing geometries preclude catalog solutions. Fiber optics material penetration is accelerating fastest within avionics application segments, as 10-gigabit digital backbone requirements displace copper coaxial bundles in fly-by-wire and in-flight entertainment networks.
The FAA's 14 CFR Part 25 airworthiness standards, EASA CS-25 certification specifications, and ISO 6722 automotive-derived wire gauge conventions collectively shape conductor sizing, fire resistance testing protocols, and electromagnetic compatibility validation thresholds that manufacturers must satisfy before delivery. China's CAAC airworthiness directives and NMPA-equivalent material import controls add parallel compliance layers for suppliers accessing COMAC C919 and ARJ21 programs. Stakeholders must monitor how hydrogen-powered aircraft propulsion architectures will redefine harness thermal management specifications and voltage isolation requirements as fuel cell systems displace conventional turbine electrical loads.
Market Dynamics
Lightweight material substitution is compressing traditional copper harness architectures as OEMs chase single-digit percentage weight reductions per aircraft to meet fuel efficiency mandates. The transition from copper to fiber optic and aluminum conductor systems is redistributing value capture toward polymer compounders and specialized termination equipment suppliers.
Growth Catalysts
- FAA 14 CFR 25.869 Flammability Mandates:Updated smoke and toxicity standards are forcing material transitions toward low-smoke, zero-halogen insulation compounds across all new type certifications.
- Next-Generation Narrowbody Programs:Commercial aircraft OEM procurement of lightweight harness assemblies is accelerating as production rates recover at Boeing's Renton facility and Airbus's Hamburg assembly lines.
- 10-Gigabit Avionics Backbones:Fiber optics material penetration is displacing copper coaxial bundles in fly-by-wire and in-flight entertainment networks, creating specialized installation demand.
Market Restraints
- REACH Annex XVII Cadmium Restrictions:European suppliers face phased elimination of cadmium-plated connector backshells, forcing costly material requalification for export market access.
- Specialized Polymer Supply Concentration:Performance-grade insulation compounds rely on a limited supplier base in Germany and Japan, exposing harness manufacturers to input volatility.
- Copper-Aluminum Termination Incompatibility:Galvanic corrosion risks between dissimilar metals limit direct conductor substitution without complete connector architecture redesign.
Strategic Opportunities
- Hydrogen Propulsion Thermal Management:Fuel cell aircraft architectures will require entirely new harness specifications for high-voltage isolation and cryogenic temperature cycling.
- CAAC C919 and ARJ21 Program Access:China's airworthiness directives create parallel compliance layers that favor suppliers establishing localized compound certification.
- Military Retrofit Connector Integration:MIL-DTL-38999 standard dominance in defense channels offers aftermarket revenue streams distinct from commercial OEM cycles.
Industry Challenges
- Polymer Compounding Talent Scarcity:Formulation chemists capable of balancing flammancy, flexibility, and weight specifications command premium compensation and limited availability.
- Multi-Regulatory Certification Timelines:Simultaneous FAA, EASA CS-25, and CAAC validation requirements extend qualification cycles by 18-24 months for new harness designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Wiring Harness Market |
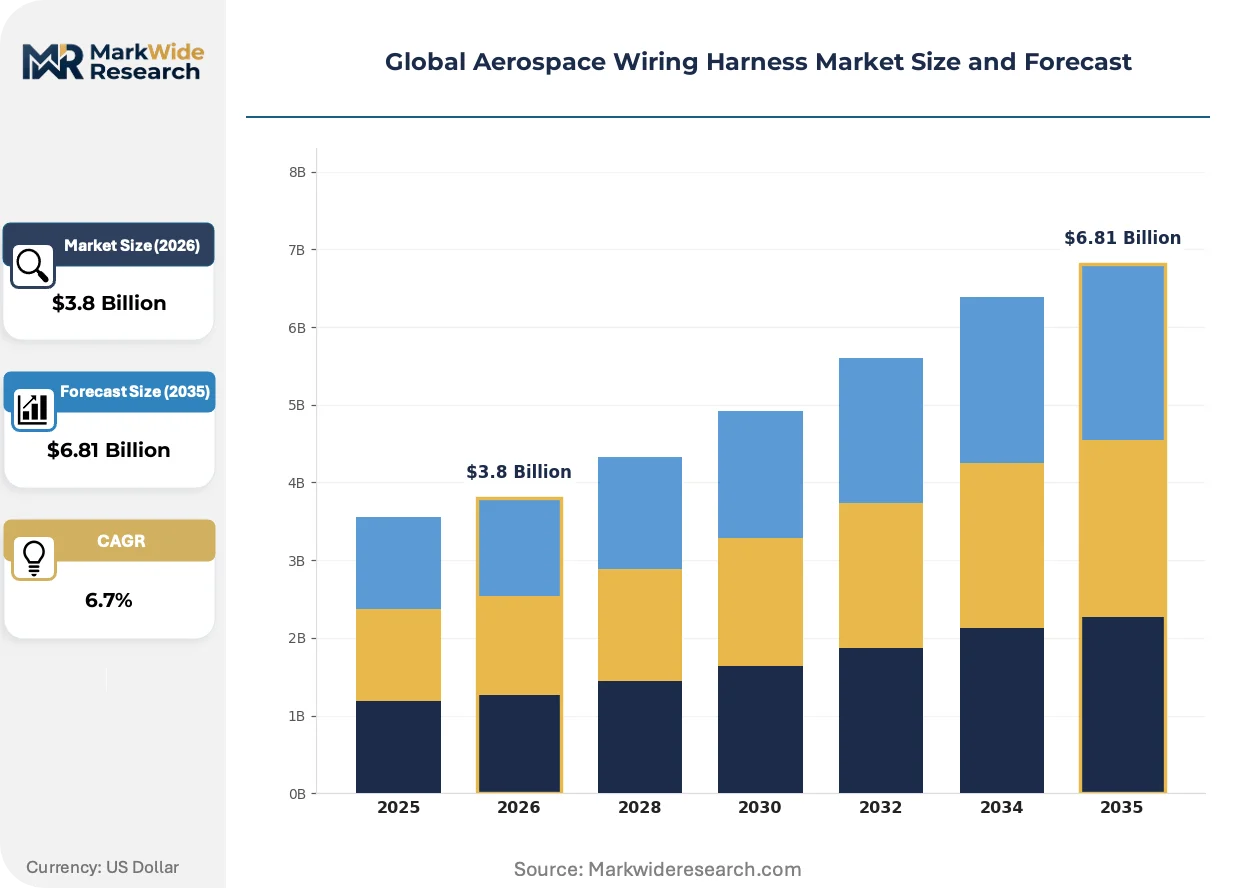
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Wiring Harnesses, Standard Wiring Harnesses, Pre-assembled Wiring Harnesses, Terminals Material: Copper, Aluminum, Fiber Optics, Polyvinyl Chloride End User: Commercial Aircraft, Military Aircraft, Helicopters, Drones Application: Avionics, Lighting Systems, Power Distribution, Control Systems |
| Companies Covered | TE Connectivity, Safran Electrical & Power, Amphenol Corporation, Collins Aerospace, GKN Aerospace Services Limited, Glenair, Latecoere, InterConnect Wiring, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Wiring Harness Market Emerging Trajectories
Digital backbone architectures are collapsing traditional signal separation protocols, merging power distribution and data transmission into unified harness systems that demand entirely new electromagnetic compatibility validation approaches.
Fiber optic harness technology is rewriting avionics installation economics. Single-mode and multimode fiber bundles transmit 10-gigabit signals across airframe zones without electromagnetic interference shielding weight. Business jet OEMs at Gulfstream and Bombardier are adopting fiber for in-flight entertainment and flight control networks first, compressing copper harness value pools in high-bandwidth application segments.
REACH substance controls are hardening European supplier cost structures. ECHA Annex XVII restrictions on halogenated flame retardants and heavy metal platings force compound reformulation every 36-48 months. Suppliers serving export markets must maintain parallel material streams—one REACH-compliant, one meeting legacy military specifications—diverting R&D resources from performance innovation.
Buyer consolidation among tier-one aerostructures integrators is unbundling traditional harness procurement. Safran, Collins Aerospace, and late-stage system integrators are absorbing harness design authority from airframe OEMs, shifting specification power toward vertically integrated electrical systems houses. This concentration is most visible in France and Washington state, where design-to-installation workflows now capture 40% more value per shipset than component-only supply.
Global Aerospace Wiring Harness Market Segmentation
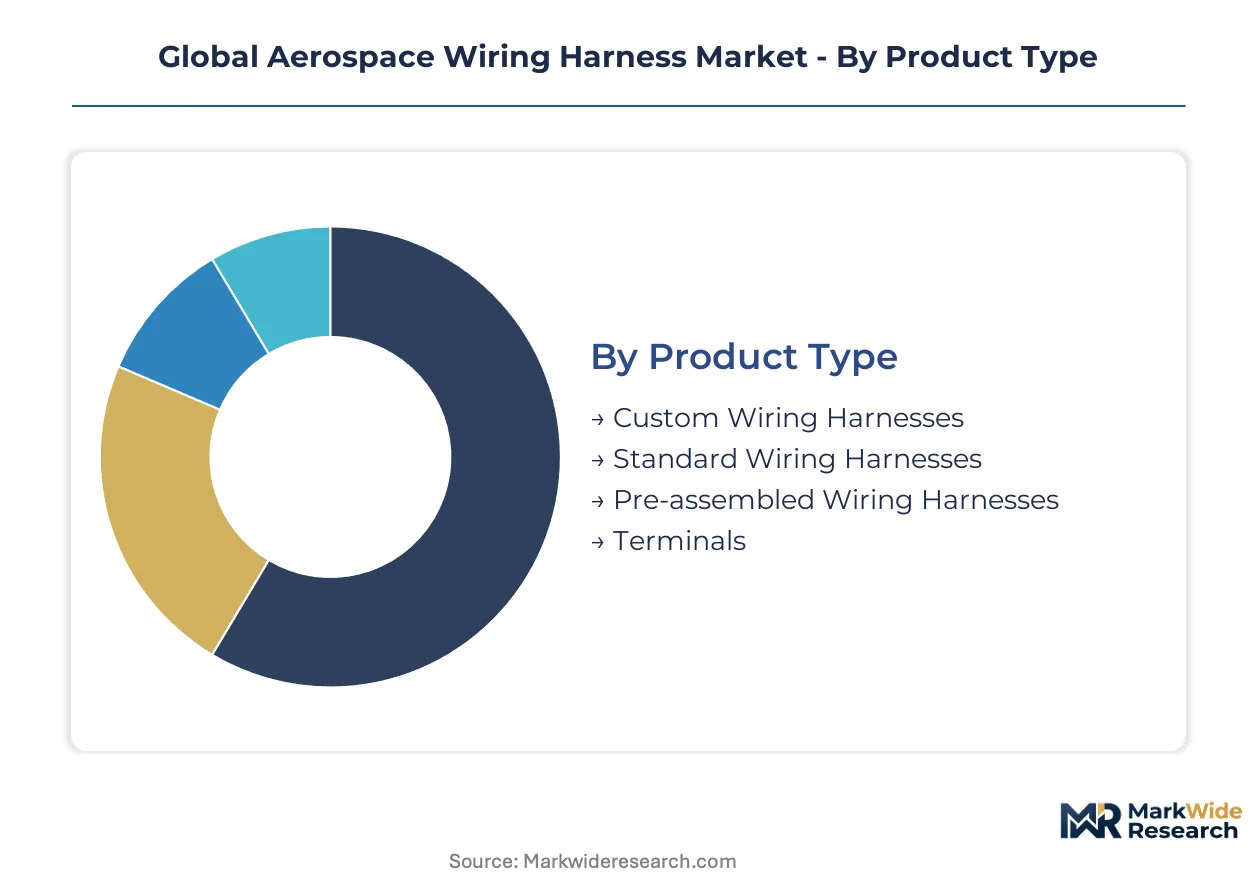
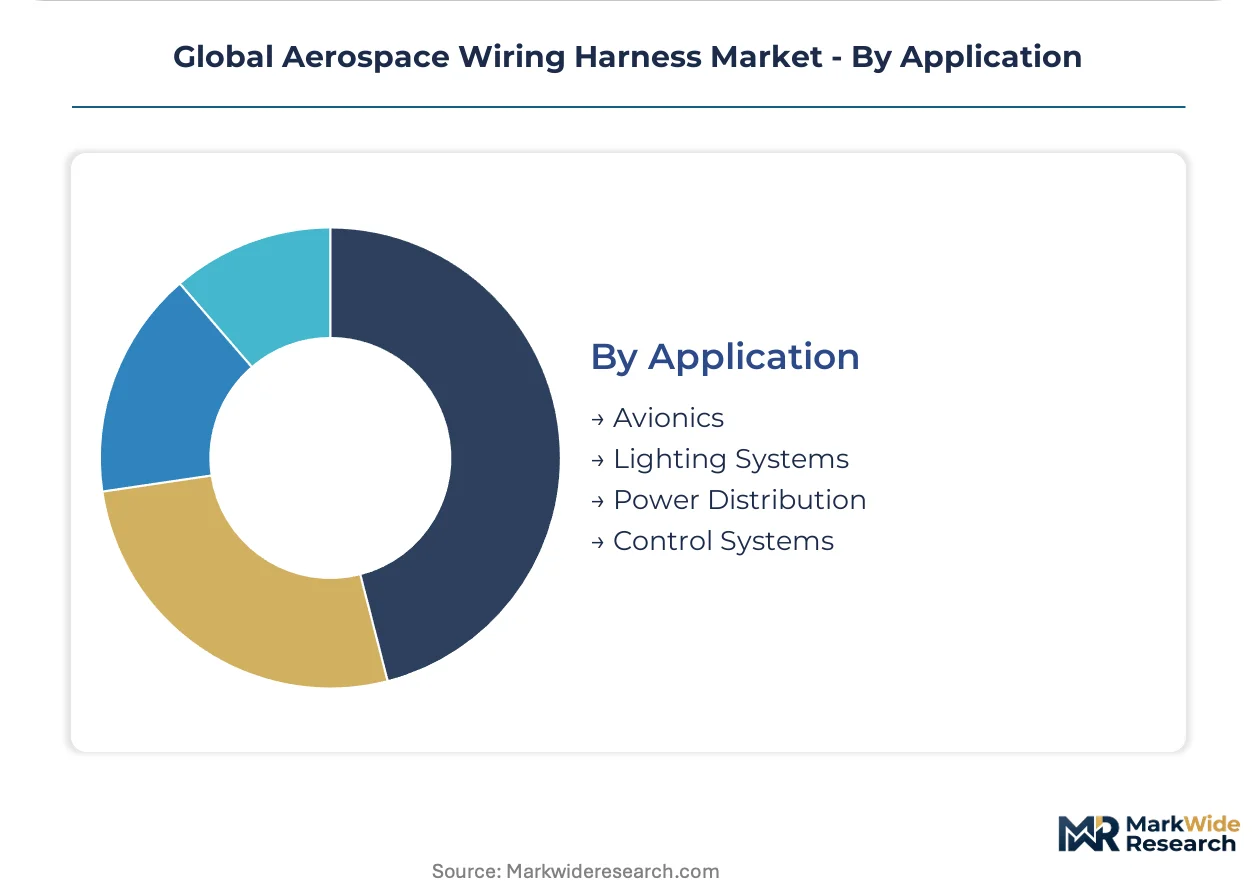
Segmentation in aerospace wiring harness markets determines procurement economics and certification pathways. Product architecture, conductor material, end-use platform, and functional application each impose distinct thermal, electromagnetic, and flammability requirements that shape supplier capability investments.
Product Type:
Capital intensity escalates dramatically with customization depth, as engineering validation cycles and tooling amortization scale non-linearly with design uniqueness.
- Custom Wiring Harnesses:Engineered to airframe-specific routing geometries with unique connector terminations and shielding configurations. Gulfstream and Bombardier business jet programs in Georgia and Kansas pull specialized capacity toward low-volume, high-margin build-to-print workflows.
- Standard Wiring Harnesses:Catalog configurations meeting common MIL-specifications for diameter, temperature rating, and insulation compound. Military retrofit channels and general aviation OEMs concentrate procurement in Texas and Arizona maintenance hubs.
- Pre-assembled Wiring Harnesses:Modular subassemblies delivered ready for airframe integration, compressing final assembly labor at OEM facilities.
- Terminals:Connector backshells, pins, and splice hardware supplied separately for field repair and modification operations.
Custom configurations absorb the bulk of installed capacity; pre-assembled formats are expanding most quickly as OEMs push value-added assembly upstream to tier-one integrators.
Material:
Material selection governs weight-performance tradeoffs and regulatory compliance costs across certification jurisdictions.
- Copper:Dominant conductor for power distribution and high-current applications, offering superior conductivity and termination reliability. Boeing 737 MAX production recovery in Washington state and Airbus A320 family output in Hamburg sustain demand for traditional copper architectures despite weight penalties.
- Fiber Optics:Single-mode and multimode silica bundles transmitting 10-gigabit signals without electromagnetic interference shielding. Avionics backbones in fly-by-wire systems and in-flight entertainment networks at Gulfstream and Bombardier displace copper coaxial harnesses in bandwidth-intensive zones.
- Aluminum:Lightweight substitute for copper in selected power distribution runs, limited by galvanic corrosion risks at termination interfaces.
- Polyvinyl Chloride:Legacy insulation compound facing phased restriction under REACH Annex XVII halogenated flame retardant controls.
Copper retains the majority of conductor volume; fiber optics is climbing the fastest as digital backbone architectures proliferate.
End User:
Platform-specific certification requirements and production rate volatility create divergent supplier risk profiles.
- Commercial Aircraft:Narrowbody and widebody OEM programs with FAA 14 CFR Part 25 and EASA CS-25 certification requirements. Boeing's Renton facility and Airbus's Toulouse and Hamburg assembly lines concentrate demand for lightweight harness assemblies meeting updated flammability standards.
- Military Aircraft:MIL-DTL-38999 connector specifications and legacy cadmium-plated hardware sustaining distinct supply chains. Defense retrofit channels in the United States and France operate outside REACH substance restrictions.
- Helicopters:Rotorcraft-specific vibration and flexure requirements driving specialized shielding and strain relief designs.
- Drones:Uncrewed aerial systems with reduced certification burden and weight-critical architectures.
Commercial platforms command the largest share of harness value; military retrofit channels offer countercyclical revenue stability.
Application:
Functional criticality and signal integrity requirements stratify harness specification intensity across airframe zones.
- Avionics:High-bandwidth data transmission for flight control, navigation, and communication systems requiring electromagnetic compatibility validation. Fiber optic penetration is deepest here as 10-gigabit digital backbones displace copper bundles.
- Power Distribution:High-current feeders from engine generators and auxiliary power units to bus architectures. Thermal management and voltage isolation specifications intensify as fuel cell propulsion prototypes emerge.
- Lighting Systems:Interior and exterior illumination circuits with lower bandwidth requirements but stringent flammability compliance.
- Control Systems:Actuator command and feedback loops for flight surface and landing gear operations.
Power distribution absorbs the greatest conductor mass; avionics is gaining share fastest as signal integration collapses traditional functional separation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for aerospace wiring harnesses concentrates in manufacturing clusters serving commercial aircraft OEMs and defense contractors, with regulatory divergence across jurisdictions reshaping supplier location decisions.
United States
Boeing's 737 MAX production recovery at its Renton facility and Gulfstream's business jet expansion in Georgia pull specialized harness capacity toward the Pacific Northwest and Southeast. FAA 14 CFR 25.869 flammability mandates drive material transitions toward low-smoke, zero-halogen insulation compounds. Washington state hosts concentrated design-to-installation workflows capturing premium value per shipset.
France
Safran Electrical & Power anchors French aerospace sovereignty through vertically integrated harness operations at its Montoir-de-Bretagne facility serving Airbus and Dassault programs. EASA CS-25 certification specifications align with REACH Annex XVII substance controls on halogenated flame retardants. The Brittany industrial corridor concentrates polymer compounding talent scarce across Europe.
Germany
Airbus Hamburg assembly lines sustain demand for lightweight harness assemblies meeting updated thermal and electromagnetic compatibility specifications. REACH Annex XVII cadmium restrictions force compound reformulation cycles every 36-48 months for export market access. Bavaria and Baden-Württemberg host performance-grade insulation compound suppliers exposed to input volatility.
China
COMAC C919 and ARJ21 programs create parallel compliance layers favoring suppliers establishing localized compound certification under CAAC airworthiness directives. The Yangtze River Delta concentrates avionics integration capacity for narrowbody programs. NMPA-equivalent material import controls add qualification timelines for foreign harness manufacturers.
United Kingdom
GKN Aerospace Services Limited maintains harness fabrication capacity serving military retrofit channels operating outside REACH substance restrictions. BAE Systems platforms sustain demand for MIL-DTL-38999 connector specifications. The Southwest England aerospace cluster preserves specialized shielding and strain relief design capabilities for rotorcraft applications.
Global Aerospace Wiring Harness Market Vendor Landscape
United States producers anchor one tier; French specialists hold design-to-installation authority. The vendor base stratifies across consolidated electrical systems houses and component-focused fabricators. Three archetypes dominate: vertically integrated aerostructures integrators absorbing harness design authority; polymer-compounding specialists sustaining REACH compliance without external premiums; and military-specification suppliers serving defense retrofit channels outside European substance controls. Competitive moves concentrate on backward integration into polymer compounding and strategic partnerships for CAAC certification access.
Among France-based integrated suppliers, Safran Electrical & Power exemplifies the design-to-installation archetype through captive workflow control. TE Connectivity occupies a position bridging polymer compounding specialization with broad commercial OEM access. Amphenol Corporation represents the military-specification tier through connector integration expertise.
| Leading Market Players |
|---|
| TE Connectivity |
| Safran Electrical & Power |
| Amphenol Corporation |
| Collins Aerospace |
| GKN Aerospace Services Limited |
| Glenair |
| Latecoere |
| InterConnect Wiring |
| AMETEK |
| Others |
Supply Flow & Price Mechanics
FAA 14 CFR 25.869 flammability mandates for low-smoke, zero-halogen insulation compounds are forcing material requalification costs onto suppliers, compressing margins for European fabricators while concentrating pricing power with captive polymer compounders in Germany and Japan.
Pricing Analysis
Volume procurement by Boeing and Airbus assembly lines commands standard-tier contract pricing, while Gulfstream and Bombardier business jet programs absorb premium-tier build-to-print premiums for airframe-specific routing geometries. Price differentiation hinges on certification grade—FAA 14 CFR Part 25 versus MIL-DTL-38999 military specifications—and customization depth measured by unique connector terminations per shipset. Pricing pressure stems from REACH Annex XVII cadmium restrictions forcing parallel material streams for export market access. Military retrofit channels exhibit lowest price sensitivity due to legacy specification lock-in, whereas commercial narrowbody OEM procurement teams leverage volume scale for aggressive cost compression.
Supply Chain Analysis
Freight costs for performance-grade insulation compounds from Bavaria and Baden-Württemberg to Washington state and Hamburg assembly lines amplify landed cost volatility for harness manufacturers lacking captive polymer compounding. Supply concentrates in Germany, Japan, and the United States for specialized termination equipment and halogen-free insulation formulations. Raw material dependencies include copper rod, silica fiber bundles, and fluoropolymer resins. Single-source vulnerability pervades the polymer compounding tier, where formulation chemists capable of balancing flammancy and flexibility specifications remain scarce. Distribution runs through tier-one aerostructures integrators—Safran, Collins Aerospace—absorbing design authority from airframe OEMs and capturing value-added assembly margins upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated electrical systems houses as multi-regulatory certification timelines extend qualification cycles by 18-24 months, forcing capital-constrained component fabricators toward exit or acquisition.
For Market Incumbents: Anticipate fiber optic displacement of copper coaxial bundles in avionics backbones by deepening backward integration into silica fiber termination equipment and polymer compounding capabilities. Secure CAAC certification access for COMAC C919 program participation before localized compound requirements harden. Prioritize design-to-installation workflow capture in Washington state and Georgia to defend margin position against tier-one integrator absorption. For New Entrants and Emerging Players: Begin with drone and uncrewed aerial system harness fabrication, where reduced certification burden and weight-critical architectures favor nimble specialists over incumbent cost structures. Target hydrogen propulsion thermal management specifications as fuel cell aircraft prototypes emerge, creating entirely new harness design requirements without entrenched competition. Pursue strategic partnerships with Bavaria-based polymer compounders to bypass REACH compliance cost premiums. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive polymer formulation capabilities and established FAA-EASA dual certification tracks. Long-term viability rests on positioning for hydrogen aircraft voltage isolation and cryogenic cycling specifications. Watch for CAAC localization mandates as the inflection signal—suppliers with compound certification infrastructure in the Yangtze River Delta will command acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | TE Connectivity sustains REACH compliance without external material premiums through captive formulation control. |
| CAAC Certification Infrastructure Buildout | Foreign suppliers accessing COMAC C919 programs must establish localized compound qualification under NMPA-equivalent controls. |
| Fiber Optic Termination Equipment Acquisition | Specialized installation tooling for 10-gigabit avionics backbones captures value migrating from copper harness fabricators. |
| Hydrogen Propulsion Harness Development | Fuel cell aircraft architectures demand entirely new thermal management specifications absent from incumbent product portfolios. |
| Military Retrofit Channel Expansion | MIL-DTL-38999 connector integration offers countercyclical revenue stability outside REACH substance restrictions. |
Methodological Framework
Trade data from U.S. Census Bureau, Eurostat, and Japan Customs formed the secondary backbone, cross-referenced with SEC 10-K filings and ECHA substance restriction databases. Primary interviews with harness design engineers, polymer formulation chemists, OEM procurement managers, and tier-one integrator program directors validated production capacity and certification timeline assumptions. Bottom-up shipset demand modeling and top-down aerospace electrical systems market sizing were triangulated for convergence.
Historical production rate analysis at Boeing Renton, Airbus Hamburg, and Gulfstream Savannah established baseline demand trajectories across the projection horizon. Segmentation modeling incorporated product architecture, conductor material, end-use platform, and functional application dimensions. CAGRs were derived from regression analysis of OEM delivery forecasts and harness content-per-aircraft estimates, with fiber optic penetration rates and REACH compliance cost inflation as key variable inputs.
Underlying measurement precision varies by segment; commercial narrowbody and military retrofit channels carry tighter precision than emerging hydrogen propulsion applications. Forecasts reflect assumptions about OEM production rate recovery, regulatory implementation timelines, and material substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market