
 Multi-Chip Module (MCM) Market | 2026-2036
Multi-Chip Module (MCM) Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Chip Module (MCM) Market Analysis
Automotive electronics is realigning the demand profile for Multi-Chip Modules as electric vehicles and advanced driver-assistance systems require higher-density power management and sensor fusion packages. Intel Corporation leverages its advanced packaging roadmap to sustain leadership in high-performance computing MCMs. Samsung Electronics anchors memory-stacking capabilities that dominate HBM and 3D-IC supply chains. Taiwan Semiconductor Manufacturing Company Limited specializes in CoWoS and InFO technologies that control the premium interposer-based MCM segment.
A Multi-Chip Module integrates multiple semiconductor dies—analog, digital, or mixed-signal—onto a common substrate using wire bonding, flip chip, or silicon interposer connections, achieving higher functional density and shorter signal paths than discrete packaging. Mixed-Signal Devices command widening application scope as edge AI and 5G base stations require tight integration of RF front-ends with digital baseband processors. Flip Chip technology leads in high-pin-count, high-reliability configurations where thermal performance and electrical parasitics determine design outcomes.
China's MEE enforces dual carbon goals that restrict energy-intensive substrate manufacturing, while REACH and RoHS in Europe constrain lead-based solder and halogenated flame retardants in MCM materials. The US FDA and FCC impose electromagnetic compatibility and safety standards on medical and telecommunications MCM deployments. Stakeholders must monitor evolving substrate material qualifications and regional carbon-border adjustments that will reshape sourcing decisions and captive production strategies.
Market Dynamics
Automotive electrification and heterogeneous integration roadmaps are compressing development cycles for high-density packaging. Tier-one suppliers now demand MCM qualification timelines that outpace traditional substrate material certification protocols.
Growth Catalysts
- Heterogeneous Integration Mandates:Advanced driver-assistance systems require sensor fusion architectures that consolidate radar, lidar, and camera processing dies into unified MCM substrates. Automotive OEMs in Germany and Japan are accelerating design-in cycles for these packages.
- China's Dual Carbon Enforcement:MEE energy-efficiency standards are forcing domestic packaging houses to adopt low-temperature co-fired ceramic and organic laminate processes that reduce firing energy by specified thresholds. This regulatory pressure is reshaping substrate material supply chains.
- Memory-Logic Convergence:High-bandwidth memory stacking with logic dies via silicon interposers is absorbing capital allocation from discrete DRAM packaging. South Korean and Taiwanese foundries are expanding CoWoS-equivalent capacity to capture this demand.
Market Restraints
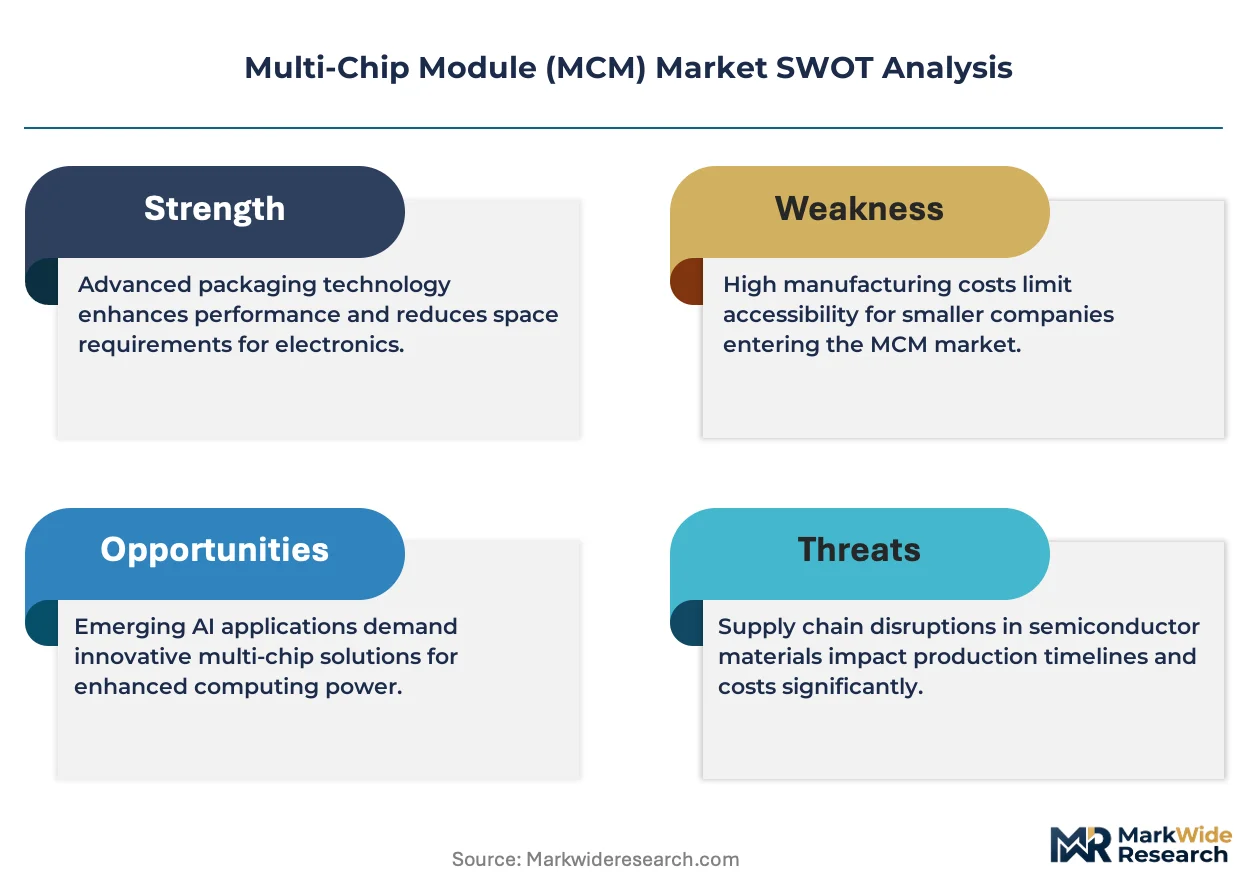
- ABF Substrate Supply Concentration:Ajinomoto Build-up Film substrate output concentrates among Japanese chemical suppliers and Taiwanese laminators. Any disruption to BT resin or glass cloth supply cascades through MCM lead times.
- REACH Chemical Restrictions:ECHA registration requirements for novel epoxy mold compounds and underfill materials extend qualification timelines by 18-24 months. European packaging houses face compliance cost escalation.
- Thermal-Mechanical Limitations:Coefficient of thermal expansion mismatch between silicon dies and organic substrates limits package size for high-power automotive MCMs. Wire bond reliability degrades beyond 25mm x 25mm footprints.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are attracting MCM assembly investments in Gujarat and Tamil Nadu. Domestic automotive and telecom equipment demand remains underpenetrated relative to East Asian benchmarks.
- Photonics-Electronics Convergence:Co-packaged optics with switch ASICs requires silicon photonics dies integrated alongside electronic dies in shared MCM substrates. Cloud infrastructure operators are driving specification development.
- EU Green Deal Procurement:CSRD-aligned sustainability reporting is creating preference for MCM suppliers with verified carbon footprint data across substrate mining, die fabrication, and assembly. Early certifiers gain tender advantages.
Industry Challenges
- Advanced Packaging Talent Scarcity:Chiplet architecture design, thermal simulation, and interposer layout expertise concentrates among experienced engineers at Taiwanese and South Korean incumbents. Western packaging houses struggle to staff these functions.
- Multi-Die Test Complexity:Known-good-die screening for stacked configurations requires probe card investments and test program development that extend NRE timelines. Yield fallout at final test destroys margin on high-pin-count MCMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Chip Module (MCM) Market |
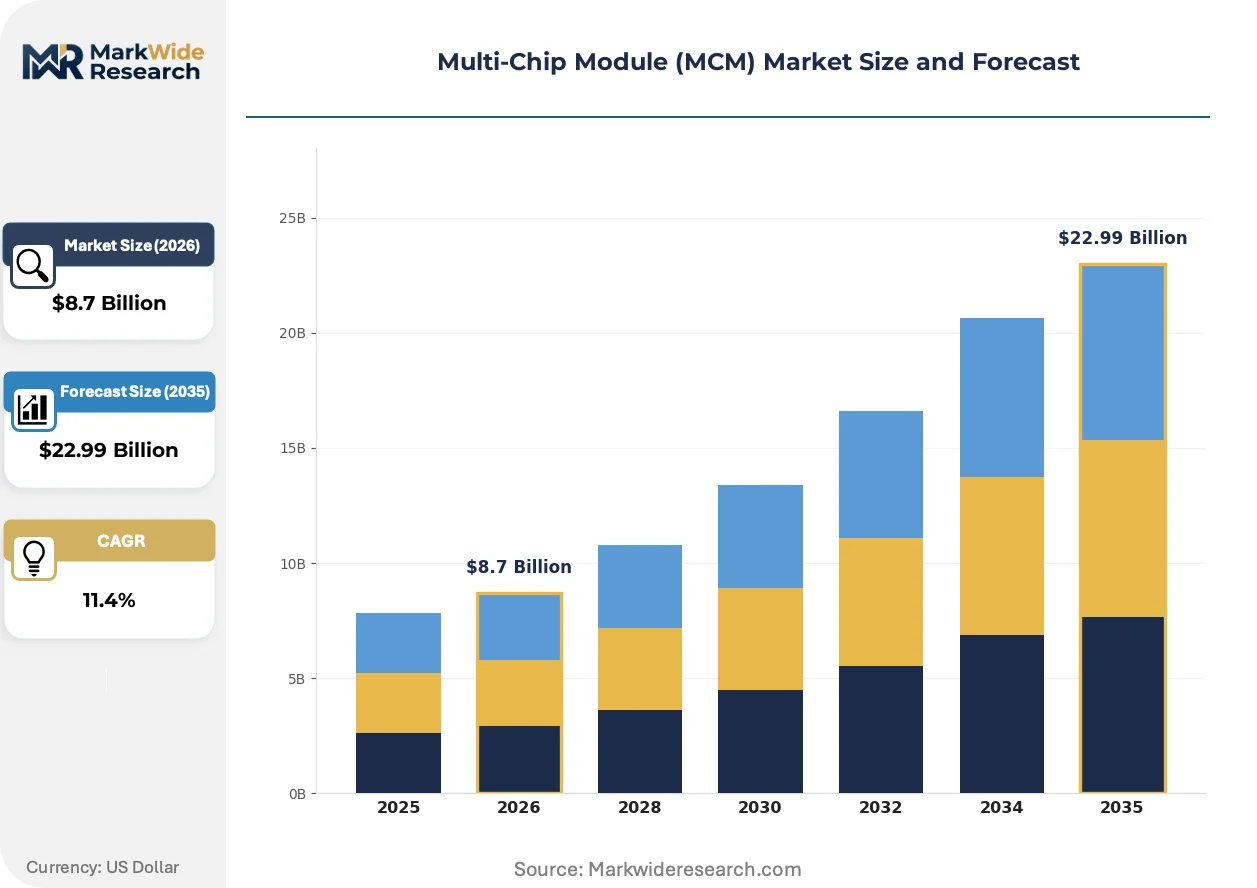
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
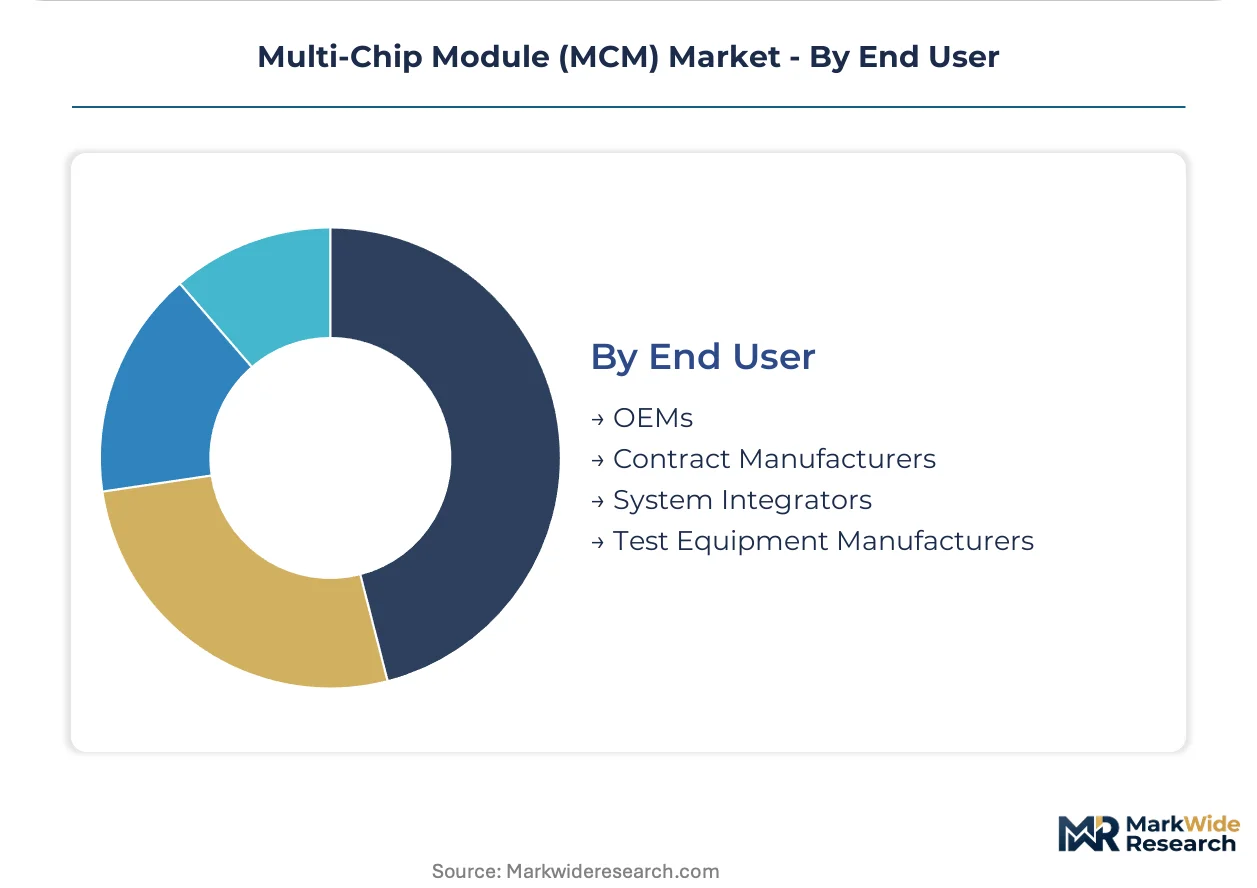
| Segmentation | Product Type: Analog Devices, Digital Devices, Mixed-Signal Devices, Power Modules Technology: Wafer Level Packaging, Chip-On-Board, Flip Chip, Surface Mount Technology Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Control End User: OEMs, Contract Manufacturers, System Integrators, Test Equipment Manufacturers |
| Companies Covered | Samsung Electronics, Intel Corporation, SK Hynix Inc., Texas Instruments Incorporated, Infineon Technologies AG, STMicroelectronics N.V., Micron Technology, Inc., Taiwan Semiconductor Manufacturing Company Limited, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Chip Module (MCM) Market Emerging Trajectories
Silicon interposer scaling and co-packaged photonics roadmaps are converging to redefine MCM architecture boundaries. Material science advances in low-loss dielectrics and thermal interface materials are unlocking power-density thresholds previously constrained by organic substrate limitations.
Embedded multi-die interconnect bridge technology is absorbing routing density requirements that previously demanded costly silicon interposers. Intel and foundry partners are qualifying EMIB for high-performance computing and automotive radar MCMs where cost constraints exclude full interposer solutions. This bridge approach is compressing the addressable market for premium CoWoS-style packaging in mid-range performance tiers.
REACH Annex XIV substance restrictions are forcing reformulation of halogenated flame retardants in MCM mold compounds and laminates. ECHA authorization timelines are compressing supplier R&D cycles as legacy brominated chemistries face sunset dates. European automotive and industrial MCM buyers are accelerating qualification of phosphorus-nitrogen alternative chemistries to avoid supply discontinuity.
Automotive tier-one procurement is consolidating qualified MCM supplier lists to reduce variation risk across vehicle platforms. Continental, Bosch, and Denso are contracting directly with OSATs and captive packaging divisions for multi-year die-bank agreements. This concentration is visible most acutely in Germany and Japan, where OEMs are vertically integrating packaging specification control to secure allocation during substrate material tightness.
Multi-Chip Module (MCM) Market Segmentation

Multi-Chip Module configurations diverge sharply across integration density, thermal envelope, and signal integrity requirements. Each segmentation axis reveals distinct procurement patterns and qualification protocols that reshape supplier relationships and captive production decisions.
Product Type:
Volume applications favor standardized die configurations, while premium tiers demand customized heterogeneous integration.
- Mixed-Signal Devices:These modules combine analog sensing front-ends with digital processing cores on shared substrates. Edge AI inference engines and 5G base station radio units in Taiwan and South Korea are absorbing the majority of mixed-signal MCM output as signal-path minimization becomes critical.
- Power Modules:High-current switching dies integrate with gate drivers and protection circuitry using direct copper bonding or sintered silver interfaces. Electric vehicle traction inverters from German and Japanese automotive OEMs are compressing qualification timelines for these thermally aggressive packages.
- Analog Devices:Precision voltage references, data converters, and RF transceivers populate these modules for instrumentation and medical imaging.
- Digital Devices:Logic-only configurations concentrate in high-performance computing where homogeneous die stacking maximizes interconnect bandwidth.
Mature deployment sits with Digital Devices. Newer deployment is concentrated in Mixed-Signal Devices.
Technology:
Cost tier separation runs from commodity surface-mount assemblies to interposer-based premium solutions.
- Flip Chip:Solder bump or copper pillar connections eliminate wire bond inductance and enable face-down die mounting with direct backside cooling. High-pin-count server processors and automotive radar chipsets from Intel and Samsung foundries are standardizing on flip chip for reliability-critical applications.
- Wafer Level Packaging:Redistribution layers and through-silicon vias are applied at wafer scale before singulation, minimizing form factor and parasitic capacitance. Image sensor modules for smartphone cameras in South Korean and Japanese manufacturing clusters are driving wafer-level MCM adoption as pixel density requirements escalate.
- Chip-On-Board:Bare die attach directly to printed circuit boards with wire bonding or epoxy encapsulation serves cost-sensitive consumer applications.
- Surface Mount Technology:Pre-packaged components on organic laminates dominate high-volume, low-complexity electronics assembly.
Surface Mount Technology commands the highest unit volumes. Flip Chip is expanding most quickly in value terms.
Application:
Customer type determines margin structure, with automotive and telecom buyers demanding extended reliability guarantees.
- Automotive Electronics:Multi-die modules for battery management, motor control, and sensor fusion must survive AEC-Q100 Grade 0 thermal cycling. Tier-one suppliers including Continental and Bosch are consolidating qualified vendor lists to reduce platform variation risk across German and Japanese vehicle programs.
- Telecommunications:Baseband processors, RF transceivers, and power amplifiers integrate in MCMs for 5G macro cells and millimeter-wave small cells. Network equipment vendors in South Korea and Taiwan are driving specifications for co-packaged optics integration.
- Consumer Electronics:Smartphones, wearables, and gaming devices prioritize miniaturization and cost minimization over extended temperature range.
- Industrial Control:Factory automation and process instrumentation require long-life availability and resistance to electrical noise.
Consumer Electronics represents the largest addressable unit base. Automotive Electronics is climbing the fastest on value expansion.
End User:
Procurement authority concentration varies, with OEMs exerting greatest specification control in safety-critical applications.
- OEMs:Original equipment manufacturers in automotive, aerospace, and medical devices define MCM architectures and qualify substrate materials directly. German automotive OEMs and Japanese industrial equipment makers are backward-integrating into packaging design to secure allocation during substrate tightness.
- Contract Manufacturers:Foxconn, Jabil, and Flex manage high-volume MCM assembly for consumer electronics brands, absorbing capital equipment risk.
- System Integrators:Defense and telecommunications contractors specify MCMs for radar, satellite, and network infrastructure programs.
- Test Equipment Manufacturers:Semiconductor ATE vendors integrate custom MCMs for high-speed probe interfaces and signal conditioning.
Contract Manufacturers handle the highest MCM unit throughput. OEMs are gaining specification authority fastest in automotive and medical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundries dominate MCM fabrication output, while Western automotive and defense buyers absorb the majority of high-reliability module consumption. This geographic split shapes substrate material flows and qualification protocols across supply chains.
China
Domestic EV manufacturers and telecom infrastructure builders drive MCM consumption for battery management and 5G baseband integration. MEE dual carbon enforcement tightens energy-efficiency standards for substrate firing processes, pushing packaging houses toward low-temperature co-fired ceramic alternatives. Yangtze River Delta clusters in Suzhou and Wuxi concentrate advanced laminate capacity serving both local and export demand.
South Korea
Memory-logic convergence applications absorb the bulk of HBM and 3D-IC module output from domestic foundries. MFDS medical device regulations and automotive AEC-Q100 standards govern qualification protocols for healthcare and vehicle electronics deployments. Seoul Capital Area and Busan-Ulsan corridors anchor silicon interposer fabrication and memory-stacking assembly operations.
Taiwan
CoWoS and InFO technology leadership positions the island as the premium interposer-based MCM supply hub for AI accelerators and high-performance computing. Trade administration export controls on advanced packaging equipment shape capacity expansion timelines and customer access tiers. Hsinchu Science Park and Taichung Precision Machinery clusters concentrate wafer-level packaging and test infrastructure.
Japan
ABF substrate supply concentration among chemical suppliers and laminators creates strategic leverage over global MCM lead times. METI industrial policy supports domestic packaging material R&D and semiconductor reshoring initiatives. Kyushu and Tohoku regions host advanced organic substrate manufacturing and automotive-grade module assembly for tier-one suppliers.
United States
Defense and aerospace contractors drive demand for radiation-hardened and high-reliability MCMs in radar and satellite applications. CHIPS Act funding accelerates domestic advanced packaging capacity buildout to reduce reliance on East Asian foundries. Arizona and Texas manufacturing corridors attract Intel and TSMC fab investments that will reshape regional substrate and interposer supply chains.
Multi-Chip Module (MCM) Market Vendor Landscape
Top-tier vendors anchor silicon interposer and memory-stacking technology, while mid-tier specialists occupy wire-bond and organic laminate segments. The market structures around three archetypes: integrated device manufacturers with captive packaging divisions, pure-play foundries offering advanced packaging services, and outsourced semiconductor assembly and test houses handling high-volume production. Capacity expansion and strategic partnerships dominate competitive moves as substrate material tightness forces die-bank agreements and allocation commitments.
Within the integrated device manufacturer tier, Intel Corporation and Samsung Electronics exemplify vertical control from die fabrication through advanced module assembly. Taiwan Semiconductor Manufacturing Company Limited occupies a distinct position as a pure-play foundry with CoWoS technology leadership. These three entities collectively represent the technology trajectory that mid-tier competitors must license or partner to access.
| Leading Market Players |
|---|
| Samsung Electronics |
| Intel Corporation |
| SK Hynix Inc. |
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| Micron Technology, Inc. |
| Taiwan Semiconductor Manufacturing Company Limited |
| Broadcom Inc. |
| Others |
Supply Flow & Price Mechanics
China's MEE dual carbon goals gate qualified supply for low-temperature co-fired ceramic substrates and premium-tier pricing access for automotive-grade MCMs. European REACH restrictions on halogenated flame retardants further segment suppliers into certified premium tiers versus uncertified standard offerings.
Pricing Analysis
Cost-down pressure on standard-tier MCMs accelerates because ABF substrate tightness forces packaging houses to absorb material inflation without full pass-through. Three-tier pricing structure across premium interposer-based, standard organic laminate, and economy wire-bond tiers separates buyers by thermal performance and reliability grade. Price differentiation traces to AEC-Q100 certification level and die-bank volume commitments, with automotive OEMs least sensitive and consumer electronics contract manufacturers most sensitive to unit cost.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Japan anchor hub-and-spoke patterns for silicon interposer and ABF substrate flows to global OSATs. Raw material dependencies center on BT resin from Japanese chemical suppliers, glass cloth laminates from Taiwanese processors, and sintered silver thermal interface materials from South Korean specialists. Single-source vulnerability concentrates in Ajinomoto Build-up Film output, with distribution running through captive die-bank agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum defines competitive positioning as incumbents pursue upstream substrate material control and downstream die-bank commitments to secure allocation.
For Market Incumbents: Lock in multi-year ABF substrate offtake agreements with Japanese chemical suppliers and Taiwanese laminators before capacity expansion lags demand. Deepen captive interposer fabrication capabilities to defend margin position against EMIB-based cost competition from Intel and foundry partners. For New Entrants and Emerging Players: Photonics-electronics convergence modules for cloud infrastructure switch ASICs represent the most penetrable white-space segment, with co-packaged optics specifications still crystallizing. Target Indian PLI scheme incentives for packaging assembly in Gujarat and Tamil Nadu, positioning for domestic automotive and telecom equipment demand with technology licensing partnerships rather than greenfield R&D. For Investors and Strategic Acquirers: Tier-one automotive procurement consolidation into multi-year die-bank agreements is the leading indicator that packaging capacity will command scarcity premiums. Mid-tier OSATs with established AEC-Q100 qualification and underutilized organic laminate capacity represent the optimal acquisition archetype over the coming decade.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Interposer Capacity Expansion | TSMC CoWoS-equivalent investments absorb capital allocation from HBM and AI accelerator demand. |
| EMIB Technology Licensing | Intel's bridge approach compresses addressable market for premium interposer solutions in mid-range tiers. |
| Low-Temperature Ceramic Process Adoption | China's MEE energy standards force domestic packaging houses toward qualified low-firing alternatives. |
| Die-Bank Agreement Consolidation | Continental, Bosch, and Denso contracts reduce supplier variation risk across German and Japanese vehicle platforms. |
| Photonics-Electronics Co-Packaging | Cloud infrastructure operators drive specification development for silicon photonics integration alongside electronic dies. |
Methodological Framework
Multi-period observation of ABF substrate lead times, silicon interposer capacity utilization, and automotive MCM qualification timelines anchored the trend analysis, supplemented by interviews with packaging R&D directors, Tier 1 supplier procurement managers, OSAT operations heads, and substrate material technical leads. Secondary validation drew from SEMI equipment billings, ECHA substance registration databases, customs trade flows for BT resin and glass cloth, and SEC filings from integrated device manufacturers. Bottom-up segment sizing triangulated against top-down foundry capacity forecasts.
Input-output matrix modeling connected die-level fabrication, substrate lamination, assembly, and test stages across product type, technology node, application, and end-user segmentation dimensions. CAGRs derived from capacity expansion announcements, equipment delivery schedules, and customer design-in pipeline visibility. Industry-specific forecast inputs included AEC-Q100 qualification velocity and REACH Annex XIV sunset date impacts on mold compound reformulation.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan Strait logistics, abrupt shifts in automotive electrification penetration, and unannounced substrate material substitutions. Forecasts reflect documented assumptions regarding foundry yield trajectories and regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market