
 Europe Metal Caps and Closures Market | 2026-2036
Europe Metal Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Caps and Closures Market Insights
Italy is reconfiguring its position as a design-to-manufacturing hub for premium beverage closures. Guala Closures SpA leverages its Emilia-Romagna production base to dominate tamper-evident wine closure exports across Southern Europe. Pelliconi & C SpA anchors its competitive stance through deep specialization in crown caps for craft brewing applications. Crown Holdings Incorporated sustains volume leadership by operating multi-material lines that serve pan-European food canning contracts.
Metal caps and closures are precision-formed sealing devices manufactured from aluminum, steel, or tinplate through deep-drawing, threading, or riveting processes, designed to preserve product integrity, enable controlled opening torque, and support extended shelf stability for packaged goods. Twist-off caps occupy the largest share of food industry procurement due to their resealability and compatibility with hot-fill pasteurization cycles. Aluminum screw closures represent the fastest-expanding material-format pairing as wineries and spirits producers abandon natural cork to eliminate contamination risk and standardize extraction force. Custom diameter specifications above 48mm are capturing disproportionate margin pools in pharmaceutical and home care segments where child-resistant and dosing-precision features command specification premiums.
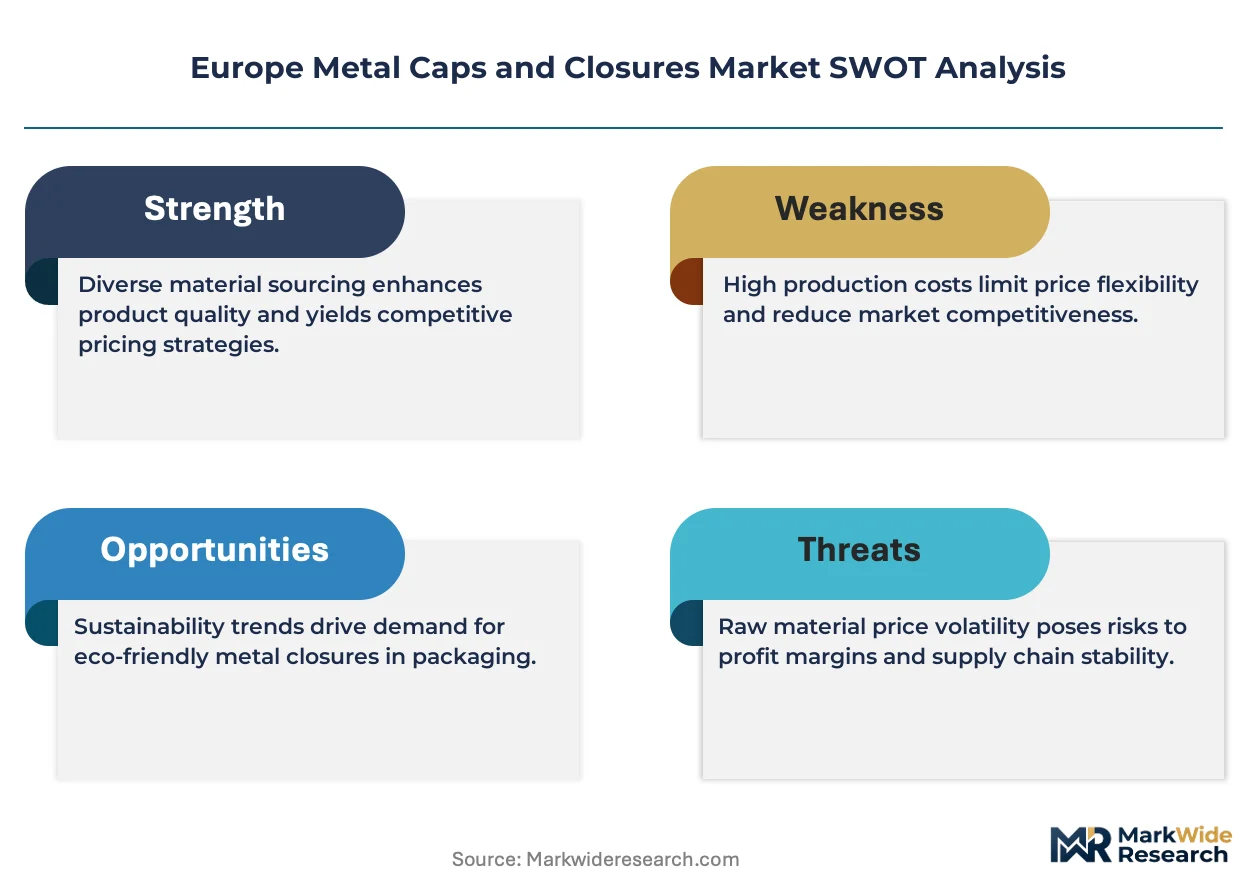
The EU Packaging and Packaging Waste Regulation and REACH compliance protocols enforced by ECHA are mandating higher recycled content thresholds and restricting certain surface coating chemistries, directly elevating R&D costs for tinplate and steel closure suppliers while accelerating aluminum substitution. CE marking requirements under the EU harmonized standards framework govern dimensional tolerances and migration limits for food-contact metal closures, creating non-tariff barriers for non-European manufacturers seeking market entry. Stakeholders must monitor how the EU Green Deal's extended producer responsibility amendments reshape collection infrastructure economics and whether Germany's national packaging law triggers cascading compliance investments across Central European supplier networks.
Market Dynamics
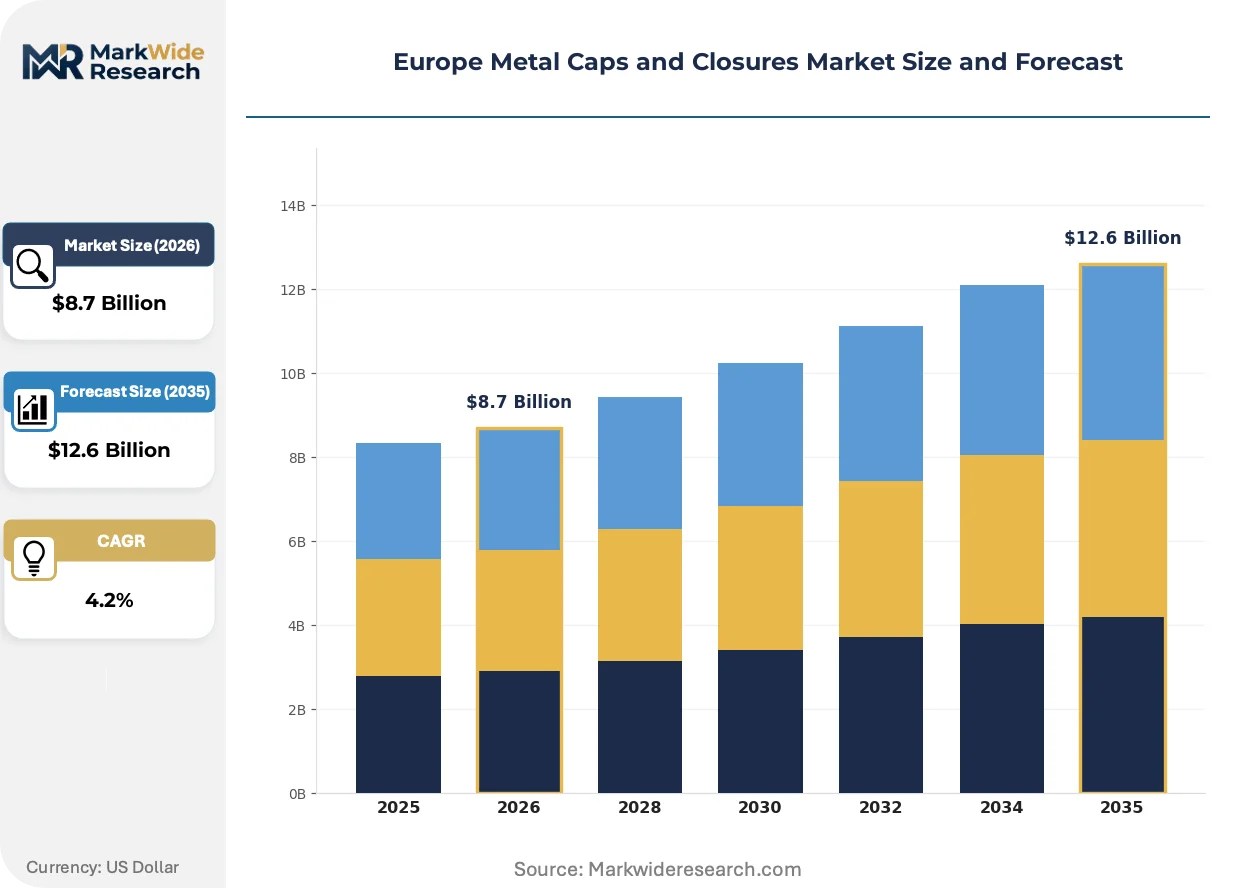
The EU Packaging and Packaging Waste Regulation is forcing aluminum substitution across closure manufacturing as recycled content mandates and surface coating restrictions reshape supplier economics and R&D priorities.
Growth Catalysts
- REACH compliance protocols:ECHA restrictions on certain tinplate surface chemistries are accelerating aluminum adoption among beverage closure suppliers seeking compliant material pathways.
- Hot-fill pasteurization compatibility:Twist-off cap formats with resealable threading are capturing expanded procurement share from European food processors running aseptic filling lines.
- Emilia-Romagna production concentration:Italy's design-to-manufacturing corridor is consolidating tamper-event wine closure exports across Southern European markets.
Market Restraints
- Steel and tinplate input volatility:Raw material cost swings for tin-coated steel sheet are compressing margin stability for traditional crown cap suppliers serving Central European brewing clusters.
- Aluminum supply concentration:Primary aluminum smelting capacity concentrates in Nordic and Eastern European zones, creating geographic vulnerability for screw closure manufacturers.
- Natural cork substitution ceiling:Premium champagne and aged wine categories maintain cork preference for oxygen transmission control, limiting aluminum closure penetration in heritage-protected appellations.
Strategic Opportunities
- Poland and Czech Republic brewing expansion:Central European craft beer production growth is generating unmet demand for specialized crown cap formats with custom embossing capabilities.
- Extended producer responsibility amendments:EU Green Deal collection infrastructure investments are creating first-mover advantage for closure suppliers with closed-loop aluminum recovery systems.
- Child-resistant dosing precision:Pharmaceutical and home care segments above 48mm diameter specifications are opening margin pools for multi-feature closure engineering.
Industry Challenges
- Deep-drawing die engineering talent:Precision metal forming expertise for complex thread geometries remains scarce across European technical training pipelines.
- CE marking migration testing timelines:Food-contact compliance validation for new coating chemistries extends product development cycles by 8-14 months.
- Multi-material line reconfiguration:Tinplate-to-aluminum conversion requires substantial press retooling and quality system recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Caps and Closures Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Riveted Caps, Twist-off Caps, Crown Caps, Metal Screw Caps Industry Vertical: Food & Beverage, Pharmaceuticals, Personal Care, Home Care Closure Diameter: 28mm, 38mm, 48mm, Custom Sizes Material: Aluminum, Steel, Tinplate, Other Alloys |
| Companies Covered | Guala Closures SpA, Pelliconi & C SpA, Technocap SpA, Crown Holdings Incorporated, Silgan Closures, Can-Pack SA, Sonoco Products Company, Herti JSC, Amcor PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Caps and Closures Market Trends and Innovations
Digital thread technologies and regulatory chemistry restrictions are converging to compress development timelines while elevating material traceability requirements across European closure supply chains.
Laser-etched serialization is digitizing aluminum screw closures for wine and spirits authentication. Premium beverage brands in France and Italy are adopting individual unit tracking to combat parallel trade. This capability is digitizing supply chain transparency and enabling direct-to-consumer verification platforms that bypass traditional distributor control.
REACH surface coating restrictions are eliminating chromate-based passivation layers from tinplate processing. ECHA enforcement is elevating R&D expenditure for compliant alternative chemistries. Food canning contract suppliers serving pan-European buyers are accelerating aluminum substitution to circumvent coating compliance complexity entirely.
Consolidated procurement by German food processing clusters is compressing supplier negotiation cycles and unbundling technical service from unit pricing. Bulk buyers in the industrial corridor are mandating vendor-managed inventory with telemetry-linked replenishment. This restructuring is most visible in steel and tinplate closure categories where specification standardization enables volume aggregation.
Europe Metal Caps and Closures Market Segmentation
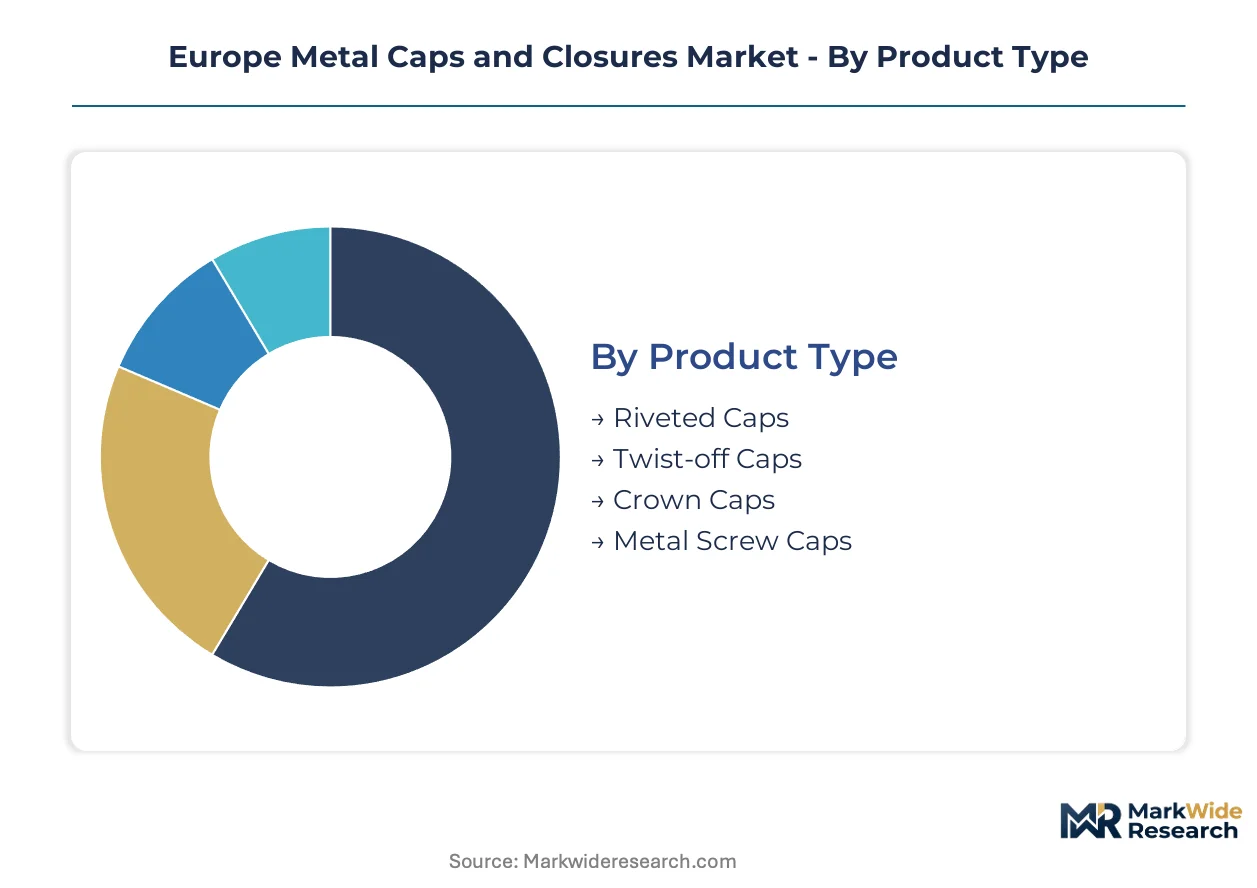
Segmentation in the Europe Metal Caps and Closures Market reveals how specification diversity drives supplier specialization and procurement fragmentation across precision-sealing applications. Closure format, end-use requirements, and material compliance create distinct competitive arenas with divergent margin structures and technical service intensity.
Product Type:
After-sales-service intensity varies sharply across closure formats, with complex threading geometries and tamper-evidence mechanisms demanding dedicated field engineering support while standardized formats operate on transactional replenishment models.
- Twist-off Caps:Resealable lug-threaded steel or tinplate closures designed for vacuum-sealed food jars and hot-fill pasteurization cycles. German food processing clusters in the Lower Saxony and Bavaria corridors drive concentrated procurement of 63mm and 82mm diameters for preserved vegetables and ready-meal segments, with REACH-compliant coating substitutions now extending supplier qualification timelines.
- Metal Screw Caps:Continuous-thread aluminum or steel closures with controlled torque specifications for beverage and pharmaceutical applications. French and Italian premium wine producers are expanding specification of 28mm and 30mm aluminum variants to eliminate cork taint risk, though heritage champagne appellations maintain natural cork requirements for controlled oxygen transmission.
- Riveted Caps:Cold-formed aluminum closures with integrated pour spouts for edible oil and spirits packaging.
- Crown Caps:Crimped tinplate shells with polyethylene liners for beer and carbonated soft drinks, facing margin compression from steel input volatility.
By volume, Twist-off Caps lead. By growth pace, Metal Screw Caps are expanding most quickly.
Industry Vertical:
Application-driven specification divergence separates commodity procurement from engineered solutions, with pharmaceutical and food safety mandates creating insurmountable compliance barriers for undifferentiated suppliers.
- Food & Beverage:The largest addressable demand pool spanning pasteurized jar foods, carbonated beverages, wine, spirits, and edible oils. Italy's Emilia-Romagna manufacturing corridor supplies tamper-evident wine closures across Southern Europe, while German industrial buyers consolidate steel and tinplate procurement through vendor-managed inventory programs with telemetry-linked replenishment.
- Pharmaceuticals:Child-resistant and senior-friendly closure systems for OTC medications and prescription packaging. Custom diameter specifications above 48mm with dosing-precision features command specification premiums in this segment, with CE marking migration testing extending development cycles.
- Personal Care:Dispensing closures for cosmetics and hair care with emphasis on aesthetic finishing and ergonomic actuation.
- Home Care:Chemical-resistant closures for cleaning products and laundry detergents requiring compatibility with aggressive formulations.
Food & Beverage dominates absolute volume. Pharmaceuticals delivers the steepest expansion trajectory through regulatory-driven specification upgrades.
Closure Diameter:
Dimensional standardization versus customization defines the margin architecture, with high-volume standardized diameters competing on unit economics while bespoke specifications capture engineering-value premiums.
- 28mm:The dominant beverage industry standard for wine, spirits, and water bottles, enabling press line standardization across European filling operations.
- 38mm:Widely specified for juices, sports drinks, and condiments requiring resealable convenience.
- 48mm:Food jar standard for preserved vegetables, sauces, and ready-meals compatible with hot-fill pasteurization.
- Custom Sizes:Diameter specifications deviating from ISO norms for pharmaceutical dosing precision, premium spirits presentation, or specialized industrial chemical containment.
28mm leads procurement volume. Custom Sizes gain share fastest through pharmaceutical and premium positioning applications.
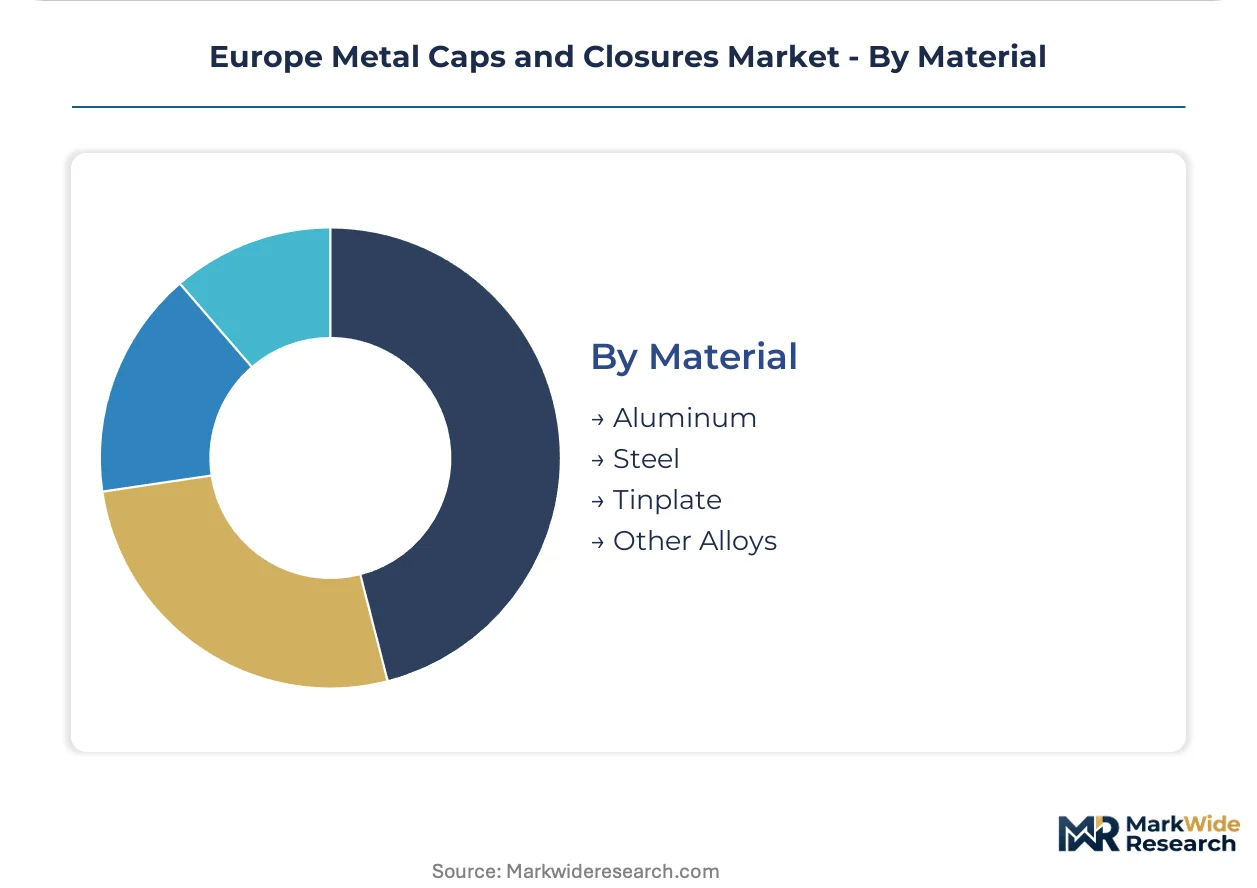
Material:
Supply concentration and regulatory chemistry restrictions are forcing material substitution decisions that reshape supplier capabilities and geographic sourcing strategies across the continent.
- Aluminum:Lightweight, infinitely recyclable metal dominating beverage screw closure production. ECHA restrictions on tinplate surface coatings are accelerating aluminum substitution, though primary smelting concentration in Nordic and Eastern European zones creates geographic supply vulnerability.
- Tinplate:Tin-coated steel sheet for crown caps and twist-off formats facing REACH compliance cost escalation. Alternative passivation chemistry R&D is elevating supplier investment requirements.
- Steel:Uncoated or lacquered carbon steel for industrial and economy-tier food applications.
- Other Alloys:Specialized copper-nickel or stainless formulations for chemical resistance or extreme temperature applications.
Tinplate retains volume leadership in food canning. Aluminum is climbing the fastest as beverage producers abandon cork and coated steel alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Europe, with Mediterranean markets prioritizing premium wine and spirits closures while Central European buyers concentrate on standardized food canning formats at scale.
Germany
Lower Saxony and Bavaria food processing clusters drive bulk procurement of 63mm and 82mm twist-off caps for preserved vegetables and ready-meals. The national packaging law mandates extended producer responsibility compliance, forcing tinplate suppliers into coating chemistry transitions. Vendor-managed inventory programs with telemetry-linked replenishment now dominate steel closure procurement in the industrial corridor.
Italy
Emilia-Romagna's design-to-manufacturing base exports tamper-evident wine closures across Southern Europe as premium beverage brands abandon natural cork. ECHA REACH protocols restrict chromate-based surface treatments, accelerating aluminum substitution among closure fabricators. Bologna-Modena production concentration anchors specialized screw closure engineering for French and Spanish winery clients.
France
Bordeaux and Champagne appellations sustain divergent closure preferences, with heritage champagne houses maintaining natural cork for oxygen transmission control while premium still wine producers convert to aluminum screw caps. ANSM pharmaceutical regulations drive child-resistant closure specifications for OTC packaging in the Île-de-France corridor. Paris-region contract manufacturers command premium positioning for 48mm-plus dosing-precision formats.
Poland
Central European craft brewing expansion generates unmet demand for specialized crown caps with custom embossing capabilities. EU Green Deal collection infrastructure investments create first-mover positioning for suppliers with closed-loop aluminum recovery systems. Warsaw-Łódź manufacturing zones attract multi-material press line investments serving pan-European beverage contracts.
Spain
Catalonia's packaging equipment ecosystem supports aluminum screw closure adoption among cava producers seeking cork taint elimination. EFSA migration limit enforcement extends CE marking validation timelines for new coating chemistries. Barcelona-area technical service providers specialize in hot-fill pasteurization compatibility testing for twist-off formats targeting export markets.
Europe Metal Caps and Closures Market Competitive Landscape
Capability concentration sits with Italian design-to-manufacturing specialists; scale advantage sits with pan-European multi-material operators serving food canning contracts. The market structures around three archetypes: premium beverage closure engineers, high-volume food canning suppliers, and specialized pharmaceutical-format fabricators. M&A activity targets aluminum conversion capabilities, while strategic partnerships secure Nordic primary aluminum supply.
Among Italy-based specialists, Guala Closures SpA and Pelliconi & C SpA exemplify the design-to-manufacturing archetype, occupying positions that bridge precision engineering with regional export concentration. Crown Holdings Incorporated anchors the scale-driven tier, representing multi-material line operators serving consolidated procurement by Central European food processors. These three sit within distinct competitive vectors—specialization versus standardization, regional density versus pan-European coverage—that define supplier positioning under tightening EU Packaging and Packaging Waste Regulation compliance.
| Leading Market Players |
|---|
| Guala Closures SpA |
| Pelliconi & C SpA |
| Technocap SpA |
| Crown Holdings Incorporated |
| Silgan Closures |
| Can-Pack SA |
| Sonoco Products Company |
| Herti JSC |
| Amcor PLC |
| Others |
Pricing and Supply Chain Analysis
Nordic primary aluminum smelting capacity concentrates upstream supply leverage for screw closure manufacturers, while tinplate coating chemistry transitions concentrate margin compression among Central European crown cap suppliers serving consolidated German food processors.
Pricing Analysis
Long-term offtake contracts dominate aluminum closure procurement as beverage brands secure volume commitments against Nordic smelter allocation constraints. Price differentiation hinges on REACH-compliant coating certification tiers and hot-fill pasteurization compatibility validation. Cost compression in tinplate categories is intensifying because ECHA chromate restrictions force R&D expenditure into alternative passivation chemistries. German food processing clusters exhibit highest price sensitivity through vendor-managed inventory aggregation, while pharmaceutical dosing-precision specifications above 48mm demonstrate lowest sensitivity due to child-resistant engineering premiums.
Supply Chain Analysis
Primary aluminum feedstock draws from Iceland, Norway, and Russia, with secondary recovery networks concentrating in Germany and Italy. Tin-coated steel sheet rests on Malaysian tin ore and Ukrainian steel coil inputs. Single-source vulnerability sits with chromate-based surface treatment chemicals facing ECHA phase-out timelines. Distribution runs through pan-European logistics hubs in Rotterdam and Hamburg serving just-in-time replenishment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation amendments are disrupting competitive economics through recycled content mandates and extended producer responsibility frameworks that favor aluminum-intensive closure portfolios.
For Market Incumbents: Pre-empt aluminum conversion capability gaps by acquiring deep-drawing die engineering talent scarce across Bologna-Modena technical training pipelines. Secure backward integration into Nordic primary aluminum supply through offtake partnerships before capacity allocation tightens. Accelerate REACH-compliant coating certification timelines to capture pharmaceutical contract specifications ahead of CE marking migration testing bottlenecks.
For New Entrants and Emerging Players: Central European craft brewing clusters in Poland and the Czech Republic represent the most penetrable entry point for specialized crown cap formats with custom embossing capabilities underserved by incumbent tinplate suppliers. Pharmaceutical child-resistant closure engineering above 48mm diameters offers specification-premium capture with lower volume scale requirements. A technical service-led go-to-market approach bypassing consolidated German vendor-managed inventory programs unlocks initial contract traction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Italian design-to-manufacturing specialists holding Emilia-Romagna production concentration and tamper-evident wine closure export dominance. Long-term viability across the analysis window favors aluminum-intensive portfolios with closed-loop recovery system integration. Monitor ECHA surface coating restriction enforcement timelines as inflection indicators for tinplate-to-aluminum substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Conversion Capacity Expansion | REACH compliance deadlines force tinplate suppliers into material substitution investments. |
| Closed-Loop Recovery System Deployment | EU Green Deal collection infrastructure creates first-mover positioning for circular supply chains. |
| Deep-Drawing Die Engineering Acquisition | Precision thread geometry talent scarcity constrains screw closure quality certification. |
| Pharmaceutical Format Certification Investment | ANSM child-resistant specifications command dosing-precision premiums above 48mm diameters. |
| Nordic Primary Aluminum Supply Partnership | Smelting concentration in Iceland and Norway creates geographic vulnerability for screw closure manufacturers. |
Research Methodology
A standing panel of closure fabrication plant managers, food processing procurement leads at German industrial clusters, beverage brand packaging directors, pharmaceutical regulatory affairs specialists, and ECHA compliance officers provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation against EU Packaging and Packaging Waste Regulation amendment drafts, ECHA REACH restriction proposals, customs trade data for aluminum and tinplate imports, and CE marking harmonized standards documentation. Bottom-up volume aggregation across product type, material, closure diameter, and end-use vertical triangulated against top-down macroeconomic demand modeling.
Scenario-bracketing around regulatory implementation timelines and raw material price volatility shaped projection outputs across the analysis window. Segmentation dimensions modeled include closure format complexity, material compliance tier, end-use safety specification intensity, and geographic production cluster concentration. CAGRs derived from installed base replacement cycles, beverage packaging format conversion rates, and pharmaceutical regulatory upgrade trajectories. Forecast inputs incorporated aluminum LME price band sensitivity and tinplate coating chemistry R&D expenditure curves.
Practitioners should monitor ECHA restriction enforcement acceleration, Nordic smelter capacity utilization, and German packaging law amendment cascades for early signals of forecast revision. Cross-checking against EU-wide packaging waste collection rate disclosures and national extended producer responsibility fee schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Cover Caps Market
Caps and Closures
Overcaps Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Drop Sealers Market