
 Push Pull Closure Market | 2026-2036
Push Pull Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Push Pull Closure Market Analysis
German injection molding specialists is consolidating capacity for high-precision push pull closure production. Bericap GmbH leverages its European toolmaking network to sustain complex multi-cavity output. Closure Systems International anchors North American supply through dedicated pharmaceutical-grade lines. Georg Menshen GmbH differentiates via deep specialization in tamper-evident push pull designs for regulated end uses.
Push pull closures are dispensing closures employing a linear push-to-open, pull-to-close mechanism, typically injection-molded from polypropylene or high-density polyethylene with integrated tamper-evident rings and defined actuation force thresholds. They secure liquid and semi-liquid products across pharmaceutical syrups, cosmetic serums, and beverage concentrates while enabling single-hand operation. Plastic dominates current volume owing to cost-efficient high-speed molding and broad chemical compatibility, though composite formats are gaining traction where barrier performance must reconcile with sustainability mandates. Reusable design types command premium positioning in cosmetics and personal care, while single-use variants retain scale advantage in pharmaceutical compliance packaging where regulatory batch traceability overrides circularity claims.
FDA 21 CFR regulations govern child-resistant packaging standards for pharmaceutical applications, directly dictating actuation force ranges and testing protocols for push pull closures. REACH and the EU Packaging and Packaging Waste Regulation impose material disclosure and recyclability thresholds that reshape resin selection and post-consumer content integration across European supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based material certification schemes to preempt compliance-driven specification changes.
Market Dynamics
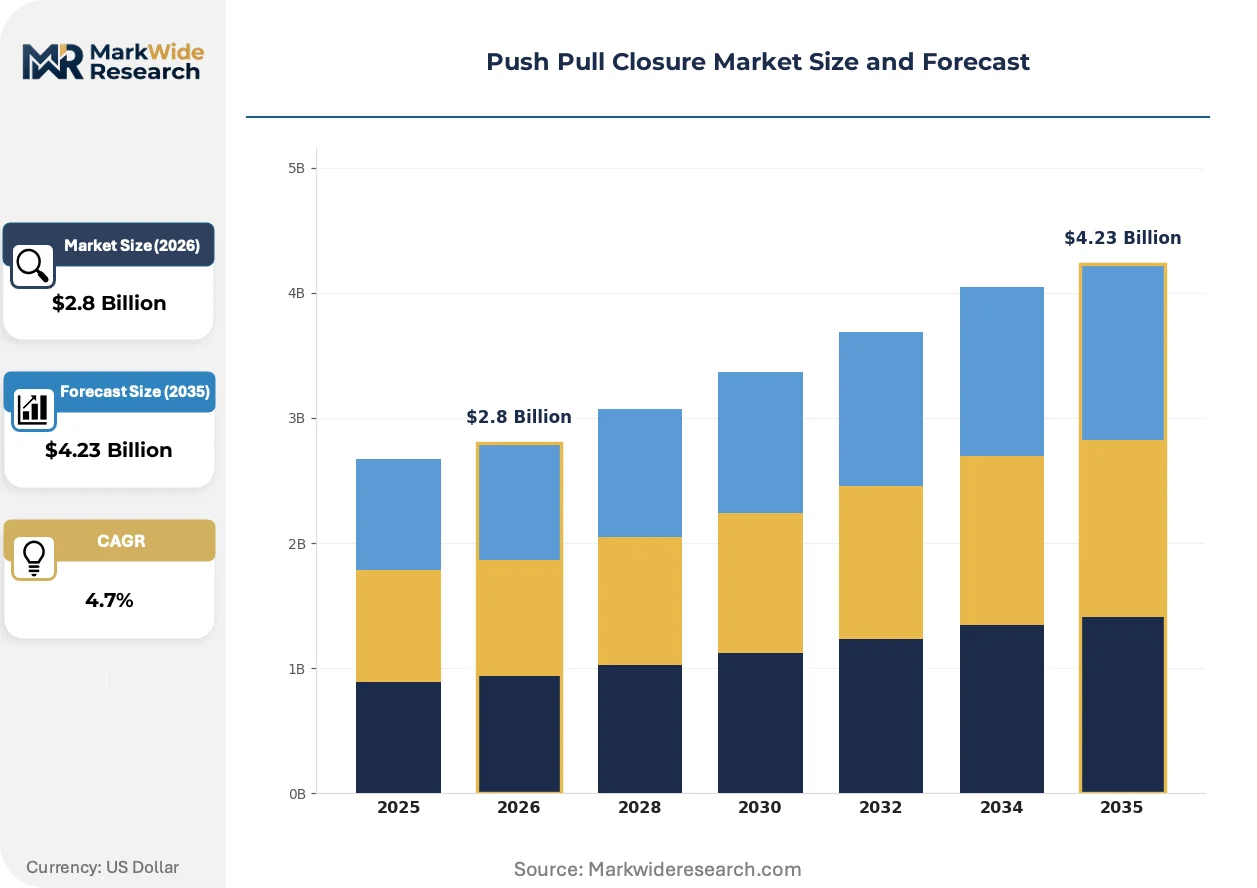
Pharmaceutical serialization mandates and EU Packaging and Packaging Waste Regulation recyclability thresholds are compressing resin selection flexibility while elevating precision molding requirements for child-resistant formats.
Growth Catalysts
- REACH chemical disclosure requirements:European formulators are accelerating migration-compliant polypropylene grades for pharmaceutical push pull closures to preempt ECHA substance restrictions.
- Precision molding clusters in Germany:Toolmaking networks serving central European pharmaceutical brands are expanding multi-cavity capacity for complex tamper-evident designs.
- FDA 21 CFR child-resistant standards:US pharmaceutical packaging lines are retrofitting for push pull actuation force compliance, pulling demand for validated closure systems.
Market Restraints
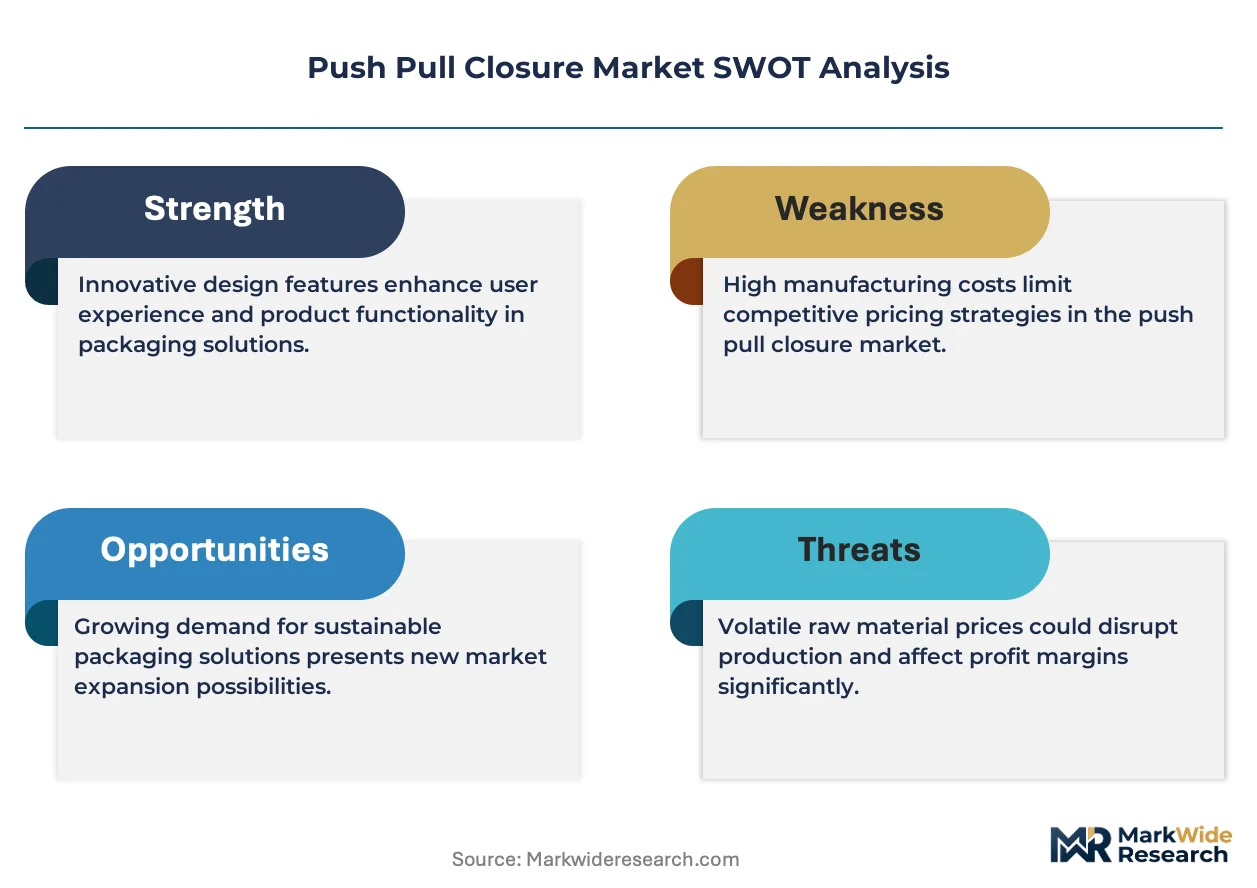
- Propylene feedstock volatility:Polypropylene resin costs fluctuate with naphtha-cracking economics, squeezing margin on high-volume pharmaceutical closure contracts.
- German toolmaking concentration:Precision mold fabrication for multi-cavity push pull formats depends on a narrow supplier base in Baden-Württemberg and Bavaria.
- Mechanical complexity ceiling:Integrated tamper-evident rings with defined break-torque specifications limit cycle-time reduction in high-speed injection molding.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO-aligned manufacturing for US and EU-bound generics is creating specification demand for FDA-validated push pull closures.
- Post-consumer recycled content mandates:EU Packaging and Packaging Waste Regulation targets for 2030 are opening specification windows for chemically recycled polypropylene in cosmetic applications.
- Connected packaging convergence:Near-field communication tag integration with push pull closures is automating authentication and supply-chain traceability for high-value pharmaceuticals.
Industry Challenges
- Multi-cavity mold validation timelines:Pharmaceutical-grade push pull closure qualification under FDA 21 CFR protocols extends commercialization cycles by 18-24 months.
- Recyclate contamination control:Post-consumer polypropylene streams struggle to meet pharmaceutical extractables and leachables thresholds without advanced sorting and decontamination infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Push Pull Closure Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Glass, Composite End User: Food & Beverage, Cosmetics, Pharmaceuticals, Industrial Distribution Channel: Online Retail, Supermarkets, Distributors, Direct Sales Design Type: Single-Use, Reusable, Custom, Standard |
| Companies Covered | Georg Menshen GmbH, Bericap GmbH, Closure Systems International, O.Berk, Mold-Rite Plastics, CL Smith, Silgan Closures, Berry Global Group, Amcor Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Push Pull Closure Market Emerging Trajectories
Automation of quality assurance and regulatory compliance is compressing development timelines while elevating the technical barrier to specification approval in pharmaceutical and cosmetic end uses.
Electro-optical inline inspection systems are automating defect detection in multi-cavity push pull closure production. German pharmaceutical packaging converters are deploying these systems at pilot scale for tamper-evident ring integrity verification. The technology is automating the elimination of manual sampling protocols that previously bottlenecked high-speed lines.
REACH Annex XVII restrictions on intentionally added microplastics are tightening material formulation disclosure requirements for cosmetic packaging. European compounders are re-engineering polypropylene additive packages to maintain UV stability without restricted substances. Pharmaceutical-grade closures face downstream pressure to demonstrate equivalent compliance to access shared molding infrastructure.
Brand-owner consolidation in European cosmetics is compressing supplier qualification cycles and elevating batch-traceability requirements. Mid-sized contract manufacturers are adopting serialized push pull closure sourcing to retain preferred vendor status with L'Oréal and Beiersdorf procurement functions. This pattern concentrates specification-setting power with German and French headquarters functions.
Push Pull Closure Market Segmentation
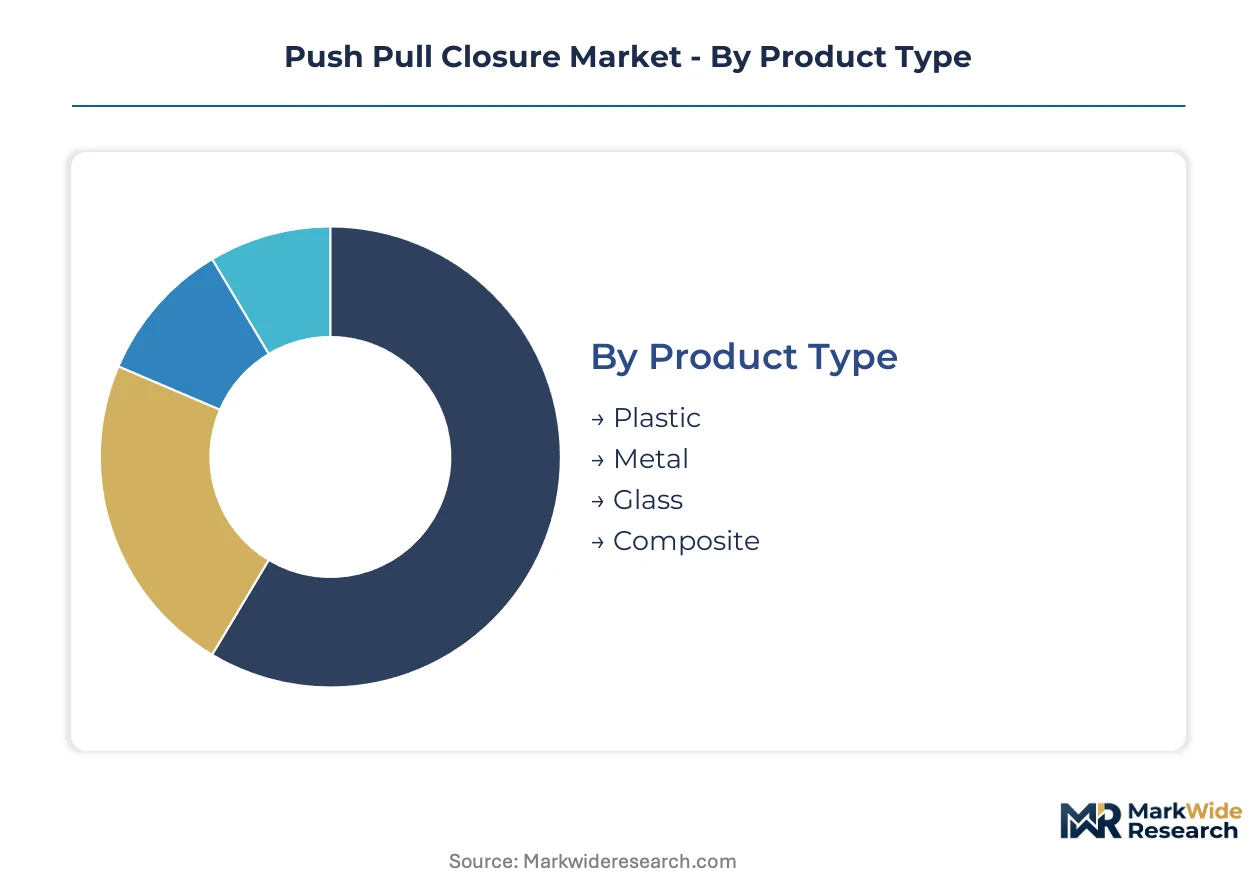
Push pull closure procurement decisions cascade from material specifications through regulatory compliance requirements to channel economics. Understanding how these dimensions intersect reveals where specification power concentrates and where margin compression threatens.
Product Type:
Standalone closure systems dominate volume, while embedded multi-component formats command premium positioning in regulated end uses.
- Plastic:Polypropylene and high-density polyethylene formulations enable high-speed injection molding with integrated tamper-evident rings. German precision molding clusters in Baden-Württemberg serve central European pharmaceutical and cosmetics brands with multi-cavity output validated under FDA 21 CFR protocols.
- Metal:Aluminum and steel variants deliver barrier performance for oxygen-sensitive pharmaceutical syrups and beverage concentrates. REACH chemical disclosure requirements are accelerating migration-compliant grade adoption as ECHA substance restrictions tighten.
- Glass:Borosilicate and soda-lime formats address high-purity pharmaceutical applications where extractables thresholds override cost considerations.
- Composite:Multi-layer structures reconcile sustainability mandates with barrier performance in cosmetic serum packaging.
Volume placements concentrate in plastic; the faster expansion belongs to composite.
End User:
Cost tiers separate compliance-driven pharmaceutical procurement from cosmetics sustainability premiums and food-service scale economics.
- Pharmaceuticals:Child-resistant push pull formats face FDA 21 CFR actuation force standards and CDSCO-aligned validation for Indian export packaging. Serialization mandates compress resin selection flexibility while elevating precision molding requirements.
- Cosmetics:Reusable design types command premium positioning as L'Oréal and Beiersdorf procurement functions elevate batch-traceability requirements. REACH Annex XVII microplastic restrictions are re-engineering polypropylene additive packages for UV stability compliance.
- Food & Beverage:Single-hand operation requirements dominate beverage concentrate applications with cost-efficient high-speed molding.
- Industrial:Chemical compatibility specifications govern adhesive and lubricant packaging with less stringent regulatory overhead.
Pharmaceuticals anchor specification-setting power; cosmetics is climbing the fastest on sustainability premiums.
Distribution Channel:
Customer type stratification separates direct specification relationships from intermediated procurement with divergent technical support requirements.
- Direct Sales:Pharmaceutical-grade closure qualification under FDA 21 CFR protocols extends commercialization cycles, favoring dedicated technical partnership models.
- Distributors:Mid-sized contract manufacturers access validated inventory for serialized sourcing to retain preferred vendor status with consolidated brand owners.
- Supermarkets:Private-label beverage and food applications concentrate volume with standardized specifications.
- Online Retail:Niche cosmetic and personal care brands access smaller minimum order quantities with extended delivery timelines.
Direct sales capture the steepest expansion trajectory as regulatory validation complexity rises.
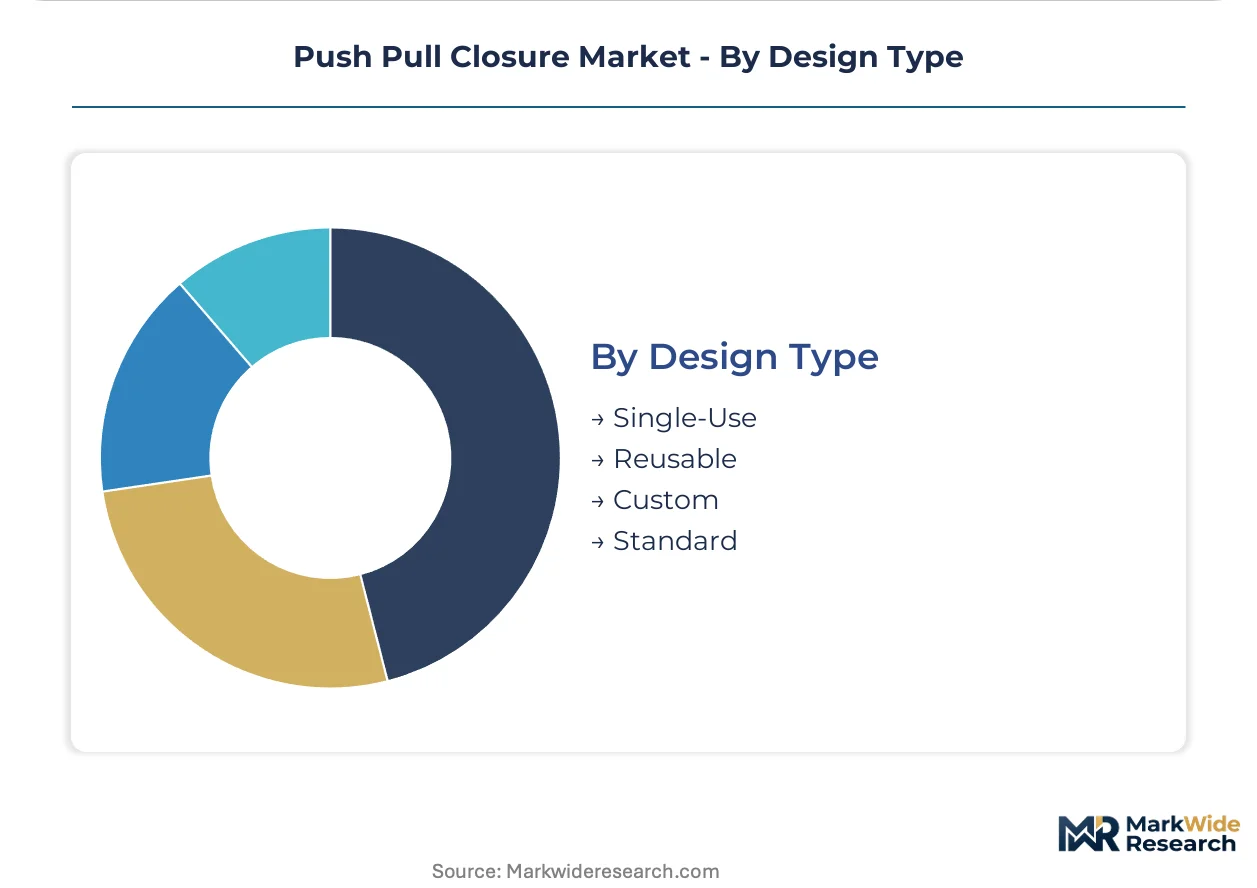
Design Type:
Maturity stages separate entrenched single-use formats from emerging reusable and custom architectures with divergent tooling investment profiles.
- Single-Use:Retains scale advantage in pharmaceutical compliance packaging where regulatory batch traceability overrides circularity claims.
- Reusable:Premium positioning in cosmetics and personal care responds to EU Packaging and Packaging Waste Regulation targets for 2030.
- Custom:Tamper-evident push pull designs for regulated end uses require deep specialization and extended mold validation timelines.
- Standard:Commodity positioning serves high-volume food and beverage applications with minimal specification differentiation.
Single-use maintains volume dominance; reusable formats gain share fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene feedstock availability clusters near major naphtha-cracking centers in Germany, the United States, and China. These locations anchor precision molding capacity for pharmaceutical-grade push pull closures. Regulatory divergence across FDA, EMA, and NMPA jurisdictions shapes resin selection and validation protocols.
United States
FDA 21 CFR child-resistant packaging standards drive actuation force compliance testing for pharmaceutical syrups and liquid medications. The EPA oversees resin manufacturing emissions near Gulf Coast petrochemical corridors. Closure Systems International maintains dedicated pharmaceutical-grade production lines serving domestic generics manufacturers and export-oriented contract packagers.
Germany
REACH chemical disclosure requirements and EU Packaging and Packaging Waste Regulation recyclability thresholds compress material formulation flexibility. ECHA substance restrictions accelerate migration-compliant polypropylene grade adoption. Baden-Württemberg and Bavaria precision molding clusters expand multi-cavity capacity for tamper-evident designs serving central European pharmaceutical brands.
India
CDSCO-aligned manufacturing for US and EU-bound generic pharmaceuticals creates specification demand for FDA-validated push pull closures. The PLI scheme for pharmaceuticals incentivizes packaging localization. Maharashtra and Gujarat injection molding corridors scale output for export-compliant child-resistant formats.
China
NMPA pharmaceutical packaging regulations and GB standards govern domestic syrup and oral liquid containment. MIIT industrial policy prioritizes high-precision mold fabrication for medical-grade plastics. Yangtze River Delta molding bases upgrade cleanroom capacity for regulated pharmaceutical applications.
Switzerland
Swissmedic pharmaceutical packaging requirements enforce stringent extractables and leachables thresholds for high-purity applications. The country's dual focus on precision manufacturing and sustainability mandates shapes premium closure sourcing. Basel-area pharmaceutical headquarters functions concentrate specification-setting power for European supply chains.
Push Pull Closure Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue composite material integration and connected packaging functionality. The vendor base stratifies across three maturity levels: multinational closure specialists with validated pharmaceutical lines, regional injection molding houses serving cosmetics and food applications, and niche custom molders for tamper-evident designs. Two dominant competitive moves define current positioning: backward integration into precision toolmaking to compress mold validation timelines, and strategic partnerships with resin compounders to secure migration-compliant material streams.
Among German-based specialists, Georg Menshen GmbH and Bericap GmbH exemplify the precision-molding archetype anchored in Baden-Württemberg's industrial corridor. Closure Systems International represents the North American pharmaceutical-grade tier with dedicated validation infrastructure. These three entities collectively illustrate how geographic proximity to regulatory agencies and petrochemical feedstock shapes competitive positioning in child-resistant and tamper-evident closure supply.
| Leading Market Players |
|---|
| Georg Menshen GmbH |
| Bericap GmbH |
| Closure Systems International |
| O.Berk |
| Mold-Rite Plastics |
| CL Smith |
| Silgan Closures |
| Berry Global Group |
| Amcor Limited |
| Others |
Supply Flow & Price Mechanics
EU Packaging and Packaging Waste Regulation recyclability targets for 2030 gate access to premium-tier pharmaceutical and cosmetics contracts, concentrating qualified supply among German precision molders with validated migration-compliant polypropylene streams. Buyers lacking certified circular material pathways face exclusion from L'Oréal and Beiersdorf procurement functions, compressing margin for undifferentiated commodity suppliers.
Pricing Analysis
Validation service bundling separates pharmaceutical-grade closure suppliers from unbundled commodity producers. Three-tier pricing structure across FDA-validated premium, REACH-compliant standard, and economy tiers reflects certification investment recovery timelines. Cost compression in economy-grade food and beverage closures intensifies as Indian export packaging scales output for generics manufacturers. Pharmaceutical buyers exhibit lowest price sensitivity due to batch traceability mandates overriding procurement cost targets.
Supply Chain Analysis
Regional distribution centers in Baden-Württemberg, Bavaria, and North Rhine-Westphalia anchor hub-and-spoke fulfillment for central European pharmaceutical brands. Polypropylene resin supply draws from German and Belgian naphtha-cracking corridors, with toolmaking dependencies concentrated in Baden-Württemberg precision clusters. Single-source vulnerability in multi-cavity mold fabrication elevates lead time risk for custom tamper-evident designs. Distribution runs through direct technical partnerships for validated pharmaceutical lines and distributor intermediaries for standardized cosmetic applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR child-resistant packaging standards erect a cost-of-compliance barrier that protects validated incumbents while forcing marginal producers toward unregulated food-service segments.
For Market Incumbents: Deploy backward integration into precision toolmaking to compress 18-24 month mold validation timelines threatened by German toolmaking concentration. Anchor capacity expansion in Maharashtra and Gujarat corridors to capture CDSCO-aligned pharmaceutical export packaging growth. Certification investment in chemically recycled polypropylene streams defends premium positioning against REACH Annex XVII additive restrictions. For New Entrants and Emerging Players: Launch via distributor-mediated access to mid-sized contract manufacturers seeking serialized sourcing for L'Oréal and Beiersdorf preferred vendor status. Target Indian pharmaceutical export packaging as the most penetrable geography, where PLI scheme localization incentives outpace domestic validation infrastructure. Pursue composite material integration for cosmetic serum applications as a specification-differentiated entry path. For Investors and Strategic Acquirers: Closure Systems International's pharmaceutical-grade line expansion is the leading indicator that North American generics manufacturing is consolidating around validated suppliers. Five-to-ten year viability favors precision molders with captive toolmaking and migration-compliant resin partnerships. Monitor ECHA substance restriction announcements as the dominant signal for material formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Toolmaking | Compresses FDA 21 CFR validation timelines for multi-cavity pharmaceutical molds. |
| Migration-Compliant Polypropylene Grade Adoption | Preempts REACH Annex XVII restrictions on cosmetic packaging additives. |
| CDSCO-Aligned Manufacturing Localization | Captures Indian pharmaceutical export packaging specification demand. |
| Chemically Recycled Content Integration | Opens EU Packaging and Packaging Waste Regulation 2030 target compliance pathways. |
| Near-Field Communication Tag Integration | Automates authentication for high-value pharmaceutical connected packaging. |
Methodological Framework
Multi-period observation of resin price indices, mold validation timelines, and regulatory submission volumes anchored the trend analysis, supplemented by interviews with injection molding plant managers, pharmaceutical packaging procurement leads, cosmetic brand technical directors, and distributor channel partners. Secondary validation drew from ECHA restriction proposal databases, FDA 21 CFR guidance documents, EU Packaging and Packaging Waste Regulation impact assessments, and German plastics association production statistics. Bottom-up capacity modeling and top-down demand triangulation reconciled volume estimates across the analysis window.
Segment-weighting applied product type, end user, distribution channel, and design type dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves against historical pharmaceutical serialization mandate adoption patterns and EU circular economy policy implementation trajectories. Forecast inputs incorporated polypropylene feedstock spread volatility and precision molding capacity utilization rates from Baden-Württemberg industrial surveys.
Feedstock price volatility, ECHA substance restriction timing, and pharmaceutical serialization mandate enforcement intensity are the dominant revision risks warranting forecast sensitivity testing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Tube Closures Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Ring Pull Caps Market