
 Global Die Cut Lids Market | 2026-2036
Global Die Cut Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Die Cut Lids Market Analysis
Single-serve dairy processors is collapsing as the dominant buyer archetype while pharmaceutical contract packers gain procurement share. Amcor plc leverages its global converting footprint to supply multi-material lid formats across both segments. Constantia Flexibles Group GmbH anchors European pharmaceutical lid demand through specialized aluminum barrier solutions. Winpak Ltd. competes in North American dairy with high-speed forming compatibility and freezer-grade seal performance.
Die cut lids are pre-cut sealing membranes, typically manufactured from aluminum foil laminates, plastic films, or paperboard composites with specified peel-force and hermetic seal parameters, designed to close cups, trays, and containers across food, beverage, and healthcare applications. Aluminum lids sustain premium positioning in retort and aseptic applications where oxygen and moisture barrier performance commands margin premiums. Plastic lids dominate volume in chilled dairy due to cost efficiency and in-mold label compatibility. Composite structures are gaining fastest in functional food segments requiring dual-compartment separation or active packaging integration.
FDA food contact substance regulations, EU REACH compliance for adhesive and coating chemistries, and China's GB standards for composite food packaging materials collectively shape material selection and migration testing protocols across the value chain. EFSA and FDA both mandate specific heavy metal thresholds and sensory neutrality for lid-to-food contact surfaces, forcing converters to maintain dual certification portfolios. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mono-material recyclable lid platforms or defend multi-layer barrier performance through chemical recycling partnerships.
Market Dynamics
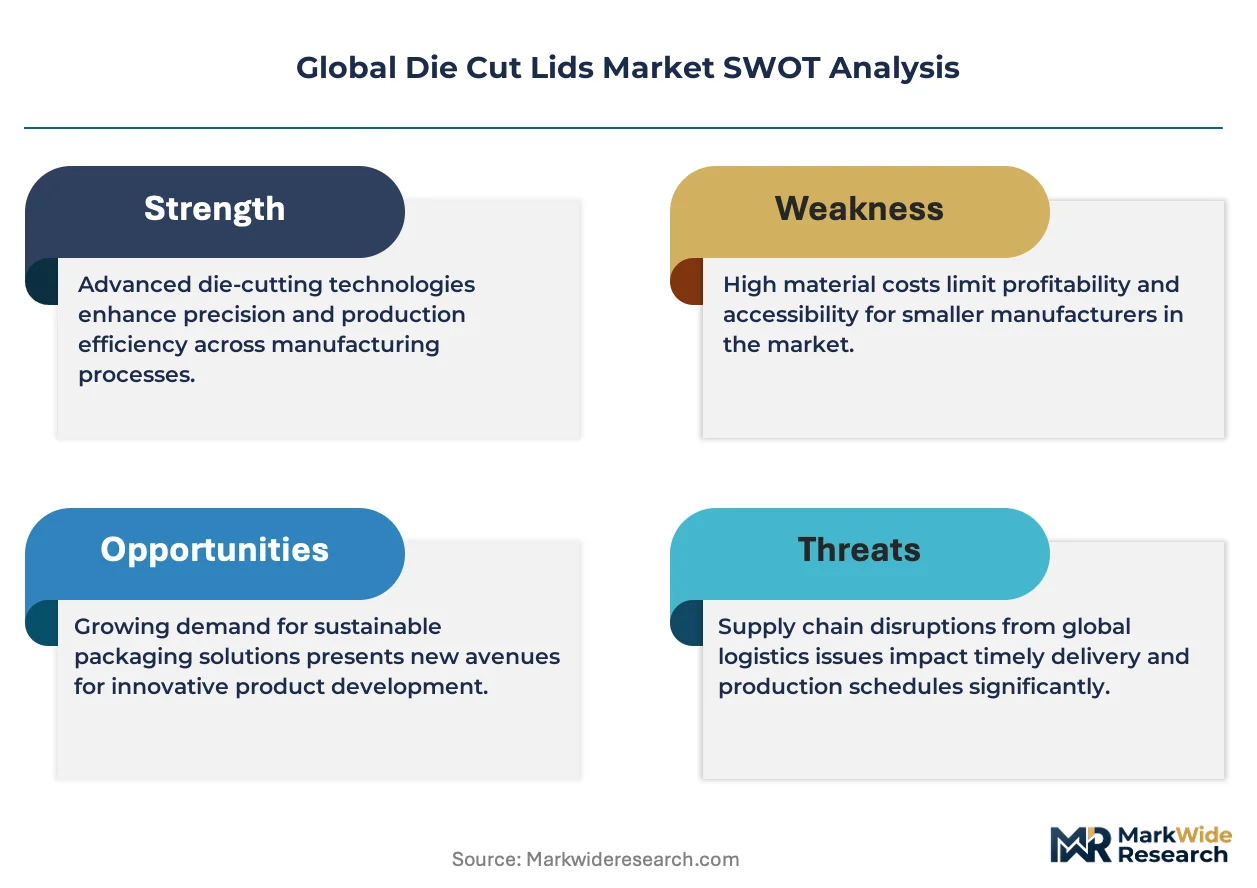
The EU Packaging and Packaging Waste Regulation (PPWR) is forcing converters to re-engineer multi-layer lid structures for recyclability, collapsing traditional barrier-performance trade-offs that previously defined competitive positioning.
Growth Catalysts
- Single-serve dairy formats:Chilled yogurt and fresh cheese cups in Germany, China, and the United States drive volume demand for peelable lidded containers across convenience retail channels.
- REACH compliance frameworks:ECHA-mandated adhesive and coating chemistry disclosures accelerate migration toward certified low-migration laminates in European pharmaceutical packaging.
- Aluminum foil barrier technology:Retort and aseptic applications sustain premium lid margins through oxygen and moisture exclusion performance in shelf-stable nutrition products.
Market Restraints
- Aluminum ingot price volatility:Raw material cost swings compress converter margins on foil-dominant lid formats, forcing pass-through pricing negotiations with dairy processors.
- Multi-material incompatibility:Current recycling infrastructure cannot sort aluminum-polyethylene laminates, creating disposal cost liabilities under emerging extended producer responsibility schemes.
- Barrier film supply concentration:Specialized coextruded films for high-performance lids concentrate among limited European and Japanese resin compounders, elevating single-source risk.
Strategic Opportunities
- India dairy modernization:Cold chain expansion and organized retail penetration create addressable demand for hermetically sealed single-serve cups in Mumbai, Delhi, and Bangalore processing corridors.
- Mono-material recyclable platforms:Polypropylene-only lid structures compatible with cup body recycling streams unlock compliance advantages under EU Green Deal circularity mandates.
- Active packaging integration:Oxygen-scavenging and moisture-regulating lid membranes extend shelf life in functional food segments requiring dual-compartment separation.
Industry Challenges
- Migration testing certification timelines:EFSA and FDA dual-approval protocols for new adhesive chemistries extend product development cycles by 18-24 months, delaying format launches.
- High-speed forming compatibility:Lid seal performance must synchronize with 1,200+ units-per-minute dairy filling lines, requiring precise peel-force calibration across temperature ranges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Die Cut Lids Market |
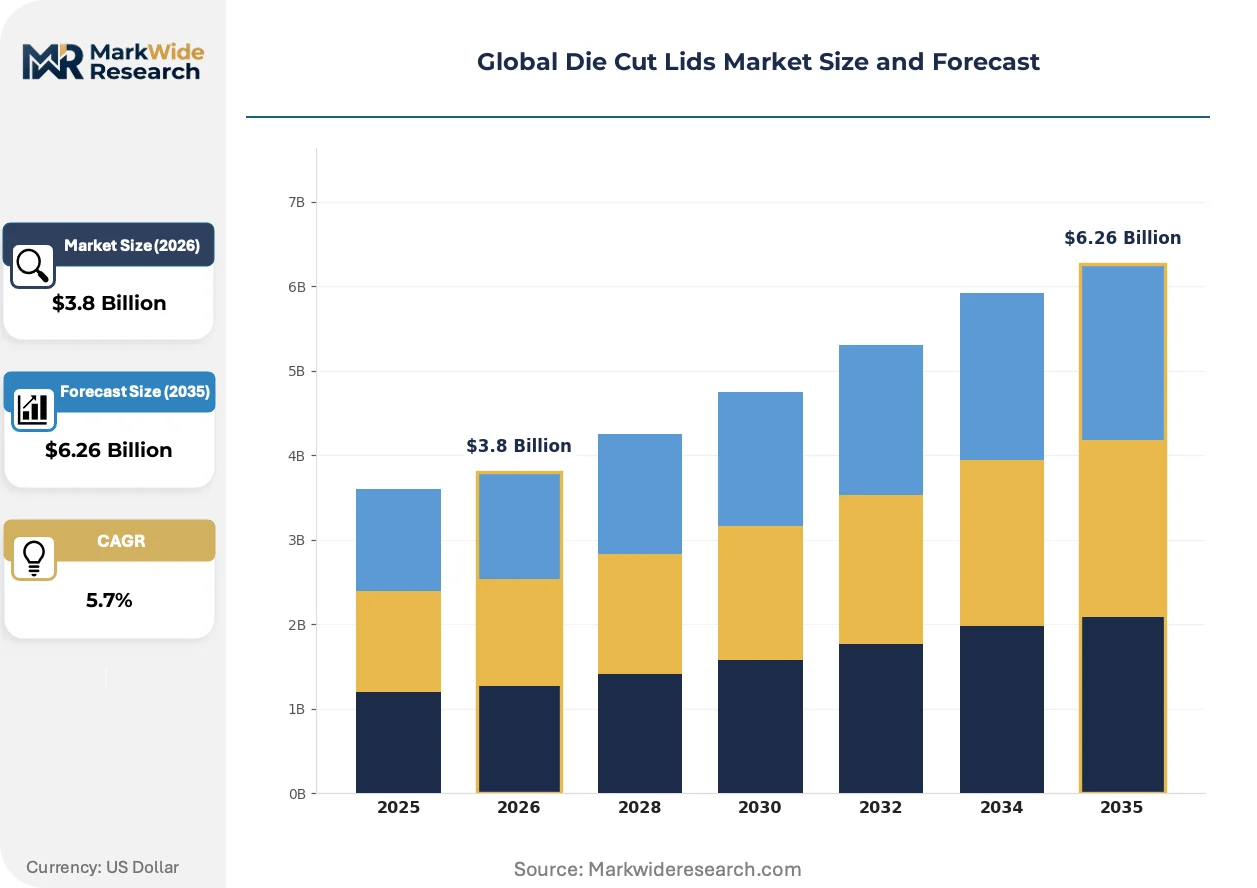
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paperboard, Aluminum, Composite Application: Food Packaging, Beverage Packaging, Personal Care, Household Products End User: Food Industry, Beverage Industry, Pharmaceutical Sector, Cosmetics Sector Distribution Channel: Online Retail, Supermarkets, Wholesalers, Direct Sales |
| Companies Covered | Avery Dennison Corporation, Amcor plc, Constantia Flexibles Group GmbH, Winpak Ltd., ProAmpac, Sonoco Products Company, Sealed Air Corporation, Quantum Packaging, Watershed Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Die Cut Lids Market Emerging Trajectories
Material science convergence and regulatory pressure are collapsing the traditional aluminum-plastic dichotomy, forcing simultaneous investment in barrier performance and end-of-life circularity.
Smart lid technologies incorporating RFID tags and freshness indicators are miniaturizing at scale. Pharmaceutical contract packers in Germany and Switzerland are piloting temperature-logging lids for cold-chain biologics. This capability is miniaturizing unit costs from specialty pharmaceutical applications toward broader food traceability deployments.
EFSA has tightened heavy metal thresholds and sensory neutrality requirements for lid-to-food contact surfaces. Converters must now maintain dual certification portfolios across FDA and EU regimes. Dairy and ready-to-drink beverage segments face the steepest compliance re-engineering costs, driving consolidation among mid-tier suppliers unable to absorb testing overhead.
Buyer concentration among pan-European dairy cooperatives is compressing supplier negotiation leverage. Three large processing groups now control majority procurement for single-serve yogurt formats, shifting contract terms toward total-cost-of-ownership frameworks that penalize seal-failure rates. This concentration is most visible in German and French dairy basins where converting capacity clusters within 150 kilometers of processing hubs.
Global Die Cut Lids Market Segmentation
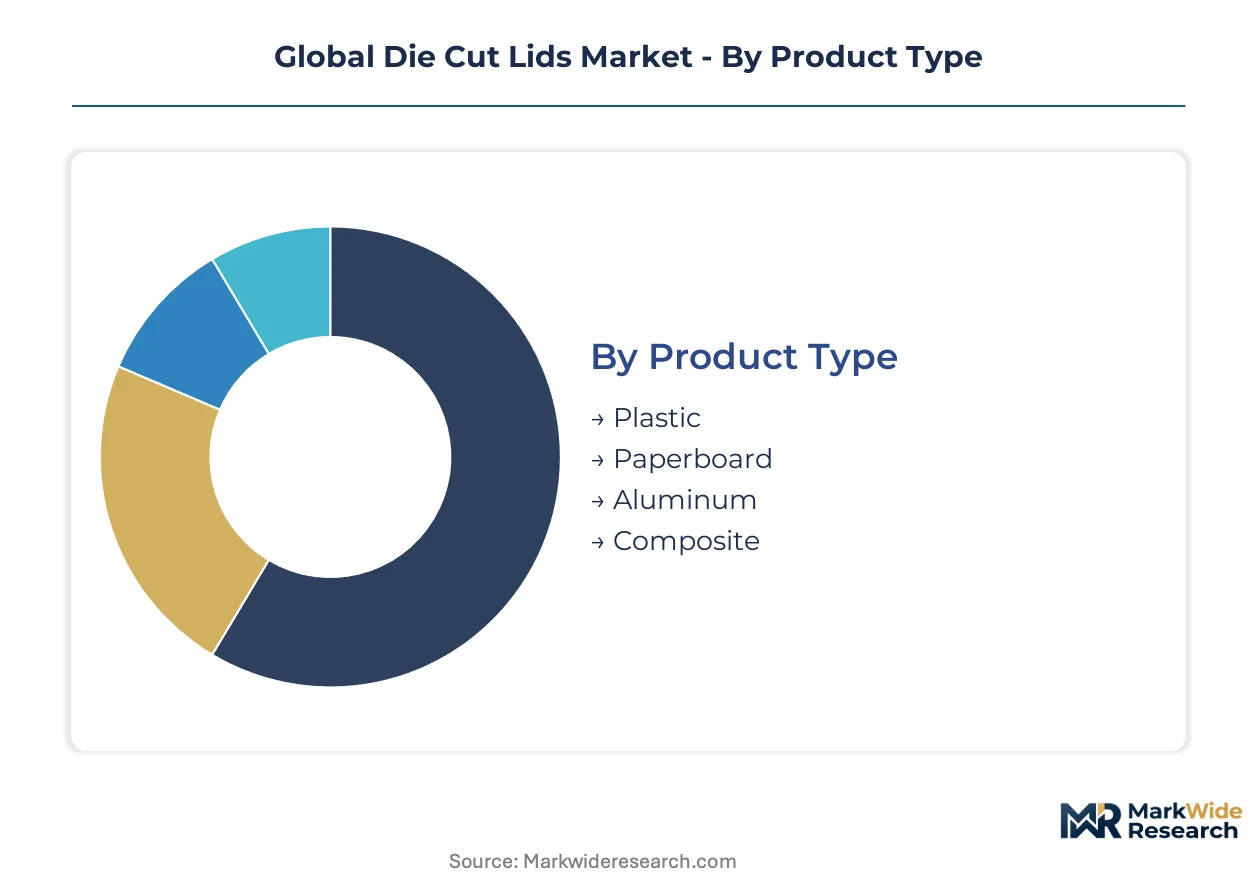
Die cut lid procurement patterns diverge sharply across material platforms and end-use specifications, with dairy processors, pharmaceutical contract packers, and cosmetics manufacturers each imposing distinct barrier, seal-force, and regulatory compliance requirements on converter portfolios.
Product Type:
Plastic lids dominate domestic consumption in Germany, China, and the United States where chilled dairy processing clusters drive high-volume, short-lead-time demand; aluminum and composite formats tilt toward export-oriented pharmaceutical and retort food applications requiring extended shelf-life certification.
- Plastic:Polypropylene and polystyrene laminates form the cost-efficient backbone of chilled yogurt and fresh cheese cup sealing. German and US dairy cooperatives specify peel-force ranges of 3-8 N/25mm for consumer-friendly opening, with in-mold label compatibility driving format standardization across convenience retail channels.
- Aluminum:Multi-layer foil structures with heat-seal lacquers deliver oxygen transmission rates below 0.01 cm³/m²/day for retort and aseptic nutrition products. Demand concentrates in Swiss and German pharmaceutical packaging where EFSA-mandated heavy metal thresholds below 0.5 mg/kg force specialized smelter relationships and dual-certification testing protocols.
- Paperboard:Fiber-based lids with polymer barrier coatings serve premium ice cream and dessert segments requiring freezer-grade seal performance down to -25°C. Japanese and South Korean converters lead technical development for this niche.
- Composite:Hybrid aluminum-plastic-paper structures enable dual-compartment separation in functional food applications. Active packaging integration—oxygen scavengers, moisture regulators—expands fastest in Swiss and Dutch nutritional supplement markets.
Plastic lids hold the largest share; momentum sits with composite formats as functional food brands demand integrated barrier-plus-dispensing functionality.
Application:
Volume scales inversely with margin across application tiers, with beverage packaging running at commodity throughput rates while personal care commands 3-4x unit premiums for aesthetic and tamper-evident specifications.
- Food Packaging:Single-serve dairy cups, ready meals, and retort trays constitute the demand core. German and French dairy basins process 1,200+ units per minute, requiring lid seal synchronization across temperature-calibrated forming lines with failure-rate penalties written into procurement contracts.
- Beverage Packaging:Ready-to-drink coffee, probiotic shots, and functional beverages drive peelable lidding demand in Chinese and US metropolitan markets. Cold-chain expansion in Indian organized retail creates new addressable demand in Mumbai and Delhi processing corridors.
- Personal Care:Cosmetic jar sealing and single-use mask packaging specify ultra-low odor migration and premium tactile surfaces. Swiss and French luxury cosmetics brands impose sensory neutrality standards exceeding FDA baseline requirements.
- Household Products:Wipe canisters and cleaning pod trays utilize cost-optimized lidding with child-resistant peel features. This segment tracks broader private-label retail trends rather than driving material innovation.
Food packaging commands the volume base; beverage packaging is climbing the fastest as functional drink formats proliferate across convenience channels.
End User:
Procurement sophistication varies dramatically by sector, with pharmaceutical buyers mandating 18-24 month migration testing documentation while food processors prioritize line-speed compatibility and total-cost-of-ownership frameworks.
- Food Industry:Pan-European dairy cooperatives and Chinese yogurt processors dominate procurement volume. Three large processing groups now control majority single-serve yogurt procurement in Germany and France, compressing supplier negotiation leverage toward penalty-based contract terms.
- Beverage Industry:Energy drink and ready-to-drink coffee brands in the United States and China specify high-barrier lidding for oxygen-sensitive formulations. Brazilian and Mexican bottlers represent emerging demand as organized retail penetration deepens.
- Pharmaceutical Sector:German and Swiss contract packers anchor European demand for aluminum barrier solutions. Temperature-logging lid pilots for cold-chain biologics are miniaturizing from specialty applications toward broader deployment.
- Cosmetics Sector:Premium skincare brands in France, South Korea, and Japan drive demand for aesthetic-grade lidding with embossed branding and holographic authentication features.
Food industry procurement holds the largest share; pharmaceutical sector engagement is expanding most quickly as biologics packaging requirements tighten.
Distribution Channel:
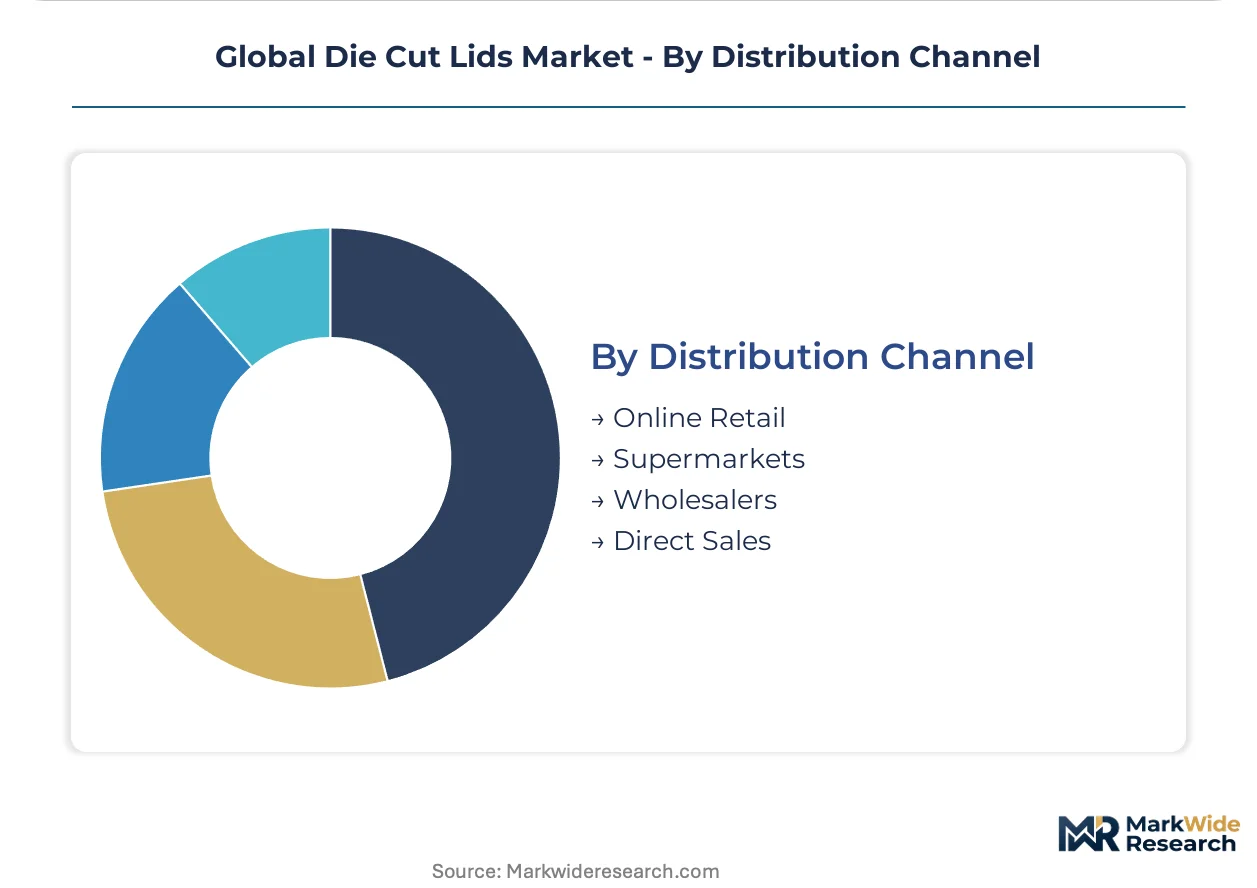
Channel selection correlates with order scale and technical service intensity, with direct sales capturing complex pharmaceutical specifications while wholesalers aggregate fragmented food processor demand.
- Direct Sales:Large dairy cooperatives and pharmaceutical contract packers negotiate multi-year supply agreements with dedicated technical service support. German and US converters maintain sales engineering teams within 150 kilometers of major processing hubs.
- Wholesalers:Regional distributors aggregate mid-tier food processor demand across secondary cities in India, Brazil, and Eastern Europe. Inventory pooling reduces lead times for standard polyethylene and polypropylene lid specifications.
- Supermarkets:Private-label retail chains in the United Kingdom and Australia increasingly specify direct converter relationships for store-brand dairy and beverage lines, bypassing traditional processor intermediaries.
- Online Retail:E-procurement platforms capture spot demand and small-batch specialty orders, particularly for cosmetic and household product startups lacking established supplier relationships.
Direct sales hold the largest share; online retail is gaining share fastest as digital procurement platforms penetrate mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export aluminum barrier lids to Swiss pharmaceutical packers, establishing the Rhine-Alpine corridor as the primary trade flow for high-specification sealing membranes in Europe.
United States
Single-serve dairy processors in Wisconsin and New York State specify peelable polypropylene lids for 1,200-unit-per-minute filling lines. FDA food contact substance regulations mandate migration testing for adhesive chemistries. Chicago and Minneapolis converting clusters supply yogurt cooperatives across the Midwest with freezer-grade seal specifications.
Germany
Pan-European dairy cooperatives in Bavaria and Lower Saxony consolidate procurement for chilled yogurt formats. EFSA heavy metal thresholds below 0.5 mg/kg force specialized smelter relationships for aluminum lid production. The Stuttgart converting corridor supplies pharmaceutical contract packers in Basel with barrier-certified membranes.
China
Ready-to-drink beverage brands in Shanghai and Guangzhou drive demand for oxygen-scavenging lid technologies. GB standards for composite food packaging materials shape material selection protocols. The Yangtze River Delta processing corridor integrates lidding supply with dairy cold-chain expansion in Hangzhou and Nanjing.
Switzerland
Pharmaceutical contract packers in Basel and Zurich anchor European demand for temperature-logging lid pilots. Swissmedic regulations for cold-chain biologics extend barrier performance requirements. The Swiss-German border region concentrates specialized aluminum converting capacity for high-margin healthcare applications.
India
Organized retail penetration in Mumbai and Delhi creates addressable demand for hermetically sealed single-serve cups. FSSAI packaging safety standards govern adhesive and coating chemistries for dairy applications. The Maharashtra and Karnataka processing corridors import forming-compatible lid specifications from East Asian converters.
Global Die Cut Lids Market Vendor Landscape
Listed leaders compete with private specialists across material platform breadth, with publicly traded packaging conglomerates commanding multi-regional converting footprints while family-owned specialists dominate narrow barrier-technology niches. The vendor base splits between integrated material-science conglomerates, regional dairy-focused converters, and pharmaceutical-certification specialists. Three archetypes define competitive positioning: scale-driven global suppliers, certification-heavy healthcare specialists, and speed-optimized dairy processors. Consolidation pressure favors backward integration into resin compounding and strategic partnerships with recycling infrastructure operators.
Within the scale-driven tier, Amcor plc and Sealed Air Corporation exemplify global converting breadth across food and healthcare segments. Constantia Flexibles Group GmbH occupies a position among European specialists with aluminum barrier expertise. These three anchors represent divergent strategic postures: multi-material portfolio breadth, regional certification depth, and pharmaceutical-grade barrier precision.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Amcor plc |
| Constantia Flexibles Group GmbH |
| Winpak Ltd. |
| ProAmpac |
| Sonoco Products Company |
| Sealed Air Corporation |
| Quantum Packaging |
| Watershed Packaging |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German dairy cooperatives and Rhine-Alpine converters lock in aluminum foil supply access while capping price volatility exposure for both parties. These structures transfer raw material risk to processors who accept volume minimums, embedding cost predictability into multi-year pharmaceutical lid contracts.
Pricing Analysis
Current-generation mono-material polypropylene lids trade at a discount to prior-generation aluminum-polyethylene laminates, while next-generation active-packaging lids with oxygen-scavenging membranes command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade barrier certification from chilled dairy commodity specifications. Cost compression in standard-tier plastic lids is intensifying because Chinese converters are expanding polypropylene film capacity. Food processors represent the most price-sensitive segment, accepting seal-failure penalties in exchange for per-unit cost reductions, while pharmaceutical contract packers prioritize migration-testing documentation over unit economics.
Supply Chain Analysis
Inventory buffers for specialized coextruded films stretch lead times when European and Japanese resin compounders face order surges from retort food packers. Supply concentrates in Germany, China, and the United States for converting capacity, with raw material dependencies on aluminum smelters in Iceland and Norway, polypropylene resin from Saudi Arabia and South Korea, and heat-seal lacquers from Swiss chemical specialists. Single-source vulnerability concentrates in high-barrier film supply, where limited qualified compounders create bottleneck risk for aseptic lid converters. Distribution runs through direct sales engineering teams co-located within 150 kilometers of major dairy processing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die cut lid procurement is approaching a platform-economics inflection as EU Green Deal circularity mandates force interoperability between mono-material lids and cup body recycling streams, collapsing traditional material silos.
For Market Incumbents: Compound barrier-certification depth in pharmaceutical aluminum lids to defend against emerging mono-material specialists attacking dairy share. Prioritize backward integration into polypropylene resin compounding to capture margin from standard-tier plastic lid commoditization. Anchor capacity expansion in the Stuttgart-Basel corridor where Swissmedic-regulated cold-chain biologics demand sustains premium positioning.
For New Entrants and Emerging Players: Technical service gaps in Indian dairy modernization present white-space entry points where European incumbents lack localized forming-line calibration support. Target Maharashtra and Karnataka processing corridors with imported forming-compatible specifications adapted to FSSAI adhesive compliance. Pursue joint-development partnerships with East Asian equipment OEMs to accelerate line-speed validation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-certification specialists with multi-year EFSA dual-approval maintenance contracts. Long-term viability favors converters with demonstrated migration-testing protocol execution rather than commodity scale. Watch for EU PPWR implementation velocity as the inflection signal separating recyclable-platform winners from stranded multi-layer asset holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Migration | Polypropylene-only lid structures unlock EU Green Deal compliance advantages in German dairy procurement. |
| Active Packaging Integration | Oxygen-scavenging membranes extend shelf life for Swiss functional food brands requiring dual-compartment separation. |
| Pharmaceutical Certification Expansion | Dual FDA-EFSA approval portfolios capture high-margin biologics demand from Basel contract packers. |
| India Cold-Chain Partnership | Localized technical service teams address forming-line calibration gaps in Mumbai and Delhi processing corridors. |
| Chemical Recycling Partnership | Multi-layer barrier lid producers defend positioning through end-of-life circularity investments under emerging EPR schemes. |
Methodological Framework
A standing panel of dairy procurement directors, pharmaceutical contract packaging executives, adhesive R&D chemists, and EFSA regulatory consultants provided ongoing calibration against secondary validation sources. Primary interviews with converters in Germany, China, and the United States combined with customs trade data, EU PPWR regulatory filings, SEC packaging sector disclosures, and aluminum ingot price benchmarks. Bottom-up volume estimates from individual processing facility capacities triangulated against top-down market sizing from end-use consumption patterns.
Consistency checks validated volume and value outputs against external benchmarks including dairy processing line installation rates, pharmaceutical packaging outsourcing indices, and resin compounding capacity announcements. Segmentation modeling captured material platform, application tier, end-use sophistication, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from trend extrapolation of single-serve format adoption, cold-chain penetration curves, and circularity policy implementation schedules.
Underlying assumptions cover sustained EU PPWR enforcement, stable aluminum-polypropylene price spreads, and continued dairy processor consolidation, with deviation risk concentrated in migration-testing certification timeline delays and recycling infrastructure deployment gaps. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Bag Closures and Seals Market