
 Metal Caps and Closures Market | 2026-2036
Metal Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Caps and Closures Market Outlook
Food-grade 316 stainless steel specification tiers is collapsing the gap between pharmaceutical and premium beverage packaging as buyers consolidate supplier bases. Crown Holdings Inc. dominates North American aluminum roll-on closure supply through captive metal sourcing. Silgan Holdings Inc. leverages its deep customer relationships with multinational food brands to sustain volume commitments across tinplate lid formats. Tecnocap Group specializes in custom deep-drawn aluminum shells for olive oil and spirits producers in Southern Europe.
Metal caps and closures are precision-formed aluminum, steel, tinplate, or stainless steel devices engineered to seal containers against contamination, oxidation, and leakage, typically manufactured through deep drawing, thread rolling, and liner insertion processes with torque specifications measured in inch-pounds. Their primary purpose is to preserve product integrity across liquid and semi-solid goods during distribution, retail display, and consumer use. Aluminum closures lead beverage applications due to lightweighting trends and recyclability mandates, while steel and tinplate lids retain margin concentration in heat-processed food segments where vacuum seal reliability outweighs material cost. Pharmaceutical screw cap demand is expanding fastest as serialization requirements and child-resistant standards tighten across regulated supply chains.
FDA food-contact substance notifications and EPA metal finishing effluent guidelines shape material selection and plant location decisions for suppliers serving the United States market. REACH restrictions on chromium VI in passivation layers and EU Packaging and Packaging Waste Directive recycling targets are accelerating tinplate-to-aluminum substitution in European closure production. BIS certification for food-contact metals and CDSCO pharmaceutical packaging standards govern market access for products entering India. Stakeholders must monitor alloy price volatility and evolving extended producer responsibility schemes to time capacity investments and material hedging strategies.
Market Dynamics
Aluminum roll-on closure adoption in emerging-market beverage bottling lines is compressing legacy tinplate demand while forcing steel closure suppliers to defend position through pharmaceutical-grade certification tiers. This material substitution wave now governs capacity planning decisions across precision-forming equipment investments.
Growth Catalysts
- REACH chromium VI restrictions:European passivation layer bans are accelerating tinplate-to-aluminum conversion in wine and spirits closure production, pulling demand toward deep-drawn aluminum shell specialists.
- India pharmaceutical bottling expansion:CDSCO serialization mandates and BIS food-contact metal certification requirements are concentrating premium steel screw cap procurement from domestic sterilization-grade suppliers.
- Tamper-evident aluminum ROPP technology:Beverage packaging line upgrades across Latin American and Southeast Asian bottling facilities are standardizing 28mm aluminum roll-on pilfer-proof formats for carbonated soft drinks.
Market Restraints
- Primary aluminum ingot price volatility:London Metal Exchange aluminum contract swings above fifteen percent annually are compressing margin predictability for deep-drawn closure manufacturers without captive smelter arrangements.
- Steel closure supply concentration:European tinplate lid production clusters in northern Italy and western Germany create geographic vulnerability to energy cost shocks and logistics disruption.
- Polymer closure substitution:Hot-fill compatible polypropylene screw caps with oxygen scavenger liners are displacing steel closures in acidic sauce and pasteurized juice segments where vacuum seal reliability requirements have relaxed.
Strategic Opportunities
- India premium beverage packaging:Domestic craft spirits and cold-pressed juice brands are adopting custom embossed aluminum closures previously reserved for import substitution, opening white space for localized deep-drawing capacity.
- EU Packaging and Packaging Waste Directive recycling targets:Mandatory aluminum recovery rates above seventy-five percent by 2030 are creating regulatory tailwind for infinitely recyclable closure formats against multi-material competitors.
- Smart closure integration:Convergence of near-field communication chips with aluminum shell forming is enabling authentication and supply chain traceability for high-value olive oil and spirits producers in Mediterranean markets.
Industry Challenges
- Deep-drawing die engineering talent scarcity:Precision metal forming expertise for thin-wall aluminum shell production concentrates among aging tool-and-die specialists in northern Italy and southwestern Germany.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact substance notification, REACH SVHC screening, and BIS laboratory testing for single closure SKUs extends commercialization cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Caps and Closures Market |
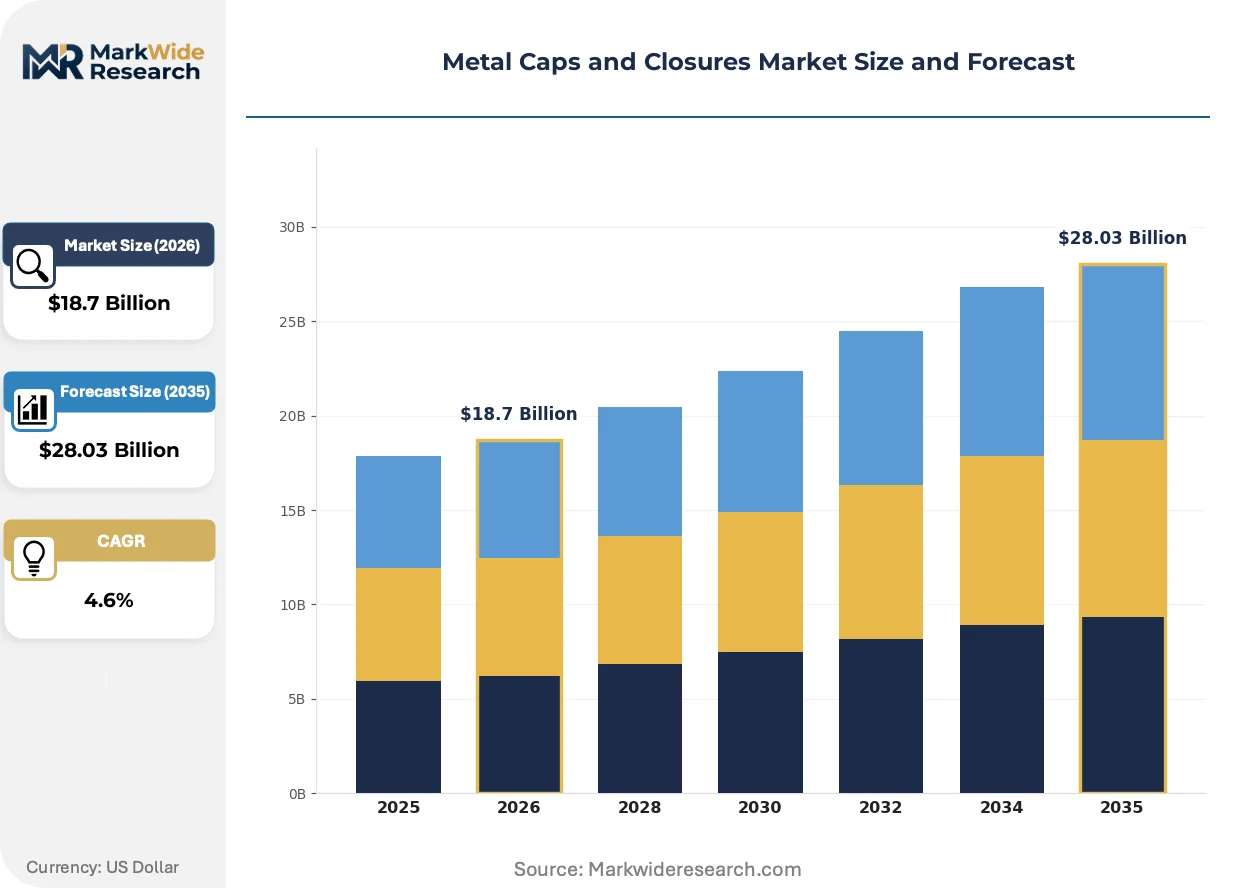
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Closures, Lids, Seals Material: Aluminum, Steel, Tinplate, Stainless Steel Application: Beverages, Pharmaceuticals, Personal Care, Food Closure Design: Flip Top, Screw Cap, Pull Tab, Snap On |
| Companies Covered | Guala Closures Group, Sonoco Products Company, Crown Holdings Inc., O.Berk Company, BERICAP, Amcor plc, Tecnocap Group, AptarGroup Inc., Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Caps and Closures Market Strategic Shifts
Active material science development in liner adhesion chemistry and shell alloy formulation is compressing performance gaps between commodity and premium closure tiers. These technical advances are redrawing competitive boundaries across beverage, food, and pharmaceutical sealing applications.
Micro-embossed aluminum shell technology with sub-millimeter relief patterns is miniaturizing brand authentication features directly into closure crowns without secondary labeling operations. Premium spirits producers in Scotland and Cognac are adopting these formats at accelerated pace to combat counterfeiting in Asian export markets. The technology is compressing demand for separate holographic seals and shrink-band secondary packaging, altering total cost calculations for high-value bottling operations.
EPA metal finishing effluent guidelines under Clean Water Act enforcement are tightening chromium and nickel discharge limits at US-based closure manufacturing plants. Surface treatment operations are relocating to jurisdictions with less stringent industrial wastewater frameworks or converting to trivalent chromium passivation systems at substantial capital cost. Heat-processed food tinplate lid suppliers serving midwestern US canneries face the most acute compliance pressure given legacy hexavalent chromium immersion lines.
Consolidated procurement by multinational beverage bottlers is compressing supplier bases toward dual-source aluminum closure arrangements with torque specification guarantees. Regional bottling cooperatives in Brazil and Mexico are displacing fragmented local supplier relationships in favor of direct contracts with integrated aluminum rolling and forming operations. This concentration is most visible in Latin American carbonated soft drink bottling, where parent company sustainability scorecards now mandate recycled content thresholds and carbon footprint disclosures from closure vendors.
Metal Caps and Closures Market Segmentation
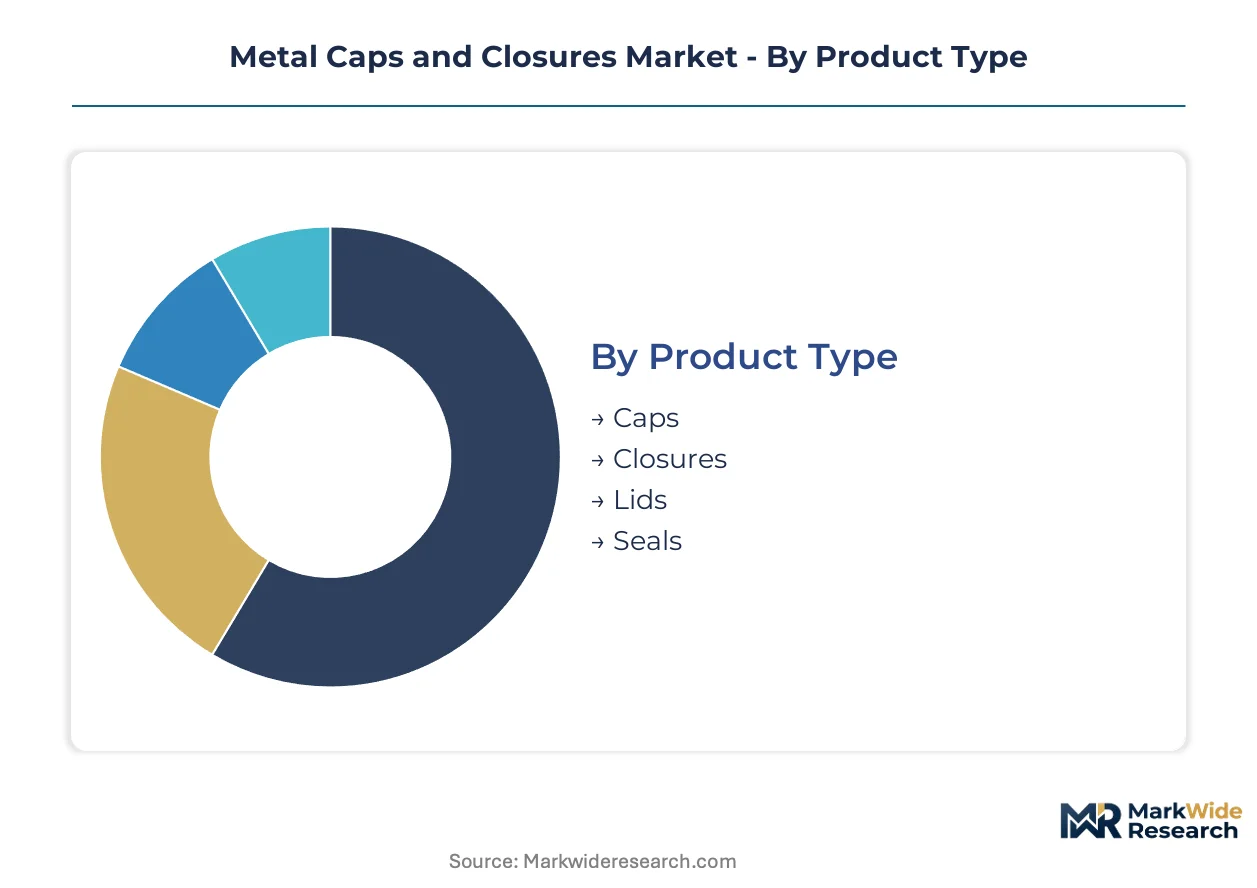
Material substitution dynamics and regulatory tiering create divergent margin profiles across closure formats. Buyers consolidate supplier bases around certification tiers that collapse traditional boundaries between pharmaceutical, beverage, and food-grade specifications.
Product Type:
Polymer substitution pressure concentrates most intensely on commodity lid formats where oxygen scavenger liners have relaxed vacuum seal requirements, while precision-formed caps defend position through tamper-evident torque specifications.
- Caps:Precision-threaded aluminum and steel devices engineered for torque-controlled sealing in carbonated beverage and pharmaceutical applications. Demand clusters in India and Brazil where bottling line upgrades standardize 28mm ROPP formats for carbonated soft drinks and serialized drug packaging.
- Closures:Multi-component sealing systems integrating shell, liner, and tamper-evident band. Pharmaceutical screw cap procurement is expanding fastest as CDSCO serialization mandates and child-resistant standards tighten across regulated supply chains in India.
- Lids:Flat or domed tinplate and aluminum covers for heat-processed food containers. Steel lid demand faces displacement from hot-fill compatible polypropylene alternatives in acidic sauce segments.
- Seals:Secondary barrier components including induction heat-seal membranes and pressure-sensitive liners. Migration toward integrated liner-shell designs compresses standalone seal volumes.
Closures anchor the volume base while caps gain share at the steepest rate.
Material:
Cost tier stratification separates captive-smelter integrated suppliers from toll-forming operations exposed to London Metal Exchange volatility.
- Aluminum:Deep-drawn 3000 and 5000 series alloys dominating beverage applications through lightweighting and infinite recyclability. REACH chromium VI restrictions in Europe accelerate tinplate-to-aluminum conversion in wine and spirits production.
- Steel:Cold-rolled tinplate and electrolytic chrome-coated steel for heat-processed food lids. European production clusters in northern Italy and western Germany face geographic vulnerability to energy cost shocks.
- Tinplate:Traditional low-carbon steel with tin coating for vacuum-seal canning applications. Regulatory pressure from EPA metal finishing effluent guidelines forces conversion to trivalent chromium passivation at substantial capital cost.
- Stainless Steel:316 and 304 specification tiers for pharmaceutical and premium beverage packaging. Food-grade 316 specification tiers are collapsing gaps between pharmaceutical and premium beverage segments as buyers consolidate supplier bases.
Aluminum commands the widest application span while stainless steel expands most quickly into cross-tier certification consolidation.
Application:
Customer type divergence separates multinational bottler procurement scorecards from regional cooperative purchasing patterns.
- Beverages:Carbonated soft drinks, bottled water, and alcoholic beverages driving aluminum ROPP standardization. Consolidated procurement by multinational bottlers compresses supplier bases toward dual-source arrangements with recycled content thresholds.
- Pharmaceuticals:Prescription and over-the-counter drug packaging requiring serialization-compatible screw caps. CDSCO mandates in India concentrate premium steel closure procurement from domestic sterilization-grade suppliers.
- Personal Care:Cosmetic and hygiene product sealing with emphasis on premium aesthetic finishes. Custom embossed aluminum closures previously reserved for import substitution now penetrate domestic craft brands in India.
- Food:Heat-processed, ambient, and chilled food preservation demanding vacuum seal reliability. Polypropylene substitution displaces steel in pasteurized juice segments where oxygen barrier requirements have relaxed.
Beverages anchor the volume base while pharmaceuticals gains share at the steepest rate.
Closure Design:
Supply concentration in deep-drawing die engineering talent shapes which formats achieve cost-competitive precision at scale.
- Flip Top:Hinged polypropylene or metal closures for single-handed dispensing in personal care and condiment applications. Convenience-driven format adoption faces margin pressure from multi-material recycling complexity.
- Screw Cap:Threaded aluminum and steel devices with torque specification guarantees. Pharmaceutical serialization requirements and beverage standardization drive fastest format expansion across regulated supply chains.
- Pull Tab:Integral aluminum opening mechanisms for beverage cans and specialty food containers. Format maturity limits growth to replacement demand and emerging market penetration.
- Snap On:Press-fit plastic or metal closures for dry goods and non-carbonated beverages. Lowest per-unit cost positions format for economy-tier commodity applications.
Screw caps anchor the volume base while flip top configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep-drawing die engineering talent concentrates in northern Italy and southwestern Germany, while aluminum smelter proximity shapes competitive positioning for beverage closure suppliers. Energy cost differentials between European and Asian production clusters are redrawing investment flows for precision-forming capacity.
United States
Midwestern canneries drive tinplate lid demand for heat-processed vegetables and sauces. EPA metal finishing effluent guidelines under Clean Water Act enforcement tighten chromium discharge limits at closure manufacturing plants in Ohio and Illinois. Chicago-area surface treatment operations face acute compliance pressure from legacy hexavalent chromium immersion lines.
Germany
Western German automotive-adjacent metal forming expertise transfers into pharmaceutical-grade steel closure production. REACH restrictions on chromium VI in passivation layers accelerate conversion to trivalent chromium systems at substantial capital cost. Düsseldorf-Cologne corridor suppliers defend position through sterilization-grade certification tiers for CDSCO-compliant export volumes.
India
Domestic craft spirits and cold-pressed juice brands adopt custom embossed aluminum closures previously reserved for import substitution. BIS certification requirements for food-contact metals and CDSCO pharmaceutical packaging standards govern market access. Maharashtra pharmaceutical bottling corridors concentrate premium steel screw cap procurement from sterilization-grade suppliers near Mumbai-Pune industrial belt.
Italy
Southern European olive oil and spirits producers sustain demand for deep-drawn aluminum shells with micro-embossed authentication features. ECHA REACH SVHC screening requirements extend commercialization cycles for specialty closure formats. Northern Italian tool-and-die clusters around Brescia and Bergamo concentrate aging precision metal forming expertise for thin-wall aluminum shell production.
Brazil
Carbonated soft drink bottling cooperatives displace fragmented local supplier relationships in favor of direct contracts with integrated aluminum operations. Parent company sustainability scorecards mandate recycled content thresholds and carbon footprint disclosures from closure vendors. São Paulo state bottling facilities standardize 28mm aluminum roll-on pilfer-proof formats through line upgrade programs.
Metal Caps and Closures Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with deep-drawing precision specialists commanding premium tiers while scale-integrated aluminum rollers defend commodity beverage positions. The vendor base separates into captive-smelter integrated suppliers, toll-forming operations exposed to London Metal Exchange volatility, and sterilization-grade certification holders serving pharmaceutical channels. Two dominant competitive moves define current positioning: backward integration into aluminum rolling capacity to hedge ingot price swings, and geographic expansion into Indian pharmaceutical bottling corridors to capture CDSCO-mandated serialization demand.
Among North American metal packaging specialists, Crown Holdings Inc. and Silgan Holdings Inc. occupy positions reflecting divergent strategic anchors. Crown exemplifies the captive-metal archetype through integrated aluminum supply chains serving beverage standardization mandates. Silgan represents relationship-driven volume commitment models across tinplate lid formats for multinational food brands. Tecnocap Group sits within the European precision-specialist tier, anchoring custom deep-drawn capacity for premium spirits authentication requirements in Mediterranean markets.
| Leading Market Players |
|---|
| Guala Closures Group |
| Sonoco Products Company |
| Crown Holdings Inc. |
| O.Berk Company |
| BERICAP |
| Amcor plc |
| Tecnocap Group |
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day die engineering lead times for precision aluminum shells concentrate pricing power among northern Italian tool-and-die clusters, while London Metal Exchange aluminum contract volatility feeds directly into toll-forming margin compression across commodity beverage closure tiers.
Pricing Analysis
REACH chromium VI restrictions dictate the pricing tier structure across European wine and spirits closure production. Three-tier pricing structure across pharmaceutical-grade 316 stainless steel, food-grade tinplate, and commodity aluminum separates certification-intensive segments from standard beverage formats. Cost compression in aluminum roll-on pilfer-proof tiers is intensifying because primary ingot contract swings exceed fifteen percent annually. Multinational beverage bottlers exhibit lowest price sensitivity through dual-source volume commitments, while regional cooperatives in Latin America face acute margin pressure.
Supply Chain Analysis
Forty-five-day aluminum coil inventory buffers at integrated rolling operations insulate captive-smelter suppliers from spot market volatility, though toll-formers remain exposed. Deep-drawing capacity concentrates in Italy, Germany, and Brazil, with raw material flows drawing from Norwegian smelter output and Guinean bauxite corridors. Single-source vulnerability concentrates in hexavalent chromium surface treatment lines facing EPA effluent enforcement. Distribution runs through direct contracts with multinational bottlers and pharmaceutical sterilization-grade suppliers near Mumbai-Pune and Düsseldorf-Cologne corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum closure adoption in emerging-market beverage bottling lines signals early-cycle expansion, with tamper-evident ROPP technology penetration accelerating across Latin American and Southeast Asian facilities.
For Market Incumbents: Secure captive aluminum rolling capacity to hedge London Metal Exchange volatility exposure in commodity beverage tiers. Defend pharmaceutical-grade positioning through CDSCO-compliant sterilization certification investments near Indian bottling corridors. Polypropylene substitution in acidic sauce segments threatens legacy tinplate lid margins.
For New Entrants and Emerging Players: Custom embossed aluminum closure design services for Indian craft spirits brands represent the most penetrable white space, as domestic producers abandon import substitution. Target Maharashtra pharmaceutical bottling corridors with serialization-compatible screw cap offerings. Pursue joint development agreements with regional cold-pressed juice brands seeking premium differentiation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade stainless steel closure production due to multi-jurisdiction certification requirements. Five-to-ten-year viability favors sterilization-grade certification holders with established FDA and CDSCO compliance track records. Monitor REACH SVHC screening timeline extensions as inflection indicator for specialty format commercialization cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive smelter arrangements insulate Crown Holdings from London Metal Exchange volatility in beverage supply. |
| Pharmaceutical Certification Investment | CDSCO serialization compliance opens Maharashtra bottling corridor procurement to sterilization-grade suppliers. |
| Trivalent Chromium Conversion | EPA effluent guideline compliance preserves Midwestern cannery tinplate lid supply from enforcement disruption. |
| Smart Closure Integration | NFC chip convergence with aluminum shells enables Cognac and olive oil authentication in Mediterranean export markets. |
| Regional Deep-Drawing Capacity Expansion | São Paulo state line upgrades standardize 28mm ROPP formats for Brazilian carbonated soft drink cooperatives. |
Study Parameters
A spread of perspectives from plant managers at precision-forming operations, procurement leads at multinational beverage bottlers, pharmaceutical packaging engineers, and toll-forming commercial directors converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA food-contact substance notifications, REACH SVHC screening databases, BIS laboratory certification records, and aluminum trade flow customs data. Bottom-up capacity assessments and top-down demand aggregation triangulated volume estimates.
Product type, material specification, application segment, closure design format, and geographic regulatory cluster dimensions structured the analytical framework across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators. Industry-specific inputs included London Metal Exchange aluminum price band assumptions and CDSCO serialization mandate implementation pacing.
Forecasts assume regulatory continuity in REACH, FDA, and BIS regimes; material policy shifts would require re-modeling. Aluminum ingot price volatility, energy cost shocks in European production clusters, and polymer substitution acceleration in heat-processed food segments constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
End Cap Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Cap Liner Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Screw Closure Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Lug Caps Market
Caps and Closures
Fez Caps Market