
 Resealable Closures and Spouts Packaging Market | 2026-2036
Resealable Closures and Spouts Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Resealable Closures and Spouts Packaging Market Analytics
Modular pouch configurations with detachable spouts is decoupling single-use rigid containers from repeat-purchase formats across food and personal care aisles. Amcor leverages its global film manufacturing footprint to supply pre-applied zipper and spout laminates at scale. Berry Global anchors North American demand through blow-molded flip-top and threaded closure lines integrated with flexible pouch converters. Huhtamaki competes in emerging markets with localized spout insertion equipment and barrier film supply.
Resealable closures and spouts packaging encompasses mechanical dispensing and sealing devices—typically polypropylene or polyethylene spout bodies with threaded, snap-fit, or slider-actuated closure mechanisms—laminated or welded to flexible film substrates to enable repeated opening, controlled pouring, and extended product protection after initial use. Flip top and spout categories lead value contribution due to premium placement in baby food, condiments, and beverages where controlled dispensing commands price premiums over standard screw cap pouches. Tamper-evident design features represent the fastest-growing specification segment as pharmaceutical and food regulators mandate visible integrity assurance across retail channels.
FDA food contact substance notifications and EU REACH compliance on plastic additives shape material selection and migration testing protocols for spout and closure suppliers accessing regulated markets. EFSA evaluations of recycled content thresholds in food-contact layers are forcing reformulation of polyolefin streams used in closure bodies and threaded fitments. Stakeholders must monitor evolving extended producer responsibility frameworks to anticipate redesign obligations before compliance deadlines harden.
Market Dynamics
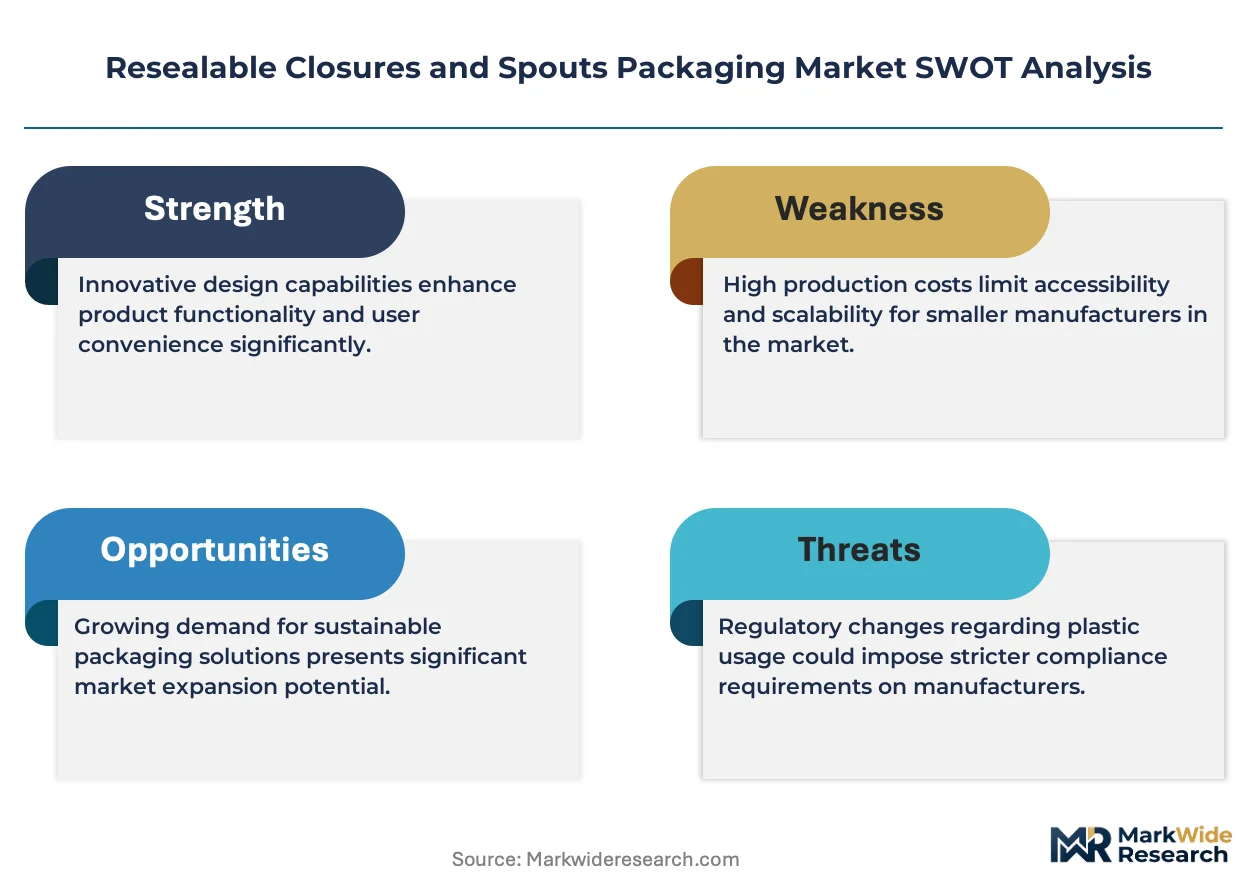
EU's Packaging and Packaging Waste Regulation is compressing design cycles across the value chain as recyclability mandates force rapid conversion from multi-material laminates to mono-polyolefin structures compatible with existing mechanical recycling infrastructure.
Growth Catalysts
- Flexible format conversion:Dairy and sauce producers in Germany are accelerating rigid-to-pouch transitions as spouted formats reduce shipping cube and shelf-space requirements.
- REACH compliance protocols:ECHA migration testing requirements for plastic additives are standardizing material specifications across member states, reducing supplier qualification friction.
- Tamper-evident mandates:EFSA and FDA parallel requirements for visible integrity assurance are pulling pharmaceutical and food brands toward certified closure systems.
Market Restraints
- Polypropylene price volatility:Propylene feedstock swings tied to naphtha cracking economics compress margin predictability for spout body manufacturers.
- Film lamination concentration:High-barrier substrate supply clusters in Germany and Austria, creating geographic vulnerability for converters elsewhere in Europe.
- Mechanical recycling incompatibility:Legacy multi-layer pouches with metallized films remain non-recyclable through standard kerbside streams, limiting circular claims.
Strategic Opportunities
- Detachable spout systems:Modular pouch configurations enable body-spout separation, allowing consumers to recycle film portions while retaining closures for reuse.
- Extended producer responsibility frameworks:France's Citeo modulation fees reward lightweight flexible formats over rigid alternatives, creating compliance-driven demand pull.
- Barrier film convergence:EVOH-PE coextrusion advances are displacing aluminum foil layers while maintaining oxygen transmission specifications for retort applications.
Industry Challenges
- Welding precision engineering:Spout-to-film ultrasonic and hot-bar sealing requires micron-level tolerance control that exceeds legacy converter capabilities.
- Migration testing timelines:EFSA food contact evaluations for novel barrier polymers extend 18-24 months, delaying product launches beyond brand planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resealable Closures and Spouts Packaging Market |
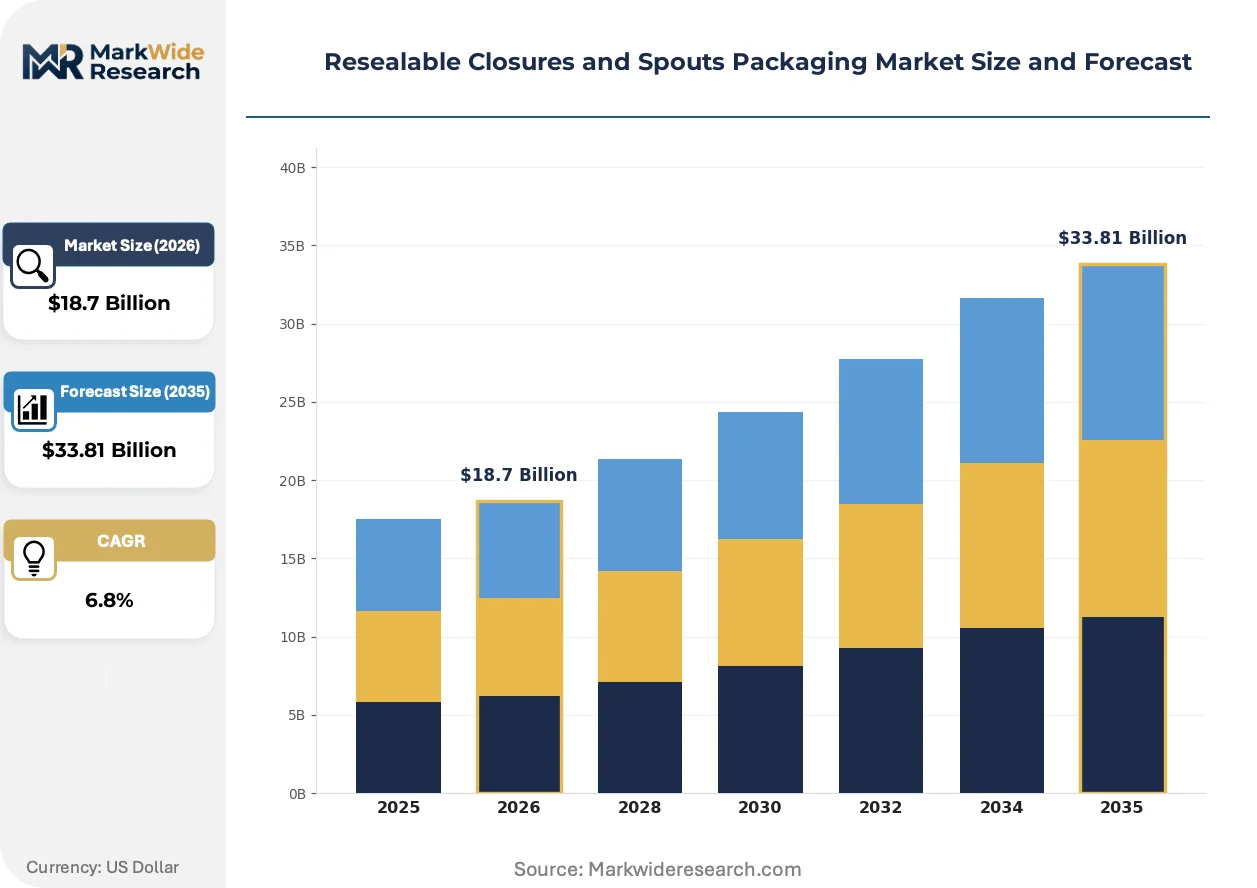
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Screw Cap, Spout, Pouch Material: Plastic, Metal, Glass, Composite End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Design Feature: Child-Resistant, Ergonomic, Tamper-Evident, Easy Open |
| Companies Covered | Amcor, Berry Global, AptarGroup, Huhtamaki, Constantia Flexibles, Silgan Dispensing, Guala Closures, Winpak, Essel Propack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resealable Closures and Spouts Packaging Market Evolving Landscape
Spout insertion and sealing equipment is automating production workflows that previously required manual handling, while regulatory pressure on recyclability is forcing material science breakthroughs in mono-polymer barrier systems.
Ultrasonic welding technology for spout-to-pouch attachment is automating what was historically a semi-manual bottleneck in converter lines. Mid-tier European dairy brands are adopting these systems at 15-20% annual replacement rates for legacy hot-bar equipment. The technology is automating throughput scaling without proportional labor expansion, compressing unit economics for regional converters competing with integrated multinationals.
EU's Packaging and Packaging Waste Regulation is mandating design-for-recycling criteria that eliminate incompatible material combinations. Industrial consequence includes forced phase-out of PET-PE-EVOH laminates in favor of all-polyolefin structures by 2030. Baby food and condiment segments in Germany and the Netherlands are responding fastest, with major brands accelerating mono-material pouch trials ahead of compliance deadlines.
Brand procurement teams are consolidating supplier relationships around converters offering integrated spout supply and insertion services. This disintermediation of separate closure vendors is compressing the traditional three-party sourcing model. The shift is most visible in French and Italian sauce markets, where single-source accountability for seal integrity is displacing fragmented quality responsibility.
Resealable Closures and Spouts Packaging Market Segmentation
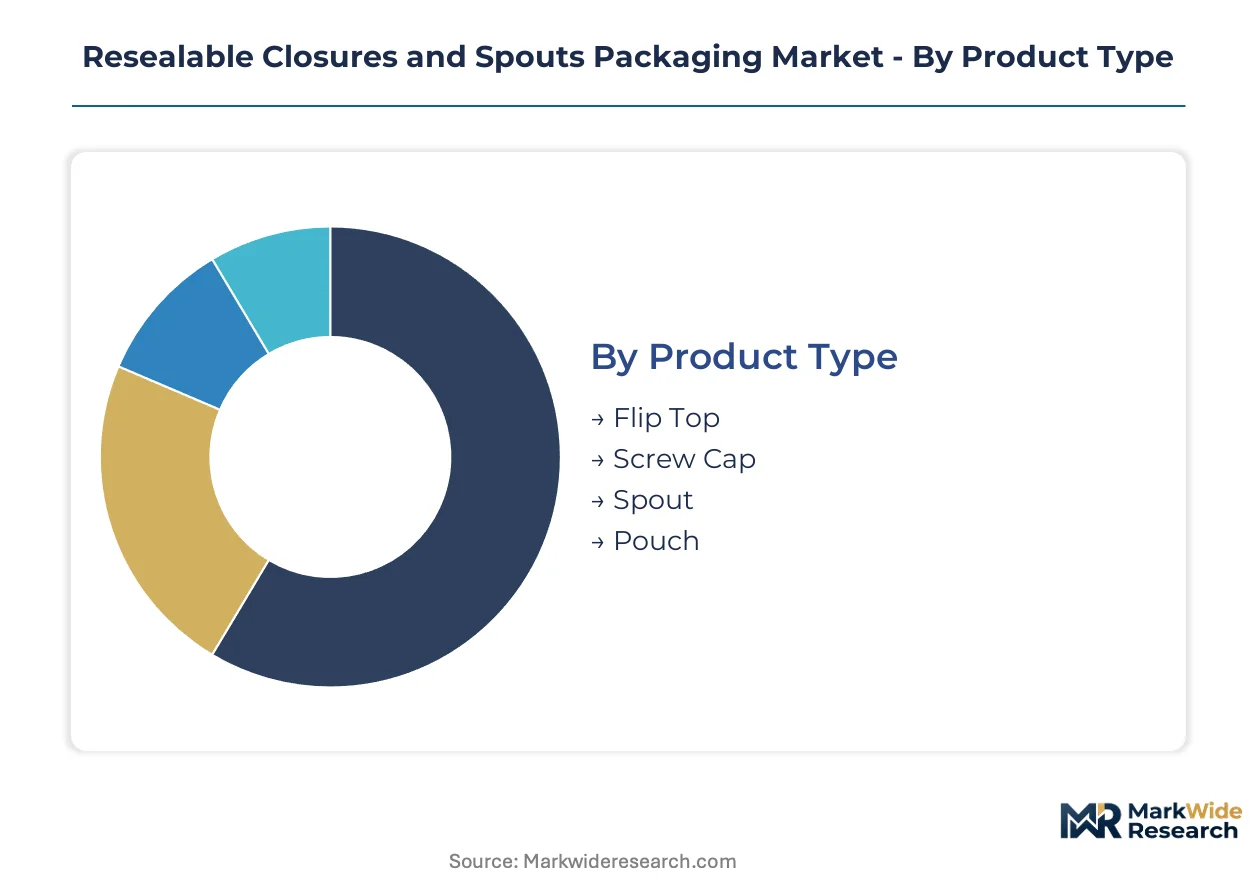
Segmentation in resealable closures and spouts packaging reveals how functional requirements, material constraints, and regulatory mandates fragment demand across incompatible technical specifications. Each dimension—product architecture, substrate chemistry, end-use performance standards, and safety engineering—creates distinct procurement criteria that reshape supplier qualification and converter investment priorities.
Product Type:
Standalone dispensing mechanisms dominate premium placement, while embedded closure systems penetrate high-volume commodity formats where unit economics favor integrated production.
- Spout:Threaded or snap-fit polypropylene bodies welded to flexible film substrates enable controlled pouring and repeated resealing. German dairy and sauce producers are converting rigid bottle lines to spouted pouches as EFSA-compliant mono-material structures displace multi-layer alternatives. REACH migration testing for polyolefin streams standardizes material specifications across EU member states.
- Flip Top:Hinged polypropylene or polyethylene lids with living-hinge construction provide single-handed dispensing access. Baby food and condiment brands in the Netherlands command price premiums for tamper-evident flip-top integration that satisfies visible integrity assurance mandates. FDA food contact substance notifications shape additive selection for suppliers accessing North American retail channels.
- Screw Cap:Threaded closure systems with torque-release specifications remain standard for beverage and pharmaceutical applications requiring hermetic sealing performance.
- Pouch:Flexible film formats with integrated zipper or slider mechanisms serve dry goods and personal care segments where extended product protection after initial use drives format selection.
Spout configurations lead volumes today; flip top integration is gaining share fastest through premium placement in controlled-dispensing categories.
Material:
Substrate chemistry determines recyclability pathways and migration compliance burden, with mono-polymer specifications displacing multi-material laminates under tightening EPR frameworks.
- Plastic:Polypropylene and polyethylene dominate spout body and closure manufacturing due to weldability, chemical resistance, and established mechanical recycling infrastructure. France's Citeo modulation fees reward lightweight flexible formats over rigid alternatives, pulling demand toward polyolefin-intensive structures. Propylene feedstock volatility tied to naphtha cracking economics compresses margin predictability for converters.
- Metal:Aluminum threaded fitments and roll-on closures serve pharmaceutical and premium beverage segments where oxygen barrier performance and torque consistency outweigh cost premiums.
- Glass:Borosilicate and soda-lime closure components remain confined to high-temperature and chemical-resistant applications in laboratory and specialty food packaging.
- Composite:Multi-substrate combinations incorporating fiber reinforcement or barrier coatings face phase-out pressure under EU Packaging and Packaging Waste Regulation design-for-recycling criteria.
Plastic substrates command installed capacity today; metal fitments are climbing fastest through pharmaceutical tamper-evident specifications.
End User:
Regulatory intensity and performance validation requirements create tiered procurement standards that separate food-contact compliance from industrial-grade specifications.
- Food & Beverage:Retort pouch, condiment, and ready-to-drink applications drive spouted format adoption as brands reduce shipping cube and shelf-space requirements. EVOH-PE coextrusion advances are displacing aluminum foil layers while maintaining oxygen transmission specifications. EFSA evaluations of recycled content thresholds in food-contact layers force polyolefin stream reformulation.
- Pharmaceuticals:Child-resistant and tamper-evident closure mandates from FDA and EMA pull demand toward certified mechanical dispensing systems with documented integrity assurance.
- Personal Care:Ergonomic dispensing and aesthetic differentiation command specification priority over barrier performance in shampoo, lotion, and cosmetic pouch formats.
- Household:Industrial chemical and cleaning product packaging prioritizes chemical compatibility and thread seal reliability in high-pH or solvent-exposure environments.
Food and beverage applications dominate shipment volumes today; pharmaceutical specifications are expanding most quickly through parallel FDA-EMA integrity mandates.
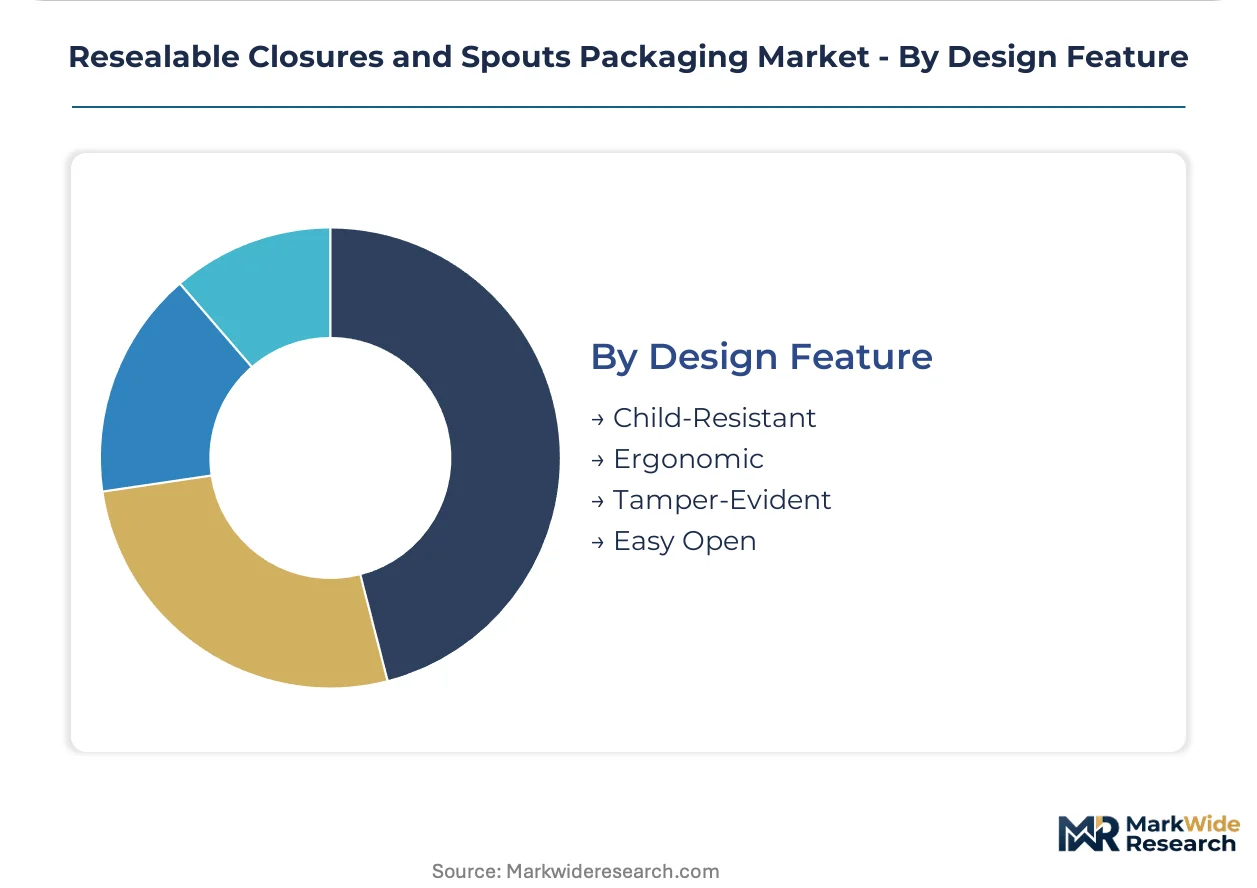
Design Feature:
Safety engineering and accessibility requirements segment demand between regulatory-mandated specifications and discretionary ergonomic investments.
- Tamper-Evident:Visible integrity assurance mechanisms—breakaway rings, shrink bands, and membrane seals—satisfy EFSA and FDA parallel requirements for pharmaceutical and food retail channels. Closure suppliers consolidate procurement relationships around integrated spout supply and insertion services to guarantee seal integrity accountability. Migration testing timelines for novel barrier polymers extend evaluation periods beyond brand planning cycles.
- Child-Resistant:Push-and-turn or squeeze-and-lift mechanisms comply with poison prevention packaging standards for pharmaceutical and household chemical applications.
- Ergonomic:Contoured grip surfaces and reduced-force opening specifications serve aging demographics and accessibility-compliant personal care positioning.
- Easy Open:Tear-notch and peelable membrane configurations address convenience positioning in single-serve and on-the-go consumption formats.
Tamper-evident specifications lead value contribution today; child-resistant engineering is gaining share fastest through tightening pharmaceutical safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging innovation traces its industrial lineage to post-war German chemical engineering clusters, where polyolefin film extrusion and welding automation first converged at scale during the 1960s.
Germany
Dairy and sauce producers in Bavaria and North Rhine-Westphalia are accelerating rigid-to-pouch conversions as spouted formats reduce logistics costs. EFSA evaluations of recycled content thresholds in food-contact layers force polyolefin stream reformulation. The Rhine-Main packaging cluster around Frankfurt anchors converter investment in ultrasonic welding equipment.
France
Citeo modulation fees reward lightweight flexible formats over rigid alternatives, pulling condiment brands toward spouted pouches. ANSM pharmaceutical packaging standards mandate tamper-evident closure systems for over-the-counter products. The Lyon-Auvergne-Rhône-Alpes corridor concentrates barrier film coextrusion capacity serving southern European markets.
Netherlands
Baby food brands in Randstad metros command price premiums for controlled-dispensing flip-top integration. REACH compliance protocols through ECHA standardize additive specifications across Benelux supply chains. Eindhoven Region hosts specialized spout insertion equipment manufacturers supplying converters throughout northwestern Europe.
United States
FDA food contact substance notifications shape polypropylene additive selection for suppliers accessing North American retail channels. EPA extended producer responsibility frameworks are emerging at state level, preempting federal packaging waste legislation. The Midwest industrial corridor around Illinois and Michigan concentrates blow-molded closure manufacturing integrated with flexible film converters.
China
SAMR food-contact material standards are tightening migration testing requirements for polyolefin closures used in infant nutrition packaging. Dual carbon goals under MEE jurisdiction are accelerating domestic converter investment in mono-material barrier structures. The Yangtze River Delta around Shanghai anchors integrated film-spout manufacturing serving Asia-Pacific export demand.
Resealable Closures and Spouts Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with integrated film-closure suppliers capturing value that fragmented component vendors cannot access. The vendor base organizes into three strategic archetypes: multinational converters with captive spout supply, specialized closure manufacturers selling into third-party film operations, and regional equipment-film integrated specialists. Dominant competitive moves include backward integration into polymer compounding and geographic expansion through licensing of insertion equipment technology.
Within the integrated multinational tier, Amcor and Berry Global exemplify scale-driven positioning across film manufacturing and pre-applied closure laminates. AptarGroup occupies a specialist position in precision dispensing and tamper-evident mechanical systems. These three anchors represent divergent strategic postures: Amcor leverages global extrusion footprint, Berry Global anchors North American demand through converter relationships, and AptarGroup concentrates on regulated pharmaceutical and food safety specifications.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| AptarGroup |
| Huhtamaki |
| Constantia Flexibles |
| Silgan Dispensing |
| Guala Closures |
| Winpak |
| Essel Propack |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EFSA-compliant mono-material structures and legacy multi-layer laminates manifests in both procurement premiums and converter qualification burdens. Buyers demanding REACH-compliant polyolefin streams pay tiered premiums that reflect migration testing documentation and film lamination concentration in German-Austrian supply clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs spout and closure procurement. Price differentiation rests on EFSA certification grade and volume scale, with pharmaceutical-grade tamper-evident systems commanding substantial premiums over commodity dairy formats. Cost compression in standard-tier polypropylene spout bodies is intensifying because propylene feedstock volatility tied to naphtha cracking economics compresses margin predictability. Brand procurement teams at mid-tier European dairy converters exhibit highest price sensitivity; pharmaceutical multinationals demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Specialized welding technician availability constrains capacity expansion in the Rhine-Main corridor around Frankfurt and the Lyon-Auvergne-Rhône-Alpes region. Geographic supply concentration centers on Germany, Austria, and France for high-barrier substrate production. Raw material dependencies draw from Saudi and Qatari propylene feedstock, German EVOH barrier resin, and Chinese spout insertion equipment. Single-source vulnerability characterizes ultrasonic welding head supply from Japanese precision manufacturers. Distribution runs through converter-direct relationships with brand procurement teams, disintermediating separate closure vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as rigid-to-pouch conversion accelerates demand for certified seal-integrity systems. Premium specification pull from pharmaceutical and baby food segments rewards suppliers with documented compliance infrastructure.
For Market Incumbents: Deepen backward integration into polymer compounding to secure REACH-compliant polyolefin streams against feedstock volatility. Anchor capacity in the Rhine-Main corridor to capture German dairy conversion demand. Certify tamper-evident systems under parallel FDA-EMA protocols to defend margin position against emerging Asian equipment suppliers. For New Entrants and Emerging Players: EU's Packaging and Packaging Waste Regulation opens a window for modular detachable-spout systems that enable film-recyclable body-spout separation. Target French condiment brands responding to Citeo modulation fees that reward lightweight formats. Enter through equipment-plus-film bundled offerings that disintermediate fragmented three-party sourcing models. For Investors and Strategic Acquirers: Consolidation pressure builds where converter capabilities fragment across welding precision, barrier film coextrusion, and regulatory documentation. Five-to-ten-year viability favors integrated film-closure suppliers over standalone equipment vendors. Target acquisition archetype: regional converters with captive spout insertion and EFSA-certified mono-material pouch lines. Signal to watch: EFSA evaluation timeline compression for recycled-content food-contact layers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-compliant polyolefin streams secure margin against naphtha-cracking volatility. |
| Ultrasonic Welding Equipment Automation | German dairy converters replace legacy hot-bar systems at 15-20% annual replacement rates. |
| Mono-Material Barrier Film Development | EVOH-PE coextrusion advances displace aluminum foil under EU design-for-recycling mandates. |
| Integrated Spout-Film Supply Consolidation | French and Italian sauce markets shift toward single-source seal-integrity accountability. |
| Detachable Spout System Launch | Modular configurations enable consumer separation of recyclable film from reusable closures. |
Research Methodology
Coverage spans Germany, France, Netherlands, United States, and China, with primary inputs from each market's converter and brand stakeholder base. Primary interviews with flexible film plant managers, dairy procurement leads, pharmaceutical packaging engineers, and spout insertion equipment manufacturers combined with secondary validation from EFSA guidance documents, FDA food contact substance notifications, EU Packaging and Packaging Waste Regulation drafts, and customs trade data. Bottom-up shipment analysis triangulated against top-down market sizing across product architecture and end-use segments.
Rate-of-change decomposition anchored growth projections to rigid-to-pouch conversion velocity, regulatory compliance deadline clustering, and equipment replacement cycle timing across the analysis window. Segmentation dimensions modeled include product type, material chemistry, end-use application, and design feature tier. CAGRs derived from volume trajectory analysis incorporating EVOH-PE coextrusion adoption curves and ultrasonic welding equipment penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA evaluation timeline extension or propylene feedstock disruption scenarios. Material deviation in EU Packaging and Packaging Waste Regulation implementation schedules or REACH migration testing protocol revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Drop Sealers Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
End Cap Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Cover Caps Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Vented Caps Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Twist Caps Market
Caps and Closures
Gamma Seal Lids Market