
 Overcaps Market | 2026-2036
Overcaps Market Size, Share, and Industry Trends Forecast 2026-2036
Overcaps Market Analytics
Aftermarket closure refurbishment revenue is narrowing as original equipment manufacturers tighten specifications and shorten replacement cycles. Berry Global Inc. leverages integrated resin-to-cap manufacturing across North American and European plants. Silgan Holdings Inc. anchors its position through metal-overcap dominance in beverage and food segments. BERICAP competes on multi-cavity tooling scale, supplying threaded overcaps to global bottling lines.
Overcaps are secondary closure components designed to fit atop primary caps or container necks, typically manufactured through injection molding, compression molding, or deep-drawing processes with wall thicknesses ranging from 0.5 to 2.5 millimeters depending on material and functional requirements. Their primary purpose is to provide tamper evidence, aesthetic finishing, brand differentiation, or additional barrier protection for packaged consumer goods. Plastic overcaps sustain the largest volume share due to polyethylene and polypropylene cost efficiency and design flexibility across pharmaceutical and personal care applications. Specialty overcaps, including child-resistant and senior-friendly variants, occupy the fastest-expanding margin pool as regulatory mandates tighten. Metal overcaps retain structural importance in premium beverage packaging where embossing and tactile finish command shelf differentiation.
FDA 21 CFR Part 170-189 governs indirect food additive compliance for polymeric overcaps entering US food and beverage channels, while EMA guidelines on pharmaceutical packaging integrity shape child-resistant closure specifications across European markets. EPA and REACH frameworks restrict certain plasticizers and heavy metals, compelling reformulation of resin compounds and migration testing protocols. Stakeholders must monitor evolving extended producer responsibility schemes and single-use plastic directives that threaten to reclassify disposable overcaps as regulated packaging waste.
Market Dynamics
REACH compliance deadlines and EU Packaging Waste Directive enforcement are forcing resin reformulation across European overcap supply chains, compressing margins for converters while accelerating recyclable substrate adoption.
Growth Catalysts
- Child-resistant mandate expansion:EMA pharmaceutical packaging integrity guidelines tighten specifications for pediatric safety closures, pulling demand toward tamper-evident overcap systems.
- Precision molding cluster density:Germany's Rhineland-Palatinate and Bavaria regions concentrate multi-cavity tooling capacity, reducing lead times for pharmaceutical contract packagers.
- Recyclable polypropylene advancement:Next-generation nucleating agents enable thinner-wall designs without sacrificing thread integrity, cutting material intensity per unit.
Market Restraints
- Feedstock volatility:Propylene monomer price swings tied to naphtha-cracker economics destabilize converter margins quarter-to-quarter.
- Tooling supply concentration:High-cavity mold fabrication concentrates among specialized German and Austrian machine builders, creating capacity bottlenecks for new entrants.
- Metal substitution ceiling:Premium beverage embossing requirements limit plastic displacement in spirits and champagne segments despite cost differentials.
Strategic Opportunities
- Senior-friendly closure gap:Arthritis-compliant opening torque specifications remain underdeveloped in North American OTC pharmaceutical packaging.
- Extended producer responsibility tailwinds:EU Green Deal packaging waste targets incentivize mono-material overcap designs that simplify post-consumer sorting.
- Digital printing convergence:Direct-to-object inkjet integration with injection molding lines enables batch-level customization for craft beverage micro-segments.
Industry Challenges
- Migration testing backlog:FDA 21 CFR Part 170-189 compliance documentation creates 14-18 month certification timelines for new resin compounds.
- Legacy press retrofit costs:All-electric injection systems required for thin-wall precision demand capital outlays that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overcaps Market |
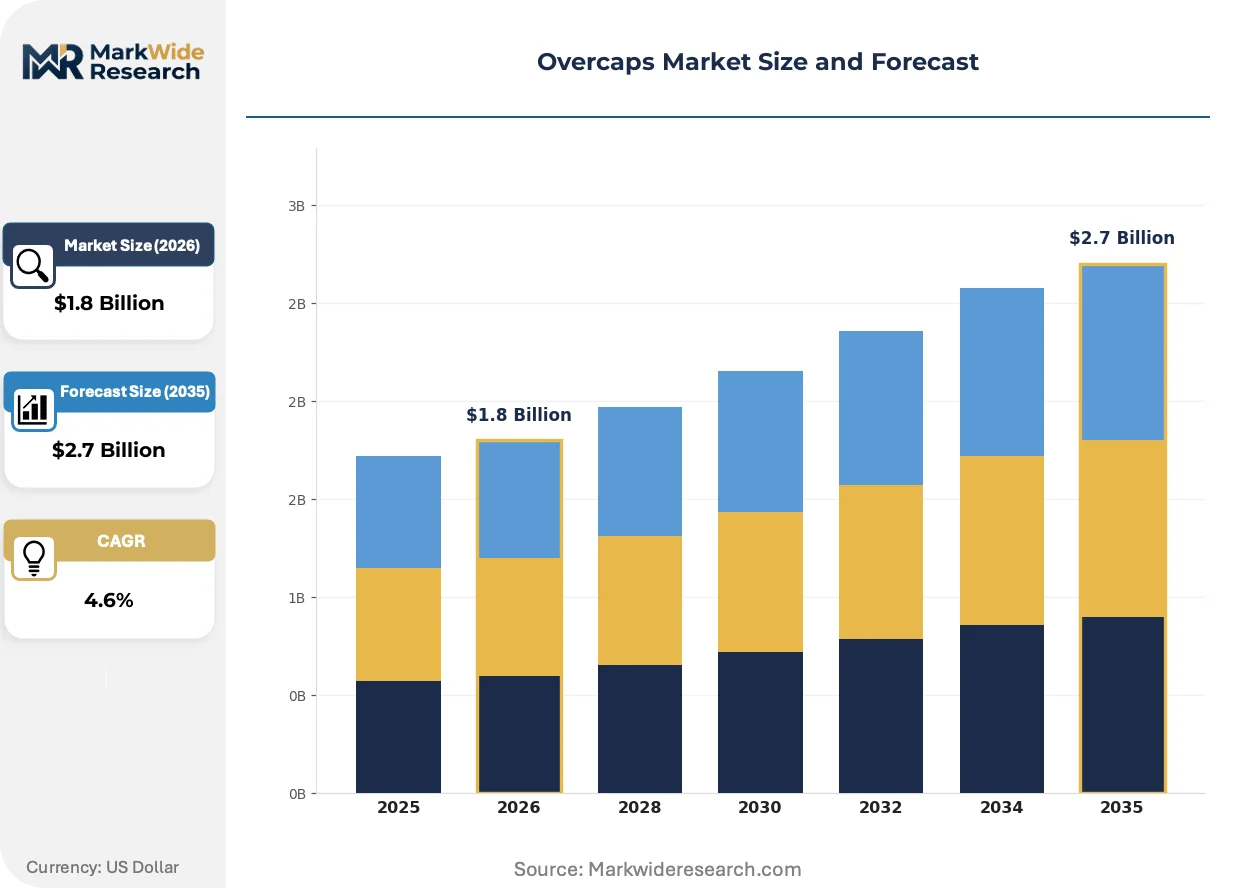
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Overcaps, Metal Overcaps, Cardboard Overcaps, Specialty Overcaps Application: Pharmaceutical Packaging, Beverage Packaging, Food Packaging, Personal Care Packaging Material: Polyethylene, Polypropylene, Aluminum, Paperboard End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | Berry Global Inc., AptarGroup, Inc., Silgan Holdings Inc., Weener Plastics Group, BERICAP, SABIC, Toray Advanced Composites, Evonik Industries AG, Suprem SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overcaps Market Evolving Landscape
Digital thread technologies and regulatory material bans are compressing traditional development cycles while opening specification windows for novel substrate combinations.
Digital mold-flow simulation is virtualizing prototype iteration for multi-cavity overcap designs, compressing lead times from twelve weeks to under four. Pharmaceutical packagers in Switzerland and Germany adopt these tools aggressively. The technology is virtualizing physical tooling trials that previously consumed 30-40% of new product introduction budgets.
REACH Annex XVII restrictions on phthalate plasticizers force reformulation of flexible overcap seals used in personal care applications. Compounders must validate alternative plasticizers through exhaustive migration testing. Food-contact overcap segments face the steepest compliance cost escalation as EFSA reviews accumulate backlogs.
Brand owners now specify batch-level traceability embedded in closure QR codes, displacing generic overcap procurement. Beverage co-packers in Italy and Spain reorganize supplier qualification around this capability. Contract manufacturers absorb the data infrastructure costs to retain multinational account access.
Overcaps Market Segmentation
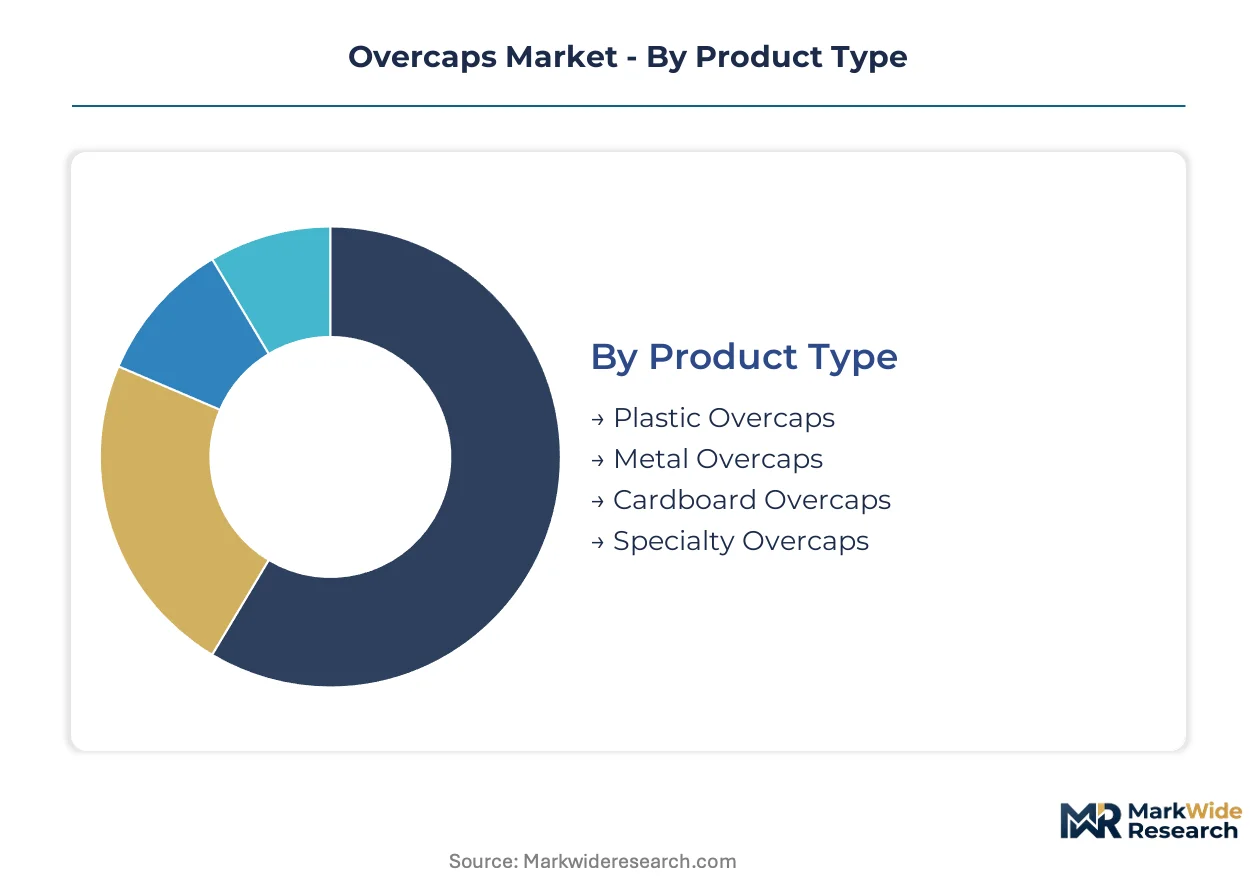
Overcap specification diversity reflects divergent barrier requirements across pharmaceutical safety mandates, beverage shelf differentiation, and food contact compliance. Material selection and molding precision determine which converters capture volume in each vertical.
Product Type:
Application durability and regulatory exposure dictate substrate selection across child-resistant, tamper-evident, and premium aesthetic functions.
- Plastic Overcaps:Injection-molded polyethylene and polypropylene constructions dominate pharmaceutical and personal care volumes due to cost efficiency and thread precision. Demand concentrates in Germany's Rhineland-Palatinate molding clusters serving EMA-compliant contract packagers with sub-0.1mm tolerance specifications.
- Metal Overcaps:Deep-drawn aluminum shells deliver embossing depth and tactile finish for premium spirits and champagne segments. Beverage packagers in France and Italy specify metal overcaps where shelf differentiation commands price premiums despite higher unit costs.
- Cardboard Overcaps:Paperboard laminates serve limited dry-goods applications with minimal moisture exposure.
- Specialty Overcaps:Child-resistant and senior-friendly variants integrate dual-action mechanisms or torque-reduction features.
Plastic overcaps hold installed capacity. Specialty overcaps are rotating up the share rankings.
Application:
End-use verticals impose distinct migration testing burdens, opening torque specifications, and line-speed requirements on closure suppliers.
- Pharmaceutical Packaging:EMA pediatric safety guidelines mandate tamper-evident overcap systems with documented opening force ranges. Swiss and German packagers drive specification tightening as FDA 21 CFR Part 170-189 compliance documentation extends new resin certification timelines.
- Beverage Packaging:Carbonation retention and crown-crown compatibility determine overcap geometry for beer and soft drink bottlers. Italian and Spanish co-packers now require batch-level QR traceability embedded in closure surfaces.
- Food Packaging:Dry condiment and spice applications tolerate thinner-wall polyethylene designs.
- Personal Care Packaging:REACH Annex XVII phthalate restrictions force flexible seal reformulation in cosmetic overcaps.
Pharmaceutical packaging commands specification authority. Beverage packaging is climbing the fastest as craft micro-segments proliferate.
Material:
Feedstock volatility and recyclability mandates are re-ranking material economics across converter portfolios.
- Polypropylene:Next-generation nucleating agents enable 15-20% wall-thickness reduction without thread deformation. German compounders supply pharmaceutical-grade grades with documented migration profiles for EMA submission packages.
- Polyethylene:LDPE and HDPE variants serve cost-sensitive food and personal care volumes where barrier requirements permit lower stiffness.
- Aluminum:Rolled and deep-drawn sheet metal retains structural importance in premium beverage embossing applications.
- Paperboard:Coated board stocks occupy niche dry-goods segments with limited regulatory exposure.
Polypropylene anchors converter resin inventories. Polyethylene is gaining share fastest as thin-wall designs cut material intensity.
End User:
Procurement authority and specification control vary sharply across the value chain, determining converter sales strategy and margin capture.
- Manufacturers:Brand-owning pharmaceutical and beverage companies dictate resin specifications, cavity counts, and traceability protocols. Swiss pharmaceutical manufacturers now mandate digital thread documentation from mold-flow simulation through production.
- Distributors:Regional packaging resellers aggregate demand from mid-tier personal care and food accounts with standardized SKU requirements.
- Retailers:Private-label specification authority concentrates in European grocery chains with sustainability scorecard requirements.
- Consumers:Direct purchasing remains negligible except for specialty refill and replacement closure channels.
Manufacturers hold specification control. Retailers are rotating up the share rankings as private-label sustainability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical packagers in Germany absorb price premiums for EMA-compliant precision molding, while beverage bottlers in Italy and Spain prioritize cost efficiency in high-volume overcap procurement.
Germany
Rhineland-Palatinate and Bavaria host dense clusters of multi-cavity tooling fabricators serving contract pharmaceutical packagers with sub-0.1mm thread tolerance capabilities. REACH Annex XVII compliance deadlines force resin reformulation across converter supply chains. Precision molding capacity concentrates around Ludwigshafen and Munich, where nucleating-agent-enhanced polypropylene grades enable thinner-wall designs.
Switzerland
Swiss pharmaceutical manufacturers mandate digital thread documentation from mold-flow simulation through production, tightening supplier qualification protocols. Swissmedic pediatric safety guidelines align with EMA packaging integrity standards. Basel and Zurich anchor high-specification overcap demand from multinational drug manufacturers.
United States
FDA 21 CFR Part 170-189 compliance documentation extends new resin certification timelines to 14-18 months, compressing converter margins. EPA frameworks restrict certain plasticizers in food-contact applications. Berry Global Inc. leverages integrated resin-to-cap manufacturing across domestic plants to defend position.
Italy
Italian beverage co-packers reorganize supplier qualification around batch-level QR traceability embedded in closure surfaces. EU Packaging Waste Directive enforcement accelerates mono-material overcap adoption. Emilia-Romagna and Lombardy concentrate craft beverage micro-segments driving digital printing convergence.
France
French spirits and champagne segments specify deep-drawn aluminum overcaps where embossing depth commands shelf differentiation. ANSM pharmaceutical packaging regulations mirror EMA child-resistant closure specifications. Premium beverage packaging demand concentrates in Reims and Épernay production zones.
Overcaps Market Competitive Landscape
Integrated resin-to-cap manufacturers and specialized multi-cavity tooling suppliers split the market along capability lines. Three strategic archetypes dominate: backward-integrated polymer compounders controlling raw material cost structures, precision molding specialists capturing pharmaceutical specification premiums, and metal-forming fabricators defending premium beverage embossing segments. Capacity expansion and digital thread technology licensing represent the dominant competitive moves as converters differentiate on traceability documentation.
Within the integrated-manufacturing tier, Berry Global Inc. exemplifies backward control over resin supply chains, while Silgan Holdings Inc. anchors metal-overcap positioning in beverage applications. BERICAP occupies a position among multi-cavity tooling scale suppliers. These three entities represent distinct strategic postures: captive resin integration, premium metal-forming specialization, and high-throughput threaded closure supply.
| Leading Market Players |
|---|
| Berry Global Inc. |
| AptarGroup, Inc. |
| Silgan Holdings Inc. |
| Weener Plastics Group |
| BERICAP |
| SABIC |
| Toray Advanced Composites |
| Evonik Industries AG |
| Suprem SA |
| Others |
Value Network & Pricing Analysis
Overcapacity in German precision molding clusters is compressing converter margins while simultaneously strengthening buyer negotiation leverage across pharmaceutical contract packaging tiers. Utilization rates below optimal thresholds force suppliers to absorb resin reformulation costs rather than pass through REACH compliance expenses, reshaping pricing power distribution along the value chain.
Pricing Analysis
Aftermarket closure refurbishment revenue drives lifetime value capture as original equipment manufacturers tighten specifications and shorten replacement cycles. Three-tier pricing structure across premium EMA-compliant, standard food-contact, and economy dry-goods levels separates pharmaceutical-grade polypropylene with documented migration profiles from thinner-wall personal care variants. Cost compression in standard-tier polyethylene overcaps is intensifying because next-generation nucleating agents enable material intensity reductions without thread deformation. Mid-tier beverage co-packers exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers absorb premiums for digital thread documentation and sub-0.1mm tolerance capabilities.
Supply Chain Analysis
Propylene monomer supply draws from naphtha-cracker economics concentrated in Germany, Belgium, and the Netherlands, with polymer compounding capacity clustering around Ludwigshafen and Rotterdam. High-cavity mold fabrication rests on specialized machine builders in Germany and Austria, while aluminum sheet metal for premium beverage embossing sources from French and Italian rolling mills. Single-source vulnerability in precision tooling creates capacity bottlenecks for new entrants seeking pharmaceutical qualification. Distribution runs through regional packaging resellers aggregating mid-tier personal care and food accounts, with direct manufacturer relationships dominating pharmaceutical and premium beverage procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in multi-cavity tooling fabrication capability and FDA 21 CFR Part 170-189 migration testing documentation creates defensive moats for incumbents while raising capital barriers for challengers seeking pharmaceutical qualification.
For Market Incumbents: Build certification moats by accelerating FDA submission packages for next-generation nucleating agent formulations before compliance timelines extend further. Invest in all-electric injection systems for thin-wall precision in Rhineland-Palatinate facilities to capture EMA specification premiums. Defend against metal substitution ceilings in premium beverage segments by embedding batch-level QR traceability that brand owners now mandate. For New Entrants and Emerging Players: Senior-friendly closure specifications for arthritis-compliant opening torque in North American OTC pharmaceutical packaging represent the most penetrable entry point with underdeveloped incumbent focus. Italian and Spanish craft beverage micro-segments driving digital printing convergence offer secondary white-space with lower tooling qualification barriers. Partner with regional distributors possessing existing pharmaceutical relationships to bypass direct manufacturer procurement protocols. For Investors and Strategic Acquirers: Capital is best deployed toward precision molding specialists with documented EMA submission packages and captive nucleating agent compounder relationships. Long-term viability hinges on converter ability to absorb extended producer responsibility scheme compliance costs without margin erosion. Watch for REACH Annex XVII expansion to additional plasticizer classes as inflection indicator for resin reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Thread Technology Licensing | Swiss pharmaceutical manufacturers now mandate simulation-to-production documentation, displacing generic suppliers. |
| Multi-Cavity Tooling Capacity Expansion | German machine builder bottlenecks create acquisition premiums for converters with in-house fabrication capability. |
| Mono-Material Design Repositioning | EU Packaging Waste Directive enforcement accelerates recyclable polypropylene adoption across Italian beverage co-packers. |
| Backward Integration into Resin Compounding | Berry Global's captive supply model defends margins against propylene monomer volatility destabilizing independent converters. |
| Senior-Friendly Mechanism Development | Arthritis-compliant torque specifications remain unaddressed in North American OTC packaging, opening specification windows. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with injection molding plant managers, pharmaceutical contract packaging procurement leads, beverage co-packer operations directors, and multi-cavity tooling fabricators; and secondary validation through FDA 21 CFR Part 170-189 filings, EMA packaging integrity guidelines, REACH Annex XVII restriction updates, and EU Packaging Waste Directive enforcement notices. Bottom-up capacity assessments across Rhineland-Palatinate and Bavaria molding clusters were triangulated against top-down demand estimates from pharmaceutical and beverage end-use verticals.
Forecast inputs considered material substitution dynamics, regulatory compliance timeline extensions, and precision molding capacity utilization across the projection horizon. Segmentation dimensions modeled include product type, application vertical, material grade tier, and end-user procurement authority. CAGRs were derived from trend extrapolation of nucleating agent adoption rates and child-resistant mandate expansion patterns, cross-referenced against resin price elasticity estimates from polymer compounder disclosures.
Practitioners should monitor REACH Annex XVII expansion scope and FDA migration testing backlog duration for early signals of certification timeline compression. Forecasts reflect assumptions regarding sustained EMA guideline alignment across European national regulators and stable naphtha-cracker economics feeding propylene supply. Cross-checking against ECHA substance restriction notifications and pharmaceutical packaging tender databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Foam End Caps Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Metal Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Nigeria Plastic Caps and Closures Market