
 Foam Cap Liners Market | 2026-2036
Foam Cap Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Cap Liners Market Foresight
Technical support subscriptions for liner performance validation is restructuring how foam cap liner suppliers monetize relationships beyond unit sales. Selig Group leverages its global manufacturing footprint to sustain long-term contracts with multinational pharmaceutical packagers. Tekni-Plex anchors North American supply through vertically integrated foam extrusion and die-cutting operations. Tri-Seal differentiates via specialized silicone foam formulations for high-temperature chemical applications.
Foam cap liners are compressible sealing elements, typically 0.5–3.0 mm thick, manufactured from closed-cell or open-cell polymer foams bonded to foil or film backings; they create hermetic seals against container land surfaces through controlled compression set and resilience recovery. Polyethylene foam dominates unit volume in food packaging due to cost-efficient moisture barrier performance, while silicone foam commands premium positioning in pharmaceutical applications requiring US FDA extractables testing compliance. Polyurethane foam occupies a mature mid-tier segment where price competition from regional converters limits margin expansion.
US FDA 21 CFR compliance for indirect food contact and pharmaceutical primary packaging shapes material selection and migration testing protocols across domestic manufacturing. REACH restrictions on isocyanate-based foam precursors in Europe are forcing reformulation investments among exporters serving EU personal care brands. ISO 9001 and ISO 15378 certification requirements for medicinal product packaging create qualification barriers that concentrate supply relationships with audited Tier-1 converters. Stakeholders must monitor evolving PFAS restrictions in foam substrates, as state-level US bans and EU proposals threaten incumbent polyethylene and polyurethane chemistries without proven fluorine-free alternatives.
Market Dynamics
Pharmaceutical packaging integrity mandates are compressing supplier qualification timelines and forcing foam cap liner manufacturers to restructure their technical service models around validation support rather than commodity supply.
Growth Catalysts
- US FDA 21 CFR closure integrity guidelines:Tightening extractables testing requirements for pharmaceutical primary packaging are disqualifying non-compliant regional converters and consolidating purchase orders with certified Tier-1 suppliers.
- Silicone foam chemistry advancement:High-temperature resilience above 200°C is opening substitution opportunities against PTFE-lined closures in aggressive chemical storage applications.
- New Jersey pharmaceutical packaging cluster:Concentrated drug manufacturing and contract packaging operations within a 150-mile radius of Newark generate localized demand pull for just-in-time liner supply.
Market Restraints
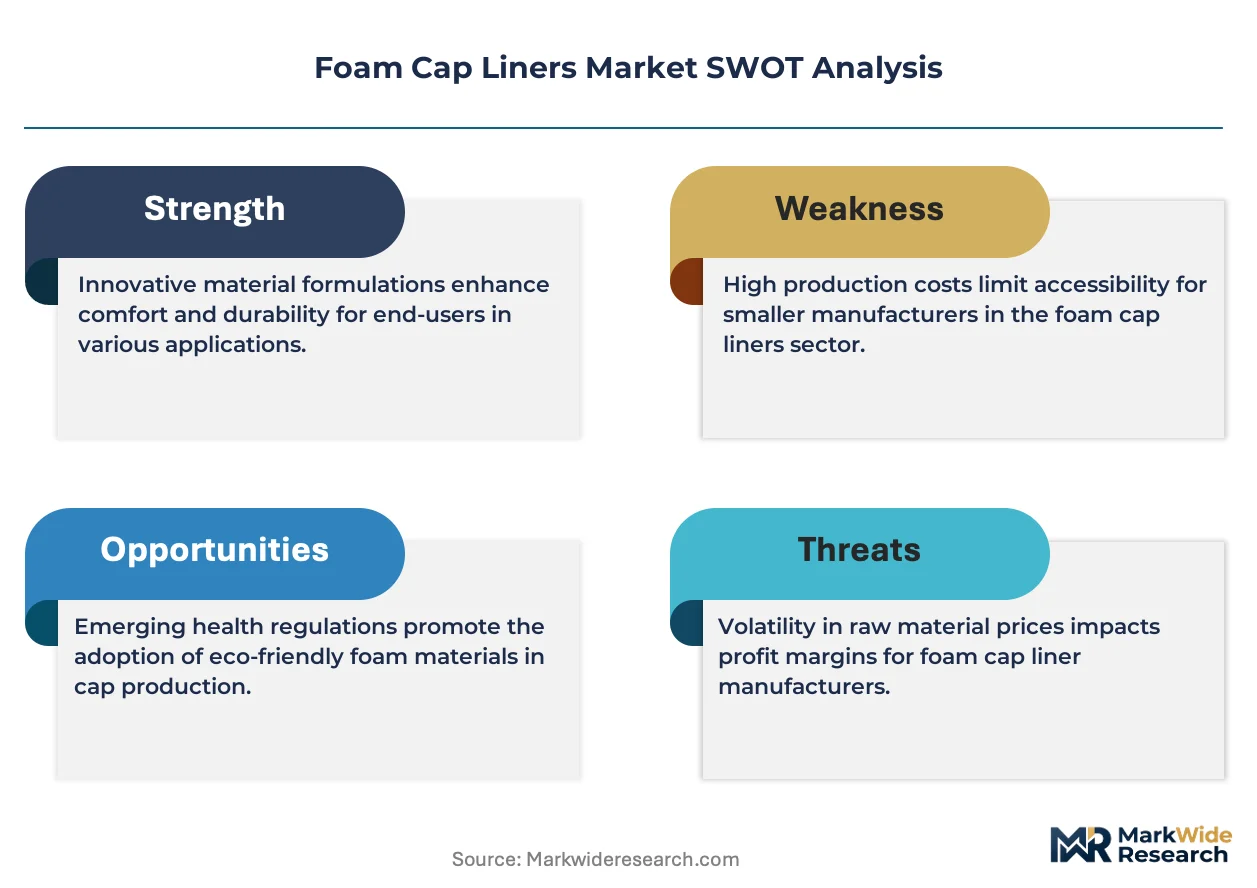
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress polyethylene foam margins, forcing quarterly contract renegotiations with food packaging buyers.
- EU REACH isocyanate restrictions:Tightening authorization requirements for polyurethane foam precursors are blocking EU market access for non-reformulated US and Asian exporters.
- Aluminum foil backing supply concentration:Three European rolling mills control pharmaceutical-grade foil substrate, creating single-source vulnerability for North American die-cutters.
Strategic Opportunities
- India pharmaceutical contract manufacturing expansion:CDSCO's alignment with ICH Q3D guidelines is creating demand for US FDA-equivalent liner validation services among domestic packagers.
- Biologic drug cold-chain packaging:Ultra-low temperature silicone foam formulations below -70°C represent unserved white space as mRNA vaccine distribution networks mature.
- Technical subscription services:Annual performance validation contracts are displacing transactional liner sales and embedding suppliers deeper into pharmaceutical quality systems.
Industry Challenges
- ISO 15378 audit backlog:Certification queue delays of 8-14 months are freezing new supplier qualification for medicinal product packaging contracts.
- Legacy compression set testing equipment:Outdated ASTM D3574 apparatus at mid-tier converters cannot generate the accelerated aging data required by pharmaceutical buyers.
- PFAS-free formulation uncertainty:Absence of validated fluorine-free foam substrates is forcing speculative R&D commitments ahead of anticipated state-level US bans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Cap Liners Market |
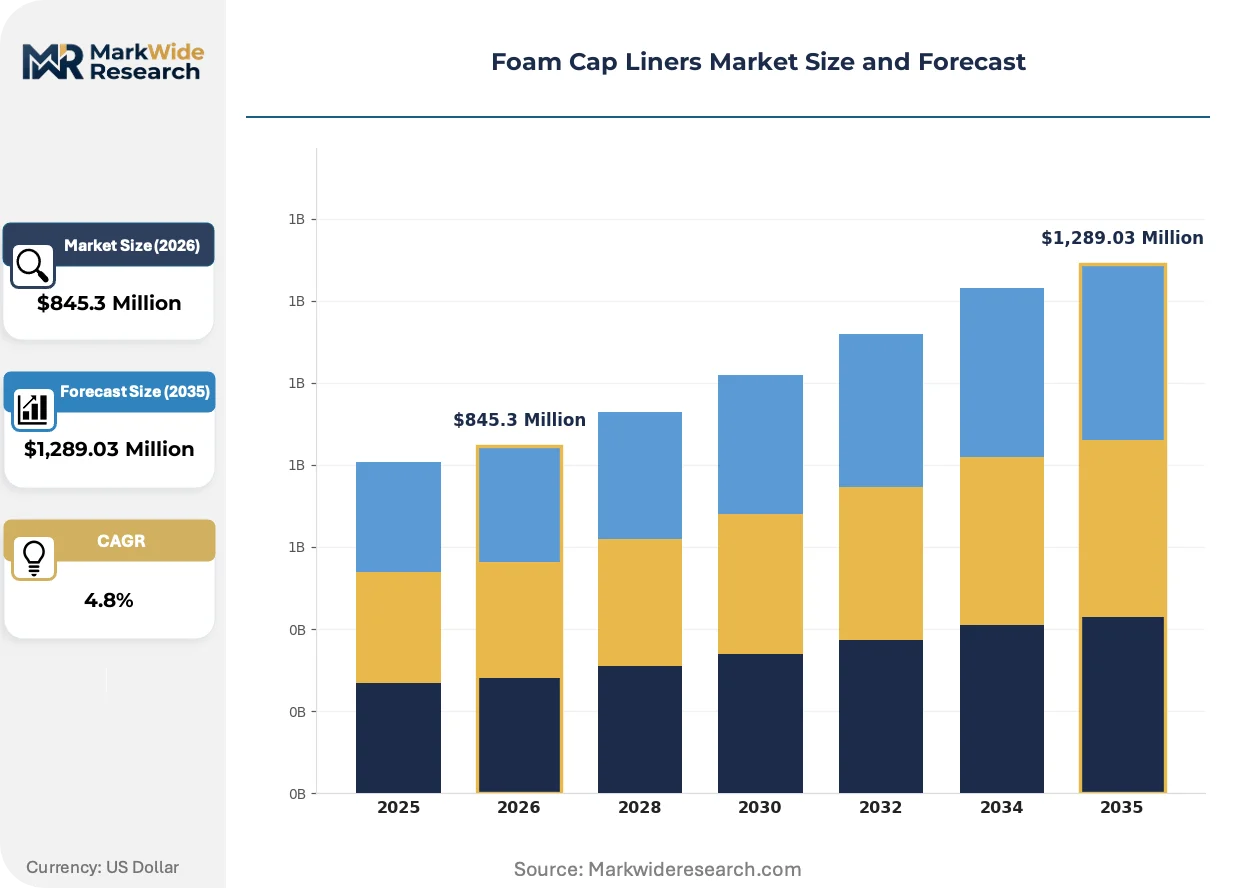
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $1,289.03 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
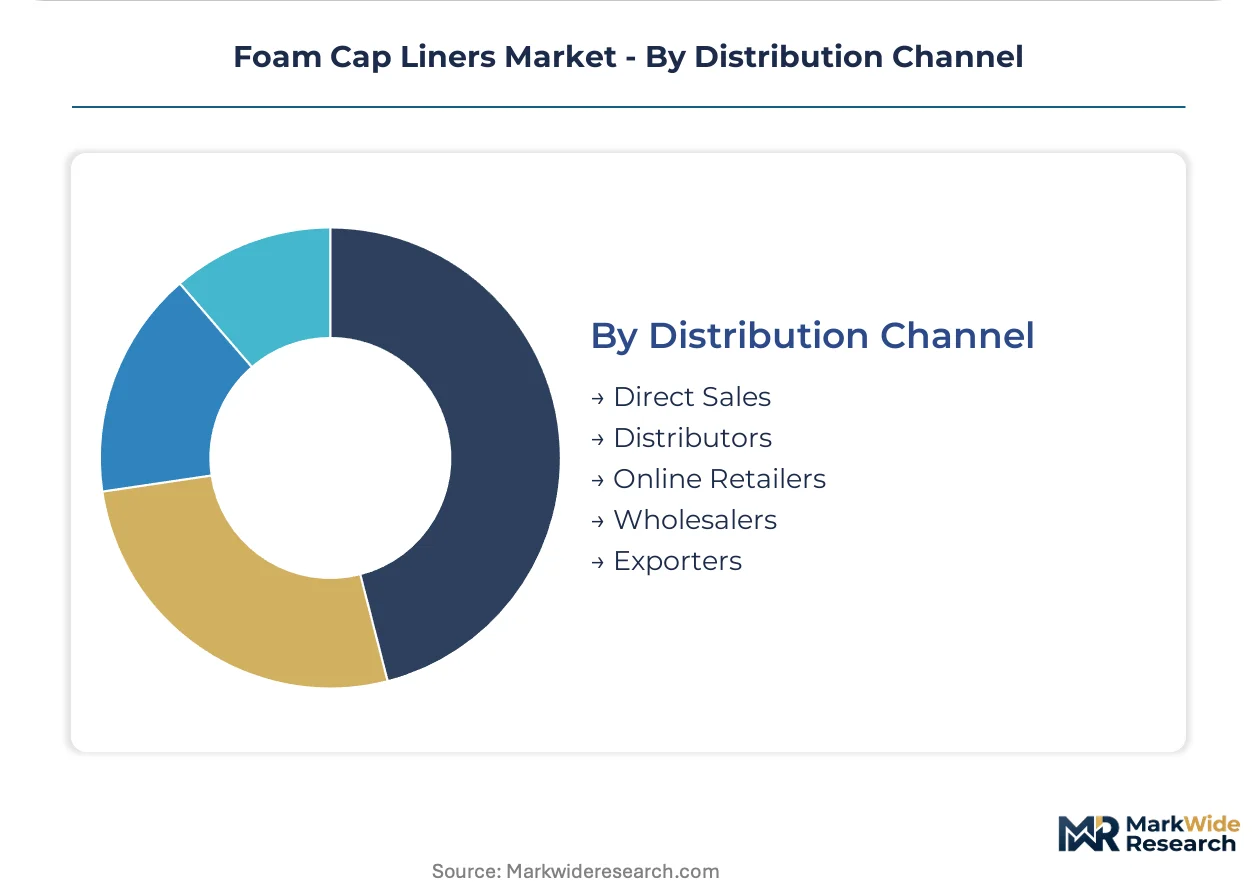
| Segmentation | Product Type: Polyurethane Foam, Polyethylene Foam, Silicone Foam, Neoprene Foam, Ethylene Vinyl Acetate, PVC Foam Application: Cosmetics, Pharmaceuticals, Food Packaging, Industrial Containers, Household Bottles, Chemical Packaging End User: Personal Care Manufacturers, Drug Makers, Food Processors, Chemical Producers, Packaging Companies, Beverage Bottlers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Exporters |
| Companies Covered | Selig Group, Tekni-Plex, Tri-Seal, Pres-On, Bluemay, Sigma CapSeal, Sun Glo, Action Technology, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Cap Liners Market Shifts & Advancements
Material science convergence with digital quality assurance is restructuring how foam cap liner suppliers differentiate beyond base chemistry, compressing the viable supplier base to those with integrated analytical capabilities.
Co-extruded multilayer foam-film laminates are consolidating technical performance expectations for pharmaceutical applications. Major drug packagers now specify three-layer constructions combining moisture barrier, compressible seal, and chemical inertness in single-source supply agreements. This specification compression is eliminating single-material foam liners from new product qualification pipelines and raising capital barriers for equipment conversion.
REACH restrictions on per- and polyfluoroalkyl substances are forcing wholesale substrate reformulation across EU-serving supply chains. ECHA's 2023 restriction proposal timeline has triggered pre-emptive investment in fluorine-free polyethylene foam by exporters seeking to maintain continental market access. Personal care brands with pan-European distribution are now requiring PFAS-free certification in supplier scorecards ahead of regulatory enforcement.
Pharmaceutical buyers are unbundling liner supply from closure assembly and contracting validation services separately. Large contract packagers near Princeton and Philadelphia are establishing captive analytical laboratories for extractables testing, reducing dependence on supplier-generated data. This capability internalization is compressing the technical services premium that foam liner manufacturers previously commanded and shifting competitive focus to lot-to-lot consistency metrics.
Foam Cap Liners Market Segmentation
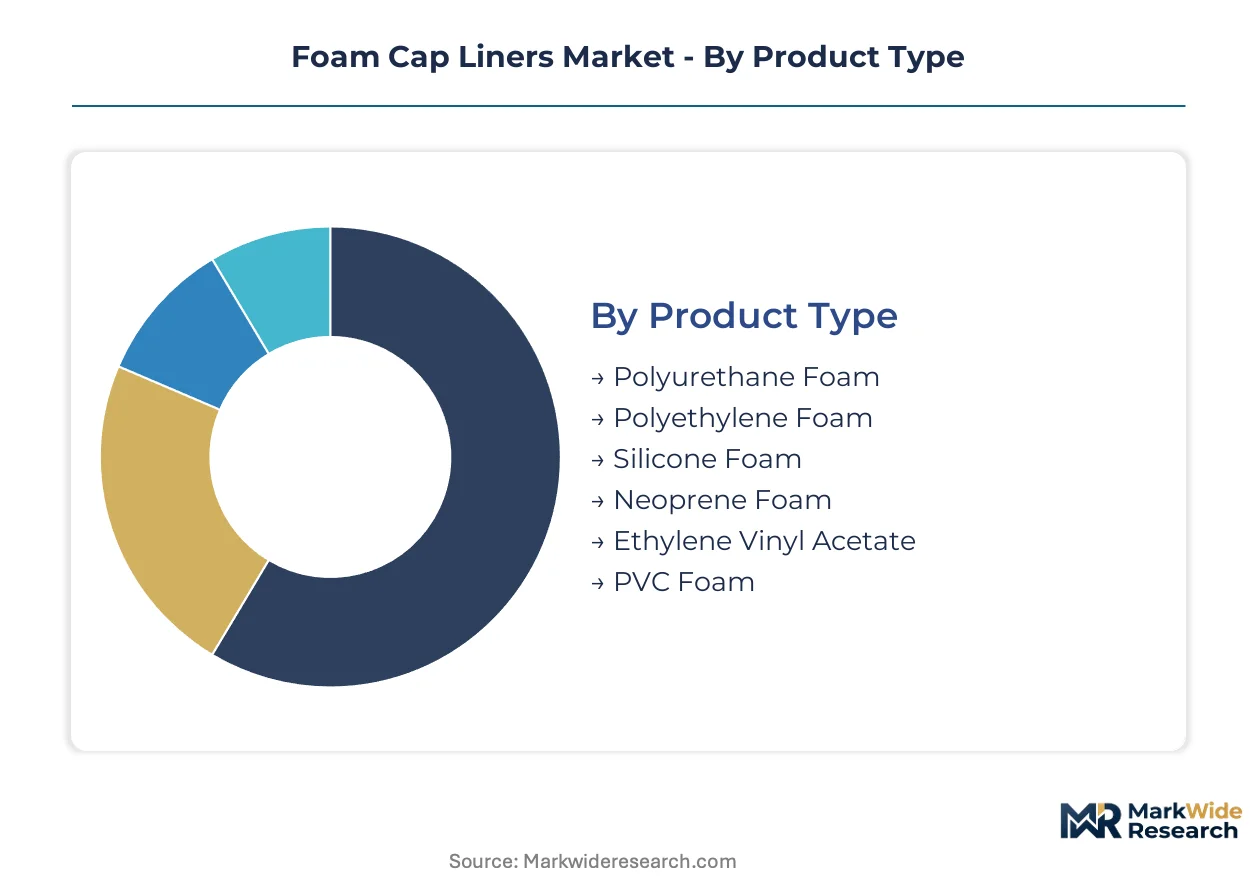
Segmentation in foam cap liners reveals how material chemistry, regulatory compliance requirements, and end-use performance specifications fragment supply relationships. Buyers select substrates based on compression set recovery, extractables profiles, and temperature resilience rather than price alone.
Product Type:
Supply concentrates around three chemistries with validated US FDA compliance pathways, while regional converters struggle to qualify niche formulations for pharmaceutical contracts.
- Polyethylene Foam:Closed-cell structure delivers moisture barrier performance at unit cost levels acceptable to high-volume food packaging operations. Demand clusters around New Jersey and Pennsylvania contract packagers serving shelf-stable condiment brands.
- Silicone Foam:Platinum-cured formulations withstand autoclave sterilization cycles above 200°C and pass US FDA extractables testing under 21 CFR indirect food contact guidelines. Drug makers in the Newark pharmaceutical corridor specify this substrate for parenteral drug vial seals.
- Polyurethane Foam:Open-cell variants dominate industrial container applications where chemical resistance takes priority over pharmaceutical-grade purity.
- Neoprene Foam:Chloroprene-based chemistry serves chemical packaging requiring resistance to hydrocarbon exposure.
- Ethylene Vinyl Acetate:Copolymer foam bridges cost and performance for household bottle applications with moderate temperature demands.
- PVC Foam:Rigid closed-cell structure supports industrial cap closures where dimensional stability under load matters more than compression recovery.
Polyethylene foam absorbs the bulk of installed capacity; silicone foam is expanding most quickly as pharmaceutical qualification timelines compress supplier selection.
Application:
Application segmentation tracks how US FDA closure integrity mandates and EU REACH chemical restrictions reshape demand concentration across end-use categories.
- Pharmaceuticals:Primary packaging for oral solids and parenteral drugs requires ISO 15378-certified liners with documented extractables profiles. Princeton-area contract packagers now mandate three-layer co-extruded constructions combining foil barrier, compressible seal, and chemically inert facing.
- Food Packaging:Moisture-sensitive dry goods and condiment bottles specify polyethylene foam with aluminum foil backing to prevent oxidative rancidity. Regional dairy processors in Wisconsin and California drive specification standardization for threaded closure compatibility.
- Cosmetics:Premium skincare brands specify silicone foam for aesthetic compression recovery and fragrance barrier performance.
- Industrial Containers:Lubricant and solvent packaging prioritizes chemical resistance over migration testing compliance.
- Household Bottles:Cleaning product manufacturers balance cost pressure with basic seal integrity requirements.
- Chemical Packaging:Aggressive substance storage demands neoprene or specialized fluoropolymer-facing liners with documented compatibility data.
Food packaging commands the greatest production volume; pharmaceutical applications are climbing the fastest as biologic drug cold-chain requirements multiply.
End User:
End user structure reflects how captive packaging operations, outsourced contract manufacturing, and merchant supply relationships distribute purchasing power across the value chain.
- Drug Makers:Large pharmaceutical manufacturers near Philadelphia and Boston maintain approved supplier lists with ISO 15378 certification mandatory for new contract awards. Internal quality systems now require lot-to-lot compression set data with statistical process control documentation.
- Personal Care Manufacturers:Multinational beauty brands with EU distribution are adding PFAS-free certification requirements to supplier scorecards ahead of ECHA enforcement timelines.
- Food Processors:National condiment and sauce brands consolidate liner procurement through packaging engineering teams focused on total applied cost rather than unit price.
- Chemical Producers:Specialty chemical manufacturers specify liners based on substance-specific compatibility testing rather than generic material certifications.
- Packaging Companies:Integrated closure manufacturers backward into foam extrusion to capture margin and reduce qualification complexity for pharmaceutical accounts.
- Beverage Bottlers:Carbonated and still water brands prioritize oxygen barrier performance with limited regulatory compliance burden.
Drug makers anchor the highest-margin segment; packaging companies are gaining share fastest through vertical integration into foam extrusion and die-cutting.
Distribution Channel:
Channel structure reveals how technical validation requirements and just-in-time delivery demands concentrate supply relationships away from transactional wholesale.
- Direct Sales:Tier-1 suppliers like Selig Group and Tekni-Plex maintain dedicated account teams for pharmaceutical packagers requiring validation support and custom die-cutting. Annual technical service subscriptions now generate recurring revenue exceeding unit sales value for qualified accounts.
- Distributors:Regional converters serving food packaging and industrial applications rely on master distributors for polyethylene foam sheet and aluminum foil substrate.
- Exporters:US manufacturers serving EU personal care brands must navigate REACH isocyanate restrictions and forthcoming PFAS limitations through specialized trade intermediaries.
- Wholesalers:Standard-dimension liners for household and industrial applications move through packaging supply wholesalers with limited technical service attachment.
- Online Retailers:Small-batch and prototype quantities reach independent cosmetic formulators and craft beverage startups through specialized e-commerce channels.
Direct sales captures the greatest value concentration; distributor relationships are extending fastest into technical subscription services for mid-tier pharmaceutical accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Newark anchors pharmaceutical foam liner demand through its concentrated contract packaging corridor serving drug makers within a 150-mile radius.
United States
Princeton-area contract packagers now mandate three-layer co-extruded liner constructions combining foil barrier, compressible seal, and chemically inert facing for parenteral drug applications. US FDA 21 CFR closure integrity guidelines tighten extractables testing requirements, disqualifying non-compliant regional converters. The New Jersey and Pennsylvania pharmaceutical packaging clusters generate localized demand pull for just-in-time liner supply.
Germany
EU REACH restrictions on isocyanate-based polyurethane foam precursors force reformulation investments among exporters serving domestic personal care brands. ECHA's 2023 PFAS restriction proposal timeline triggers pre-emptive investment in fluorine-free polyethylene foam by suppliers seeking continental market access. The Düsseldorf-Cologne industrial corridor concentrates pharmaceutical packaging engineering and liner specification authority.
India
CDSCO alignment with ICH Q3D guidelines creates demand for US FDA-equivalent liner validation services among domestic pharmaceutical packagers. Maharashtra's Mumbai-Pune pharmaceutical manufacturing belt drives specification adoption for contamination-resistant seals in oral solid dosage packaging. Domestic contract manufacturers expand cold-chain infrastructure for biologic drug distribution.
China
NMPA pharmaceutical packaging regulations tighten material compliance requirements for primary packaging used in injectable drug applications. The Yangtze River Delta pharmaceutical manufacturing zone concentrates demand for silicone foam liners with documented extractables profiles. Regional foam extruders invest in ISO 15378 certification to qualify for multinational drug maker supplier lists.
Japan
PMDA guidelines for pharmaceutical container closure systems shape material selection protocols for domestic and export-oriented drug packaging. The Kanto region's Tokyo-Osaka pharmaceutical corridor maintains stringent supplier qualification timelines compressing purchase decisions to audited Tier-1 converters. Local packagers prioritize lot-to-lot compression set data with statistical process control documentation.
Foam Cap Liners Market Competitive Landscape
Capital-heavy foam extrusion and die-cutting operations compete with asset-light technical service providers for pharmaceutical validation contracts. The supplier base concentrates around certified Tier-1 converters with ISO 15378 audit completion, while mid-tier regional players face exclusion from medicinal product packaging procurement. Three strategic archetypes dominate: vertically integrated multinationals with global manufacturing footprints, specialized silicone foam formulators serving high-temperature applications, and regional polyethylene converters focused on food packaging volume. Competitive moves center on backward integration into aluminum foil substrate supply and annual technical subscription services that embed suppliers deeper into pharmaceutical quality systems.
Among North American fabricators, Selig Group, Tekni-Plex, and Tri-Seal occupy positions representing distinct competitive archetypes. Selig Group exemplifies the multinational technical service model through its global manufacturing footprint sustaining long-term pharmaceutical contracts. Tekni-Plex anchors regional supply through in-house production of foam extrusion and precision die-cutting operations. Tri-Seal sits within the specialized formulation tier, differentiated via silicone foam chemistry for aggressive chemical storage applications requiring high-temperature resilience above 200°C.
| Leading Market Players |
|---|
| Selig Group |
| Tekni-Plex |
| Tri-Seal |
| Pres-On |
| Bluemay |
| Sigma CapSeal |
| Sun Glo |
| Action Technology |
| Winpak |
| Others |
Supply & Pricing Matrix
Ethylene and propylene price index volatility cascades through foam cap liner supply chains, compressing polyethylene foam margins and forcing quarterly contract renegotiations with food packaging buyers while pharmaceutical-grade silicone foam maintains pricing power through ISO 15378 certification scarcity.
Pricing Analysis
Margin tightening in polyethylene foam reflects ethylene feedstock volatility and regional converter overcapacity. Three-tier pricing structure across pharmaceutical-certified, food-grade standard, and industrial economy levels separates ISO 15378-audited suppliers from uncertified competitors. Pricing pressure intensifies in food packaging as buyers consolidate purchase orders for volume leverage. Drug makers show least price sensitivity, prioritizing extractables documentation and lot-to-lot consistency over unit cost.
Supply Chain Analysis
ISO 15378 certification gating concentrates pharmaceutical-grade supply among audited Tier-1 converters in the United States, Germany, and Japan. Raw material dependencies center on petrochemical feedstocks, pharmaceutical-grade aluminum foil from European rolling mills, and platinum-cured silicone precursors. Single-source vulnerability in foil substrate supply creates qualification bottlenecks for North American die-cutters. Distribution runs through direct technical service relationships for pharmaceutical accounts and master distributors for food packaging volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where US FDA 21 CFR closure integrity guidelines erect barrier-to-entry moats favoring certified incumbents with validated extractables testing capabilities.
For Market Incumbents: Deepen technical subscription services to embed recurring revenue relationships beyond unit sales. Expand captive aluminum foil substrate supply to mitigate European rolling mill concentration risk. Prioritize PFAS-free formulation R&D ahead of anticipated state-level US bans threatening incumbent polyethylene chemistries.
For New Entrants and Emerging Players: Begin with cold-chain silicone foam formulations for biologic drug distribution networks as the most penetrable white space. Target Indian pharmaceutical contract manufacturers seeking US FDA-equivalent validation services. Pursue technical partnership models rather than capital-heavy extrusion capacity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with partial ISO 15378 qualification progress in the United States and Germany. Long-term viability hinges on regulatory compliance infrastructure rather than commodity manufacturing scale. Watch ECHA PFAS enforcement timelines as inflection indicator for fluorine-free substrate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Unlocks pharmaceutical primary packaging contracts requiring documented quality management systems. |
| Backward Integration into Foil Substrate | Reduces single-source dependency on European rolling mills for pharmaceutical-grade backing supply. |
| PFAS-Free Formulation Development | Preserves EU market access ahead of ECHA restriction enforcement timelines. |
| Technical Subscription Services Launch | Captures recurring revenue from validation support beyond transactional liner sales. |
| Cold-Chain Silicone Foam Scale-Up | Addresses unserved demand from mRNA vaccine distribution network expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with foam extrusion plant managers, pharmaceutical packaging engineers, regulatory affairs specialists at drug makers, and procurement leads at contract packagers. FDA 21 CFR guidance documents, ECHA restriction proposals, CDSCO circulars, and ISO 15378 audit registries provided compliance pathway validation. Bottom-up capacity utilization estimates triangulated against top-down end-use demand segmentation.
Reconciliation of production volume data, import-export flows, and end-use consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, application regulatory cluster, end-user procurement structure, and distribution channel type. CAGRs derived from elasticity-adjusted demand curves incorporating pharmaceutical packaging growth and food packaging replacement cycles.
Feedstock price volatility, regulatory enforcement timing, and certification audit queue delays are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in PFAS regulatory enforcement schedules or pharmaceutical closure integrity guideline amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Shrink Bands Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Foam End Caps Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
Ribbed Phenolic Caps Market
Caps and Closures
Dauber Caps Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Dropper Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
End Cap Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Crown Caps Market