
 Europe Metal Closures Market | 2026-2036
Europe Metal Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Closures Market Foresight
CE marking under the EU Machinery Directive is collapsing the supplier base for automated capping equipment and closure feeding systems, effectively filtering out uncertified entrants. Crown Holdings Incorporated leverages its integrated steel-tinplate supply chain to sustain volume leadership across Central European beverage canning lines. Silgan Holdings anchors its position through deep specialization in pharmaceutical-grade aluminum closures for Nordic and Benelux markets.
Europe metal closures are precision-formed sealing devices manufactured from aluminum, steel, tinplate, or composite laminates, typically specified to tolerances of 0.1 mm for thread engagement and hermetic integrity; they function to preserve contents against oxidation, contamination, and tampering across packaged goods supply chains. Caps and lids occupy the dominant share of value, with aluminum screw caps for wine and spirits commanding premium positioning in Italy and France, while can ends face margin compression from lightweighting mandates despite stable food-sector offtake. Steel closures for processed food tins retain mature demand profiles in Eastern Europe, whereas composite closures with integrated pour spouts are gaining traction in cosmetics and household chemical applications.
The EU Packaging and Packaging Waste Regulation, alongside REACH compliance administered by ECHA and national implementations of the F-Gas Regulation affecting coolant-dependent forming processes, collectively elevate material traceability and recyclability requirements for closure producers. EMA guidelines for pharmaceutical primary packaging further constrain design freedom, mandating extractables and leachables testing that extends qualification cycles. Stakeholders must monitor how the EU Green Deal's evolving extended producer responsibility frameworks will reshape material specifications and sourcing economics before the next regulatory consolidation phase.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles and forcing converters to requalify lighter tinplate and aluminum specifications before the next consolidation phase takes effect.
Growth Catalysts
- Aluminum Screw Cap Adoption:Premium beverage brands across France and Italy are specifying aluminum screw caps for wine and spirits, responding to consumer preference shifts toward shelf-life reliability and tamper evidence.
- REACH Compliance Traceability:ECHA-administered material traceability requirements are pulling pharmaceutical packaging toward aluminum closures with documented extractables and leachables profiles.
- Bavarian Food Canning Cluster:Concentrated food processing operations in Bavaria sustain steady procurement of steel and composite closures for processed vegetable and meat applications.
Market Restraints
- Input Cost Volatility:Aluminum and tinplate price swings compress converter margins, particularly for small-batch pharmaceutical closure orders where material hedging is uneconomical.
- CE Marking Collapse:The EU Machinery Directive's certification requirements for automated capping equipment are filtering out uncertified machinery suppliers, concentrating equipment sourcing among a narrowing base of qualified vendors.
- Plastic Closure Substitution:Polymer-based child-resistant and dispensing closures are capturing share in cosmetics and household chemical segments where metal's premium positioning cannot be justified.
Strategic Opportunities
- Poland and Romania Expansion:Underpenetrated food canning and emerging pharmaceutical packaging operations in Eastern Europe present volume growth corridors for steel and aluminum closure suppliers.
- Integrated Pour Spout Convergence:Composite closures combining metal shells with plastic pour spouts are opening cosmetic and chemical applications where controlled dispensing commands price premiums.
- EU Green Deal EPR Tailwinds:Extended producer responsibility frameworks are incentivizing recyclable aluminum designs and closed-loop material recovery systems ahead of mandated targets.
Industry Challenges
- Extractables Testing Timeline:EMA pharmaceutical primary packaging guidelines mandate extended qualification cycles for extractables and leachables testing, stretching new product introduction timelines.
- Precision Forming Skill Gap:Tolerance requirements of 0.1 mm for thread engagement and hermetic integrity are outpacing available technician training programs in Central European manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Closures Market |
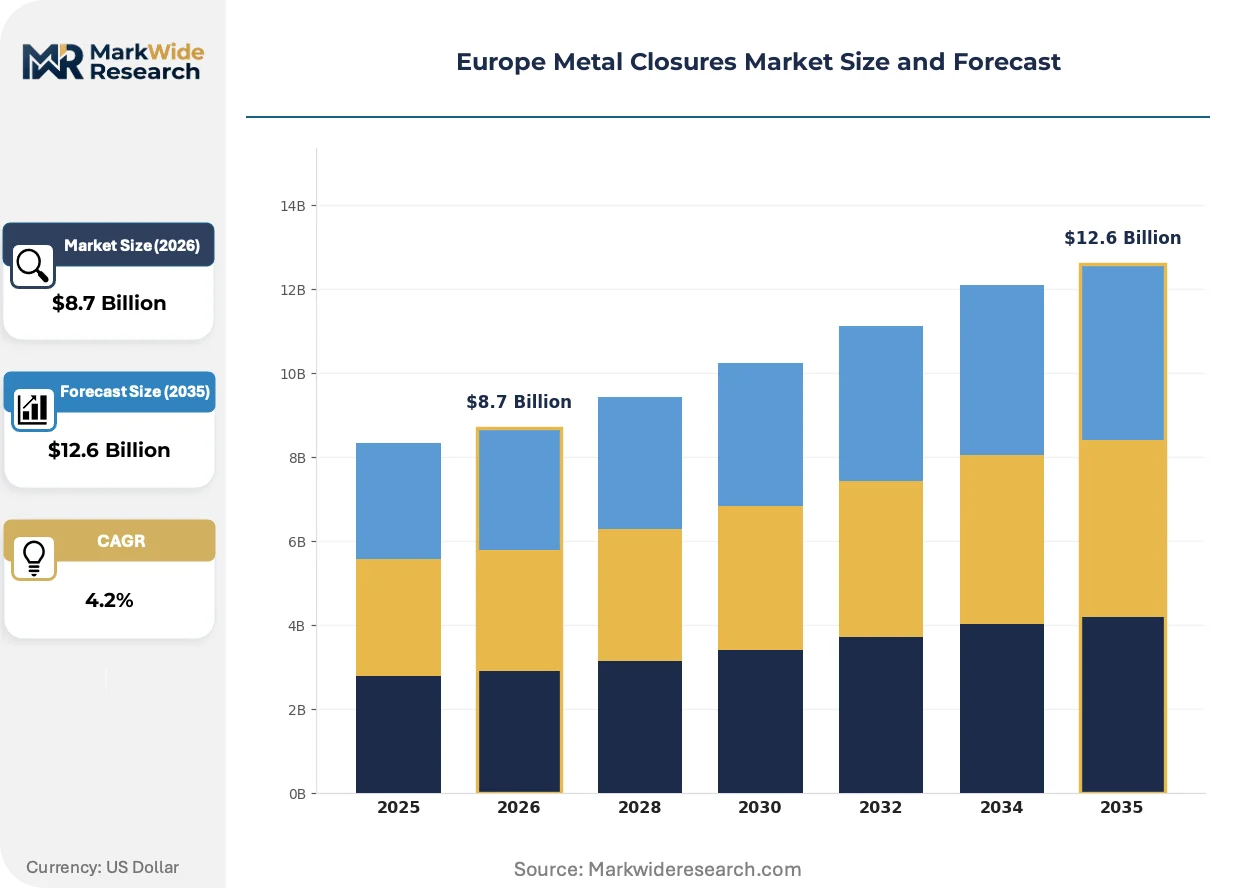
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Lids, Tins, Can Ends Material: Aluminum, Steel, Tinplate, Composite End Use Sector: Food & Beverage, Cosmetics, Pharmaceuticals, Household Closure Style: Screw Thread, Corking, Push-On, Snap-On |
| Companies Covered | Technocap Group, Pelliconi & C. SpA, Crown Holdings Incorporated, Herti JSC, CAN-PACK S.A., Silgan Holdings, Sonoco Products Company, Amcor PLC, Guala Closures Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Closures Market Shifts & Advancements
Material science advances and regulatory precision requirements are reshaping closure specifications across European beverage, pharmaceutical, and food packaging value chains.
Thread-forming aluminum alloys are miniaturizing closure profiles while maintaining hermetic seal integrity. Pharmaceutical packagers in the Nordic region are adopting these reduced-weight specifications for oral solid dose containers. The technology is miniaturizing material inputs per unit, compressing aluminum consumption rates and enabling compliance with lightweighting mandates without sacrificing barrier performance.
REACH and the EU F-Gas Regulation are tightening coolant-dependent forming process requirements. Closure producers must now document refrigerant alternatives and energy recovery systems in extrusion and deep-drawing operations. German and Austrian converters face the most acute compliance pressure, with Bavarian facilities investing in closed-loop coolant systems ahead of national implementation deadlines.
Brand procurement teams are consolidating supplier relationships around integrated closure-and-liner systems. Beverage canning operations in North Rhine-Westphalia are shifting from component sourcing to pre-assembled closure solutions that reduce line changeover downtime. This concentration is most visible among mid-cap wine and spirits bottlers in the Rhineland-Palatinate region, where technical service integration now outweighs unit price in supplier selection criteria.
Europe Metal Closures Market Segmentation
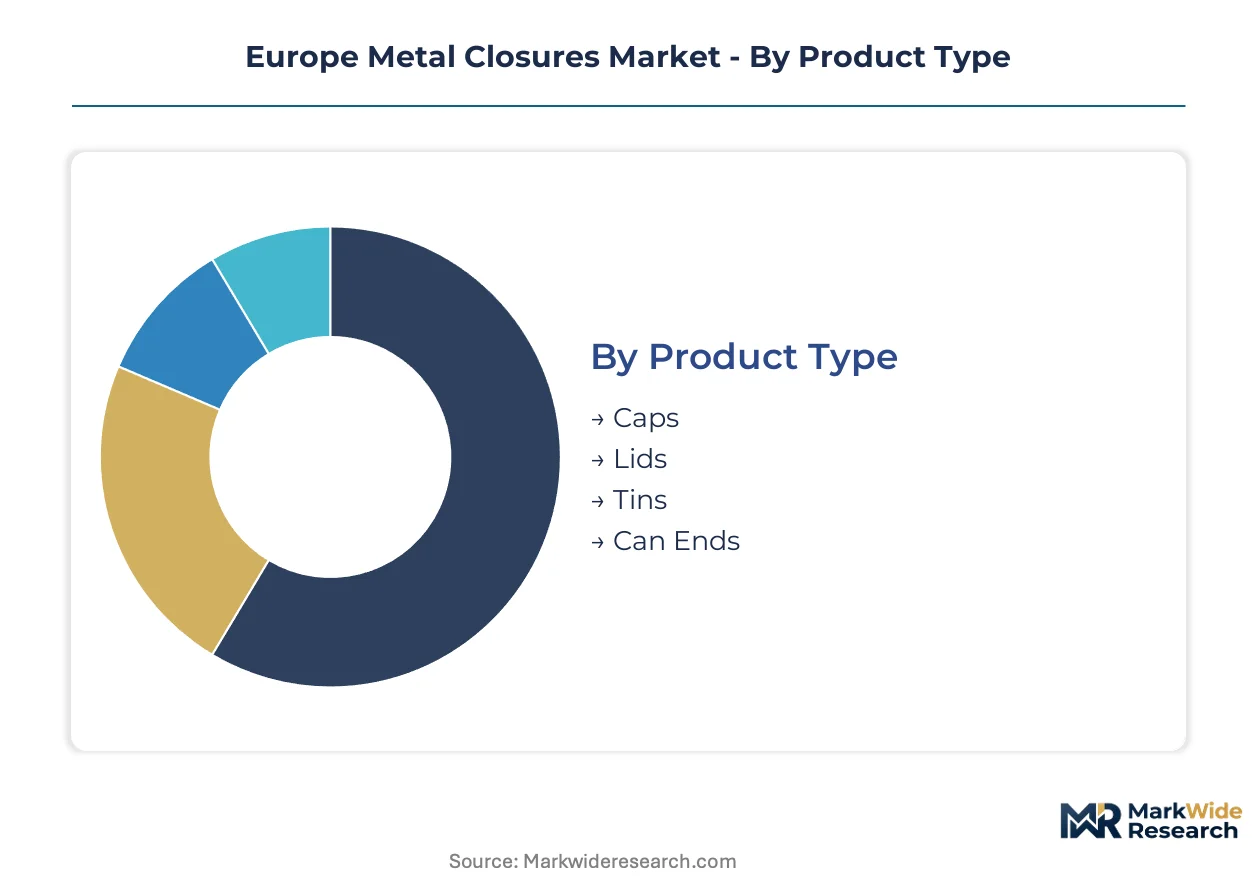
Europe Metal Closures Market segmentation reveals how regulatory pressure, material science advances, and end-use specialization fragment procurement patterns across the continent. Distinct compliance regimes for food contact materials, pharmaceutical primary packaging, and beverage sealing create tiered specification requirements that reshape supplier economics.
Product Type:
REACH and EU Packaging and Packaging Waste Regulation differentiate closure categories by recyclability mandates and material recovery targets, forcing converters to requalify specifications ahead of consolidation deadlines.
- Caps:Precision-formed aluminum and steel devices with 0.1 mm thread tolerances dominate wine and spirits applications across France and Italy. Premium beverage brands specify screw caps for shelf-life reliability and tamper evidence, compressing cork alternatives in mid-tier positioning.
- Lids:Hermetic sealing components for processed food containers face lightweighting pressure under extended producer responsibility frameworks. Bavarian food canning clusters sustain steady procurement of steel lid specifications for vegetable and meat preservation.
- Tins:Pressed steel enclosures for dry goods and specialty foods retain mature demand profiles in Eastern European markets.
- Can Ends:Beverage and food can sealing components encounter margin compression from aluminum lightweighting mandates despite stable sector offtake.
Caps handle the majority of throughput; can ends are gaining share fastest on lightweighting compliance requirements.
Material:
Cost tier differentiation separates premium recyclable aluminum from standard tinplate and economy-positioned steel specifications.
- Aluminum:Lightweight, corrosion-resistant metal specified for pharmaceutical-grade closures with documented extractables profiles. Nordic oral solid dose packagers adopt thread-forming alloys that miniaturize material inputs per unit.
- Steel:High-strength ferrous material for processed food tins and heavy-duty industrial closures. Eastern European food canning operations in Poland and Romania sustain procurement of steel specifications where cost positioning outweighs weight reduction.
- Tinplate:Steel substrate with tin coating for corrosion-resistant food contact applications facing requalification pressure.
- Composite:Metal-plastic laminates with integrated pour spouts command price premiums in cosmetics and household chemical dispensing.
Aluminum captures the steepest expansion trajectory on pharmaceutical and premium beverage specification; steel retains volume anchoring in food preservation.
End Use Sector:
Application-specific qualification timelines separate pharmaceutical packaging with EMA-mandated extractables testing from faster-cycle food and beverage procurement.
- Food & Beverage:Dominant demand concentration spanning wine screw caps in Italy, beer can ends in Germany, and processed vegetable tins across Central Europe. North Rhine-Westphalia canning lines shift toward pre-assembled closure solutions to reduce changeover downtime.
- Pharmaceuticals:Primary packaging for oral solid doses and liquid formulations requiring EMA extractables and leachables documentation. Silgan Holdings anchors supply for Nordic and Benelux markets with specialized aluminum closure production.
- Cosmetics:Controlled dispensing applications where composite closures with pour spouts displace pure metal alternatives.
- Household:Chemical and cleaning product packaging where child-resistant polymer closures compete with metal specifications.
Food and beverage handles the majority of throughput; pharmaceuticals is climbing the fastest on regulatory-driven material traceability requirements.
Closure Style:
Customer type stratification separates precision-threaded specifications for premium beverages from snap-on economy solutions for mass-market food.
- Screw Thread:Precision-machined helical engagement systems for wine, spirits, and pharmaceutical containers. Aluminum screw thread specifications command premium positioning across French and Italian beverage markets.
- Corking:Traditional sealing for wine and sparkling beverages facing displacement by screw cap alternatives.
- Push-On:Friction-fit closures for dry goods and non-pressurized containers.
- Snap-On:Engaging ring designs for convenience food and household chemical applications.
Screw thread handles the majority of throughput; snap-on is expanding most quickly on cosmetics and household chemical dispensing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is redistributing procurement patterns across European metal closure markets, with compliance timelines favoring converters in jurisdictions with established recycling infrastructure and documented material traceability systems.
Germany
Bavarian food canning operations sustain heavy demand for steel and composite closures, while North Rhine-Westphalia beverage canning lines shift toward pre-assembled closure solutions. The national implementation of extended producer responsibility frameworks under the EU Green Deal pressures converters toward lighter tinplate specifications. Stuttgart-area machinery suppliers face acute CE marking requirements for automated capping equipment.
France
Premium wine and spirits brands across Bordeaux and Champagne specify aluminum screw caps for shelf-life reliability and tamper evidence. ANSM pharmaceutical packaging guidelines align with EMA extractables testing mandates, constraining closure qualification timelines. Lyon-based cosmetics packagers adopt composite closures with integrated pour spouts for controlled dispensing applications.
Italy
Chianti and Prosecco producers expand aluminum screw cap adoption, displacing cork alternatives in mid-tier positioning. REACH compliance administered by ECHA drives material traceability investments among closure converters in Emilia-Romagna. Parma's food processing cluster maintains procurement of steel lid specifications for processed meat and dairy preservation.
Poland
Emerging pharmaceutical packaging operations in the Warsaw and Łódź regions present volume growth corridors for aluminum closure suppliers. Underpenetrated food canning infrastructure sustains demand for economy-positioned steel specifications. National alignment with EU Packaging and Packaging Waste Regulation timelines lags Western European implementation, extending design requalification windows.
Netherlands
Rotterdam's port logistics and chemical processing concentration supports composite closure manufacturing for cosmetics and household chemical applications. Benelux pharmaceutical packagers source specialized aluminum closures with documented extractables profiles. Dutch converters invest in closed-loop material recovery systems ahead of mandated EU Green Deal targets.
Europe Metal Closures Market Competitive Landscape
Player mix skews toward integrated metal packaging conglomerates with captive steel-tinplate supply chains and specialized pharmaceutical-grade closure fabricators. Market structure concentrates volume leadership among three to four vertically integrated operators with pan-European production footprints, while mid-tier specialists occupy niche pharmaceutical and premium beverage segments. Two dominant strategic archetypes emerge: scale-driven beverage canning suppliers and precision-forming pharmaceutical specialists. Competitive moves center on capacity consolidation in Eastern European growth corridors and technology licensing for thread-forming aluminum alloys.
Among the integrated packaging conglomerates, Crown Holdings Incorporated and Silgan Holdings occupy positions exemplifying scale-driven and specialization-focused archetypes respectively. Crown Holdings leverages its steel-tinplate supply chain integration across Central European beverage canning lines. Silgan Holdings anchors supply relationships for pharmaceutical-grade aluminum closures across Nordic and Benelux markets. Herti JSC and CAN-PACK S.A. represent Eastern European-based fabricators capturing volume growth in underpenetrated food canning and emerging pharmaceutical packaging operations. Guala Closures Group and Pelliconi & C. SpA exemplify premium beverage closure specialists with concentrated exposure to Italian and French wine and spirits specifications.
| Leading Market Players |
|---|
| Technocap Group |
| Pelliconi & C. SpA |
| Crown Holdings Incorporated |
| Herti JSC |
| CAN-PACK S.A. |
| Silgan Holdings |
| Sonoco Products Company |
| Amcor PLC |
| Guala Closures Group |
| Others |
Supply & Pricing Matrix
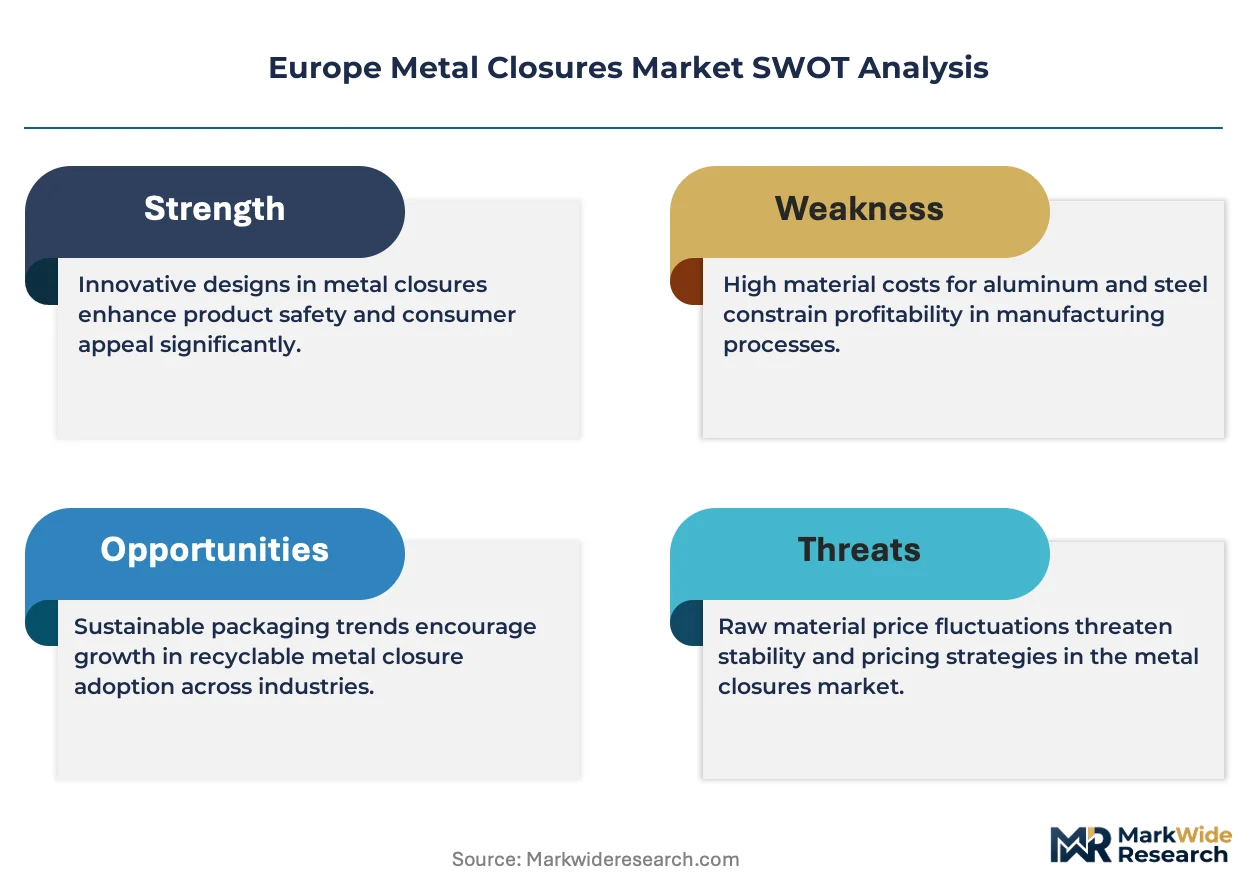
Capacity utilization rates above 85% at German tinplate rolling mills compress converter margins while anchoring price floors for beverage can ends across North Rhine-Westphalia. This scale concentration lets integrated steel suppliers dictate contract terms to mid-tier closure fabricators, who pass aluminum input volatility downstream to pharmaceutical packagers with limited hedging capacity.
Pricing Analysis
Certification level (EMA-grade vs. standard food-contact) creates the primary spread between premium pharmaceutical aluminum closures and commodity steel lids. Three-tier pricing structure across premium, standard, and economy levels reflects extractables documentation depth and thread precision tolerances. Cost compression in standard-grade tinplate is intensifying because REACH requalification cycles extend converter overhead recovery periods. Small-batch pharmaceutical orders show least price sensitivity; Eastern European food canning operations exhibit highest.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for aluminum coil imports. Raw material sourcing draws from German tinplate production, Nordic primary aluminum smelters, and Italian steel rolling capacity. Single-source vulnerability concentrates in pharmaceutical-grade aluminum alloy formulations qualified to EMA extractables standards. Distribution runs through converter-direct relationships with Bavarian food processors and Rhineland-Palatinate beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-forming technician shortages and EMA qualification bottlenecks constrain output expansion faster than capital deployment, creating durable scarcity rents for qualified European converters.
For Market Incumbents: Consolidate around captive tinplate supply and CE-certified equipment fleets to outlast margin compression from polymer substitution in cosmetics. Backward integration into aluminum coil slitting secures thread-forming alloy access against Nordic smelter allocation constraints. Target capacity maintenance in Bavaria over Eastern European expansion to preserve service density. For New Entrants and Emerging Players: Differentiate on EMA-compliant extractables documentation for Polish and Romanian pharmaceutical packaging operations still sourcing from Western European incumbents. White-space concentrates in composite closure pour-spout integration for Benelux cosmetics packagers. Go-to-market through technical service partnerships with machinery OEMs supplying automated capping lines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade closure specialists with locked EMA qualification cycles and multi-year supply agreements. Long-term viability hinges on regulatory compliance durability rather than volume scale. Acquisition targets: mid-cap fabricators with documented extractables libraries and technician training pipelines. Signal to monitor: EU Green Deal EPR implementation timelines accelerating lightweighting capex demands.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Acceleration | Compresses new product introduction timelines for Nordic oral solid dose packagers. |
| Aluminum Lightweighting Investment | Enables compliance with EU Packaging and Packaging Waste Regulation targets ahead of deadlines. |
| Closed-Loop Coolant System Deployment | Addresses F-Gas Regulation constraints for Bavarian deep-drawing operations. |
| Pre-Assembled Closure Integration | Reduces line changeover downtime for North Rhine-Westphalia beverage canning lines. |
| Eastern European Capacity Expansion | Captures volume growth in underpenetrated Polish and Romanian food canning markets. |
Research Methodology
Desk research of EU regulatory filings, ECHA substance databases, and trade association capacity surveys preceded structured interviews with closure converter plant managers, pharmaceutical packaging procurement leads, beverage brand technical directors, and machinery OEM sales engineers. Primary fieldwork across Bavaria, North Rhine-Westphalia, and Emilia-Romagna validated secondary estimates of tinplate and aluminum consumption patterns. Bottom-up facility capacity tallies triangulated against top-down end-use demand segmentation.
Variance decomposition across material cost pass-through, regulatory compliance lag effects, and substitution elasticity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use sector, closure style, and regional regulatory cluster. CAGRs derived from installed capacity growth rates, EMA qualification pipeline visibility, and lightweighting mandate compliance schedules. Industry-specific inputs encompassed aluminum LME forward curves and pharmaceutical packaging capex intentions.
Material uncertainties — aluminum price volatility, EPR implementation delays, polymer substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and technician training pipeline recovery. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Metal Containers Market
Metal Packaging
Aluminum Foil Packaging Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
Brass Foils Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
North America Metal Packaging Market