
 Drop Sealers Market | 2026-2036
Drop Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Drop Sealers Market Foresight
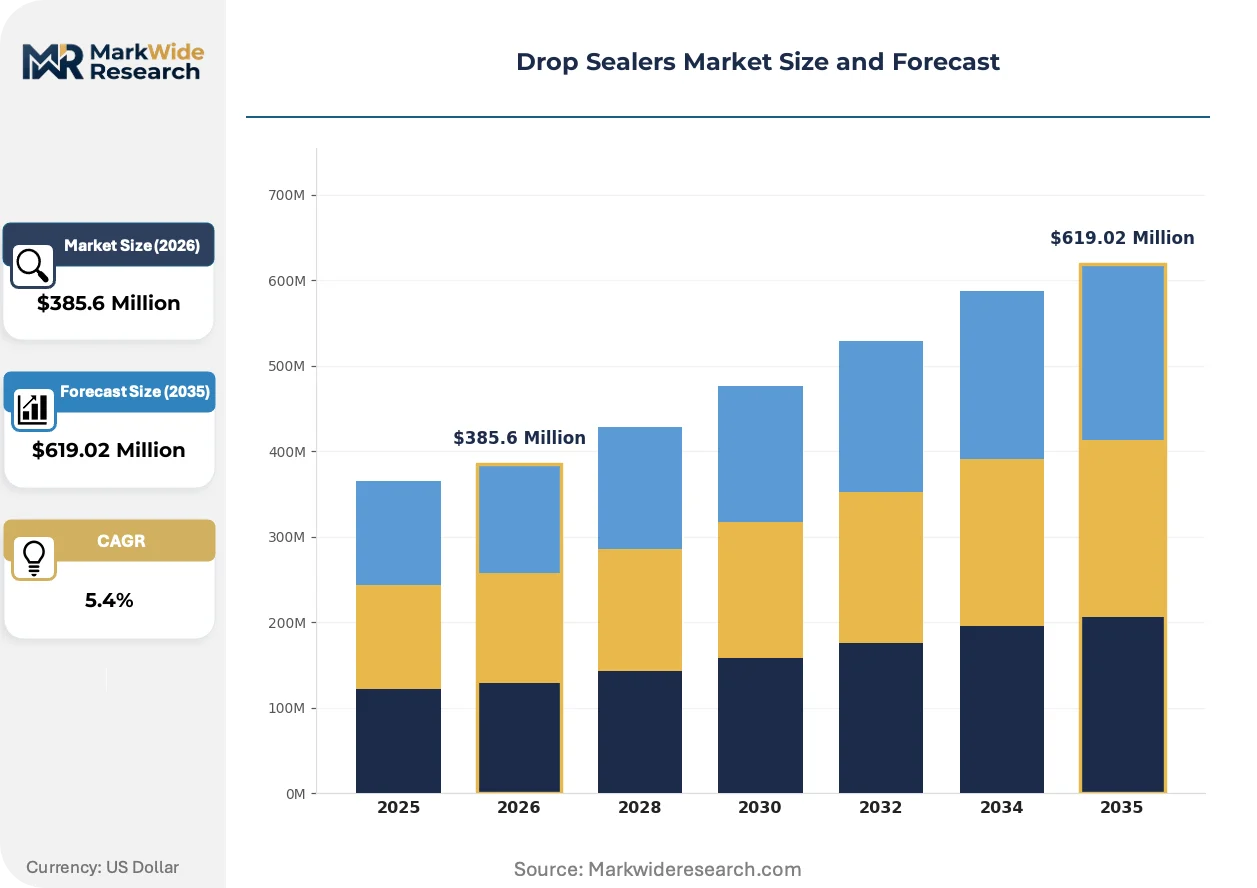
REACH compliance is hardening material certification requirements for European drop sealer suppliers. PAC Machinery leverages its vacuum technology portfolio to sustain North American pharmaceutical contracts. MULTIVAC Group anchors European market presence through in-house thermal sealing R&D.
Drop sealers are mechanical devices that apply controlled heat, pressure, or ultrasonic energy to bond thermoplastic films, foils, or coated papers, typically achieving seal widths of 2–10 mm at temperatures between 120°C and 200°C depending on substrate composition; their primary purpose is to create hermetic closures that prevent contamination, extend shelf life, and maintain sterility in packaged goods. Automated sealers now lead capital expenditure flows among food processing end users seeking throughput above 60 units per minute, while ultrasonic technology represents the fastest-expanding segment as manufacturers replace thermal methods to eliminate particulate generation in cleanroom pharmaceutical environments. Electric sealers occupy the mature volume tier, serving small-batch operations where pneumatic infrastructure remains uneconomical.
FDA 21 CFR Part 11 and EU MDR shape validation documentation burdens for pharmaceutical sealers sold into regulated markets, while OSHA lockout/tagout standards govern maintenance access design for automated equipment deployed in US manufacturing facilities. Stakeholders must weigh ultrasonic conversion costs against thermal equipment retrofit paths as substrate portfolios diversify.
Market Dynamics
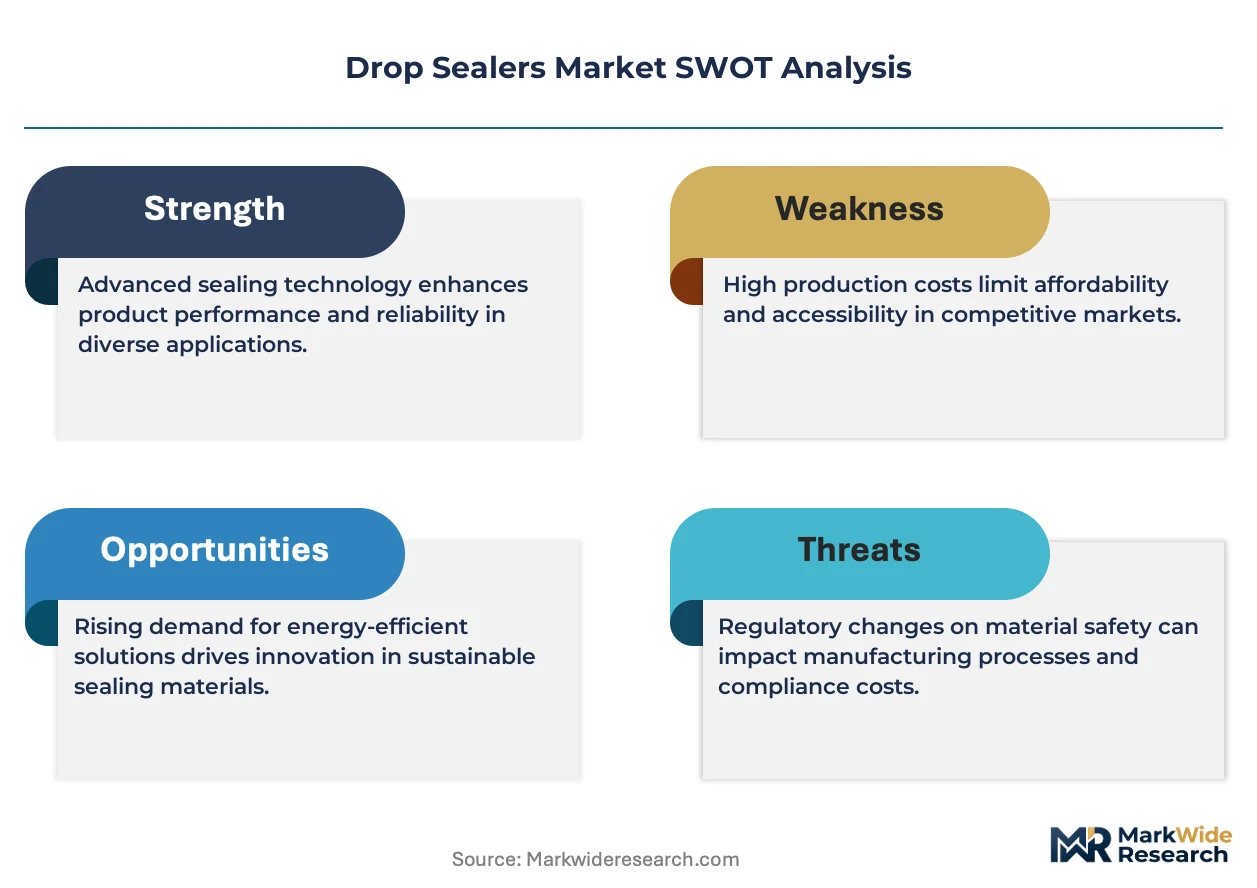
Ultrasonic sealing technology is absorbing capital flows from thermal equipment as pharmaceutical cleanroom standards harden substrate compatibility requirements across automated packaging lines.
Growth Catalysts
- EU MDR traceability mandates:German pharmaceutical manufacturers are expanding automated sealer procurement to comply with serialization and verification requirements for medical device packaging.
- Food safety protocols:North American food processing plants are prioritizing thermal technology sealers in equipment budgets to achieve hermetic closures that extend shelf life for perishable goods.
- REACH compliance hardening:ECHA material certification requirements are forcing European suppliers to validate thermoplastic film substrates for chemical safety, creating replacement demand for certified equipment.
Market Restraints
- Stainless steel and precision alloy volatility:Input cost swings for sealer frame materials compress margin predictability for mid-tier equipment manufacturers.
- Ultrasonic transducer supply concentration:Piezoelectric component sourcing clusters in East Asian manufacturing zones, exposing buyers to single-region disruption risk.
- Thermal particulate generation limits:Cleanroom pharmaceutical applications face technical barriers where heated sealing produces contamination unacceptable to FDA sterility guidelines.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO regulatory alignment with international standards is creating demand for validated sealing equipment in emerging formulation clusters.
- Ultrasonic-thermal hybrid systems:Convergence of energy modalities enables substrate flexibility for contract packagers serving diversified client portfolios.
- OSHA lockout/tagout retrofit services:Maintenance access redesign for existing automated equipment represents recurring revenue streams in US manufacturing facilities.
Industry Challenges
- FDA 21 CFR Part 11 validation documentation:Pharmaceutical sealers require extensive electronic record compliance, extending sales-to-commissioning timelines and consuming technical support capacity.
- Legacy pneumatic infrastructure incompatibility:Small-batch operations face integration complexity when upgrading to electric sealers without compressed air system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drop Sealers Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Sealers, Manual Sealers, Pneumatic Sealers, Automated Sealers End User: Food Processing, Pharmaceuticals, Packaging Industry, E-commerce Application: Sealing, Packaging, Curing, Inspection Technology: Thermal Technology, Ultrasonic Technology, Vacuum Technology, Laser Technology |
| Companies Covered | PAC Machinery, Inpak Systems, SIGMA Equipment, Promarksvac Corp., SencorpWhite, Technopack Corporation, MULTIVAC Group, Sealer Sales, ULMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drop Sealers Market Shifts & Advancements
Equipment functionality is fragmenting along cleanroom-versus-industrial fault lines as substrate portfolios diversify and regulatory documentation burdens intensify.
Ultrasonic sealing is absorbing market positioning previously held by thermal alternatives in pharmaceutical environments. Cleanroom operators at sterile fill-finish facilities are adopting piezoelectric bonding to eliminate particulate generation from heated tooling. The technology is absorbing premium pricing power as FDA inspectors flag thermal seal integrity in aseptic processing audits.
REACH substance restrictions are reshaping material validation protocols for European suppliers. ECHA candidate list expansions now cover plasticizers and stabilizers common in flexible packaging films. Thermal sealer manufacturers serving German and French pharmaceutical markets are reformulating heating element coatings to maintain compliance.
Service contract unbundling is altering buyer-supplier relationships in North American food processing. Plant operators are separating equipment purchase from validation support and spare parts provisioning, treating sealing lines as modular capital assets. This pattern concentrates most visibly in California and Illinois dairy packaging facilities where throughput requirements exceed 60 units per minute.
Drop Sealers Market Segmentation
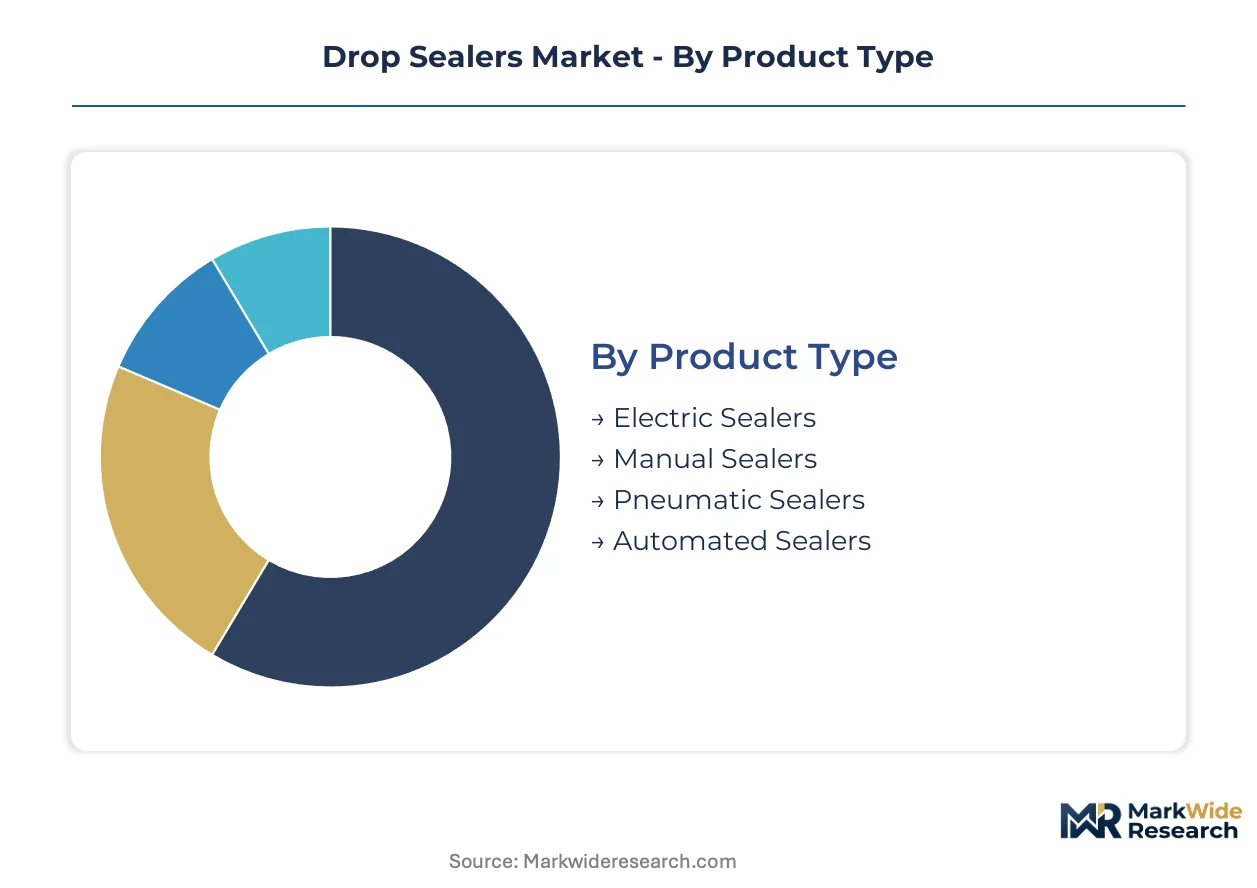
Drop sealer procurement cycles diverge sharply between capital-intensive automated lines and maintenance-driven manual equipment replacements. Pharmaceutical serialization mandates and food safety protocol upgrades are compressing replacement timelines across multiple technology tiers.
Product Type:
Upgrade cycles for automated equipment now run 18-24 months shorter than legacy pneumatic infrastructure as throughput requirements harden.
- Automated Sealers:Programmable logic-controlled systems achieve line speeds exceeding 60 units per minute with integrated vision inspection. German pharmaceutical manufacturers facing EU MDR traceability mandates are prioritizing these systems for medical device packaging lines.
- Electric Sealers:Servo-driven heating elements deliver precision temperature control between 120°C and 200°C without compressed air dependency. Small-batch operations in California dairy packaging facilities favor these units where pneumatic infrastructure remains uneconomical.
- Manual Sealers:Hand-operated impulse units serve prototype development and specialty packaging runs with seal widths of 2-10 mm.
- Pneumatic Sealers:Air-actuated systems dominate legacy installations in high-volume food processing plants with existing compressor infrastructure.
Automated sealers sit at the top of the volume ranking, with electric sealers climbing the fastest as pneumatic retrofit costs deter greenfield investments.
End User:
Regulatory documentation burdens fragment procurement priorities between sterile pharmaceutical environments and industrial food processing.
- Pharmaceuticals:Aseptic fill-finish facilities require FDA 21 CFR Part 11 validation documentation for electronic record compliance. Cleanroom operators are absorbing ultrasonic technology to eliminate particulate generation from heated tooling in sterile packaging zones.
- Food Processing:North American plants prioritize thermal technology sealers for hermetic closures extending perishable shelf life. Illinois and California dairy facilities exceeding 60 units per minute are unbundling equipment purchase from validation support contracts.
- Packaging Industry:Contract packagers serving diversified client portfolios demand substrate flexibility across thermal and ultrasonic modalities.
- E-commerce:Fulfillment centers require rapid-changeover sealing equipment for variable carton dimensions and mixed product flows.
Food processing commands the largest installed base, though pharmaceuticals are expanding most quickly as serialization mandates harden equipment specifications.
Application:
Functional requirements stratify between primary closure creation and downstream quality verification processes.
- Sealing:Core bonding function applying controlled heat, pressure, or ultrasonic energy to thermoplastic films, foils, and coated papers. Pharmaceutical cleanroom standards are displacing thermal methods with piezoelectric bonding to satisfy FDA sterility guidelines.
- Packaging:Integrated line operations combining sealing with forming, filling, and labeling functions. E-commerce fulfillment centers prioritize rapid-changeover configurations for variable throughput demands.
- Curing:Post-seal thermal treatment for adhesive activation and structural integrity in multi-layer barrier films.
- Inspection:Vision-system verification of seal integrity, width consistency, and contamination detection. EU MDR traceability requirements are mandating integrated inspection modules for medical device packaging.
Sealing functions retain the dominant equipment allocation, with inspection modules gaining share fastest as regulatory documentation burdens intensify.
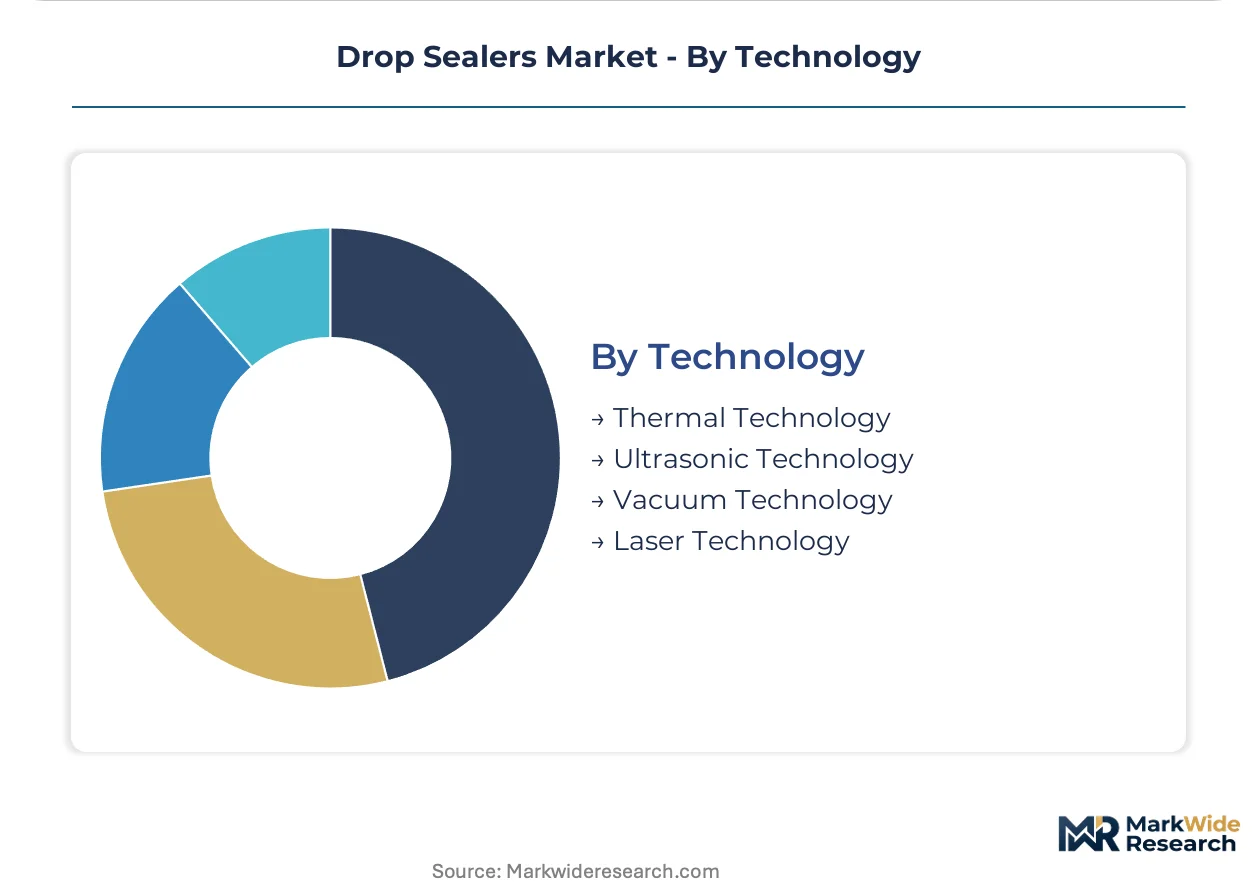
Technology:
Energy modality selection increasingly determines substrate compatibility and cleanroom qualification pathways.
- Ultrasonic Technology:Piezoelectric transducers generate high-frequency mechanical vibration for molecular bonding without thermal particulate generation. FDA inspectors flagging thermal seal integrity in aseptic processing audits are accelerating adoption at sterile fill-finish facilities.
- Thermal Technology:Resistive heating elements bonding thermoplastic substrates at 120°C-200°C dominate North American food processing budgets. REACH substance restrictions are forcing reformulation of heating element coatings for European pharmaceutical markets.
- Vacuum Technology:Atmospheric extraction prior to sealing extends shelf life for oxygen-sensitive pharmaceutical and food products.
- Laser Technology:Focused beam welding for precision micro-sealing applications in medical device and electronics packaging.
Thermal technology maintains the broadest installed base, with ultrasonic systems expanding most quickly as cleanroom standards harden across pharmaceutical manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent and North American food processing expertise anchor regional demand concentration for drop sealing equipment. Pharmaceutical serialization mandates and cleanroom qualification requirements are redistributing procurement volumes across manufacturing clusters.
United States
OSHA lockout/tagout standards govern maintenance access redesign for automated equipment in Illinois and California dairy facilities. FDA 21 CFR Part 11 validation documentation extends sales-to-commissioning timelines for pharmaceutical sealers serving aseptic fill-finish operations. Chicago-area contract packagers are unbundling equipment purchase from validation support contracts.
Germany
EU MDR traceability mandates are compressing replacement timelines for medical device packaging lines. ECHA REACH substance restrictions force reformulation of heating element coatings for thermoplastic film compatibility. Bavarian pharmaceutical manufacturers are expanding automated sealer procurement to comply with serialization requirements.
India
CDSCO regulatory alignment with international standards is creating demand for validated sealing equipment in emerging formulation clusters. FSSAI food safety protocols prioritize hermetic closure systems for perishable goods distribution. Maharashtra and Gujarat pharmaceutical packaging facilities are upgrading thermal infrastructure to meet export compliance standards.
Japan
METI industrial standards shape precision equipment specifications for electronics and medical device packaging applications. PMDA pharmaceutical manufacturing guidelines enforce sterility maintenance in cleanroom sealing operations. Osaka-area precision machinery clusters are integrating ultrasonic technology to eliminate particulate generation.
China
NMPA pharmaceutical packaging regulations mandate traceability systems for domestic and export-bound medical products. SAMR standardization initiatives accelerate equipment certification for food processing applications. Yangtze River Delta manufacturing zones are absorbing vacuum sealing technology for oxygen-sensitive pharmaceutical products.
Drop Sealers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the drop sealers market. The vendor base stratifies between thermal equipment incumbents with broad food processing exposure and ultrasonic technology entrants targeting pharmaceutical cleanroom applications. Three archetypes dominate: diversified packaging machinery conglomerates, specialized sealing technology pure-plays, and regional fabrication houses serving maintenance-driven replacement cycles. Competitive moves concentrate on M&A for technology portfolio expansion and strategic partnerships for regulatory validation support capacity.
Within the diversified machinery tier, MULTIVAC Group and ULMA Group exemplify European conglomerates with in-house thermal sealing R&D capabilities. PAC Machinery occupies a position among North American specialists leveraging vacuum technology portfolios. SencorpWhite represents the mid-scale fabrication archetype serving regional food processing and industrial packaging demand. These anchors illustrate the geographic and technological fault lines structuring competitive positioning.
| Leading Market Players |
|---|
| PAC Machinery |
| Inpak Systems |
| SIGMA Equipment |
| Promarksvac Corp. |
| SencorpWhite |
| Technopack Corporation |
| MULTIVAC Group |
| Sealer Sales |
| ULMA Group |
| Others |
Supply & Pricing Matrix
German pharmaceutical OEMs concentrating automated sealer procurement under EU MDR mandates operate on bundled equipment-validation-service contracts that concentrate pricing power with thermal technology incumbents.
Pricing Analysis
Equipment-validation unbundling now separates hardware purchase from FDA 21 CFR Part 11 documentation support and spare parts provisioning across North American food processing plants. Three-tier pricing structure across premium certified, standard industrial, and economy manual tiers differentiates by validation depth and throughput capability. Pricing pressure stems from stainless steel input volatility compressing margin predictability for mid-tier manufacturers. Small-batch operations in California dairy facilities exhibit highest price sensitivity due to pneumatic retrofit avoidance, while aseptic pharmaceutical cleanrooms absorb premium ultrasonic systems with minimal negotiation leverage.
Supply Chain Analysis
Domestic-content requirements in India's PLI scheme for pharmaceutical machinery are redirecting component sourcing toward Maharashtra and Gujarat fabrication clusters. Piezoelectric transducer supply concentrates in East Asian manufacturing zones, while precision alloy frame materials draw from German and Japanese specialty steel producers. Single-region disruption risk in ultrasonic component sourcing exposes buyers to tariff exposure and logistics chokepoints. Distribution runs through OEM-direct channels for automated lines and regional distributor networks for manual replacement equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR traceability mandates and FDA sterility guidelines continuously refresh equipment replacement cycles across pharmaceutical manufacturing.
For Market Incumbents: Anchor thermal technology market share through in-house heating element coating reformulation for REACH compliance. Defend against ultrasonic displacement by certifying hybrid thermal-ultrasonic systems for contract packagers serving diversified substrate portfolios. Vertical integration into precision alloy frame production mitigates stainless steel volatility exposure.
For New Entrants and Emerging Players: Contract packaging service providers represent the most accessible channel partner type for ultrasonic technology penetration. Target Indian pharmaceutical packaging clusters where CDSCO regulatory alignment creates validation-equipment demand without entrenched incumbent relationships. Lead with substrate-flexibility messaging against thermal-only legacy installations.
For Investors and Strategic Acquirers: Diversified packaging machinery conglomerates are the most active acquirer in this space, seeking ultrasonic technology portfolios to complement thermal R&D capabilities. Acquisition targets with FDA 21 CFR Part 11 validation documentation capacity command premium positioning. Watch for ultrasonic transducer supply consolidation as inflection signal for technology access pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Technology Acquisition | piezoelectric bonding capability eliminates particulate generation in FDA-audited cleanrooms. |
| REACH-Compliant Coating Development | Reformulated heating elements maintain ECHA certification for German pharmaceutical markets. |
| Validation Documentation Unbundling | Modular service contracts align with California dairy facility capital asset treatment. |
| Indian Manufacturing Footprint Expansion | Maharashtra and Gujarat proximity captures CDSCO-aligned pharmaceutical packaging demand. |
| Hybrid System Platform Launch | Thermal-ultrasonic convergence serves contract packagers with diversified client portfolios. |
Research Methodology
Multiple input streams — plant engineer interviews, OEM procurement director consultations, regulatory affairs specialist surveys, and aftermarket service head discussions — were reconciled against FDA 510(k) filings, EMA device registrations, SEC equipment manufacturer disclosures, and customs trade data for precision alloy and piezoelectric component flows. Bottom-up equipment shipment analysis and top-down pharmaceutical packaging capital expenditure estimates were triangulated for cross-validation.
Historical thermal-to-ultrasonic technology transition patterns were cross-referenced against expert panel assessments of cleanroom qualification timelines across the projection horizon. Segmentation dimensions modeled include automation tier, energy modality, end-use vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression analysis and substrate diversification trajectory assessment, incorporating EU MDR implementation pace and REACH substance restriction expansion as pharmaceutical-specific forecast inputs.
Revisions become necessary when ultrasonic transducer supply disruptions, stainless steel price volatility spikes, or regulatory timeline accelerations materialize beyond modeled assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Cap Liner Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Crown Caps Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Box Latch Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Laminated Tube Closure Market