
 Benelux Plastic Caps and Closures Market | 2026-2036
Benelux Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Benelux Plastic Caps and Closures Market Insights
Belgium's Flanders region is reshaping regional supply dynamics through expanded injection-molding capacity for beverage closures. Berry Global Inc sustains broad polymer conversion capabilities across multiple end-use categories. Bericap Holding GmbH dominates tethered-cap technology for carbonated soft drinks. Kornelis Caps & Closures specializes in precision dispensing closures for pharmaceutical applications.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically manufactured from polypropylene or high-density polyethylene, designed to seal, protect, and enable controlled access to packaged contents across liquid and semi-solid products. The Food & Beverage end-user segment anchors volume demand through high-frequency replenishment cycles and stringent hygiene requirements. Flip Top and Tamper Evident product types command premium positioning in on-the-go consumption and regulated pharmaceutical channels respectively. Polypropylene material grade leads formulation share due to chemical resistance and reclosability performance.
REACH compliance through ECHA and the EU Single-Use Plastics Directive govern material composition, recyclability mandates, and tethered-cap requirements across Benelux manufacturing. CE marking protocols and national packaging decrees in Belgium, the Netherlands, and Luxembourg further standardize product safety and environmental accountability. Stakeholders must monitor recycled-content quota escalations and mechanical recycling infrastructure readiness to secure long-term formulation flexibility and market access.
Market Dynamics
The EU Single-Use Plastics Directive is collapsing legacy closure designs across Benelux converting operations, forcing simultaneous retooling for tethered-cap mandates and recycled-content minimums while beverage bottlers accelerate order volumes for compliant formats.
Growth Catalysts
- Tethered-cap mandates:The EU Single-Use Plastics Directive requires attached caps on single-use beverage containers by 2024. Belgian and Dutch converters are expanding injection-molding lines to meet this specification.
- Randstad logistics density:The Netherlands' concentrated distribution corridor enables just-in-time delivery to European beverage and pharmaceutical packagers. Closure suppliers co-locate molding operations near Rotterdam-Antwerp port complexes.
- Pharmaceutical dispensing precision:High-barrier oncology and biologic formulations demand child-resistant and metered-dose closures. Dutch and Belgian converters capture this specification-driven replacement cycle.
Market Restraints
- Recycled resin supply scarcity:Food-grade rPP and rHDPE availability lags behind EU-mandated quotas. Benelux converters face formulation constraints and price volatility for compliant feedstock.
- Mold fabrication bottlenecks:Precision multi-cavity tooling for tethered-cap geometries requires extended lead times from specialized German and Italian suppliers. Capacity reservation delays project timelines.
- Substitution by aluminum:Premium beverage brands trial crown corks and screw-thread aluminum closures for perceived sustainability positioning. This threatens volume in carbonated soft drink segments.
Strategic Opportunities
- Luxembourg pharmaceutical growth:The Grand Duchy's expanding generics and biosimilar manufacturing base lacks indigenous closure supply. Belgian and Dutch molders can capture this adjacent geography.
- Mono-material flexible packaging convergence:PE-based pouches with integrated dispensing fitments are displacing rigid bottles in personal care. Closure suppliers can extend molding expertise into film-lamination partnerships.
- Digital watermarking integration:AIM-Digimarc and similar traceability standards enable automated sorting of post-consumer closures. Early adoption supports premium positioning for EPR-compliant brands.
Industry Challenges
- Multi-cavity mold commissioning:Tethered-cap geometries require complex hot-runner systems with synchronized ejection. Belgian toolrooms report 20-30 week lead times for validated production molds.
- Food-contact notification timelines:EFSA novel food contact material approvals for recycled-content resins extend 18-24 months. Formulation lock-in risks obsolescence against evolving mechanical recycling outputs.
- Legacy line integration:Compression-molding equipment predating 2018 lacks servo-precision for thin-wall tethered designs. Dutch converters face capital decisions on retrofit versus replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benelux Plastic Caps and Closures Market |
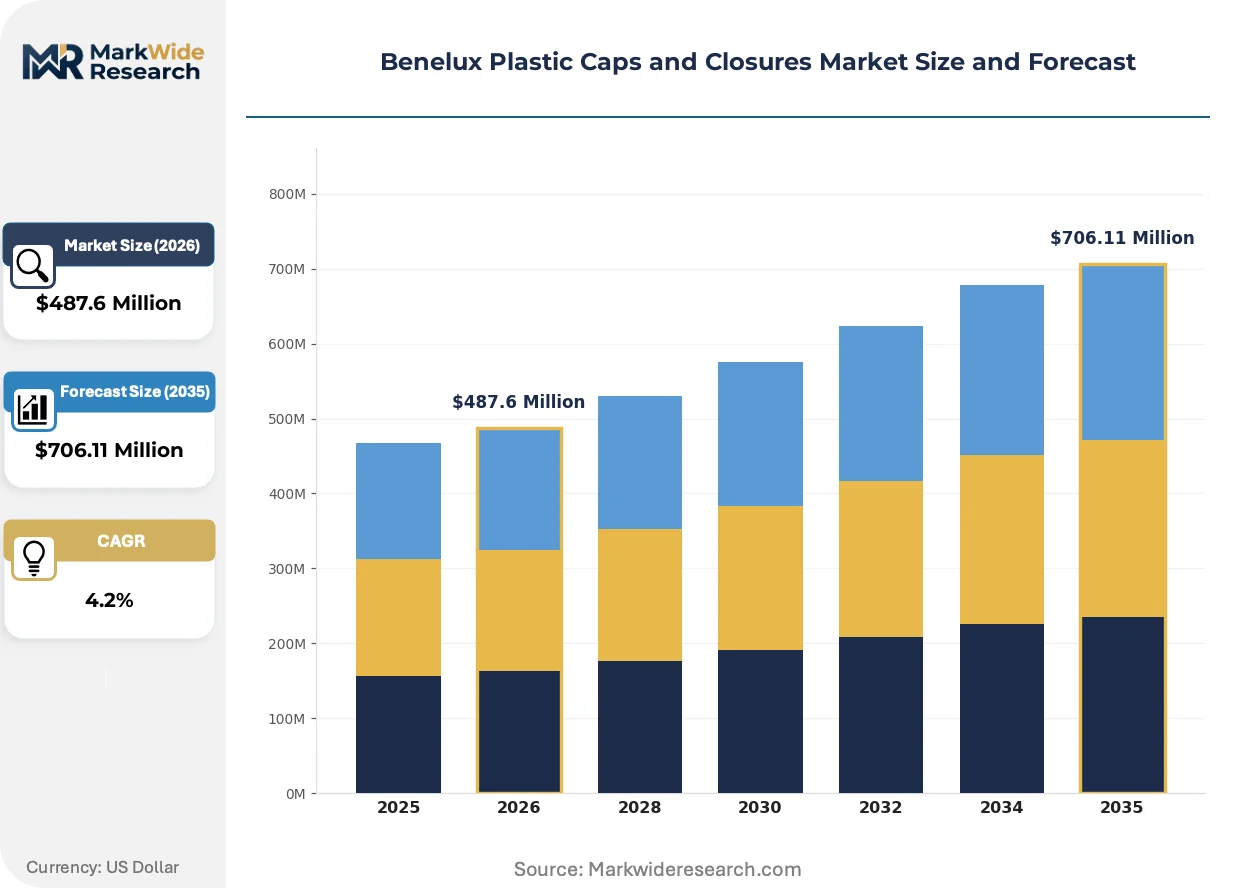
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $706.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Spray, Tamper Evident, Push-Pull Material: PP, HDPE, PET, PVC End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Closure Design: Child-Resistant, Dispensing, Screw Cap, Snap Fit |
| Companies Covered | Amcor Group GmbH, Bericap Holding GmbH, Berry Global Inc, Protective Industries Inc, Eurocap & Eurocork, Berlin Packaging Netherlands, Keizer International BV, Kornelis Caps & Closures, Closure Systems International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benelux Plastic Caps and Closures Market Trends and Innovations
Active material science and digital traceability are compressing product development cycles across Benelux closure manufacturing. Three concurrent shifts are redefining competitive capability requirements.
Lightweighting through finite-element topology optimization is collapsing material usage norms in beverage closure design. Berry Global and Bericap deploy simulation-driven rib structures that maintain torque retention with 15-20% reduced polypropylene mass. Belgian bottlers validate these designs through accelerated shelf-life testing. The technology is collapsing historical gram-weight specifications that governed mold cavitation economics.
REACH Article 33 disclosure obligations and the EU Packaging and Packaging Waste Regulation are tightening substance transparency across Benelux supply chains. ECHA SCIP database requirements force converters to document SVHC presence in colorants and slip agents. Pharmaceutical and personal care brands now audit closure suppliers for full material disclosure. Dutch converters are responding by consolidating additive portfolios to reduce compliance complexity.
Belgian beverage distributors are consolidating procurement through cooperative purchasing platforms that aggregate volume across mid-tier bottlers. This concentration is displacing bilateral supplier relationships that dominated the 2015-2020 period. Tier-two converters face margin compression as these platforms standardize specifications and compress negotiation cycles. The shift is most visible in Flanders' independent mineral water and craft brewing segments.
Benelux Plastic Caps and Closures Market Segmentation
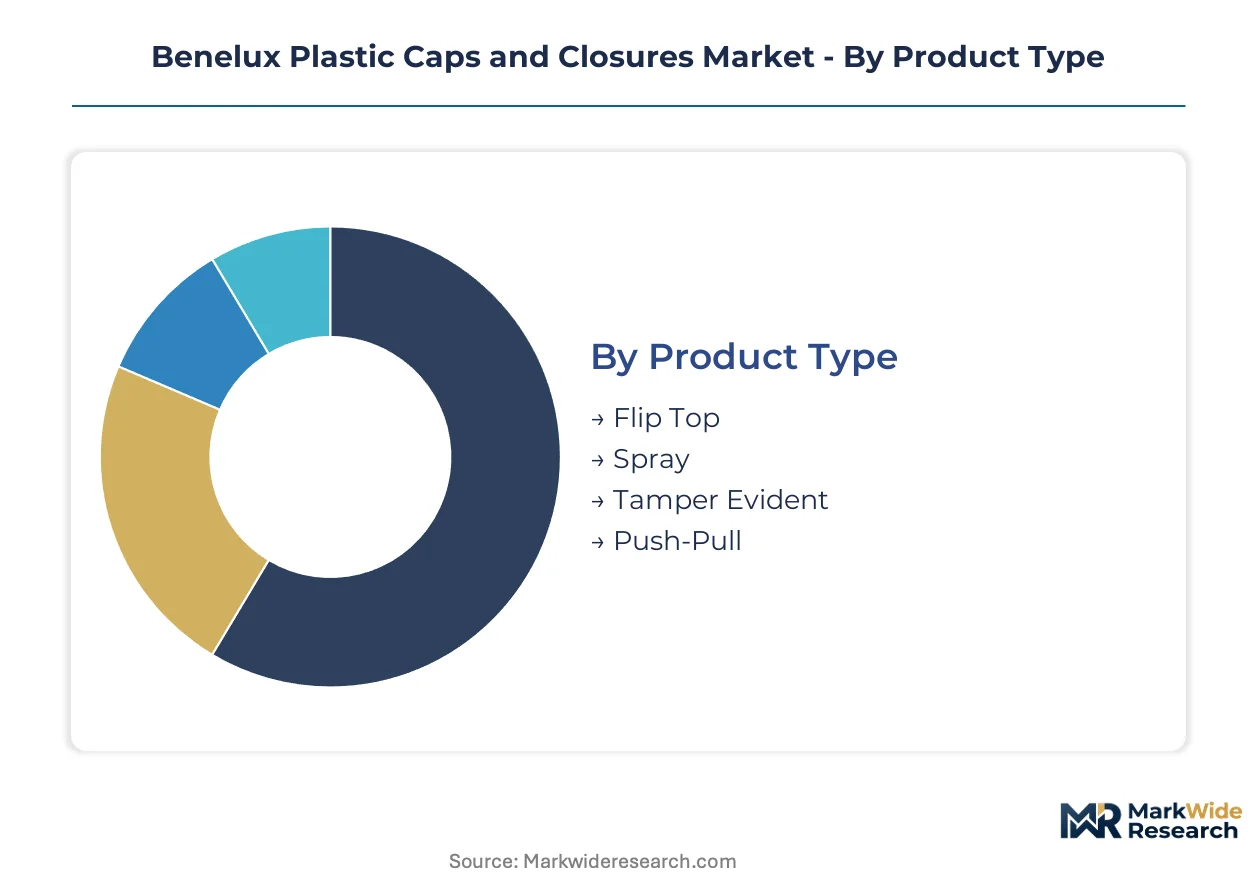
Segmentation in Benelux plastic caps and closures reveals how regulatory mandates and end-use specifications fragment manufacturing requirements. Each dimension carries distinct tooling, material, and compliance obligations that reshape converter specialization.
Product Type:
Mature formats dominate beverage volume while tethered-cap mandates accelerate design turnover across emerging specifications.
- Flip Top:Hinged polypropylene constructions enable single-handed dispensing for on-the-go consumption. Dutch converters supply Randstad corridor beverage packagers facing EU Single-Use Plastics Directive tethered-cap deadlines. Flip Top retains volume leadership; Tamper Evident holds the steepest expansion curve.
- Spray:Precision-molded actuator mechanisms with dip tube interfaces serve personal care and household chemical applications. Belgian molders near Antwerp port clusters capture aerosol replacement cycles for European cosmetic brands.
- Tamper Evident:Ring-break or membrane-seal designs provide visible breach indication for pharmaceutical and high-value food channels. Flanders injection-molding capacity expansions target this specification.
- Push-Pull:Two-stage valve mechanisms suit sports nutrition and functional beverages. Dutch converters report growing order volumes from Belgian protein drink bottlers.
Flip Top commands the largest production runs; Tamper Evident is climbing the fastest on regulatory tailwinds.
Material:
Cost tier stratification separates commodity resins from specialized grades facing recycled-content quota pressure.
- PP:Polypropylene delivers chemical resistance and fatigue performance for reclosable beverage applications. Belgian converters prioritize PP for tethered-cap compliance given its hinge-flex durability.
- HDPE:High-density polyethylene offers stiffness and stress-crack resistance for pharmaceutical and household chemical closures. Dutch molders face feedstock scarcity as EU recycled-content mandates escalate.
- PET:Polyester closures serve carbonated beverage applications requiring CO2 barrier performance. Limited penetration in Benelux due to compatibility constraints with standard bottlenecks.
- PVC:Polyvinyl chloride persists in specific pharmaceutical blister-lid applications despite REACH scrutiny. Belgian converters report declining order volumes as ECHA substance restrictions tighten.
PP dominates formulation share; HDPE faces the steepest supply-side constraints from mechanical recycling infrastructure gaps.
End User:
Application intensity varies sharply across replenishment frequency and regulatory burden.
- Food & Beverage:High-velocity replenishment cycles and hygiene mandates anchor volume demand. Belgian mineral water and craft brewing segments consolidate procurement through cooperative platforms.
- Pharmaceuticals:Child-resistant and metered-dose specifications drive precision molding requirements. Luxembourg's expanding generics manufacturing lacks indigenous closure supply.
- Personal Care:Aesthetic differentiation and dispensing functionality command premium positioning. Dutch converters supply Rotterdam-port cosmetic packagers.
- Household Products:Chemical resistance and cost efficiency govern specification. Belgian molders serve cleaning product distributors across Flanders logistics hubs.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest expansion curve on biosimilar manufacturing growth.
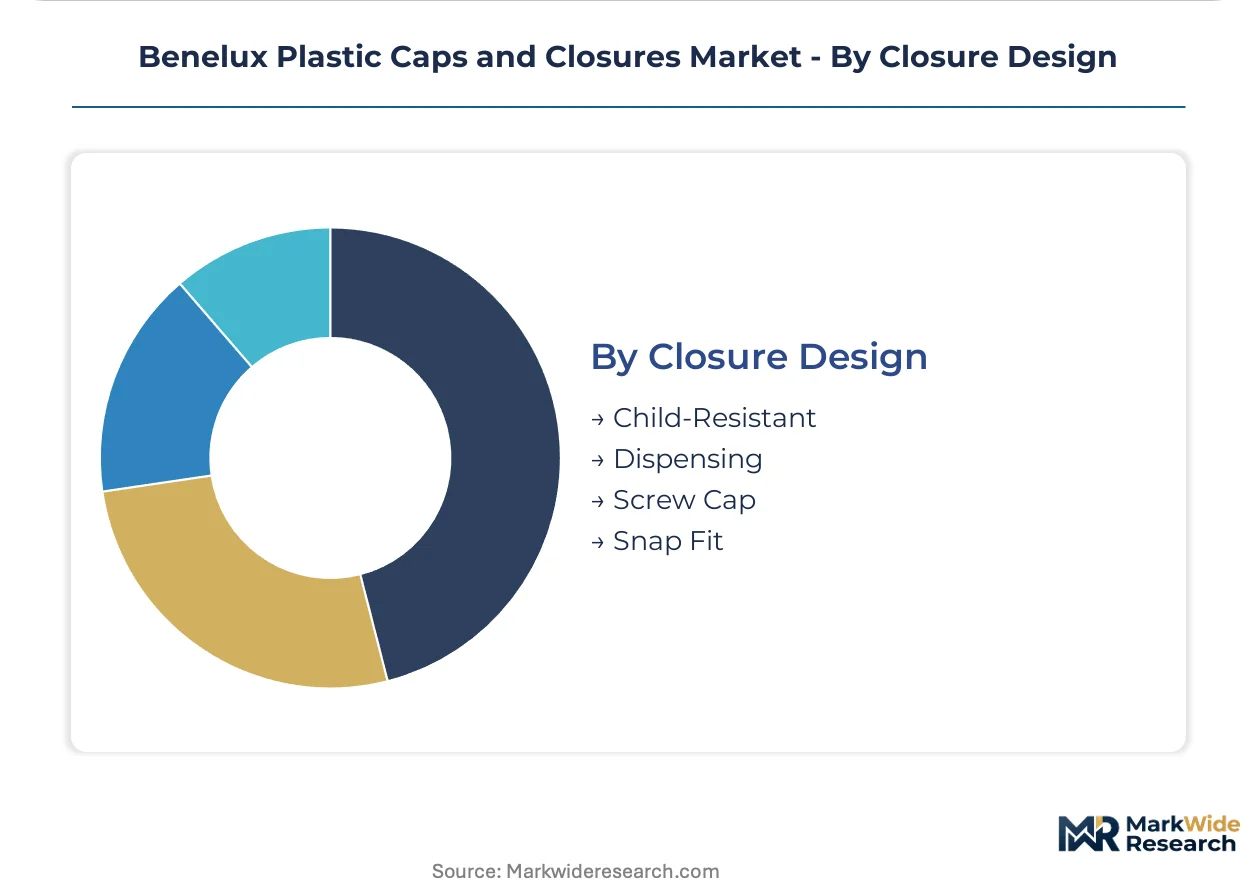
Closure Design:
Margin tier separation distinguishes commoditized screw formats from specialized safety and dispensing systems.
- Child-Resistant:Dual-action or squeeze-and-turn mechanisms prevent pediatric access to hazardous contents. Dutch converters capture oncology and biologic formulation demand.
- Dispensing:Metered-dose or precision-orifice designs enable controlled substance release. Belgian molders specialize in pharmaceutical applications.
- Screw Cap:Threaded closure systems dominate beverage and food commodity volumes. Flanders capacity expansions target tethered-screw redesigns.
- Snap Fit:Interference-fit designs serve single-serve and portion-control applications. Limited penetration outside dairy and condiment segments.
Screw Cap dominates unit volume; Child-Resistant is gaining share fastest on pharmaceutical safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux converting capacity clusters around Antwerp-Rotterdam port infrastructure, with Belgian molders and Dutch logistics operators forming an integrated supply corridor. Three national markets exhibit distinct demand profiles tethered to beverage, pharmaceutical, and chemical processing concentrations.
Belgium
Flanders hosts expanded injection-molding operations serving carbonated beverage bottlers with tethered-cap formats. REACH compliance through ECHA governs resin composition and additive disclosure across Wallonia and Brussels-Capital manufacturing. Antwerp port clusters enable rHDPE and rPP import for recycled-content quota fulfillment.
Netherlands
Randstad logistics density supports just-in-time closure delivery to Rotterdam-port beverage packagers and pharmaceutical distributors. The Dutch national packaging decree implements EU Single-Use Plastics Directive tethered-cap deadlines ahead of continental timelines. Eindhoven-Brabant toolrooms supply precision multi-cavity molds to regional converters.
Luxembourg
The Grand Duchy's expanding generics and biosimilar manufacturing base generates specification-driven closure demand without indigenous molding supply. EMA pharmaceutical guidelines shape child-resistant and metered-dose requirements for oncology formulations. Belgian and Dutch suppliers capture this adjacent geography through cross-border logistics.
Benelux Plastic Caps and Closures Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and tooling. The Benelux market exhibits tiered concentration with multinational polymer converters occupying scale positions and regional molders capturing specification niches. Two archetypes dominate: diversified packaging platforms with broad polymer conversion capabilities, and precision closure specialists with tethered-cap or pharmaceutical dispensing expertise. Competitive dynamics center on mold fabrication capacity reservation and recycled-content resin sourcing partnerships.
Among Germany-based platform operators, Bericap Holding GmbH exemplifies tethered-cap technology leadership for carbonated applications. Berry Global Inc represents diversified polymer conversion across multiple end-use categories. Kornelis Caps & Closures occupies the precision dispensing specialist tier for pharmaceutical channels. These three entities anchor distinct competitive vectors within the regional supply structure.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Bericap Holding GmbH |
| Berry Global Inc |
| Protective Industries Inc |
| Eurocap & Eurocork |
| Berlin Packaging Netherlands |
| Keizer International BV |
| Kornelis Caps & Closures |
| Closure Systems International |
| Others |
Pricing and Supply Chain Analysis
German and Italian precision mold suppliers anchor upstream capacity for tethered-cap tooling, concentrating margin capture in the multi-cavity hot-runner tier while Belgian and Dutch converters absorb downstream price volatility from recycled resin scarcity.
Pricing Analysis
The EU Single-Use Plastics Directive dictates the pricing tier structure across Benelux closure manufacturing. Three-tier pricing separates pharmaceutical-grade dispensing closures from standard beverage tethered caps from economy snap-fit formats. Price differentiation hinges on EFSA food-contact certification status and volume scale of cooperative procurement platforms. Cost compression in commodity screw-cap segments is intensifying because Flanders bottlers aggregate demand through shared purchasing consortia. Mid-tier mineral water packagers exhibit highest price sensitivity; oncology pharmaceutical distributors show least.
Supply Chain Analysis
Specialized mold fabricators in Germany and Italy hold captive capacity for tethered-cap geometries. Raw material flows draw from Antwerp-Rotterdam petrochemical clusters for virgin PP and HDPE, with rPP and rHDPE sourcing from mechanical recycling operations in Belgium and the Netherlands. Single-source vulnerability concentrates in precision hot-runner systems from Italian toolrooms. Distribution runs through Randstad logistics corridors to just-in-time beverage and pharmaceutical packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cooperative purchasing platforms are reconstituting buyer-side market power, creating platform-economics inflection as aggregated volume displaces bilateral supplier relationships across Flanders beverage segments.
For Market Incumbents: Pre-empt margin erosion from aluminum substitution trials by securing long-term rPP supply partnerships with mechanical recyclers in Antwerp port zones. Accelerate mold fabrication capacity reservations with German toolrooms before lead times extend further. Tethered-cap compliance deadlines create urgency for incumbent lock-in.
For New Entrants and Emerging Players: Pursue Luxembourg pharmaceutical closure supply as the Grand Duchy's biosimilar manufacturing base lacks indigenous molding capacity. Target child-resistant and metered-dose specifications for oncology formulations where precision requirements limit commodity competition. Establish cross-border logistics partnerships with Belgian distributors to serve EMA-regulated demand.
For Investors and Strategic Acquirers: Capital is best deployed toward precision dispensing specialists with pharmaceutical certification and digital watermarking integration capabilities. Five-to-ten year viability favors converters with formulation flexibility for escalating recycled-content quotas. Monitor EFSA novel food contact material approval timelines as inflection indicator for resin technology obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPP Supply | Secures food-grade recycled resin access ahead of EU quota escalations. |
| Multi-Cavity Mold Capacity Reservation | Locks German toolroom output for tethered-cap compliance deadlines. |
| Digital Watermarking Adoption | Positions for AIM-Digimarc traceability standards in EPR compliance. |
| Luxembourg Distribution Partnership | Captures adjacent geography demand from expanding biosimilar manufacturing. |
| Pharmaceutical Certification Investment | Enables child-resistant closure supply for oncology formulation growth. |
Research Methodology
A standing panel of injection-molding plant managers, beverage procurement directors at cooperative purchasing platforms, pharmaceutical packaging engineers, and Eindhoven-Brabant toolroom operators provided ongoing calibration across primary fieldwork. Secondary validation drew from ECHA SCIP database disclosures, EU Packaging and Packaging Waste Regulation implementation timelines, Belgian national packaging decrees, and customs trade data for rPP and rHDPE flows through Antwerp-Rotterdam corridors. Bottom-up capacity assessments at Flanders converting facilities were triangulated against top-down demand modeling from beverage bottler order aggregations.
Scenario bracketing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-user industry, and closure design complexity. CAGRs were derived from unit volume trajectories by segment and value-per-unit adjustments for regulatory compliance cost pass-through. Industry-specific forecast inputs incorporated tethered-cap mandate implementation schedules and mechanical recycling infrastructure buildout timelines.
Sensitivities concentrate around EFSA approval delays for novel recycled-content resins and aluminum substitution acceleration in premium beverage segments. Forecasts reflect assumptions on mold fabrication lead time normalization and rPP supply scaling. Quarterly review of ECHA substance restriction proposals and cooperative platform procurement volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Twist Caps Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Spain Plastic Cap and Closure Market