
 Lined Lug Caps Market | 2026-2036
Lined Lug Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Lined Lug Caps Market Foresight
Specialty chemical packagers are unwinding their historical preference for standard unlined closures toward lined lug caps that guarantee volatile content containment. Silgan Holdings Inc. dominates North American metal closure supply through captive manufacturing scale. Berry Global, Inc. differentiates via deep plastic liner formulation expertise across polypropylene and vinyl substrates. Béricap GmbH & Co. KG anchors European pharmaceutical closure demand with precision-molded composite designs.
Lined lug caps are threaded closures incorporating compressible liners—typically pulp-backed vinyl, foamed polyethylene, or induction-seal laminates—between the cap shell and container land surface, creating a hermetic seal against gas or liquid migration. The liner compresses under applied torque to fill surface irregularities, making these caps essential for vacuum-packed foods, corrosive chemicals, and sterile pharmaceuticals. Plastic caps lead volume across food and beverage use cases where cost and corrosion resistance matter, while metal caps command premium positions in thermal-processed and high-acid applications. Composite caps represent the fastest-expanding segment as converters merge aluminum shells with engineered polymer liners to satisfy dual barrier and lightweighting requirements. Twist-off closure styles dominate retail food packaging, whereas screw-on configurations prevail in pharmaceutical and chemical segments where reseal integrity governs specification.
FDA 21 CFR regulations on food contact substances and EU MDR technical documentation requirements shape liner material approvals and migration testing protocols for pharmaceutical applications. EPA chemical containment standards and OSHA workplace exposure rules further tighten closure performance specifications for industrial chemical transport. REACH compliance in Europe and evolving state-level packaging extended producer responsibility laws in California and New York add compliance layers that favor suppliers with certified material traceability systems. Stakeholders must monitor liner resin qualification timelines and regional recycling compatibility mandates to avoid specification obsolescence.
Market Dynamics
Pharmaceutical and food safety regulators on both sides of the Atlantic are tightening liner material migration limits and child-resistant testing protocols, forcing converters to requalify entire product portfolios and compressing time-to-market for new closure designs.
Growth Catalysts
- EU MDR Technical Documentation:European pharmaceutical packagers are accelerating lined lug cap procurement to satisfy enhanced tamper-evidence and traceability mandates under the Medical Device Regulation.
- Metal Shell-Polymer Liner Composites:Thermal-processed food manufacturers are specifying aluminum-polypropylene hybrid closures to achieve lightweighting without sacrificing high-acid barrier performance.
- California Extended Producer Responsibility:The state's packaging recycling mandates are pulling demand toward lined caps with certified mono-material compatibility and blockchain-traceable liner resins.
Market Restraints
- Pulp-Backed Vinyl Liner Supply:Concentrated vinyl resin production on the US Gulf Coast exposes converters to hurricane-driven feedstock disruptions and force majeure declarations.
- Induction-Seal Laminate Qualification Timelines:FDA 21 CFR food contact notification reviews now stretch 18-24 months for novel multilayer liner substrates, freezing specification updates.
- Twist-Off Metal Substitution:Snap-fit plastic closures with integrated seals are capturing shelf-stable juice and sauce volumes where reseal cycles remain low.
Strategic Opportunities
- India Pharmaceutical Export Packaging:CDSCO-aligned contract packagers serving EU and US markets represent an underserved demand pocket for child-resistant lined lug systems.
- Closed-Loop Chemical Tote Refill:Corrosive chemical distributors are piloting returnable intermediate bulk containers with replaceable lined lug closures, creating recurring liner revenue streams.
- EU Green Deal Carbon Border Adjustment:European food exporters are sourcing aluminum lug caps with verified low-carbon primary metal to preempt CBAM compliance costs on packaged goods.
Industry Challenges
- Induction Sealing Technician Shortage:Packagers struggle to hire operators capable of calibrating high-frequency sealing heads across variable container land surfaces and liner compressibility profiles.
- Legacy Screw-On Tooling Retrofit:Pharmaceutical filling lines with 1960s-era capping heads require seven-figure capital outlays to achieve the torque precision demanded by modern composite lined closures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lined Lug Caps Market |
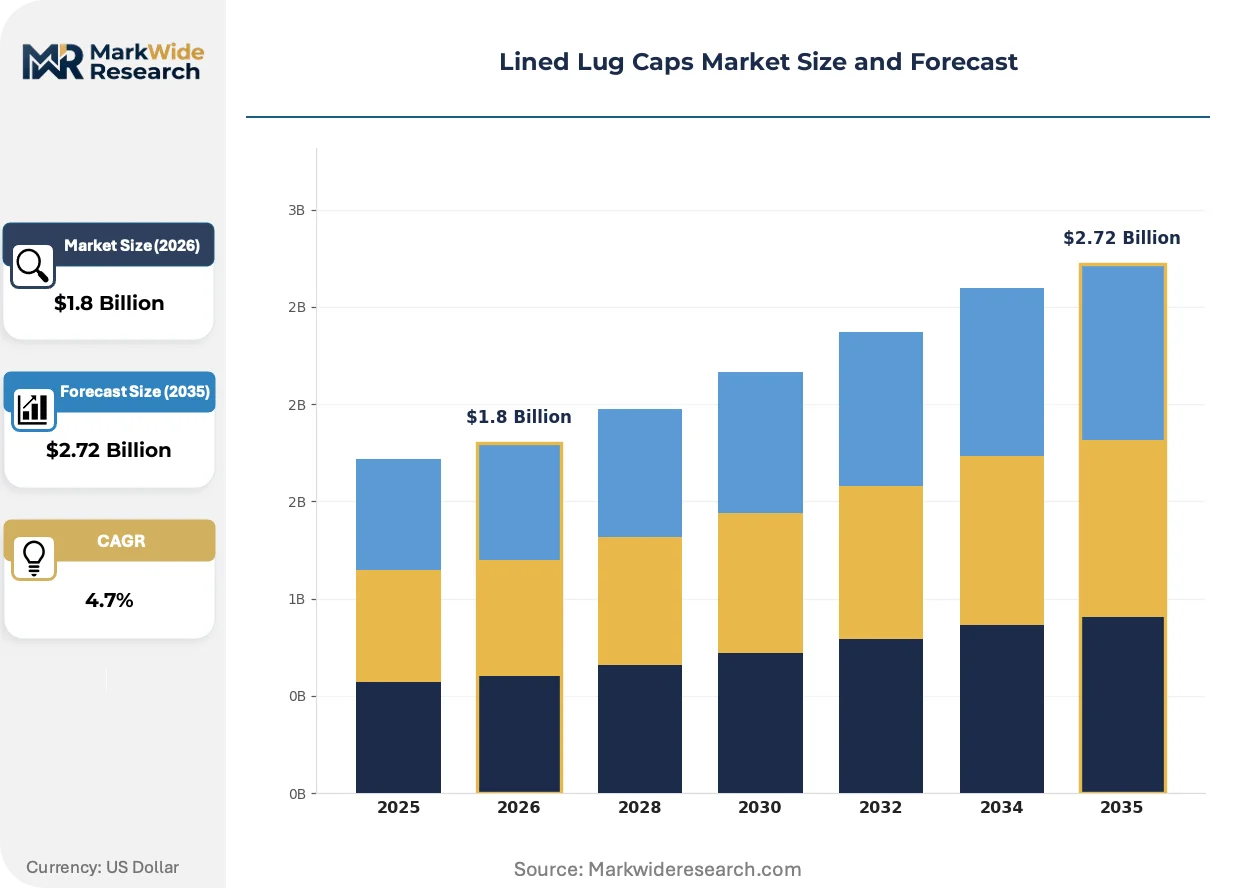
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Metal Caps, Composite Caps, Specialty Caps Material: Polypropylene, Aluminum, Steel, Vinyl Use Case: Food & Beverage, Pharmaceuticals, Chemicals, Cosmetics Closure Style: Twist-Off, Snap-On, Screw-On, Pull-Tab |
| Companies Covered | Aptar Group Inc., Ball Corporation, Silgan Holdings Inc., Massilly, Béricap GmbH & Co. KG, Crown Holdings Inc., Berry Global, Inc., Pelliconi, Amcor Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lined Lug Caps Market Shifts & Advancements
Converters are racing to integrate smart authentication features and bio-based liner substrates while reconfiguring manufacturing footprints to serve regional recycling compliance regimes.
Induction-seal laminate liners with embedded holographic tamper-evidence layers are supplanting conventional pulp-backed vinyl in high-value pharmaceutical and nutraceutical applications. Contract packagers serving FDA-regulated facilities are specifying these laminates for 60% of new product introductions. The shift is compressing margins for legacy vinyl liner compounders unable to qualify holographic substrate adhesion.
REACH Article 33 SVHC disclosure requirements are forcing European closure assemblers to map sub-supplier resin formulations through four tiers. Industrial chemical packagers are now rejecting lined caps lacking full material composition documentation. German and French distributors are consolidating procurement around suppliers with certified supply chain transparency systems.
Direct-to-contract-manufacturer specification influence is displacing traditional brand-owner-driven closure selection in generic pharmaceutical packaging. Indian and Chinese CDMOs are now issuing their own lined lug cap technical standards, bypassing historical reliance on innovator company specifications. This pattern is most visible in Bangalore and Hyderabad, where regional packagers command specification authority for EU-exported oral solid doses.
Lined Lug Caps Market Segmentation
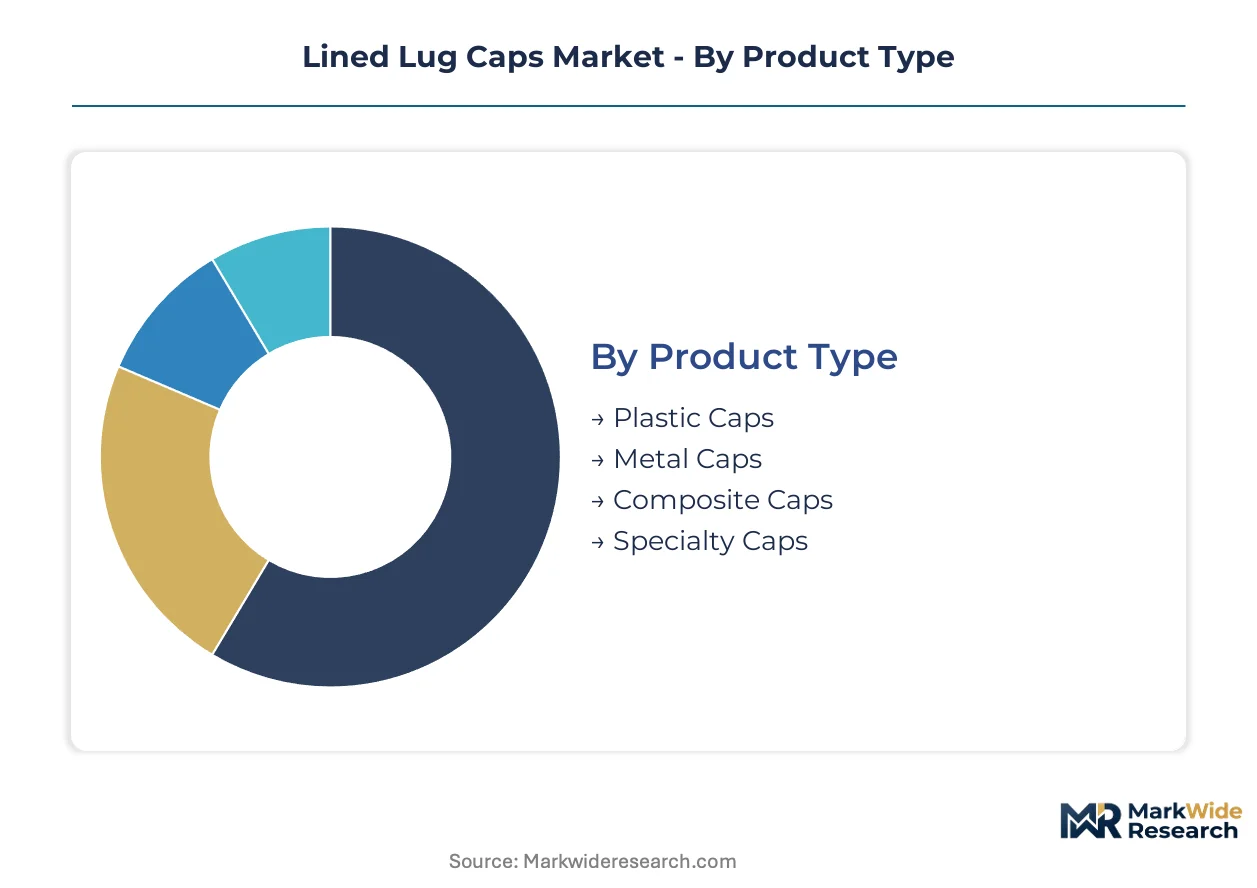
Lined lug cap specifications diverge sharply across end-use compliance regimes, with pharmaceutical and food safety mandates dictating liner material approvals, torque tolerances, and migration testing protocols. Procurement patterns cluster around performance tiers rather than pure cost optimization, creating distinct specification silos that resist cross-segment substitution.
Product Type:
FDA 21 CFR food contact substance rules and EU MDR technical documentation requirements create divergent qualification burdens across shell materials, with metal and composite caps facing extended approval timelines for novel liner substrates.
- Plastic Caps:Polypropylene and polyethylene shells dominate high-volume food and beverage applications where corrosion resistance and cost efficiency outweigh thermal processing demands. Bottled sauce and condiment packagers in the US and Germany specify these caps for pH-neutral products with moderate shelf-life requirements, though California extended producer responsibility mandates are forcing rapid reformulation toward mono-material recyclability.
- Metal Caps:Aluminum and tinplate shells with pulp-backed vinyl or induction-seal liners command premium positions in thermal-processed foods and high-acid applications requiring vacuum integrity. Italian tomato processors and US pickle manufacturers specify twist-off metal configurations to survive retort cycles, with EU Green Deal carbon border adjustments now pulling demand toward verified low-carbon primary aluminum sourcing.
- Composite Caps:Hybrid aluminum-polymer designs merge shell strength with engineered liner precision for pharmaceutical and nutraceutical applications demanding child-resistant functionality.
- Specialty Caps:Custom-molded configurations serve corrosive chemical and sterile parenteral drug segments with extreme barrier specifications.
Established volume favors plastic caps; emerging adoption favors composite caps.
Material:
Raw material sourcing geography and REACH Article 33 SVHC disclosure obligations are consolidating procurement around suppliers with certified four-tier resin traceability.
- Polypropylene:Homopolymer and copolymer grades form the backbone of food-grade plastic caps and composite cap liners, with nucleated formulations improving dimensional stability under induction sealing heat. German automotive chemical packagers and Indian pharmaceutical exporters are accelerating polypropylene liner adoption for CDSCO-aligned export packaging.
- Aluminum:Rolled and deep-drawn shells provide structural integrity for thermal-processed applications, with European food exporters sourcing verified low-carbon primary metal to preempt EU carbon border adjustment compliance costs.
- Steel:Tin-free steel and electrolytic tinplate alternatives serve cost-sensitive industrial chemical segments where magnetic detection matters.
- Vinyl:Plasticized and unplasticized polyvinyl chloride formulations persist in legacy pulp-backed liners despite REACH SVHC scrutiny and hurricane-vulnerable Gulf Coast supply concentration.
Commodity scale favors polypropylene; specification premium favors aluminum.
Use Case:
End-use regulatory intensity creates non-overlapping specification universes, with pharmaceutical and chemical segments demanding documentation regimes incompatible with food-grade procurement workflows.
- Food & Beverage:Shelf-stable sauces, juices, and condiments drive twist-off plastic and metal cap volumes, with packagers calibrating liner compressibility against glass jar land surface variability. US and Italian processors specify induction-seal laminates for extended shelf-life products.
- Pharmaceuticals:Oral solid dose and liquid formulations require child-resistant and tamper-evident lined lug systems meeting FDA 21 CFR and EU MDR standards. Bangalore and Hyderabad CDMOs are issuing independent technical specifications for EU-exported generics.
- Chemicals:Corrosive and volatile content containment drives specification of fluoropolymer-lined metal caps for industrial transport.
- Cosmetics:Premium skincare and fragrance applications demand aesthetic shell finishes with functional liner seals.
Volume concentration favors food and beverage; margin premium favors pharmaceuticals.
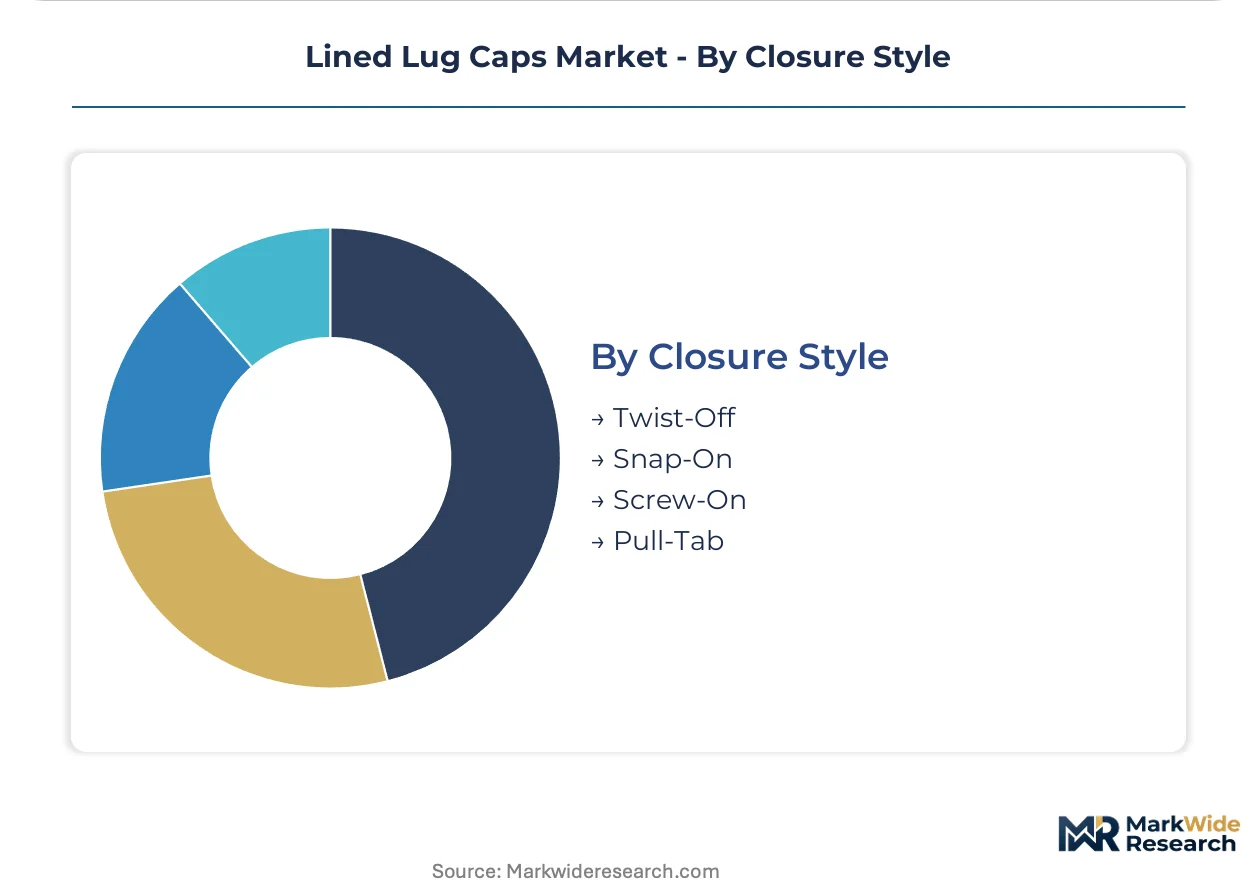
Closure Style:
Torque precision requirements and reseal cycle expectations determine style selection, with pharmaceutical lines requiring capital-intensive screw-on tooling upgrades incompatible with legacy capping equipment.
- Twist-Off:Lugged metal shells with compressible liners dominate retail food packaging, delivering hermetic seals through 90-degree rotation without tool assistance. German and French food processors specify these for vacuum-packed vegetables and preserves.
- Screw-On:Continuous thread configurations with precise torque tolerances govern pharmaceutical and chemical applications where reseal integrity across multiple cycles determines specification. US generic drug packagers face seven-figure capital outlays to retrofit 1960s-era capping heads for modern composite lined closures.
- Snap-On:Plastic configurations with integrated seals capture low-reseal juice and sauce volumes where twist-off metal cost is unjustified.
- Pull-Tab:Tamper-evident ring designs serve single-serve beverage and pharmaceutical unit-dose applications.
Consumer convenience favors twist-off; regulatory compliance favors screw-on.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical packagers export child-resistant lined lug systems to EU and US buyers, while German food processors supply vacuum-packed preserves across European retail chains. This trade-flow architecture concentrates specification authority in manufacturing clusters aligned with CDSCO, FDA, and EU MDR compliance regimes.
United States
California's extended producer responsibility mandates are pulling packagers toward mono-material lined caps with blockchain-traceable liner resins. FDA 21 CFR food contact notification reviews now stretch 18-24 months for novel multilayer substrates. Chicago-area sauce and condiment processors specify induction-seal laminates for extended shelf-life glass jar applications.
Germany
Tomato processors in the Stuttgart region specify twist-off metal configurations with verified low-carbon primary aluminum to preempt EU Green Deal carbon border adjustment costs. REACH Article 33 SVHC disclosure requirements force closure assemblers to map sub-supplier resin formulations through four tiers. Bavarian automotive chemical packagers accelerate polypropylene liner adoption for corrosion-resistant containment.
India
Bangalore and Hyderabad CDMOs now issue independent lined lug cap technical standards for EU-exported oral solid doses, bypassing historical reliance on innovator company specifications. CDSCO-aligned contract packagers serving US and European markets represent underserved demand pockets for child-resistant systems. Gujarat-based specialty chemical exporters specify fluoropolymer-lined metal caps for volatile content containment.
Italy
Emilia-Romagna food processors anchor European demand as regional manufacturers shift toward metal lug closures with enhanced liner barrier properties for high-acid preserves. Parma-area packagers calibrate liner compressibility against glass jar land surface variability for vacuum-packed vegetable applications. Italian tomato processors specify twist-off metal configurations to survive aggressive retort cycles.
France
Lyonnaise chemical distributors pilot returnable intermediate bulk containers with replaceable lined lug closures, creating recurring liner revenue streams for corrosive content transport. ANSM pharmaceutical packaging standards align with EU MDR technical documentation requirements for tamper-evidence and traceability. Paris-region cosmetic packagers demand aesthetic shell finishes with functional liner seals for premium fragrance applications.
Lined Lug Caps Market Competitive Landscape
Listed leaders compete with private specialists across shell material and liner formulation capabilities. The vendor base clusters around three concentration nodes: North American metal closure fabricators with captive aluminum supply, European precision-molded composite specialists, and Asia-Pacific plastic closure converters with integrated liner compounding. Strategic moves center on backward integration into liner resin production and geographic expansion to serve regional recycling compliance regimes.
Among European precision-molded specialists, Béricap GmbH & Co. KG exemplifies the pharmaceutical-grade composite archetype, while Massilly occupies a position within the metal closure tradition. Silgan Holdings Inc. represents the North American scale-driven tier with captive manufacturing infrastructure. Berry Global, Inc. sits within the plastic liner formulation specialist category, anchoring polypropylene and vinyl substrate expertise.
| Leading Market Players |
|---|
| Aptar Group Inc. |
| Ball Corporation |
| Silgan Holdings Inc. |
| Massilly |
| Béricap GmbH & Co. KG |
| Crown Holdings Inc. |
| Berry Global, Inc. |
| Pelliconi |
| Amcor Ltd |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day vinyl resin lead times on the US Gulf Coast compress converter margins and amplify pricing power for integrated suppliers with captive liner compound production. This inventory pressure intersects with FDA 21 CFR qualification delays to stratify procurement costs across legacy and next-generation closure platforms.
Pricing Analysis
Next-generation induction-seal laminate liners command 40-60% premiums over pulp-backed vinyl configurations, while legacy metal shell-polymer composites occupy mid-tier positioning. Pricing stratifies across premium, standard, and economy tiers based on FDA food contact certification status and volume scale. Cost compression in standard vinyl-backed closures is intensifying because hurricane-vulnerable Gulf Coast feedstock concentration exposes converters to force majeure surcharges. Generic pharmaceutical packagers exhibit highest price sensitivity, whereas EU MDR-aligned CDMOs absorb premium pricing for tamper-evident composite systems.
Supply Chain Analysis
Forty-five-day liner resin inventories at European compounders rest on concentrated vinyl production along the US Gulf Coast, German polypropylene formulation clusters, and Chinese aluminum shell rolling mills. Raw material dependencies center on plasticized PVC resins, nucleated polypropylene grades, and deep-drawn aluminum coil. Single-source vulnerability in Gulf Coast vinyl supply creates disruption exposure during Atlantic hurricane season. Distribution runs through direct-to-CDMO specification channels in Bangalore and Hyderabad, bypassing traditional brand-owner procurement hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation mandates and California extended producer responsibility laws constitute a dual regulatory inflection, accelerating specification turnover and consolidating procurement around certified traceability systems.
For Market Incumbents: Fortify backward integration into liner resin production to offset Gulf Coast supply volatility, while embedding blockchain-traceable material documentation to preempt REACH Article 33 SVHC disclosure penalties. Silgan Holdings and Berry Global must defend against emerging composite specialists by locking multi-year offtake agreements with Indian CDMOs in Hyderabad and Bangalore. For New Entrants and Emerging Players: Anchor in fluoropolymer-lined metal cap segments serving Gujarat-based specialty chemical exporters, where volatile content containment specifications outpace incumbent qualification capacity. Target closed-loop chemical tote refill pilots in Lyon and Stuttgart, where recurring liner replacement revenue streams remain underdeveloped. Lead with CDSCO-aligned technical documentation capabilities to bypass innovator company specification gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming closure divisions lacking pharmaceutical-grade composite expertise. Five-to-ten-year viability hinges on MDR compliance infrastructure and low-carbon aluminum sourcing relationships. Watch for EU Green Deal carbon border adjustment implementation signals as demand-pull inflection for verified primary metal procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Resin Production | Gulf Coast vinyl concentration exposes converters to hurricane-driven force majeure disruptions. |
| Blockchain-Traceable Material Documentation | REACH Article 33 SVHC disclosure mandates four-tier sub-supplier mapping for European pharmaceutical packagers. |
| CDSCO-Aligned Technical Standard Development | Bangalore and Hyderabad CDMOs now issue independent specifications bypassing innovator company gatekeeping. |
| Low-Carbon Primary Aluminum Sourcing | EU Green Deal carbon border adjustments pull Stuttgart tomato processors toward verified metal procurement. |
| Closed-Loop Chemical Tote Refill Pilots | Lyon distributors pilot returnable IBC systems creating recurring liner revenue streams for corrosive transport. |
Research Methodology
Desk research of FDA 21 CFR food contact substance notifications, EU MDR technical documentation databases, and REACH Article 33 SVHC registries preceded structured interviews with pharmaceutical packaging engineers, chemical procurement leads at German automotive suppliers, Italian tomato processor operations directors, and Indian CDMO quality assurance managers. Bottom-up volume modeling triangulated against top-down value estimates derived from customs trade data and SEC 10-K segment disclosures.
Variance decomposition across shell material, liner substrate, closure style, and end-use regulatory intensity segments shaped the analytical framework over the projection horizon. CAGRs emerged from logistic diffusion curves fitted to qualification timeline data and regional compliance mandate implementation schedules. Induction-seal laminate adoption rates and CDSCO-aligned export packaging growth served as industry-specific forecast anchors.
Material uncertainties — FDA food contact notification review duration extensions, Atlantic hurricane frequency affecting Gulf Coast vinyl supply, and EU carbon border adjustment scope finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and substitution elasticity between closure technologies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Aerosol Valves Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Cap Liner Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Ring Pull Caps Market