
 Global Medical Vacuum System Market | 2026-2036
Global Medical Vacuum System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Vacuum System Market Foresight
Modular system bundling is broadening buyer choice across the Global Medical Vacuum System Market as hospitals shift from standalone pumps to integrated central vacuum networks with remote monitoring modules. Atlas Copco AB leverages its industrial compressor heritage to anchor large-scale hospital infrastructure contracts in Europe. Gardner Denver Holdings sustains competitive positioning through specialized oil-free rotary vane architectures for surgical theaters. Busch Vacuum Solutions dominates the laboratory diagnostics segment with dry-running vacuum technologies that eliminate contamination risks.
A medical vacuum system generates sub-atmospheric pressure through mechanical displacement to evacuate fluids, gases, or surgical debris from patient cavities or closed-loop clinical equipment, typically operating between 150 and 760 mmHg absolute pressure depending on the clinical application. Rotary vane vacuum pumps occupy the largest product category due to proven reliability in continuous-duty hospital environments, while scroll vacuum pumps represent the fastest-expanding segment as healthcare facilities prioritize oil-free operation to meet stringent infection control protocols. Electromechanical technology leads the technology split because of precise variable-speed control, though microcontroller-based systems are gaining share as facilities integrate vacuum assets into building management platforms.
The FDA enforces 510(k) premarket notification requirements for medical vacuum devices used in surgical and respiratory applications, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance through EUDAMED registration. ISO 7396-1 specifies medical gas pipeline system requirements including vacuum distribution infrastructure, directly shaping product design and installation standards. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC for connected vacuum systems as hospital networks harden against ransomware threats to critical clinical infrastructure.
Market Dynamics
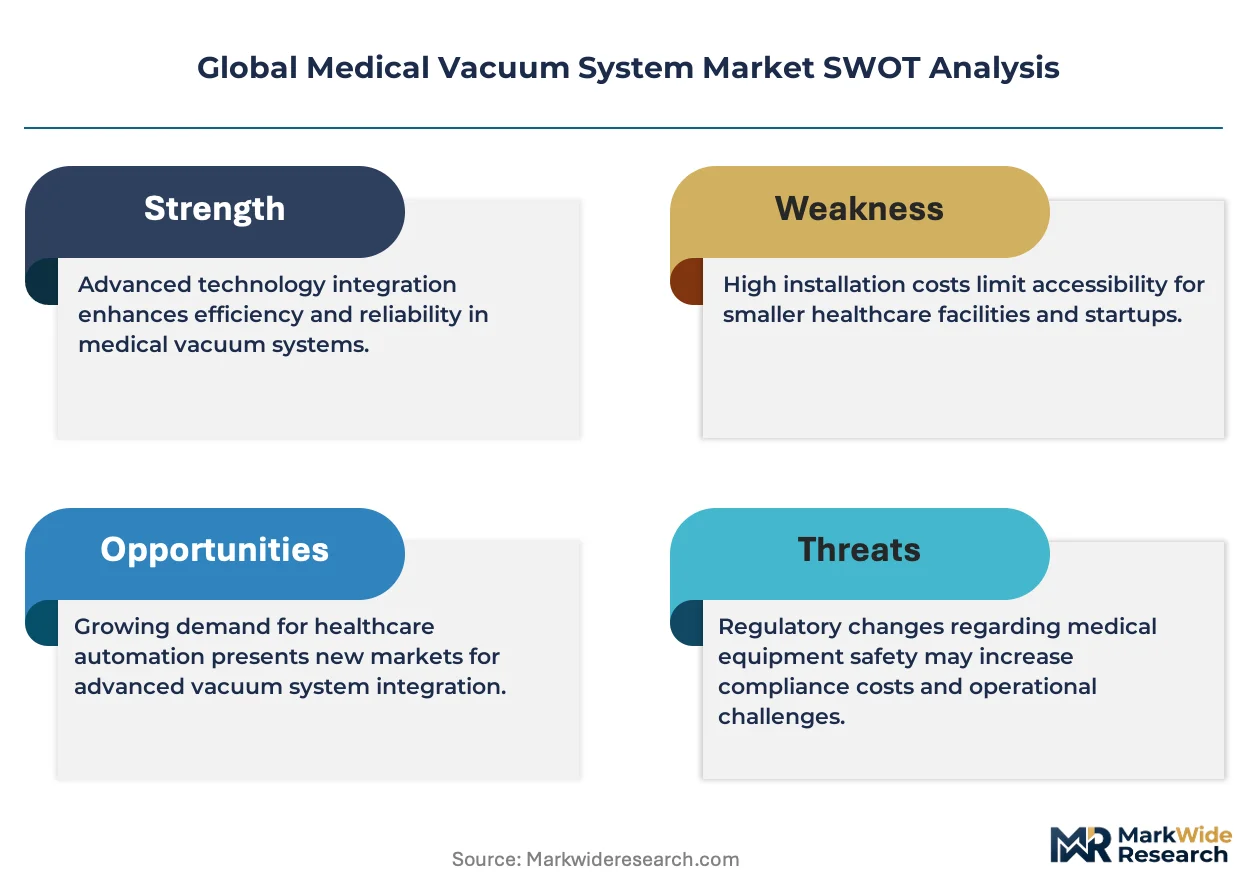
Centralized vacuum infrastructure is displacing standalone pump installations in hospital modernization programs across Germany, the United States, and Japan, compressing vendor margins while expanding service contract attach rates.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance mandates through EUDAMED registration are accelerating replacement cycles for legacy vacuum equipment in European surgical centers.
- Ambulatory surgical centers:Outpatient procedural volume expansion in the United States is driving demand for compact, mobile vacuum units with rapid sterilization protocols.
- Oil-free rotary vane technology:Infection control protocols in Japanese tertiary hospitals are pulling demand away from lubricated pump architectures toward dry-running alternatives.
Market Restraints
- Stainless steel and specialty alloy costs:Input price volatility for vacuum chamber materials is compressing gross margins for mid-tier equipment manufacturers.
- German component concentration:Precision vacuum sensor supply chains cluster in Baden-Württemberg, creating geographic vulnerability for system integrators.
- Technical limitation:Scroll pump architectures face duty-cycle constraints in continuous surgical suction applications exceeding 18 hours.
Strategic Opportunities
- India:Hospital infrastructure expansion under the Ayushman Bharat scheme is opening demand for modular central vacuum networks in tier-2 and tier-3 cities.
- Cybersecurity integration:Convergence of vacuum system monitoring with building management platforms creates white space for IEC 62443-compliant remote diagnostics modules.
- Home healthcare respiratory therapy:Portable suction device demand is emerging in post-acute care settings across the United States and Japan.
Industry Challenges
- Biomedical engineering talent:Shortage of technicians qualified in ISO 7396-1 pipeline certification is extending installation timelines for central vacuum projects.
- FDA 510(k) pathway complexity:Evolving cybersecurity documentation requirements for connected vacuum systems are lengthening premarket notification preparation.
- Legacy infrastructure integration:Retrofitting 1990s-era medical gas pipeline systems with variable-speed vacuum controls requires custom engineering without standardized adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Vacuum System Market |
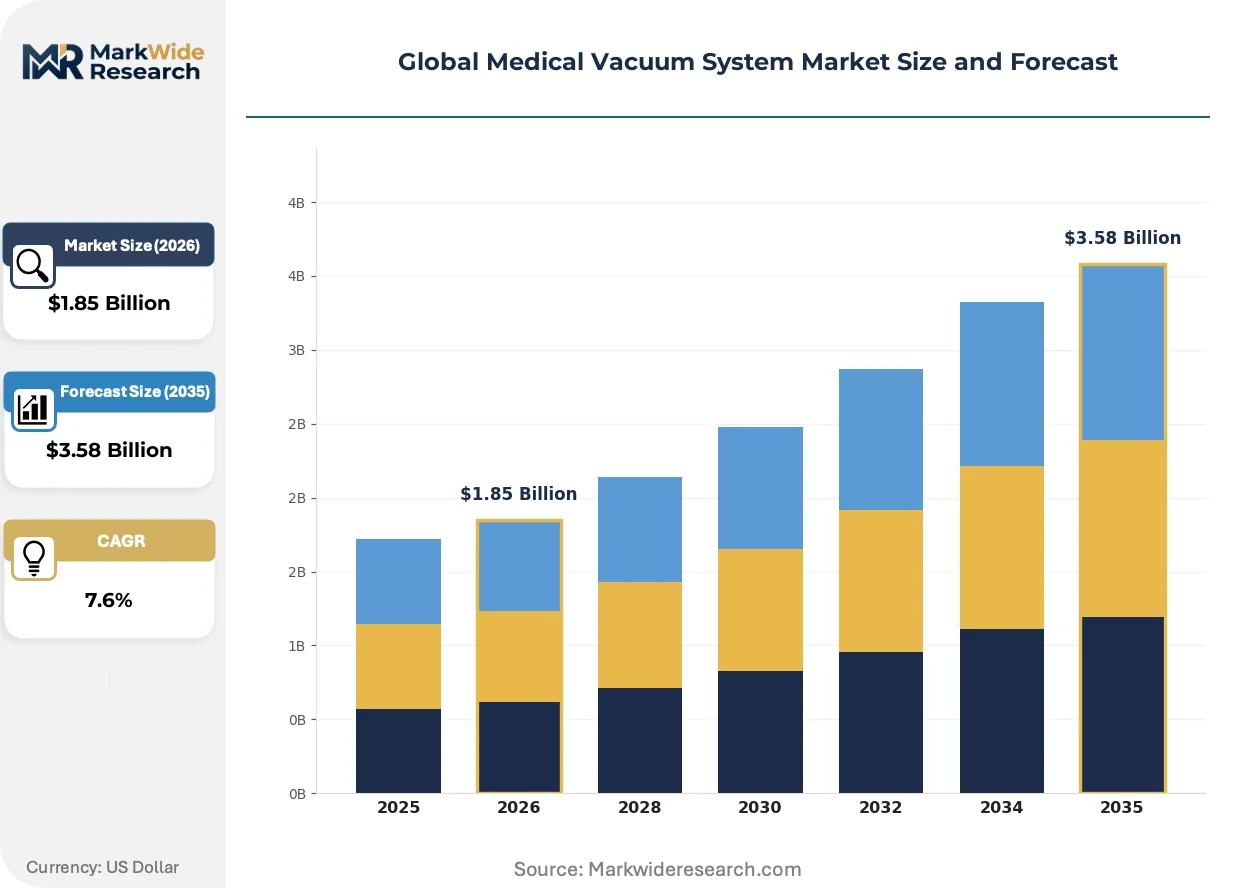
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.58 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Vacuum Pumps, Diaphragm Vacuum Pumps, Rotary Vane Vacuum Pumps, Liquid Ring Vacuum Pumps, Scroll Vacuum Pumps Technology: Electromechanical, Pneumatic, Electrohydraulic, Electromagnetic, Microcontroller-based Application: Surgical Aspiration, Anesthesia Delivery, Laboratory Diagnostics, Respiratory Therapy, Waste Management End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Dental Clinics, Research Institutions |
| Companies Covered | Atlas Copco AB, Gardner Denver Holdings, Busch Vacuum Solutions, Drägerwerk AG & Co. KGaA, Air Techniques, Allied Healthcare Products, ConvaTec Inc., Medela AG, Ohio Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Vacuum System Market Shifts & Advancements
Digital connectivity and oil-free architectures are compressing the technology lifecycle for medical vacuum equipment, forcing incumbents to restructure R&D allocation toward software-enabled service models.
Dry-running scroll vacuum technology is consolidating market share in laboratory diagnostics and pharmaceutical manufacturing segments. Academic medical centers in Germany and Switzerland are adopting these systems to eliminate hydrocarbon contamination risks in cell culture applications. The shift is consolidating procurement decisions around single-source vendors capable of delivering both hardware and validated cleaning protocols.
Japan's PMDA has tightened cybersecurity premarket requirements for networked medical devices including vacuum systems with remote monitoring capabilities. Manufacturers must now submit threat modeling documentation and software bill of materials prior to approval. Surgical equipment distributors in Tokyo and Osaka are responding by building in-house regulatory affairs capabilities to navigate extended review timelines.
Service contract unbundling is fragmenting traditional equipment procurement patterns in United States health systems. Hospital materials management departments are separating capital equipment acquisition from multi-year maintenance agreements, pressuring OEMs to compete on hourly service rates rather than bundled lifecycle pricing. The trend is most visible in California and Texas IDN consolidations where centralized procurement functions negotiate vacuum infrastructure at system-wide scale.
Global Medical Vacuum System Market Segmentation
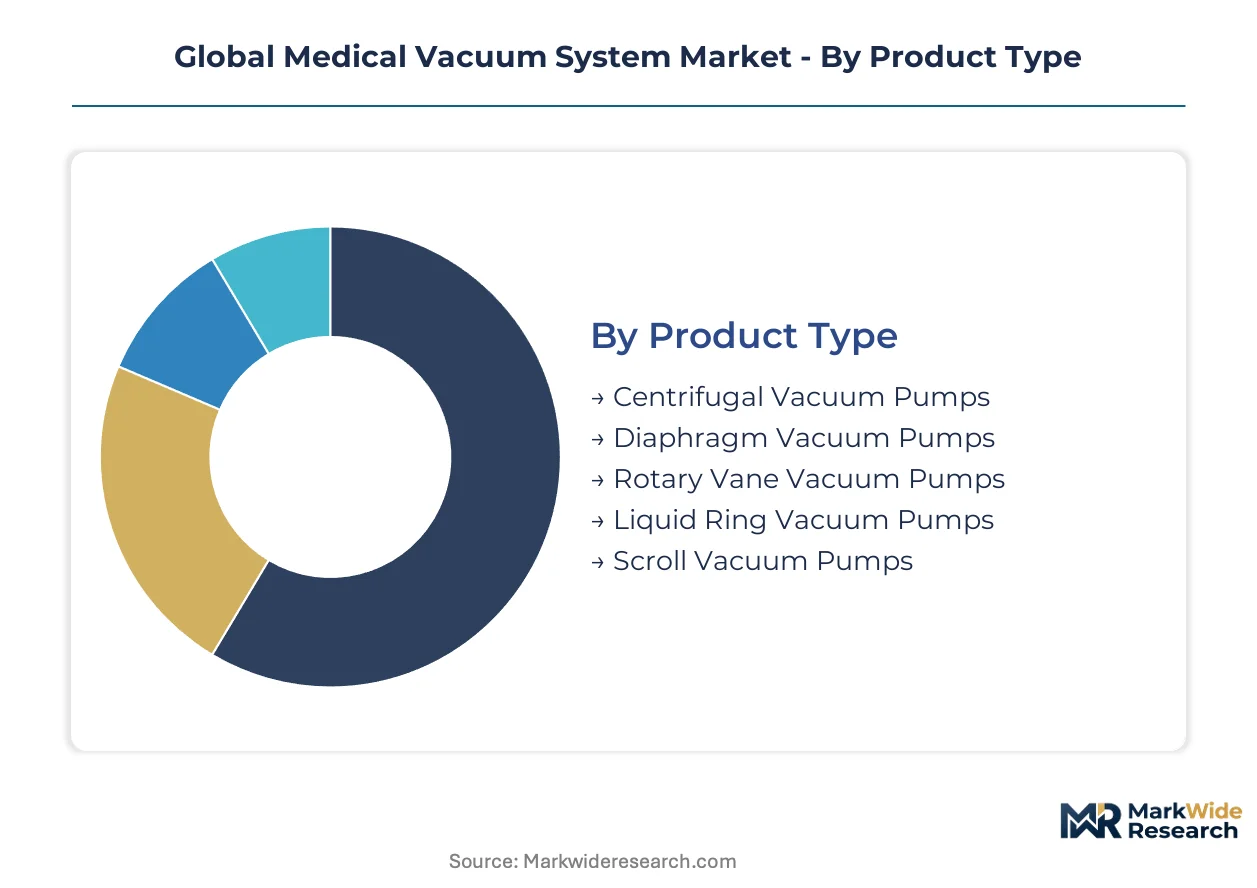
Medical vacuum system procurement decisions pivot on infection control protocols, continuous-duty reliability, and integration with existing pipeline infrastructure. Segmentation reveals how technology choices diverge between high-volume surgical environments and precision laboratory applications.
Product Type:
Hospital engineering departments prioritize proven uptime records and maintenance accessibility when selecting pump architectures for central vacuum networks.
- Rotary Vane Vacuum Pumps:Oil-sealed or dry-running positive displacement pumps deliver consistent vacuum levels across variable demand cycles. German and Japanese tertiary hospitals specify these for 24/7 surgical suction infrastructure due to decades of field-proven reliability.
- Scroll Vacuum Pumps:Orbiting spiral mechanisms compress gas without lubricant contact, eliminating hydrocarbon contamination. Swiss and German academic medical centers are consolidating procurement around these systems for cell culture and pharmaceutical manufacturing applications where purity protocols are non-negotiable.
- Centrifugal Vacuum Pumps:Dynamic compression technology suited for large-scale central systems serving multiple clinical wings simultaneously.
- Diaphragm Vacuum Pumps:Oscillating membrane designs isolate pumped media from mechanical components, preferred in portable respiratory therapy devices.
- Liquid Ring Vacuum Pumps:Rotating impeller systems using sealing liquid for compression, deployed in waste management and fluid evacuation where moisture tolerance matters.
Volume sits with Rotary Vane; growth tilts toward Scroll.
Technology:
Control precision and building integration capabilities separate premium system configurations from commodity alternatives.
- Electromechanical:Variable-speed motor drives enable precise vacuum level modulation matched to real-time surgical demand. United States health systems specify these for integration with building automation platforms that monitor energy consumption across clinical infrastructure.
- Microcontroller-based:Embedded processing enables predictive maintenance algorithms and remote diagnostic connectivity. Japanese PMDA cybersecurity requirements are accelerating validation investment for networked vacuum assets in Tokyo and Osaka medical centers.
- Pneumatic:Compressed air-driven venturi systems for mobile applications where electrical isolation is required.
- Electrohydraulic:Fluid power transmission for high-torque continuous-duty applications in large hospital central plants.
- Electromagnetic:Linear motor actuation for ultra-quiet operation in neonatal and psychiatric care environments.
Electromechanical dominates installed base; Microcontroller-based climbs fastest as facilities harden connected infrastructure.
Application:
Clinical workflow intensity and regulatory scrutiny depth determine vacuum system specification stringency.
- Surgical Aspiration:High-flow suction systems evacuate blood, tissue, and irrigation fluids during operative procedures. United States ambulatory surgical centers are driving demand for compact units with rapid sterilization turnaround to support high-volume outpatient caseloads.
- Laboratory Diagnostics:Precision vacuum control for sample processing, filtration, and analytical instrument support. Dry-running technologies are consolidating share here as diagnostic manufacturers eliminate oil contamination risks from quality-sensitive workflows.
- Anesthesia Delivery:Scavenging systems capture waste anesthetic gases to protect operating room personnel.
- Respiratory Therapy:Portable suction devices for airway clearance in post-acute and home healthcare settings.
- Waste Management:Centralized collection systems transporting biohazardous materials through sealed pipeline networks.
Surgical Aspiration captures the largest revenue pool; Laboratory Diagnostics expands most quickly on contamination-free technology migration.
End User:
Capital allocation authority and infrastructure lifecycle stage shape procurement channel access for vacuum system vendors.
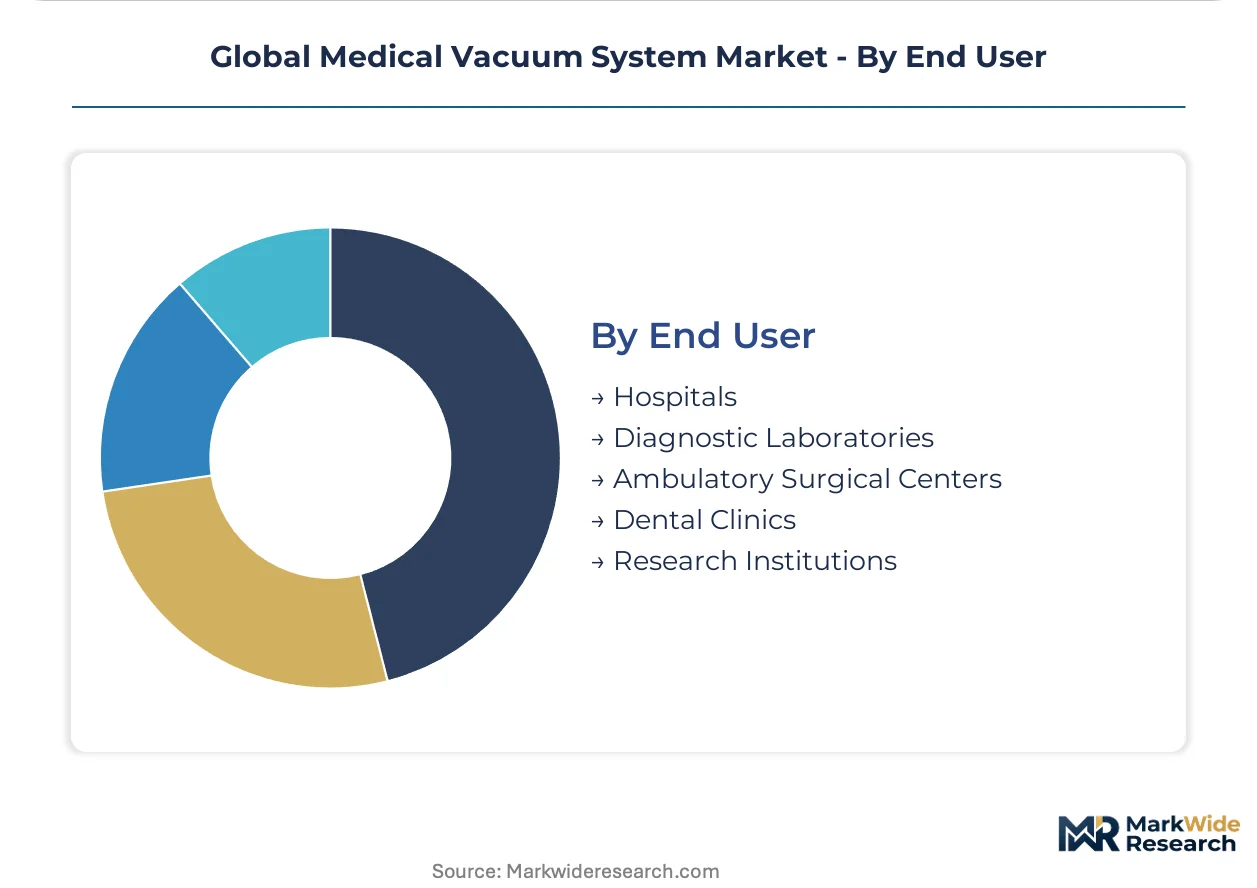
- Hospitals:Centralized vacuum plant installations serving multiple clinical departments through ISO 7396-1 compliant pipeline networks. Germany, the United States, and Japan are prioritizing modernization of 1990s-era infrastructure with variable-speed controls and remote monitoring modules.
- Ambulatory Surgical Centers:Standalone or portable vacuum units for procedure-specific suction requirements. Outpatient volume expansion in the United States is pulling demand toward compact systems with simplified maintenance protocols.
- Diagnostic Laboratories:Precision vacuum for analytical workflows, with contamination control as primary specification driver.
- Dental Clinics:Chairside suction for operative procedures, typically lower vacuum level requirements than surgical applications.
- Research Institutions:Specialized configurations for experimental protocols requiring custom vacuum profiles.
Hospitals anchor current revenue; Ambulatory Surgical Centers offer the steepest expansion trajectory on outpatient procedural volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital modernization programs in Germany's Baden-Württemberg region and Japan's Kansai corridor are concentrating procurement authority for central vacuum infrastructure among specialized system integrators.
United States
Ambulatory surgical centers in Texas and Florida are driving compact vacuum unit procurement as outpatient procedural volumes climb. FDA 510(k) premarket notification requirements for connected devices are lengthening approval timelines for networked vacuum systems. California health systems are unbundling service contracts from capital equipment purchases, pressuring OEMs to compete on hourly maintenance rates.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia are retrofitting 1990s-era medical gas pipeline networks with variable-speed vacuum controls. EU Medical Device Regulation post-market surveillance mandates through EUDAMED registration are accelerating replacement cycles for legacy equipment. Precision vacuum sensor supply chains cluster in Baden-Württemberg, creating geographic concentration risk for system integrators.
Japan
PMDA cybersecurity premarket requirements for networked medical devices are extending review timelines for vacuum systems with remote monitoring capabilities. Tokyo and Osaka medical centers are demanding threat modeling documentation and software bills of materials prior to approval. Infection control protocols in tertiary hospitals are pulling demand toward dry-running pump architectures.
India
Hospital infrastructure expansion under the Ayushman Bharat scheme is opening demand for modular central vacuum networks in tier-2 and tier-3 cities. Maharashtra and Gujarat are seeing concentrated procurement activity as state governments allocate capital budgets to district hospital upgrades. Domestic system integrators are partnering with European component suppliers to meet ISO 7396-1 pipeline certification standards.
Switzerland
Academic medical centers in Zurich and Basel are adopting dry-running scroll vacuum systems to eliminate hydrocarbon contamination risks in cell culture applications. Swissmedic regulations align with EU MDR requirements, streamlining cross-border procurement for hospital groups operating in both jurisdictions. The shift is consolidating procurement decisions around single-source vendors capable of delivering validated cleaning protocols.
Global Medical Vacuum System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Global Medical Vacuum System Market, creating a tiered structure where scale-driven industrial manufacturers anchor large infrastructure contracts while regional specialists capture service-intensive niches. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with compressor heritage, specialized vacuum technology pure-plays, and medical device OEMs with integrated suction portfolios. Competitive dynamics center on M&A activity targeting regional service capabilities and strategic partnerships for cybersecurity-compliant connectivity modules.
Within the diversified industrial tier, Atlas Copco AB and Gardner Denver Holdings exemplify scale-driven competitors leveraging compressor and pump manufacturing heritage to anchor hospital infrastructure contracts. Busch Vacuum Solutions occupies a position among specialized vacuum pure-plays, with its dry-running technology portfolio aligning to laboratory diagnostics demand. These three companies represent distinct competitive positioning vectors—industrial scale, application specialization, and contamination-free technology leadership—without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Gardner Denver Holdings |
| Busch Vacuum Solutions |
| Drägerwerk AG & Co. KGaA |
| Air Techniques |
| Allied Healthcare Products |
| ConvaTec Inc. |
| Medela AG |
| Ohio Medical Corporation |
| Others |
Supply & Pricing Matrix
Hospital procurement committees in Germany, the United States, and Japan concentrate purchasing authority for central vacuum infrastructure, locking in contract-based long-term offtake pricing with multi-year service attachments. This buyer concentration compresses vendor margins while elevating the strategic value of aftermarket service revenue streams.
Pricing Analysis
Short lead-time premiums command substantial markups in emergency replacement scenarios for surgical theater vacuum systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated configurations from CE-marked alternatives and uncertified commodity units. Cost compression in mid-tier equipment is intensifying because stainless steel and specialty alloy input volatility erodes manufacturer margins. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, while Japanese tertiary hospitals prioritize certification grade over unit economics.
Supply Chain Analysis
Refurbishment flows for rotary vane vacuum pumps create secondary market circulation that tempers new equipment pricing in European hospital systems. Precision vacuum sensor manufacturing clusters in Germany, precision casting operations concentrate in Japan, and control module assembly anchors in the United States. Component sourcing draws from specialty alloy foundries, precision-machined rotors, and IEC-certified microcontrollers. Single-source vulnerability in Baden-Württemberg sensor supply creates geographic concentration risk. Distribution runs through specialized medical gas system integrators rather than direct OEM-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Medical Vacuum System Market functions as a cost-of-compliance arena where EU Medical Device Regulation post-market surveillance mandates through EUDAMED registration erect substantial barrier-to-entry moats for validated equipment suppliers.
For Market Incumbents: To counter service contract unbundling by United States health systems, Atlas Copco AB and Gardner Denver Holdings should deepen captive supply of precision vacuum sensors through backward integration into Baden-Württemberg component networks. Certification investment in IEC 62443-compliant remote diagnostics modules secures positioning in Japanese PMDA cybersecurity premarket pathways. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the lowest-friction entry vector for modular central vacuum networks in India's tier-2 and tier-3 cities under Ayushman Bharat infrastructure expansion. Home healthcare respiratory therapy portable suction devices in post-acute United States settings represent the most penetrable white-space segment with minimal incumbent saturation. For Investors and Strategic Acquirers: The window for entry favors specialized vacuum pure-plays with dry-running scroll technology portfolios aligned to laboratory diagnostics contamination-free migration. Long-term viability hinges on software-enabled service model transition rather than hardware-centric revenue. FDA 510(k) cybersecurity documentation submission volumes signal inflection timing for connected infrastructure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EUDAMED Registration Compliance | Accelerates replacement cycles for legacy vacuum equipment in European surgical centers. |
| IEC 62443 Cybersecurity Certification | Enables PMDA premarket approval for networked vacuum systems in Tokyo and Osaka medical centers. |
| Backward Integration into Sensor Manufacturing | Reduces geographic concentration risk from Baden-Württemberg precision vacuum component clusters. |
| Modular Central Vacuum Network Deployment | Captures tier-2 and tier-3 city demand under India's Ayushman Bharat hospital infrastructure expansion. |
| Software Companion Development | Supports building management platform integration for United States health system energy monitoring requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital biomedical engineers, GPO contracts managers, medical gas system integrators, and regulatory affairs specialists at vacuum equipment manufacturers. FDA 510(k) premarket notification databases, EU EUDAMED registration records, ISO 7396-1 pipeline certification registries, and hospital procurement databases provided quantitative grounding. Bottom-up equipment unit estimates and top-down infrastructure spending projections were cross-validated through triangulation.
Segment-level volume and value outputs were reconciled across product type, technology architecture, clinical application, and end-user facility category throughout the forecast period. CAGRs were derived from installed base turnover modeling and replacement cycle acceleration factors. Forecast inputs incorporated EU MDR compliance deadlines, PMDA cybersecurity review timeline extensions, and outpatient procedural volume trajectories in United States ambulatory surgical centers.
The model holds under stable regulatory enforcement intensity and continuous hospital infrastructure modernization commitment; deviation in trade policy affecting specialty alloy inputs or cybersecurity premarket requirement scope shifts would revise trajectory. Practitioners should monitor FDA guidance document updates for connected device documentation and German precision component export licensing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Operating Light Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Blood Bank Refrigerators Market