
 Transportation Condensing Units Market | 2026-2036
Transportation Condensing Units Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Condensing Units Market Analytics
Aftermarket service revenue is reshaping profit pools across the transportation condensing unit value chain. Thermo King leverages its installed base of transport refrigeration units to capture recurring maintenance contracts. Carrier Global Corporation anchors North American fleet retrofit demand through extensive dealer networks. Daikin Industries, Ltd. competes in Asia-Pacific with localized manufacturing and region-specific product configurations.
Transportation condensing units are self-contained refrigeration systems that compress and liquefy refrigerant vapor using compressors rated between 2 and 50 horsepower, delivering cooling capacities from 5,000 to 120,000 BTU per hour for mobile cold-chain applications. Their primary purpose is maintaining precise temperature corridors for perishable cargo across trucks, trailers, railcars, and marine containers. Scroll compressor technology dominates mid-duty logistics fleets due to superior energy efficiency and reduced vibration profiles compared to reciprocating alternatives. Air-cooled condensing units occupy the largest product share because they eliminate water infrastructure dependencies in mobile environments. Distributed installation architectures are gaining traction among pharmaceutical shippers requiring redundant temperature control across multi-zone trailers.
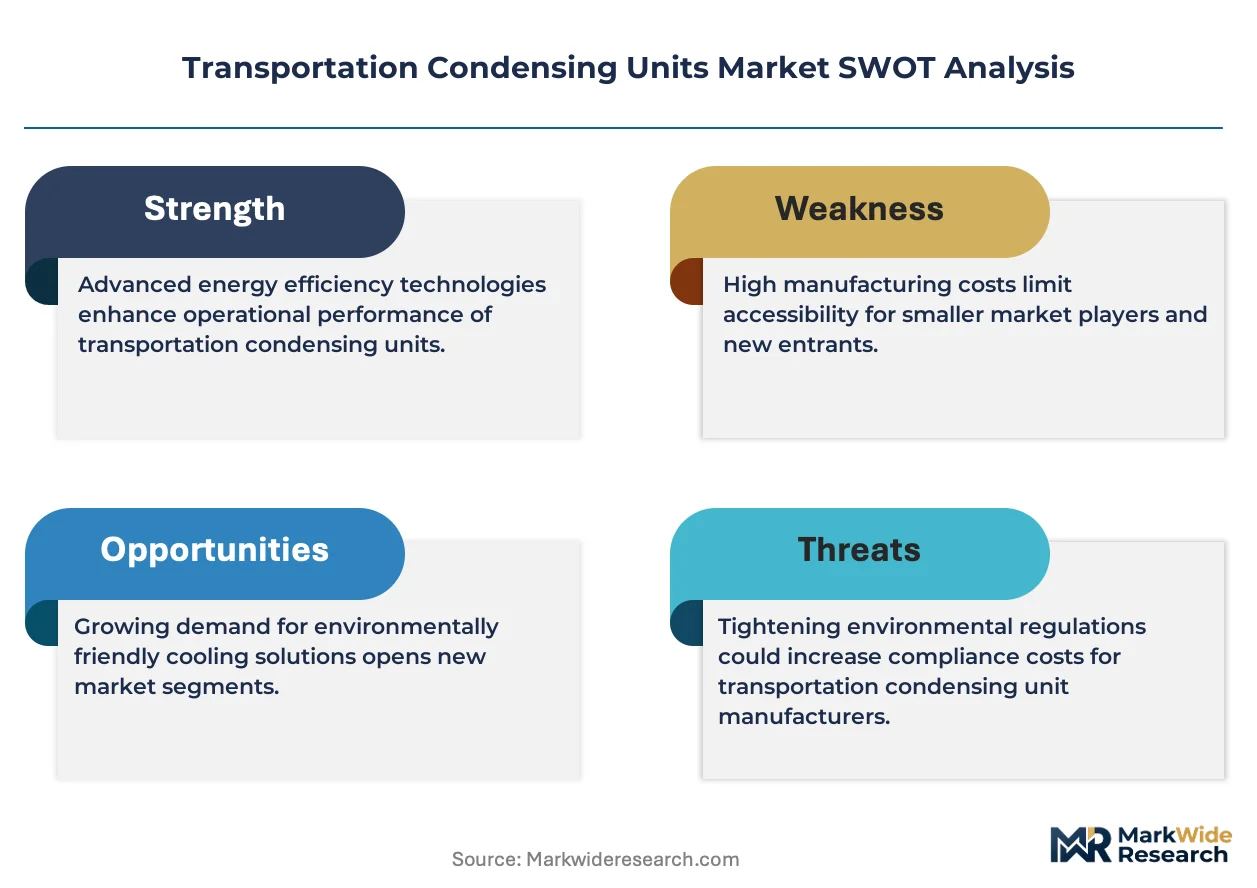
The EPA enforces refrigerant phase-down schedules under the AIM Act, compelling manufacturers to redesign systems around lower-GWP alternatives like R-452A and R-1234yf. The EU F-Gas Regulation imposes progressively stricter quotas on hydrofluorocarbon consumption, directly limiting market access for non-compliant equipment. Fleet operators and OEM procurement teams must monitor refrigerant transition timelines and compressor compatibility roadmaps to avoid stranded asset risk in refrigerated transport fleets.
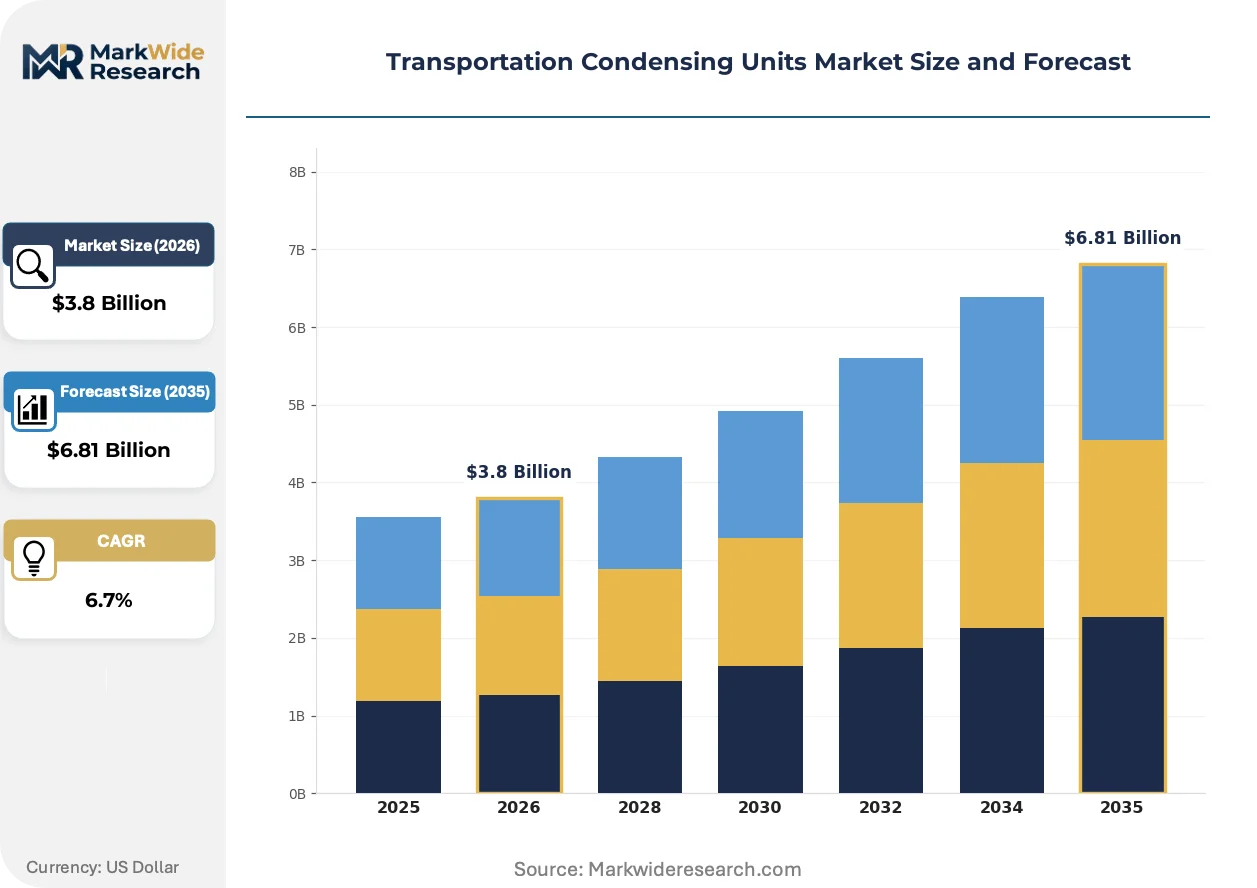
Market Dynamics
Refrigerant chemistry transitions under the EPA AIM Act and EU F-Gas Regulation are forcing compressor redesign cycles across transportation condensing unit portfolios, compressing product development timelines while expanding validation costs for fleet-grade thermal systems.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Biologics distribution networks require redundant temperature zones in multi-compartment trailers, driving specification upgrades for distributed condensing architectures.
- EU F-Gas Regulation:Hydrofluorocarbon quota reductions accelerate fleet replacement schedules as operators preempt non-compliant equipment obsolescence.
- Scroll compressor adoption:Energy efficiency mandates in Germany favor scroll technology over reciprocating alternatives for mid-duty logistics applications.
Market Restraints
- Copper and aluminum price volatility:Raw material input swings compress OEM margins on air-cooled condenser coil production.
- Compressor supply concentration:Critical component sourcing clusters in East Asian manufacturing hubs expose fleets to extended lead times.
- R-1234yf thermodynamic limitations:Lower cooling capacity per refrigerant mass requires larger compressor displacement for equivalent BTU output.
Strategic Opportunities
- Indian cold-chain infrastructure:FSSAI food safety mandates and PLI scheme incentives create first-mover positioning for transport refrigeration OEMs.
- Rail intermodal integration:Refrigerated railcar specifications converge with over-the-road trailer standards, enabling unified condensing unit platforms.
- Predictive maintenance convergence:IoT sensor networks and compressor telemetry unlock outcome-based service contracts for fleet operators.
Industry Challenges
- Refrigerant handling certification:EPA Section 608 technician requirements constrain service network expansion for lower-GWP alternatives.
- Legacy fleet retrofit complexity:R-452A compatibility gaps in aging compressor architectures force premature asset retirement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Condensing Units Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Evaporative, Hybrid Technology: Reciprocating Compressors, Scroll Compressors, Screw Compressors, Centrifugal Compressors End User: Logistics, Transportation, Food and Beverage, Pharmaceuticals Installation: Onboard Systems, Centralized Systems, Distributed Systems, Modular Systems |
| Companies Covered | Thermo King, Daikin Industries, Ltd., Emerson Electric Co., Mitsubishi Electric Corporation, BITZER Kühlmaschinenbau GmbH, Carrier Global Corporation, GEA Group Aktiengesellschaft, Johnson Controls International plc, Danfoss A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Condensing Units Market Evolving Landscape
Digital twin architectures are compressing validation cycles for transport refrigeration systems. Fleet operators now demand real-time thermal performance visibility across multi-modal cargo movements.
Telematics-integrated condensing units are virtualizing compressor diagnostics and predictive fault detection. Pharmaceutical shippers in Germany and the Netherlands adopt these systems fastest. The technology is virtualizing traditional scheduled maintenance intervals into condition-based interventions.
The EPA enforces refrigerant phase-down schedules that accelerate lower-GWP compressor platform development. Equipment manufacturers must maintain dual refrigerant compatibility across transitional model years. Heavy-duty long-haul fleets face the steepest compliance cost curves under these mandates.
Fleet procurement teams unbundle after-sales service from equipment purchase contracts. Third-party cold-chain logistics providers in North America now source maintenance separately through specialized service networks. This pattern concentrates in temperature-sensitive pharmaceutical distribution verticals.
Transportation Condensing Units Market Segmentation
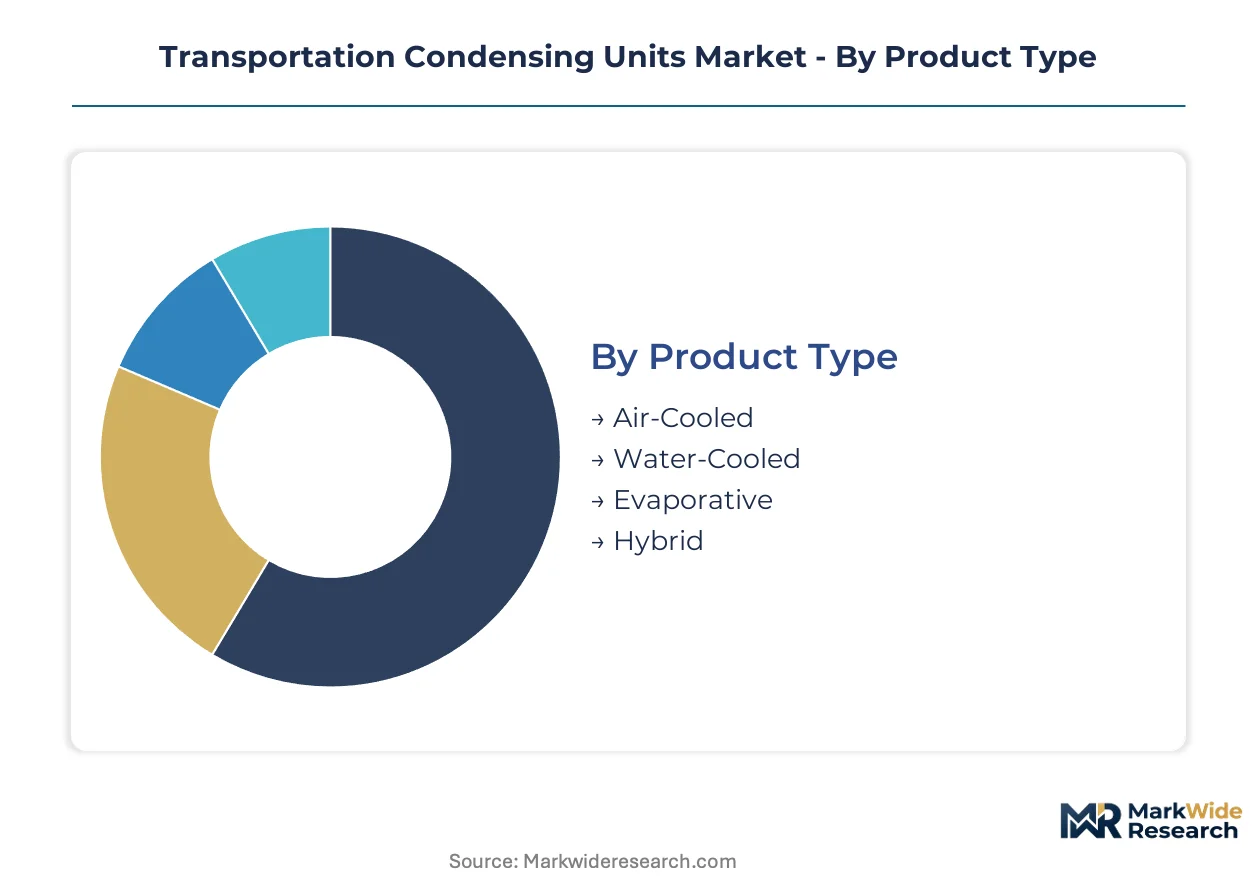
Segmentation in transportation condensing units determines service contract structures and spare parts forecasting accuracy. Fleet operators specify architectures based on cargo temperature sensitivity, route duration, and multi-modal transfer requirements. Procurement teams align compressor technology choices with refrigerant transition timelines and regional maintenance network density.
Product Type:
After-sales-service intensity varies sharply across cooling architectures, with coil maintenance schedules and refrigerant recharge frequencies driving lifetime cost divergences.
- Air-Cooled:These systems reject heat through finned aluminum coils and electric fans, eliminating water infrastructure dependencies in mobile environments. Demand concentrates in over-the-road trucking fleets across Germany and the United States, where route flexibility outweighs efficiency penalties in humid climates.
- Water-Cooled:Higher heat rejection efficiency suits marine container applications and rail intermodal terminals with reliable water access. Pharmaceutical shippers in the Netherlands specify these for port-adjacent cold storage yards where ambient temperatures spike seasonally.
- Evaporative:Adiabatic cooling pads reduce condensing temperatures in arid regions. Operators in Arizona and Nevada deploy these for desert corridor routes.
- Hybrid:Switching logic between air-cooled and evaporative modes optimizes energy use across climate zones. Emerging specifications in Australia target transcontinental rail corridors.
Air-cooled systems hold the largest share; momentum sits with hybrid architectures as multi-modal operators seek climate-adaptive flexibility.
Technology:
Compressor selection dictates capital expenditure tiers and determines compatibility with lower-GWP refrigerant formulations under EPA and EU F-Gas mandates.
- Scroll Compressors:Orbiting scroll geometry delivers 15-20% efficiency gains over reciprocating alternatives with reduced vibration transmission to cargo. German mid-duty logistics fleets specify these under national energy efficiency ordinances, with Carrier and Thermo King dominating retrofit demand.
- Reciprocating Compressors:Piston-driven compression remains cost-effective for small-capacity applications below 15 horsepower. Food distributors in India favor these for last-mile refrigerated three-wheelers where acquisition cost sensitivity dominates.
- Screw Compressors:Helical rotor pairs handle large refrigerant volumes for heavy-duty long-haul trailers. Deployment concentrates in North American pharmaceutical distribution corridors.
- Centrifugal Compressors:High-speed impeller designs suit railcar and marine container scale. Limited adoption reflects specialized maintenance requirements.
Scroll technology commands the dominant installed base; screw compressors are climbing the fastest as heavy-duty fleets expand refrigerated capacity.
End User:
Customer-type segmentation reveals divergent specification priorities, with pharmaceutical and food safety regulations imposing distinct validation and documentation burdens.
- Logistics:Third-party cold-chain operators require modular architectures supporting rapid fleet reconfiguration across contract transitions. Temperature audit trails for FDA and EMA compliance drive telematics integration.
- Transportation:Asset-light trucking companies prioritize acquisition cost minimization and dealer network proximity over advanced efficiency specifications.
- Food and Beverage:Perishables distributors face FSSAI mandates in India and USDA inspection protocols in the United States, requiring redundant cooling capacity.
- Pharmaceuticals:Biologics shippers in Germany and Switzerland specify distributed multi-zone systems with independent compressor redundancy for high-value cargo.
Logistics providers represent the largest revenue pool; pharmaceuticals are expanding most quickly as biologics distribution networks proliferate.
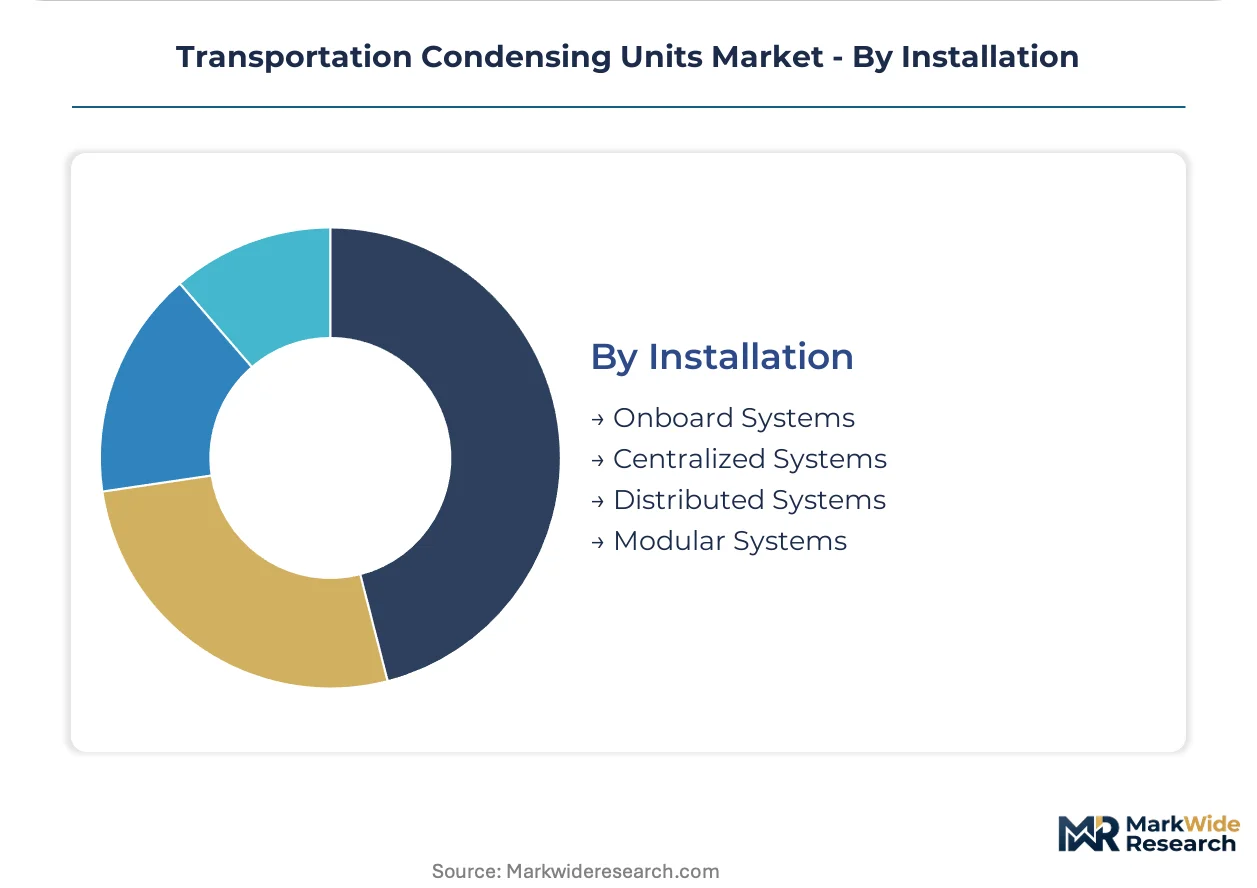
Installation:
System architecture determines upfront engineering costs and ongoing service accessibility, with distributed and modular designs fragmenting supplier relationships across component tiers.
- Onboard Systems:Self-contained units mount directly to truck chassis or trailer frames, integrating compressor, condenser, and evaporator in single enclosures. Dominant specification for North American over-the-road fleets.
- Centralized Systems:Single large-capacity units serve multiple cargo zones through ducted air distribution. Rail intermodal operators in Europe favor these for uniform temperature maintenance across extended carriages.
- Distributed Systems:Multiple independent condensing units zone temperature control precisely, enabling simultaneous frozen and refrigerated compartments. Pharmaceutical shippers mandate these for multi-compartment trailers.
- Modular Systems:Swappable compressor and condenser modules reduce downtime during peak season fleet utilization. Emerging preference among Indian cold-chain startups seeking asset flexibility.
Onboard systems retain the largest installed base; distributed architectures are gaining share fastest as temperature-sensitive cargo diversification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian fleet operators prioritize acquisition cost above efficiency specifications, while German pharmaceutical shippers absorb premium pricing for redundant temperature control systems.
United States
Third-party cold-chain logistics providers expand refrigerated fleet capacity along pharmaceutical distribution corridors between New Jersey and Illinois. EPA AIM Act refrigerant phase-down mandates accelerate compressor platform transitions toward lower-GWP alternatives. Carrier Global Corporation anchors retrofit demand through extensive dealer networks concentrated in the Midwest and Southeast.
Germany
Automotive OEMs and commercial vehicle builders anchor regional procurement of scroll compressor systems for mid-duty logistics applications. National energy efficiency ordinances favor technology transitions away from reciprocating alternatives. The KBA enforces stringent vehicle refrigeration performance standards that compress product validation timelines for transport equipment suppliers.
India
FSSAI food safety mandates and PLI scheme incentives create first-mover positioning for transport refrigeration OEMs entering cold-chain infrastructure buildouts. Last-mile refrigerated three-wheeler demand concentrates acquisition-sensitive procurement on cost-optimized reciprocating compressor configurations. Fleet operators in Maharashtra and Gujarat prioritize modular system architectures supporting rapid asset reconfiguration.
Netherlands
Pharmaceutical shippers specify water-cooled condensing units for port-adjacent cold storage yards where ambient temperatures spike seasonally. EU F-Gas Regulation hydrofluorocarbon quotas accelerate fleet replacement schedules ahead of compliance deadlines. Rotterdam's intermodal terminals drive specifications converging marine container and over-the-road trailer refrigeration standards.
China
Domestic cold-chain logistics operators expand refrigerated truck capacity along coastal manufacturing belts serving export-oriented food processing clusters. MEE enforcement of dual carbon goals pressures compressor manufacturers toward energy-efficient platform development. Yangtze River Delta fleet operators test hybrid air-cooled and evaporative systems for transcontinental route optimization.
Transportation Condensing Units Market Competitive Landscape
Capability concentration sits with specialized compressor technology developers; scale advantage sits with diversified thermal systems conglomerates. The vendor base stratifies across three tiers: integrated transport refrigeration OEMs, component-focused compressor specialists, and diversified industrial automation conglomerates. Two dominant competitive moves define current positioning: backward integration into refrigerant handling certification networks and geographic expansion through localized manufacturing joint ventures.
Among integrated transport refrigeration specialists, Thermo King and Carrier Global Corporation exemplify the installed-base leverage archetype, converting recurring maintenance contracts into defensive revenue streams. Daikin Industries, Ltd. occupies a position within the Asia-Pacific manufacturing optimization tier. BITZER Kühlmaschinenbau GmbH represents the European compressor technology concentration archetype. These three anchors illustrate divergent strategic postures: fleet service network density, regional manufacturing localization, and component technology specialization respectively.
| Leading Market Players |
|---|
| Thermo King |
| Daikin Industries, Ltd. |
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| BITZER Kühlmaschinenbau GmbH |
| Carrier Global Corporation |
| GEA Group Aktiengesellschaft |
| Johnson Controls International plc |
| Danfoss A/S |
| Others |
Value Network & Pricing Analysis
Overcapacity in East Asian compressor manufacturing clusters is compressing supplier margins while simultaneously granting procurement leverage to North American fleet operators negotiating multi-year service contracts. This utilization imbalance feeds directly into pricing posture: OEMs absorb cost volatility on air-cooled condenser coils to defend installed-base relationships, while passing aluminum and copper swings through to spot-market buyers.
Pricing Analysis
Long-term offtake agreements dominate fleet procurement, with pharmaceutical shippers locking three-to-five-year contracts bundling equipment and predictive maintenance telemetry. Three-tier pricing structure across premium, standard, and economy levels separates redundant distributed systems from single-compressor configurations. Cost compression in entry-tier reciprocating units is intensifying because Indian last-mile operators prioritize acquisition cost over efficiency specifications. Logistics providers exhibit highest price sensitivity; biologics distributors absorb premiums for independent zone redundancy.
Supply Chain Analysis
Export-control regimes on high-efficiency compressor motors limit technology flows from Germany and Japan to certain end-markets, fragmenting sourcing strategies. Manufacturing concentrates in China, Germany, and the United States, with scroll compressor production anchored in German automotive supplier networks. The supply chain draws from copper and aluminum coil suppliers, refrigerant chemical producers, and precision motor winders. Single-source vulnerability concentrates in East Asian semiconductor components for IoT-integrated units. Distribution runs through OEM captive service networks and third-party cold-chain specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting around telematics-integrated compressor diagnostics, where interoperability between fleet management systems and condensing unit telemetry creates winner-take-most dynamics. The shift from scheduled to condition-based maintenance contracts restructures margin capture toward data-enabled service providers.
For Market Incumbents: Harden defensive positions by deepening backward integration into refrigerant handling certification networks, constraining service network expansion by non-compliant competitors. Add scroll compressor capacity in Germany to preempt EU F-Gas quota-driven demand surges. Incumbent leverage rests on installed-base telemetry conversion to recurring revenue contracts. For New Entrants and Emerging Players: Indian cold-chain infrastructure buildouts represent the most penetrable white-space, where FSSAI mandates and PLI incentives lower entry barriers for modular system architectures. Target Maharashtra and Gujarat fleet operators seeking rapid asset reconfiguration capabilities. Partner with local three-wheeler OEMs for last-mile reciprocating compressor integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across distributed multi-zone systems as pharmaceutical compliance requirements expand engineering validation burdens. Long-term viability favors targets with captive refrigerant platform development and telematics integration capabilities. Watch EPA refrigerant phase-down enforcement velocity as inflection indicator for fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | EPA AIM Act and EU F-Gas Regulation mandates force lower-GWP compressor redesign cycles across OEM portfolios. |
| Predictive Maintenance Integration | IoT sensor networks and compressor telemetry unlock outcome-based service contracts for pharmaceutical fleet operators. |
| Geographic Manufacturing Localization | Joint ventures in India and China reduce tariff exposure and align with PLI scheme incentive structures. |
| Modular System Architecture Development | Swappable compressor modules reduce downtime for Indian cold-chain startups seeking asset flexibility. |
| Refrigerant Handling Certification Expansion | EPA Section 608 compliance networks constrain competitor service network growth in lower-GWP transitions. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement managers, aftermarket service directors, compressor engineering leads, and cold-chain logistics operators and refined through secondary validation. Primary interviews combined with regulatory filing analysis, customs trade data, OEM technical documentation, and fleet operator maintenance records. Bottom-up unit economics triangulated against top-down market sizing across product type, compressor technology, end-user vertical, and installation architecture segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include cooling architecture, compressor technology tier, cargo temperature sensitivity, route duration category, and regional regulatory cluster. CAGRs derived from installed-base growth rates, fleet replacement cycle timing, and refrigerant transition compliance deadlines. Industry-specific inputs incorporated pharmaceutical distribution network expansion and rail intermodal specification convergence.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric refrigeration challengers or hydrogen fuel cell entrants would shift outcomes. Material shifts in EPA refrigerant phase-down enforcement velocity or EU F-Gas quota allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market