
 Czech Republic Road Freight Transport Market | 2026-2036
Czech Republic Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Road Freight Transport Market Outlook
Euro VI emission compliance is collapsing the competitive set toward operators with capital reserves for fleet renewal. DSV A/S leverages its integrated European network to sustain cross-border volumes through Czech distribution hubs. Raben Group anchors temperature-controlled capacity for pharmaceutical and food clients across the country. Geis Group specializes in dedicated contract logistics for automotive suppliers clustered near Ostrava.
Czech Republic road freight transport encompasses the movement of goods by motor vehicle over public road networks, utilizing tractor-trailers with gross combination weights up to forty tonnes and specialized bodies including refrigerated units, flatbeds, and curtain-sided configurations designed for palletized, bulk, or temperature-sensitive cargo. Full truck load services dominate corridor flows between industrial zones, while refrigerated trucks command premium pricing from pharmaceutical end users requiring GDP-validated cold chain integrity. Less than truck load networks consolidate margin pools around Prague and Brno terminal infrastructure, though dedicated freight contracts with automotive OEMs lock in the most predictable revenue streams.
The European Union's Mobility Package enforcement through the Czech Ministry of Transport reshapes driver posting rules and cabotage access for international operators. EU Green Deal emission benchmarks, transposed via national climate legislation, mandate progressive CO2 reductions that filter fleet procurement toward alternative fuels. The State Transport Policy Office coordinates infrastructure investment priorities with these regulatory timelines. Stakeholders must weigh the capital intensity of zero-emission vehicle transitions against the contracting window for diesel asset residual values.
Market Dynamics
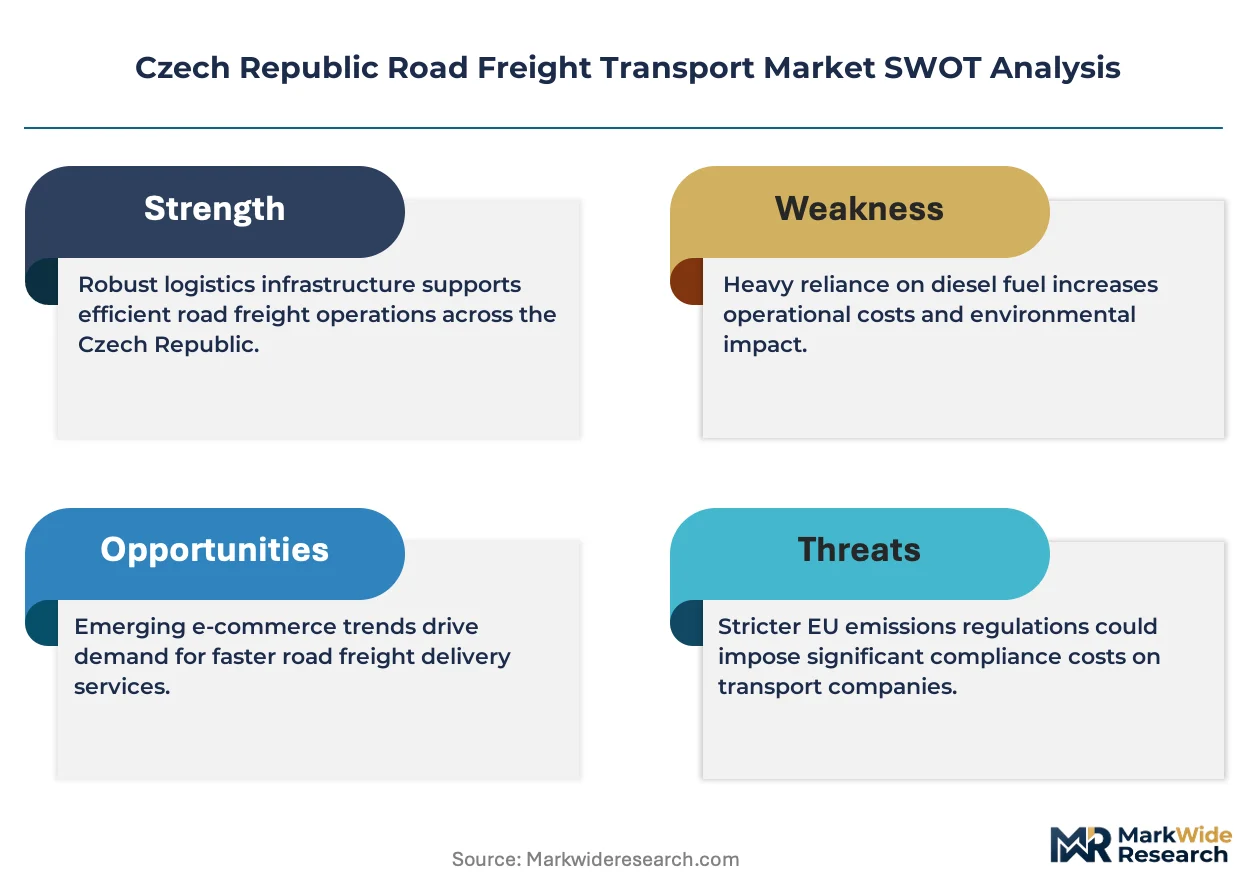
The EU Green Deal's emission benchmarks are compressing diesel asset residual values while forcing capital reallocation toward alternative drivetrains across Czech fleet operations.
Growth Catalysts
- Central Bohemia industrial clustering:Automotive OEM expansion around Prague and Mladá Boleslav is generating dedicated contract logistics demand with multi-year volume commitments.
- EU Mobility Package posting rules:Harmonized driver regulations are reducing administrative friction for cross-border operators serving Czech distribution hubs.
- Temperature-controlled pharmaceutical flows:GDP-validated cold chain requirements from biologics manufacturers are commanding premium rate structures on refrigerated capacity.
Market Restraints
- Zero-emission vehicle capital intensity:Battery-electric and hydrogen tractor procurement requires fleet operators to absorb three-to-five-year payback periods against contracting diesel resale markets.
- Driver availability constraints:Czech Ministry of Transport licensing throughput and demographic shifts are tightening qualified operator supply faster than automation can offset.
- Border infrastructure bottlenecks:Corridor congestion on D1 motorway segments between Prague and Brno is extending transit times and eroding schedule reliability for time-definite services.
Strategic Opportunities
- Moravian-Silesian automotive supplier density:Ostrava-region component manufacturers remain underserved by dedicated contract logistics relative to their production volumes.
- Last-mile electrification incentives:National climate legislation subsidies for urban zero-emission delivery vehicles are creating favorable total-cost-of-ownership economics for regional parcel consolidation networks.
- Pharmaceutical cold chain GDP certification:Regulatory tailwinds from the EU's tightened good distribution practice enforcement are differentiating certified operators in a fragmented temperature-controlled market.
Industry Challenges
- Telematics integration with legacy fleet management systems:Real-time tracking and predictive maintenance platforms require costly middleware development to interface with decade-old dispatch software.
- Alternative fuel infrastructure timing risk:Fleet procurement decisions must anticipate hydrogen and megawatt-charging corridor deployment schedules that remain provisional under State Transport Policy Office planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Road Freight Transport Market |
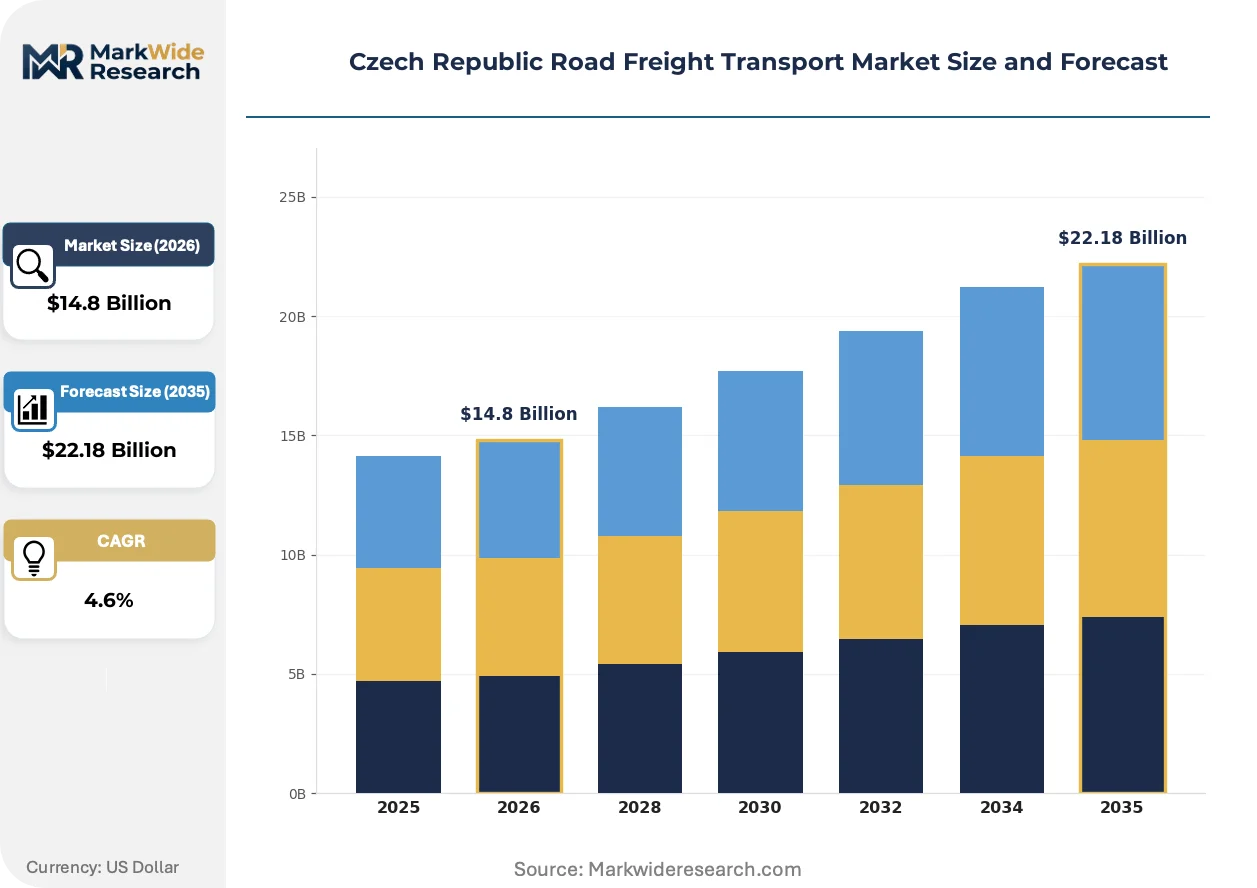
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Intermodal, Dedicated Freight Vehicle Type: Flatbed, Refrigerated Truck, Box Truck, Tanker End User: Manufacturing, Retail, Automotive, Pharmaceuticals Delivery Model: Door-to-Door, Terminal-to-Terminal, Expedited, Scheduled |
| Companies Covered | DSV A/S, Raben Group, Geis Group, DACHSER, Deutsche Bahn AG, AGROFERT AS, CMA CGM Group, Smidl Holding, Unterer Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Road Freight Transport Market Strategic Shifts
Digital freight matching and predictive analytics are restructuring how Czech operators allocate capacity, price spot movements, and manage asset utilization across volatile corridor demand.
Battery-electric tractors with 400-plus kilometer range are supplanting diesel units on predictable regional loops between Prague, Brno, and Ostrava. Food retailers with fixed distribution schedules are piloting overnight depot charging configurations. This transition is compressing maintenance revenue pools for traditional engine-overhaul service networks while shifting lifecycle value toward battery management and charging infrastructure operators.
The EU Green Deal's CO2 emission performance standards for heavy-duty vehicles are mandating progressive fleet average reductions through 2030. Czech operators must now weigh acquisition timing against anticipated technology cost curves and residual value collapse for internal combustion assets. Pharmaceutical and automotive verticals with Scope 3 reporting obligations are accelerating carrier selection criteria toward verified emission disclosure.
Shippers are consolidating freight procurement onto platform-based tendering systems that compress contract duration from annual to quarterly cycles. Large manufacturing accounts in Central Bohemia are disintermediating traditional freight forwarder relationships through direct carrier connectivity. This pattern is most pronounced among automotive OEMs with sufficient volume to justify dedicated lane negotiations and internal freight optimization teams.
Czech Republic Road Freight Transport Market Segmentation
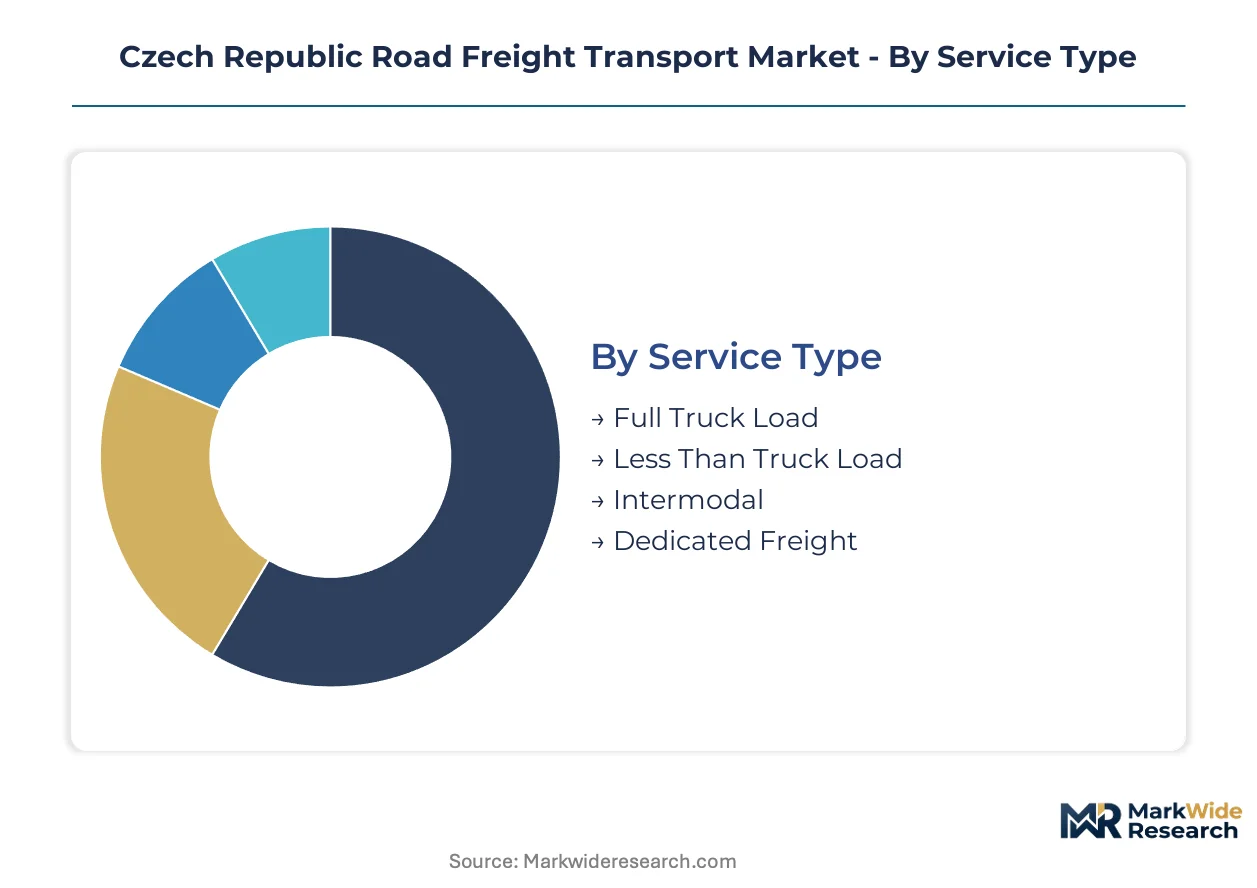
Road freight segmentation in the Czech Republic reveals how service specialization, vehicle configuration, and delivery urgency map onto distinct margin architectures across the Prague-Brno-Ostrava corridor. Understanding these divisions exposes where capital deployment yields defensive positioning versus commodity exposure.
Service Type:
Margin pools concentrate in contracted capacity arrangements rather than spot-market exposure, with multi-year automotive agreements commanding rate premiums over transactional freight.
- Full Truck Load:Dedicated tractor-trailer units moving complete shipments for single shippers dominate corridor flows between Central Bohemia automotive plants and Moravian-Silesian supplier parks. OEM production schedules in Mladá Boleslav and Ostrava lock in predictable revenue streams with penalty clauses for service failure.
- Less Than Truck Load:Consolidated shipments from multiple shippers require terminal infrastructure investment around Prague and Brno to achieve density economics. Food retailers and mid-sized manufacturers without sufficient volume for dedicated lanes accept longer transit times in exchange for per-kilogram rate efficiency.
- Intermodal:Rail-road combinations reduce driver hour constraints on long-haul international connections through Czech distribution hubs.
- Dedicated Freight:Exclusive vehicle allocation for single accounts captures the highest rate premiums but requires volume commitments that only pharmaceutical and automotive verticals can sustain.
The dominant share belongs to Full Truck Load, while Dedicated Freight is closing the gap fastest.
Vehicle Type:
Equipment specialization creates tiered rate structures, with temperature-controlled assets capturing premium returns against standardized flatbed commoditization.
- Flatbed:Open-deck configurations for oversized machinery and construction materials face rate pressure from low barriers to entry and minimal differentiation. Central Bohemia industrial projects generate seasonal demand spikes, but year-round utilization depends on cross-border construction equipment movements.
- Refrigerated Truck:Insulated bodies with integrated cooling units command rate premiums from pharmaceutical manufacturers requiring GDP-validated cold chain integrity. Biologics production facilities around Prague and Brno generate consistent backhaul challenges that specialized operators solve through temperature-controlled return cargo arrangements.
- Box Truck:Enclosed dry van bodies handle the majority of palletized consumer goods distribution with standardized loading dimensions.
- Tanker:Specialized liquid and bulk commodity transport requires hazmat certification that limits competitive entry in chemical and fuel logistics.
Box Truck capacity holds the largest fleet share, though Refrigerated Truck deployment is expanding most quickly.
End User:
Vertical-specific service requirements fragment carrier selection criteria, with regulatory compliance and reporting obligations outweighing pure rate competition in certified segments.
- Manufacturing:Industrial shippers prioritize schedule reliability and damage-free handling over pure transportation cost, with just-in-time production systems penalizing late deliveries through contract penalties. Machinery and electronics producers in Central Bohemia generate consistent corridor demand with predictable seasonal patterns.
- Automotive:OEM and tier-one supplier logistics requirements demand sequenced part delivery, real-time tracking integration, and contingency planning for production line stoppages. Škoda Auto's Mladá Boleslav operations anchor dedicated contract logistics with multi-year volume commitments that smaller operators cannot match.
- Retail:Distribution center replenishment and store delivery networks concentrate demand around urban consolidation facilities with time-definite scheduling requirements.
- Pharmaceuticals:GDP certification and temperature documentation requirements create vendor qualification barriers that limit carrier pools and sustain premium rate structures.
Automotive logistics commands the deepest contract penetration, while Pharmaceuticals shows the steepest expansion trajectory.
Delivery Model:
Urgency premiums and infrastructure requirements segment pricing power, with expedited services capturing disproportionate margins relative to asset utilization efficiency.
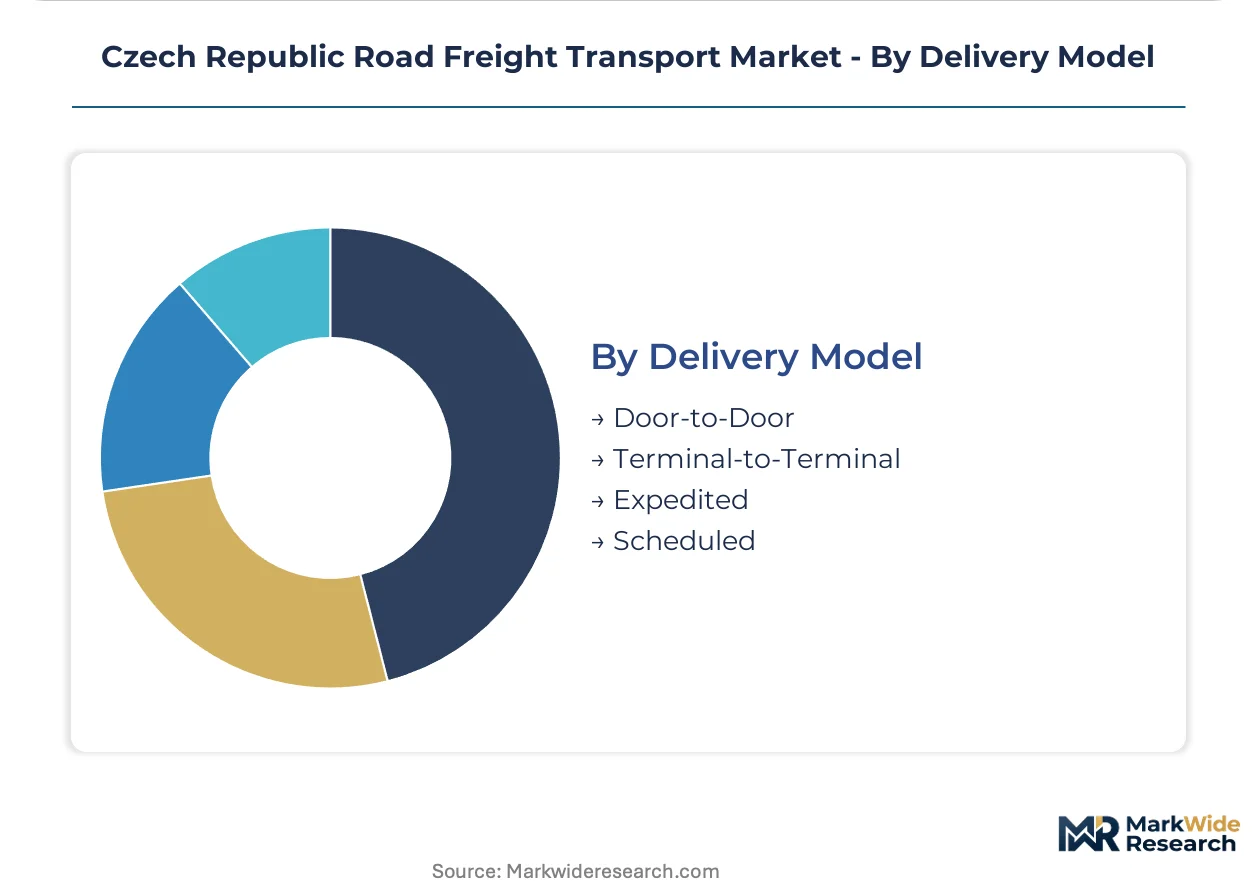
- Door-to-Door:Complete origin-to-destination service eliminates shipper handling requirements and captures full value chain margin. E-commerce fulfillment networks and just-in-time manufacturing in Central Bohemia drive demand for direct delivery without intermediate consolidation.
- Expedited:Time-critical shipments with guaranteed transit windows command rate multiples over standard service, with pharmaceutical emergency supplies and automotive line-down situations generating inelastic demand. Dedicated vehicle allocation and driver team operations inflate cost bases that shippers accept when production stoppage costs exceed transportation premiums.
- Terminal-to-Terminal:Shipper-managed first and last mile reduces carrier responsibility and rate capture in exchange for lower per-kilometer charges.
- Scheduled:Recurring fixed-departure services optimize asset utilization through predictable demand aggregation but limit pricing flexibility.
Door-to-Door service retains the largest volume share, yet Expedited delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Czech road freight capacity concentrates along the Prague-Brno-Ostrava industrial corridor, with terminal infrastructure and fleet assets clustering around Central Bohemia automotive plants and Moravian-Silesian supplier parks. Cross-border flows into Germany, Poland, Austria, and Slovakia absorb the majority of international tonnage, while domestic distribution networks feed e-commerce fulfillment and manufacturing replenishment cycles.
Germany
German automotive OEMs in Bavaria and Saxony generate substantial inbound component flows through Czech distribution hubs, with just-in-time sequences demanding sub-24-hour transit reliability. The EU Mobility Package posting rules, enforced through German Federal Office for Goods Transport oversight, harmonize driver regulations across this high-volume corridor. Dresden and Nuremberg manufacturing clusters anchor dedicated contract logistics lanes into Mladá Boleslav and Ostrava.
Poland
Polish manufacturing expansion in Silesia and Greater Poland Voivodeship is redirecting traditional north-south European flows through Czech territory, with Katowice-region automotive suppliers leveraging Prague-hubbed consolidation. Poland's national climate legislation transposes EU Green Deal benchmarks into fleet procurement mandates that mirror Czech regulatory timelines. The Wrocław industrial zone generates temperature-controlled pharmaceutical movements requiring GDP-validated cold chain handoffs at Czech border terminals.
Austria
Viennese pharmaceutical and machinery exporters utilize Czech LTL networks for cost-efficient distribution into Central European markets, with Linz industrial clusters contributing steel and chemical bulk movements. Austria's Federal Ministry for Climate Action coordinates alternative fuel corridor planning with Czech State Transport Policy Office infrastructure timelines. The Vienna-Brno-Prague triangle supports dedicated freight contracts for automotive sequencing that bypass traditional forwarder intermediation.
Slovakia
Slovak automotive production in Bratislava and Žilina generates synchronized component flows with Czech assembly plants, with cross-border shuttle services operating on fixed departure schedules. Bratislava-based logistics operators exploit EU cabotage liberalization to position capacity within Czech domestic markets. The Košice region's emerging electronics manufacturing is testing dedicated contract logistics models previously deployed in Central Bohemia.
Hungary
Hungarian food processing and automotive suppliers in Győr and Budapest source packaging materials and components through Czech LTL terminals, with Budapest-hubbed operators competing for backhaul capacity into Moravia. Hungary's Ministry of Innovation and Technology administers electric vehicle transition subsidies that align with Czech national climate legislation incentive structures. The Budapest-Brno corridor is attracting battery-electric tractor pilots from operators seeking predictable regional loop economics.
Czech Republic Road Freight Transport Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Czech road freight, with integrated European networks competing against specialized domestic operators for corridor dominance. The market presents a tiered structure: pan-European logistics groups with capital reserves for fleet renewal, mid-sized regional specialists with vertical expertise in temperature-controlled or automotive segments, and fragmented local carriers exposed to diesel asset residual value compression. Strategic differentiation concentrates in contract logistics capability, alternative drivetrain procurement timing, and pharmaceutical cold chain certification. Competitive moves center on dedicated freight contract capture with automotive OEMs and strategic partnerships for charging infrastructure access.
Among integrated European network operators, DSV A/S and DACHSER occupy positions exemplifying cross-border scale advantages, while Raben Group and Geis Group represent specialized regional archetypes with deep vertical expertise in temperature-controlled and automotive contract logistics respectively. These named entities anchor the competitive spectrum: DSV A/S demonstrates the pan-European consolidation model, Raben Group illustrates certification-driven premium positioning, and Geis Group exemplifies dedicated contract logistics specialization in industrial clustering zones. Smidl Holding and Unterer Group sit within the mid-tier regional specialist category, competing through corridor-specific density rather than network breadth. The competitive dynamic pits these archetypes against one another for multi-year automotive contracts and pharmaceutical GDP-certified capacity, with fleet decarbonization timelines becoming the primary selection criterion for sustainability-conscious shippers.
| Leading Market Players |
|---|
| DSV A/S |
| Raben Group |
| Geis Group |
| DACHSER |
| Deutsche Bahn AG |
| AGROFERT AS |
| CMA CGM Group |
| Smidl Holding |
| Unterer Group |
| Others |
Value Chain & Pricing Dynamics
Forty-eight-hour lead-time windows on the Prague-Brno-Ostrava corridor concentrate pricing power with operators holding dedicated terminal infrastructure, while inventory compression at automotive OEMs feeds back into contract rate premiums for guaranteed capacity access.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across Czech road freight, with emission-compliant fleets commanding rate premiums over legacy diesel operators facing residual value collapse. Three-tier pricing stratifies across GDP-certified pharmaceutical cold chain, automotive just-in-time sequencing, and commoditized construction materials flatbed. Cost compression in temperature-controlled segments is intensifying because biologics manufacturers consolidate carrier pools around verified emission disclosure. Food retailers exhibit highest price sensitivity due to thin retail margins, while pharmaceutical emergency supply contracts show inelastic demand.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive verticals, with Škoda Auto's Mladá Boleslav operations maintaining sub-24-hour component cycles that eliminate strategic stockpiling. Manufacturing inputs draw from Germany, Poland, and Slovakia, with Bavarian precision components and Silesian steel anchoring cross-border flows. Battery-electric tractor procurement and hydrogen corridor deployment schedules create single-source vulnerability for fleet operators awaiting infrastructure commitment. Distribution runs through Prague-hubbed LTL terminals for mid-market consolidation, while dedicated freight bypasses intermediate handling entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in Czech road freight transport rests on EU Mobility Package harmonization accelerating cross-border operator penetration into previously fragmented domestic lanes.
For Market Incumbents: Consolidate terminal density around Brno and Ostrava to defend against platform-based freight matching disintermediation. Secure multi-year automotive sequencing contracts before OEMs build internal freight optimization teams. Battery-electric fleet renewal serves as the critical lever for retaining pharmaceutical and automotive accounts with Scope 3 reporting obligations.
For New Entrants and Emerging Players: Anchor in Moravian-Silesian automotive supplier parks, where dedicated contract logistics penetration lags production volume growth. Target GDP-certified cold chain capacity for biologics manufacturers frustrated with incumbent service fragmentation. Go-to-market positioning should emphasize verified emission disclosure and charging infrastructure partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because emission compliance capital requirements will collapse the competitive set toward scaled operators with balance sheet capacity for zero-emission transitions. Acquisition focus centers on mid-sized regional specialists with automotive vertical expertise and terminal infrastructure in Central Bohemia. The signal to watch is diesel asset residual value compression accelerating forced exits among fragmented local carriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Emission Fleet Procurement | Battery-electric tractors with 400-kilometer range secure pharmaceutical contracts requiring verified emission disclosure. |
| GDP Certification Investment | Regulatory tailwinds from tightened EU good distribution practice enforcement differentiate operators in temperature-controlled segments. |
| Dedicated Contract Logistics Expansion | Multi-year agreements with Škoda Auto and tier-one suppliers lock in predictable revenue streams with penalty-backed reliability. |
| Terminal Infrastructure Consolidation | Prague and Brno hub density achieves LTL consolidation economics that platform-based competitors cannot replicate. |
| Charging Infrastructure Partnership | Megawatt-charging corridor access determines viable deployment timing for regional battery-electric loops. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Czech Ministry of Transport regulatory filings, EU Mobility Package implementation guidance, and automotive OEM procurement disclosures. Fleet operators, pharmaceutical logistics managers, and terminal infrastructure directors provided operational perspective. Secondary validation drew from State Transport Policy Office planning documents, customs trade flow data, and vehicle registration databases. Bottom-up capacity modeling triangulates against top-down corridor demand estimates.
Segmentation dimensions modeled span service type, vehicle configuration, end-user vertical, and delivery urgency across the projection horizon. CAGRs derive from fleet size evolution, emission compliance timelines, and industrial production forecasts. Forecast inputs incorporate EU Green Deal CO2 performance standards for heavy-duty vehicles and national climate legislation subsidy trajectories.
Underlying assumptions cover regulatory enforcement consistency, infrastructure deployment schedules, and diesel residual value trajectories, with deviation risk concentrated in alternative fuel corridor timing and driver availability constraints. Revision becomes warranted when battery-electric tractor total-cost-of-ownership economics cross threshold parity against diesel alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
United Kingdom Road Freight Transport Market