
 Boxcar Scars Market | 2026-2036
Boxcar Scars Market Size, Share, and Industry Trends Forecast 2026-2036
Boxcar Scars Market Analysis
Clinical-grade fractional laser specifications is collapsing the gap between medical and aesthetic outcomes. Lumenis Ltd leverages its proprietary pulse-delivery platforms to sustain premium positioning across dermatology networks. Candela Medical differentiates through dual-wavelength systems that anchor its installed base in North American teaching hospitals. Merz Inc. navigates European reimbursement complexity with its integrated training-and-device bundling model.
Boxcar scars constitute deep, sharply demarcated atrophic lesions with vertical walls and flat bases, typically measuring 0.5 to 4 millimeters in diameter, caused by inflammatory acne disrupting collagen architecture in the reticular dermis. Laser Therapy commands the dominant revenue position due to repeat-session economics and capital-equipment lock-in, while Dermal Fillers represent the fastest-expanding margin pool as hyaluronic acid formulations achieve longer residence times. Chemical Peels occupy a mature, price-compressed tier serving mild Grade I presentations, whereas Grade III and Grade IV severity levels concentrate procedural value in physician-directed settings.
FDA 510(k) premarket notification requirements govern device safety and efficacy claims for ablative and non-ablative laser systems in the United States, while the EU MDR framework imposes stricter clinical-evidence thresholds for CE-marked scar-treatment devices across Germany, France, and Italy. HIPAA privacy standards shape patient data management for tele-dermatology consultations that increasingly precede in-office procedures. Stakeholders must monitor evolving FDA guidance on combination-device classification as energy-based platforms integrate real-time temperature feedback.
Market Dynamics
Fractional laser device economics is bifurcating treatment accessibility across dermatology networks, as capital-equipment lock-in concentrates procedural value in physician-directed settings while compressing margins for standalone aesthetic clinics.
Growth Catalysts
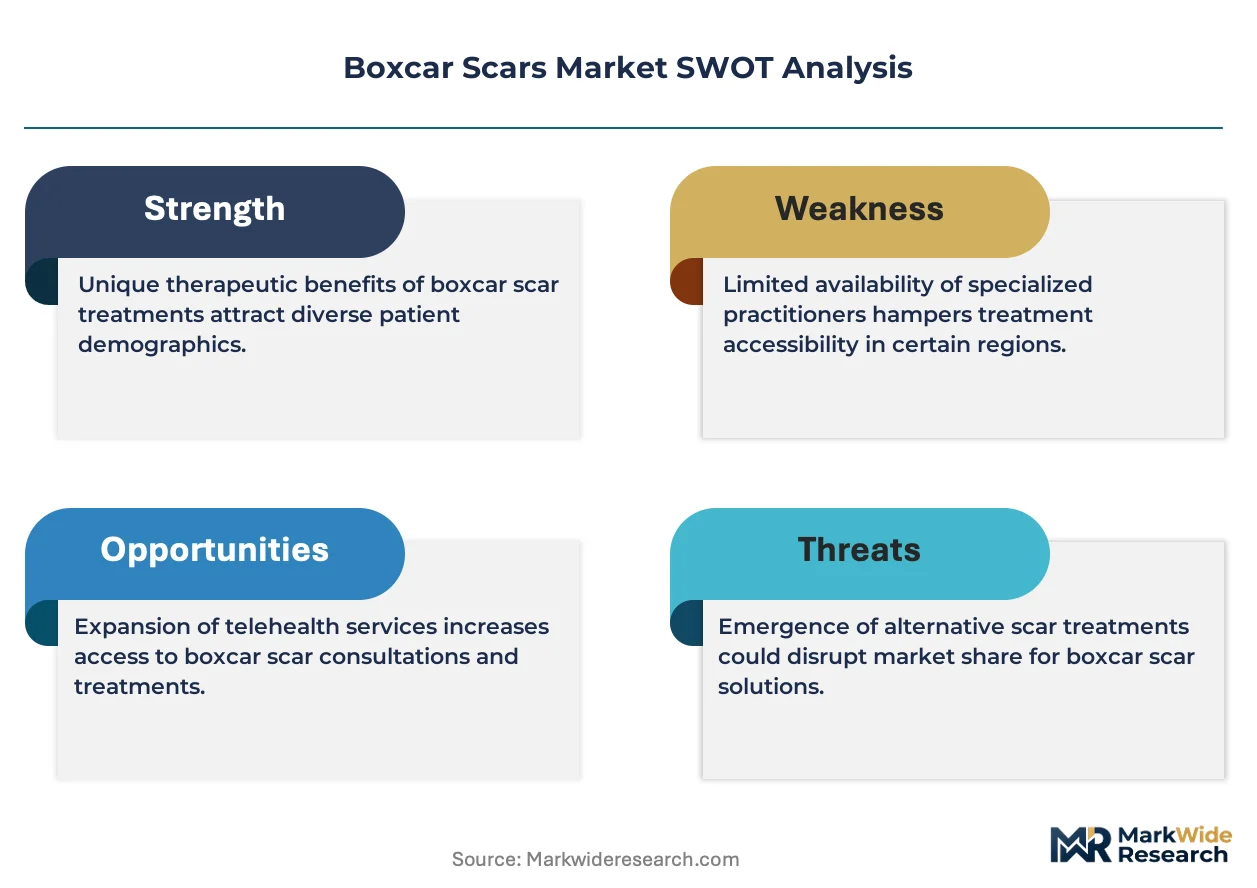
- FDA 510(k) clearance pathways:Streamlined premarket notification for ablative laser systems accelerates competitive entry in the United States, expanding device availability for Grade III and Grade IV scar presentations.
- Hyaluronic acid formulation advances:Extended residence times in next-generation dermal fillers is reshaping repeat-treatment economics and pulling patient volume from temporary camouflage solutions.
- Seoul and Los Angeles clinical clusters:Concentrated dermatology infrastructure in these metropolitan hubs generates protocol standardization and training density that diffuses through international physician networks.
Market Restraints
- Capital intensity of fractional CO2 platforms:Six-figure equipment costs and maintenance contracts create barriers to entry for mid-tier aesthetic practices, concentrating supply in hospital-affiliated dermatology departments.
- EU MDR clinical-evidence thresholds:Stricter documentation requirements for CE-marked scar-treatment devices extend approval timelines and inflate regulatory compliance costs across Germany, France, and Italy.
- Non-ablative laser substitution:Lower-downtime alternatives capture mild-to-moderate scar cases, compressing addressable volume for premium ablative protocols.
Strategic Opportunities
- Tele-dermatology consultation precedents:HIPAA-compliant remote triage workflows expand patient funnel efficiency, converting digital inquiries into in-office procedural bookings.
- Combination-device classification guidance:Evolving FDA frameworks for energy-based platforms with integrated temperature feedback create first-mover advantages for real-time safety systems.
- Integrated training-and-device bundling:European reimbursement complexity favors commercial models that wrap physician education into capital sales, locking in installed base loyalty.
Industry Challenges
- Fractional laser technician certification pipelines:Shortage of credentialed operators capable of adjusting pulse parameters for varying scar depths limits throughput in high-volume clinics.
- Legacy electronic health record integration:Scar photography documentation and treatment planning modules require custom API development, delaying deployment of connected device ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boxcar Scars Market |
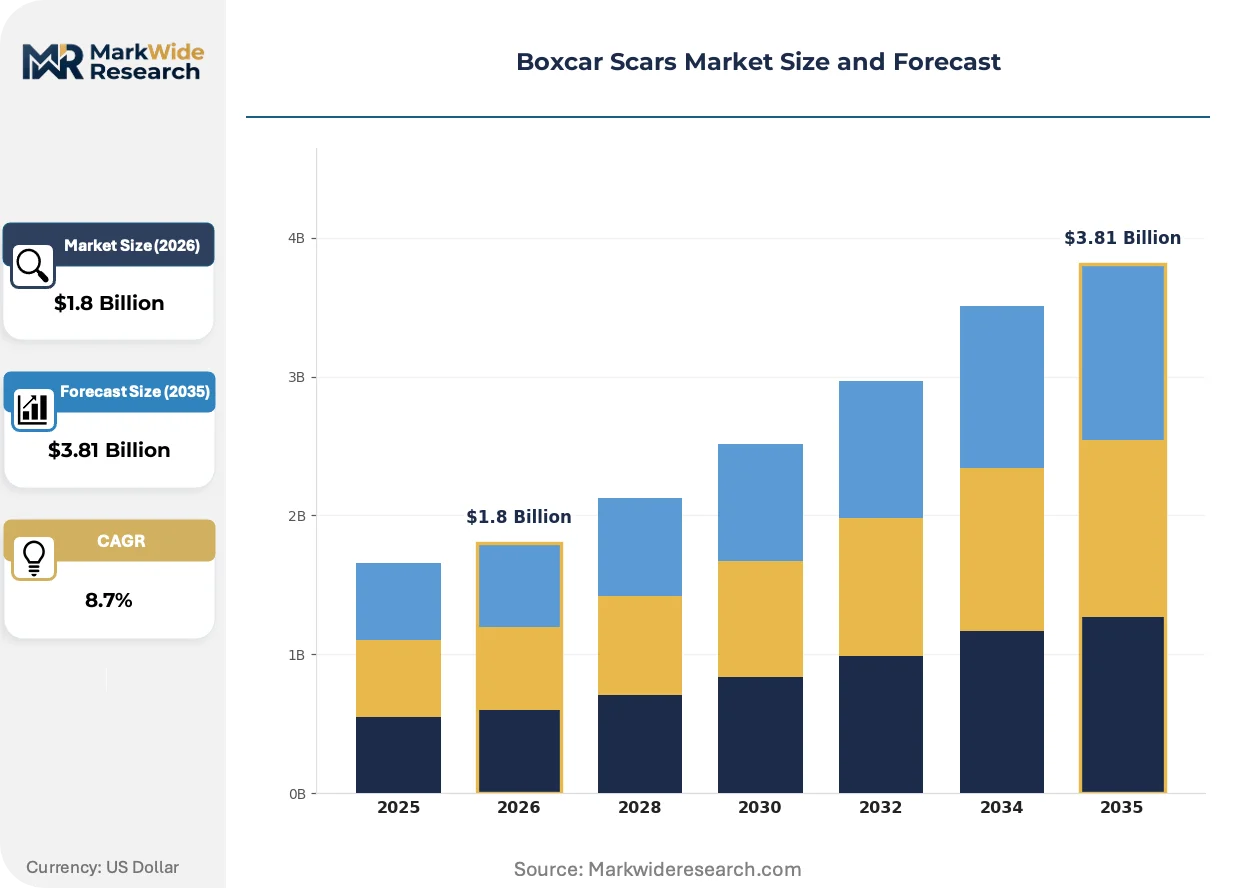
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Laser Therapy, Microdermabrasion, Chemical Peels, Dermal Fillers Patient Demographics: Teenagers, Adults, Middle-Aged, Elderly Severity Level: Grade I, Grade II, Grade III, Grade IV Application Area: Face, Back, Neck, Chest |
| Companies Covered | Lumenis Ltd, Merz Inc., Cynosure Inc., Cutera, Inc., CeraVe, Bausch Health Companies Inc., Sonoma Pharmaceuticals Inc., Smith & Nephew plc, Candela Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boxcar Scars Market Emerging Trajectories
Clinical-grade specifications is collapsing boundaries between medical and aesthetic outcomes, forcing competitive repositioning across device manufacturers and treatment protocols.
Non-ablative fractional laser technology is bifurcating market tiers. Mid-power 1550nm erbium-glass systems deliver collagen remodeling with minimal downtime, attracting working-age professionals who cannot accommodate ablative recovery periods. This capability split is compressing price premiums for standalone non-ablative treatments while elevating combination-protocol margins.
EU MDR post-market surveillance requirements mandate systematic clinical follow-up for CE-marked scar devices, compelling manufacturers to fund longitudinal outcome registries. German notified bodies enforce stricter biocompatibility testing for handpiece materials that contact compromised skin. European dermatology networks respond by consolidating purchasing around vendors with established MDR technical documentation.
Patient-initiated research behaviors now precede most consultation requests. Digital-native adults arrive with procedure-specific questions drawn from physician-education platforms and peer forums, compressing the traditional information-asymmetry window. Los Angeles and Seoul clinics report shortened decision cycles as informed patients self-triage toward fractional laser or filler pathways before initial visits.
Boxcar Scars Market Segmentation
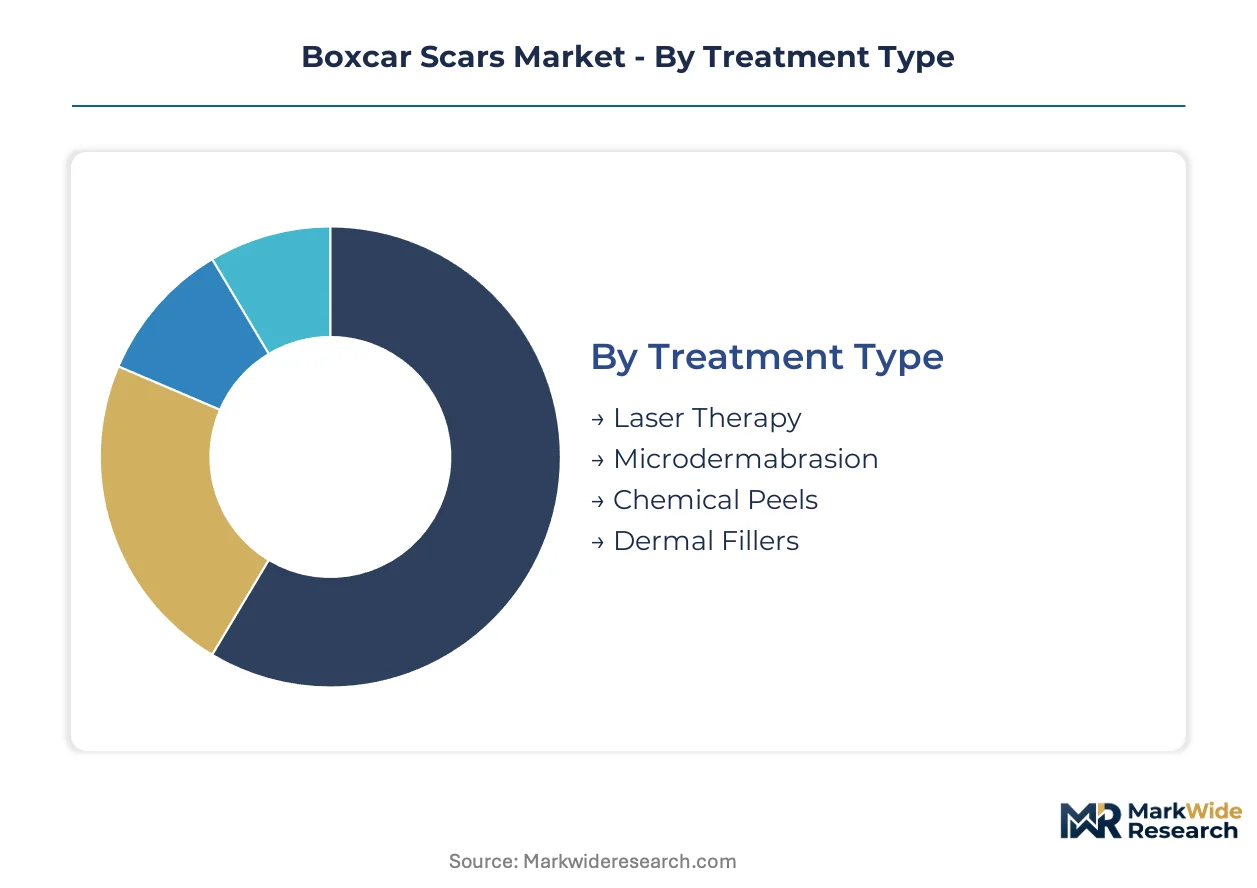
Treatment modality selection for boxcar scars hinges on lesion depth, patient downtime tolerance, and capital-equipment access at the point of care. Channel economics bifurcate procedural value between hospital-affiliated dermatology departments and standalone aesthetic clinics.
Treatment Type:
Channel-mix dynamics concentrate high-margin ablative protocols in physician-directed settings while pushing non-ablative alternatives through aesthetic clinic networks.
- Laser Therapy:Ablative and non-ablative fractional systems deliver collagen remodeling through controlled thermal injury. Seoul and Los Angeles clinical clusters anchor protocol standardization that diffuses through international training networks. By volume, Laser Therapy leads. By growth pace, Dermal Fillers is ahead.
- Dermal Fillers:Hyaluronic acid formulations restore immediate volume to atrophic lesions. Extended residence times in next-generation products pull patient volume from temporary camouflage solutions toward repeat-treatment economics.
- Chemical Peels:Superficial and medium-depth acid applications address mild Grade I presentations. Price compression limits margin expansion in this mature tier.
- Microdermabrasion:Mechanical exfoliation targets epidermal texture irregularities with minimal downtime. Entry-level positioning restricts this modality to aesthetic clinic channels.
Cost-tier stratification separates capital-intensive laser platforms from consumable-driven filler and peel alternatives.
Patient Demographics:
Volume concentration among working-age adults reflects employment-related downtime constraints and discretionary spending capacity.
- Adults:Patients aged 18-35 drive procedural volume for facial scar revision. Digital-native research behaviors compress consultation-to-treatment decision cycles in this cohort.
- Middle-Aged:Patients aged 36-55 pursue combination protocols addressing accumulated photodamage alongside atrophic scarring. Higher disposable income supports premium ablative treatment courses.
- Teenagers:Active acne management precedes scar intervention, limiting addressable volume to post-inflammatory cases with parental consent frameworks.
- Elderly:Thinning dermal collagen and comorbidity profiles restrict candidacy for aggressive ablative protocols in this segment.
Adults generate the highest absolute procedure counts. Middle-Aged patients show the steepest expansion trajectory as delayed treatment seekers enter the funnel.
Severity Level:
Grade classification determines reimbursement coding, treatment intensity, and setting-of-care requirements across dermatology networks.
- Grade III:Deep atrophic lesions with vertical walls measuring 2-4 millimeters demand physician-directed fractional laser protocols. FDA 510(k)-cleared ablative systems anchor treatment pathways for this severity tier.
- Grade IV:Severe tissue loss extending into the reticular dermis requires combination approaches integrating laser resurfacing with subcision or filler augmentation. Academic medical centers concentrate expertise for these complex presentations.
- Grade I:Superficial lesions respond to chemical peels and non-ablative modalities. Aesthetic clinics capture this volume through lower-barrier entry points.
- Grade II:Moderate depth scarring bridges treatment settings, with severity assessment determining protocol selection between peel series and fractional laser introduction.
Grade III lesions dominate revenue concentration. Grade IV presentations are expanding most quickly as combination protocols gain protocol acceptance.
Application Area:
Anatomical site dictates device handpiece selection, anesthesia requirements, and post-procedure care complexity.
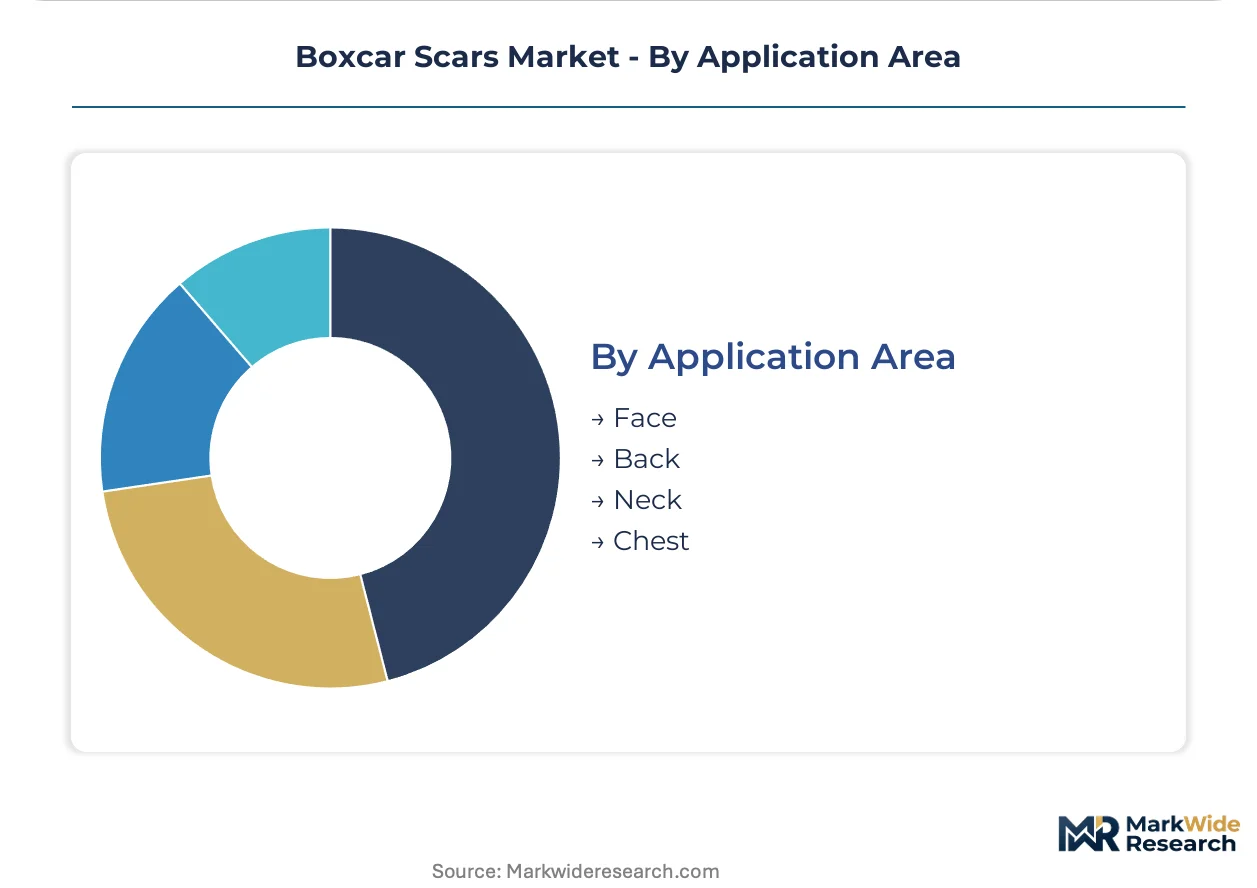
- Face:Cosmetic visibility drives patient motivation and willingness to undergo multi-session fractional laser courses. Precision requirements favor smaller spot-size devices for periorbital and perioral zones.
- Back:Extensive surface area and thicker dermal substrate necessitate higher fluence settings. Keloid risk elevation shapes conservative parameter selection.
- Chest:Thin skin and proximity to cardiac tissue limit ablative depth. Non-ablative fractional protocols predominate in this anatomical region.
- Neck:Horizontal skin tension lines and vascular density complicate healing dynamics. Lower treatment densities reduce adverse event incidence.
Facial applications command the highest procedure volume. Back treatments are gaining share fastest as body-contouring awareness extends beyond facial aesthetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters in Israel and the United States concentrate fractional laser production capacity, while clinical demand disperses across metropolitan dermatology networks in Seoul, Los Angeles, and London.
United States
FDA 510(k) clearance pathways accelerate competitive entry for ablative laser systems targeting Grade III and IV presentations. HIPAA privacy standards shape tele-dermatology consultation workflows that precede in-office procedures. Los Angeles anchors the country's highest procedural density, with dermatology networks reporting shortened patient decision cycles driven by digital-native research behaviors.
South Korea
MFDS regulatory frameworks govern medical device approvals for fractional laser platforms distributed domestically and exported throughout Asia-Pacific. Seoul's Gangnam district concentrates the world's densest cluster of aesthetic dermatology clinics, generating protocol standardization that diffuses through international physician training networks. Korean device manufacturers leverage this clinical infrastructure to validate next-generation pulse-delivery systems.
Germany
EU MDR post-market surveillance requirements mandate systematic clinical follow-up for CE-marked scar-treatment devices, extending approval timelines beyond predecessor directives. German notified bodies enforce stricter biocompatibility testing for handpiece materials contacting compromised skin. Frankfurt and Munich dermatology departments anchor combination-protocol expertise for severe Grade IV presentations.
United Kingdom
MHRA conformity assessment procedures align with EU MDR evidence thresholds while maintaining independent market authorization pathways. London's Harley Street medical district concentrates private dermatology capacity serving international patients seeking facial scar revision. NHS reimbursement coding limits public-sector access to premium ablative protocols, bifurcating treatment accessibility.
Japan
PMDA marketing authorization requirements impose extended clinical trial obligations for novel energy-based devices entering the Japanese market. Tokyo and Osaka metropolitan areas concentrate the country's aesthetic dermatology infrastructure, with patient volumes skewing toward middle-aged demographics pursuing combination protocols. Japanese manufacturers prioritize non-ablative fractional systems aligned with cultural preferences for minimal downtime.
Boxcar Scars Market Vendor Landscape
Concentration sits with integrated device-and-training bundlers and dual-wavelength platform specialists. The vendor base spans three tiers: premium-positioned laser manufacturers with proprietary pulse-delivery architectures, mid-market non-ablative system providers competing on accessibility, and consumable-driven filler and peel suppliers. Strategic moves center on M&A to acquire temperature-feedback safety technologies and geographic expansion into Seoul and Los Angeles clinical clusters.
Within the premium laser tier, Lumenis Ltd and Candela Medical exemplify device manufacturers leveraging proprietary platforms to sustain positioning across dermatology networks. Merz Inc. occupies a distinct archetype as an integrated bundler navigating European reimbursement complexity through training-and-device commercial models. These three entities anchor competitive dynamics without exhaustive claims about specific product configurations or strategic initiatives.
| Leading Market Players |
|---|
| Lumenis Ltd |
| Merz Inc. |
| Cynosure Inc. |
| Cutera, Inc. |
| CeraVe |
| Bausch Health Companies Inc. |
| Sonoma Pharmaceuticals Inc. |
| Smith & Nephew plc |
| Candela Medical |
| Others |
Supply Flow & Price Mechanics
Ninety-day handpiece replacement cycles concentrate procurement leverage among Israeli and US device manufacturers, compressing margin buffers for mid-tier aesthetic clinics while amplifying pricing power for premium laser platform vendors with captive consumable streams.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across ablative and non-ablative fractional laser systems. Three-tier pricing stratifies across premium physician-directed platforms, standard hospital-affiliated installations, and economy-grade aesthetic clinic configurations. Cost compression in the economy tier intensifies because Korean manufacturers are flooding Asian-Pacific markets with mid-power erbium-glass alternatives. Hospital purchasing committees show the least price sensitivity due to bundled training-and-service contracts, while standalone aesthetic clinics face acute margin pressure from consumable lock-in.
Supply Chain Analysis
Israel and the United States anchor fractional laser manufacturing, with Seoul and Los Angeles serving as validation hubs for next-generation pulse-delivery architectures. German optical component suppliers and Japanese precision-motor manufacturers feed critical subassemblies into final assembly lines. Single-source vulnerability concentrates in ytterbium fiber laser modules sourced from a handful of specialized foundries. Distribution runs through direct sales forces for premium hospital systems and third-party medical device distributors for mid-market aesthetic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boxcar scar treatment demand tracks elective healthcare spending cycles, with procedure volumes recovering as working-age adults resume discretionary dermatology investments deferred during economic contraction phases.
For Market Incumbents: Fortify installed base loyalty by embedding temperature-feedback safety systems ahead of evolving FDA combination-device guidance. Deepen backward integration into ytterbium fiber laser production to offset single-source supply risk. Prioritize certification investment for EU MDR technical documentation to defend European market access against compliance-weak competitors. For New Entrants and Emerging Players: Anchor in the Middle-Aged demographic segment, where delayed treatment seekers entering the funnel show the steepest expansion trajectory and lowest price sensitivity. Target aesthetic clinic channels in secondary US metropolitan markets where capital-equipment lock-in has not yet consolidated. Lead with non-ablative fractional platforms featuring minimal downtime protocols that differentiate against entrenched ablative competitors. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring-revenue play because hyaluronic acid filler residence times are extending and repeat-treatment economics are reshaping patient lifetime value. Acquisition focus should center on dual-wavelength platform specialists with proprietary pulse-delivery architectures and established Seoul or Los Angeles training network density. Monitor FDA guidance publication timelines as inflection signals for first-mover advantage windows in combination-device classification.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates competitive entry for ablative laser systems targeting Grade III and IV presentations. |
| EU MDR Technical Documentation | Stricter clinical-evidence thresholds extend approval timelines and inflate compliance costs across German and French notified bodies. |
| Integrated Training-and-Device Bundling | European reimbursement complexity favors commercial models wrapping physician education into capital sales to lock installed base loyalty. |
| Tele-Dermatology Consultation Precedent | HIPAA-compliant remote triage workflows expand patient funnel efficiency and convert digital inquiries into procedural bookings. |
| Temperature-Feedback Safety Integration | Evolving FDA frameworks for energy-based platforms create first-mover advantages for real-time thermal monitoring systems. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database extracts. Dermatologists, biomedical engineers, GPO contracts managers, and aesthetic clinic operators provided procedure-volume and pricing-intelligence inputs. Bottom-up demand modeling triangulates against top-down capital-equipment shipment analysis.
Segmentation dimensions modeled include treatment modality, patient demographic cohort, scar severity grade, and anatomical application site across the projection horizon. CAGRs derive from procedure-volume growth trajectories and per-session pricing dynamics. Forecast inputs incorporate MFDS and PMDA approval pipeline status for Korean and Japanese device manufacturers.
Underlying assumptions cover sustained FDA 510(k) pathway stability and EU MDR post-market surveillance enforcement continuity, with deviation risk concentrated in reimbursement coding shifts and hyaluronic acid formulation patent cliff timing. Recalibration cycles align with material shifts in regulatory guidance publication and notified body interpretation evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Traction Equipment Market