
 Asia-Pacific Customs Brokerage Market | 2026-2036
Asia-Pacific Customs Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Customs Brokerage Market Outlook
Buyer concentration among Asia-Pacific e-commerce platforms is expanding as cross-border volume aggregates toward mega-marketplaces and direct-to-consumer brands. Kuehne + Nagel leverages its digital customs platform to anchor automated declaration workflows across Chinese and Southeast Asian ports. DHL Group Logistics competes through integrated brokerage-forwarding bundles that sustain margin capture in high-velocity lanes. Sinotrans Limited dominates domestic China customs clearance while extending coverage into ASEAN corridors through localized licensing partnerships.
Asia-Pacific customs brokerage encompasses licensed intermediary services managing tariff classification, duty calculation, and regulatory compliance on behalf of importers and exporters, typically operating through electronic data interchange systems integrated with national customs platforms such as China's Golden Customs System or Singapore's TradeNet. The primary commercial purpose centers on minimizing border delays, ensuring accurate duty remittance, and maintaining audit-ready documentation trails across heterogeneous regulatory regimes. Ocean freight brokerage commands the largest service-type volume given containerized manufacturing exports from China and Vietnam, though air freight brokerage generates superior per-shipment margins driven by pharmaceutical and electronics expedited clearances. Large corporations represent the most entrenched client-type segment, while blockchain-enabled documentation trails constitute the fastest-growing technology dimension as regulators in Singapore and Australia pilot paperless trade frameworks.
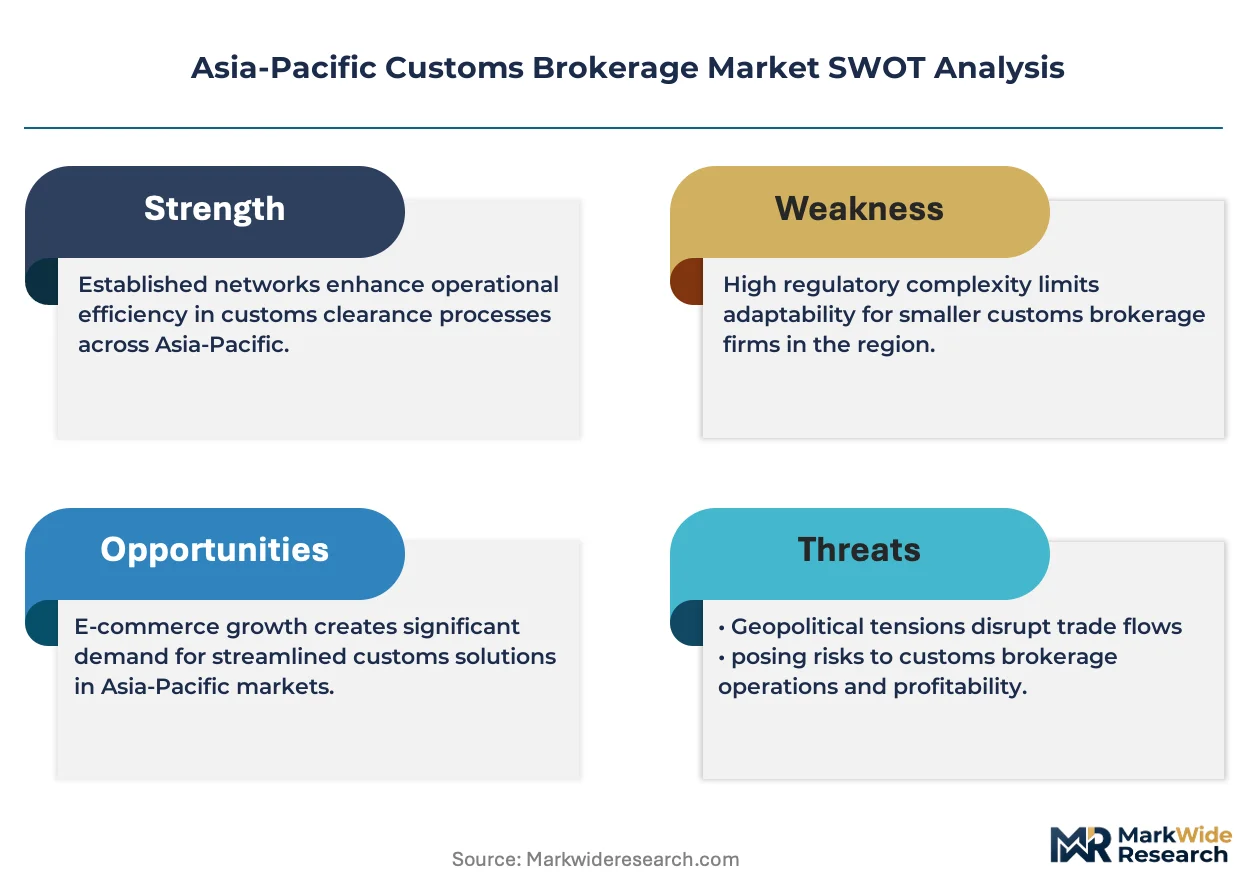
China's General Administration of Customs enforces stringent advance declaration requirements and risk-profiling protocols that shape broker technology investments and staffing competencies. Singapore Customs and Australia's Australian Border Force both mandate electronic submission standards through their respective national single windows, compressing processing timelines while elevating compliance failure costs. India's Central Board of Indirect Taxes and Customs imposes integrated GST reconciliation obligations that demand broker systems architecture capable of real-time tax computation. Stakeholders must monitor divergence between national digital customs maturity levels when allocating platform development resources across multi-country networks.
Market Dynamics
Digital customs platforms are compressing clearance timelines across Asia-Pacific ports, forcing licensed brokers to restructure fee models around automation throughput rather than document volume. This technological inflection is redistributing margin capture toward operators with proprietary API integrations into national single-window systems.
Growth Catalysts
- China's dual carbon goals:Carbon-border documentation requirements are generating new compliance service lines around emissions verification and green tariff classification.
- Southeast Asian manufacturing corridors:Vietnam, Thailand, and Indonesia are expanding bonded warehouse networks that require specialized in-zone clearance expertise.
- Blockchain-enabled documentation:Singapore's TradeTrust framework and Australia's pilot paperless trade programs are accelerating broker investment in distributed-ledger audit trails.
Market Restraints
- Customs platform fragmentation:Divergent national single-window maturity levels between Singapore, India, and Indonesia force redundant system investments across multi-country broker networks.
- Licensed personnel scarcity:China's advance declaration mandates and risk-profiling protocols require specialized tariff-classification expertise that outpaces training pipeline output.
- Freight rate volatility:Container shipping cost swings compress broker margins on bundled forwarding-clearance contracts during rate spike periods.
Strategic Opportunities
- India's GST reconciliation mandate:Real-time tax computation requirements create white space for brokers with integrated ERP-to-customs data architecture.
- Pharmaceutical cold-chain clearances:Temperature-controlled air freight corridors between South Korea, Singapore, and Australia command premium per-shipment margins.
- Cross-border e-commerce aggregation:Direct-to-consumer brand consolidation is driving demand for consolidated de minimis entry processing across ASEAN last-mile networks.
Industry Challenges
- Legacy EDI system migration:Brokers operating hybrid paper-electronic workflows face integration complexity when national customs platforms mandate full API-only submission protocols.
- Audit-ready documentation retention:Australia's Australian Border Force and China's General Administration of Customs impose multi-year record-keeping standards that strain archival infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Customs Brokerage Market |
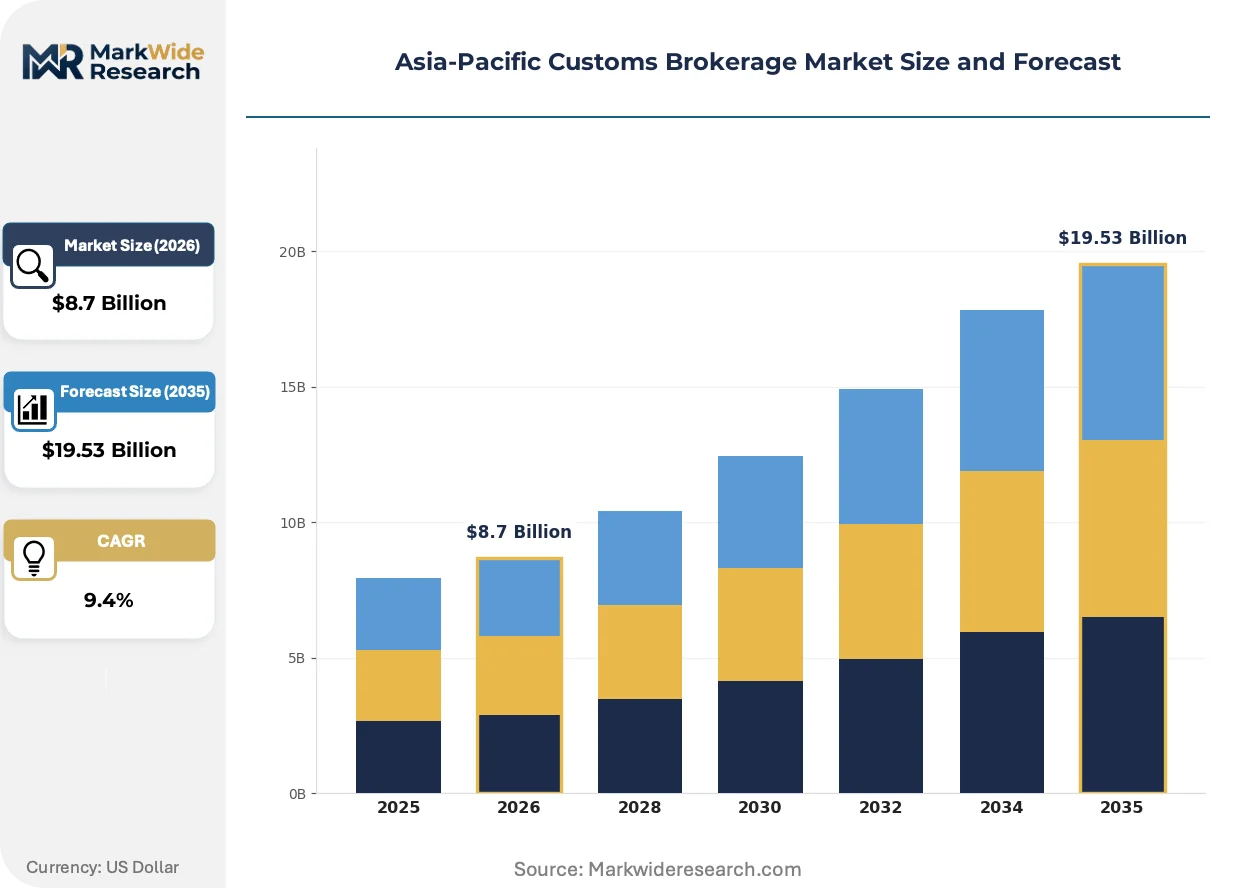
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Ground Transportation, Warehousing Industry Vertical: Retail, Manufacturing, E-commerce, Pharmaceuticals Client Type: Small Enterprises, Large Corporations, Government Agencies, Non-Profit Organizations Technology: Blockchain, Cloud Computing, AI, Automation |
| Companies Covered | Kintetsu World Express, Kuehne + Nagel, DHL Group Logistics, Sinotrans Limited, DB Schenker, Geodis Logistics, HTH Corporation, Nippon Express, Yusen Logistics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Customs Brokerage Market Strategic Shifts
Automation is compressing the traditional customs brokerage value chain, with technology investments now determining competitive position more than licensed office footprint. Three forces are actively restructuring how clearance services are procured and delivered across Asia-Pacific trade lanes.
Blockchain-based trade documentation is consolidating fragmented paper trails into unified digital ledgers that customs authorities and commercial banks can verify in parallel. Pharmaceutical exporters and high-value electronics shippers in Singapore and Australia are adopting these platforms fastest. This consolidation is eliminating documentary discrepancy disputes that previously delayed release by days.
China's Golden Customs System upgrade mandates machine-readable advance declarations and AI-assisted risk profiling for all containerized imports. The regulation forces brokers to retrain staff on algorithmic classification logic rather than interpretive tariff coding. Southeast Asian transshipment hubs are responding by developing mirror-compatible data formats to preserve seamless cargo flow.
Cross-border e-commerce platforms are unbundling traditional brokerage-forwarding bundles and sourcing clearance as standalone API-accessible services. Direct-to-consumer brands in Vietnam and Indonesia now procure automated classification engines on per-SKU subscription terms. This shift is most visible in apparel and consumer electronics verticals where SKU velocity overwhelms traditional per-shipment pricing models.
Asia-Pacific Customs Brokerage Market Segmentation
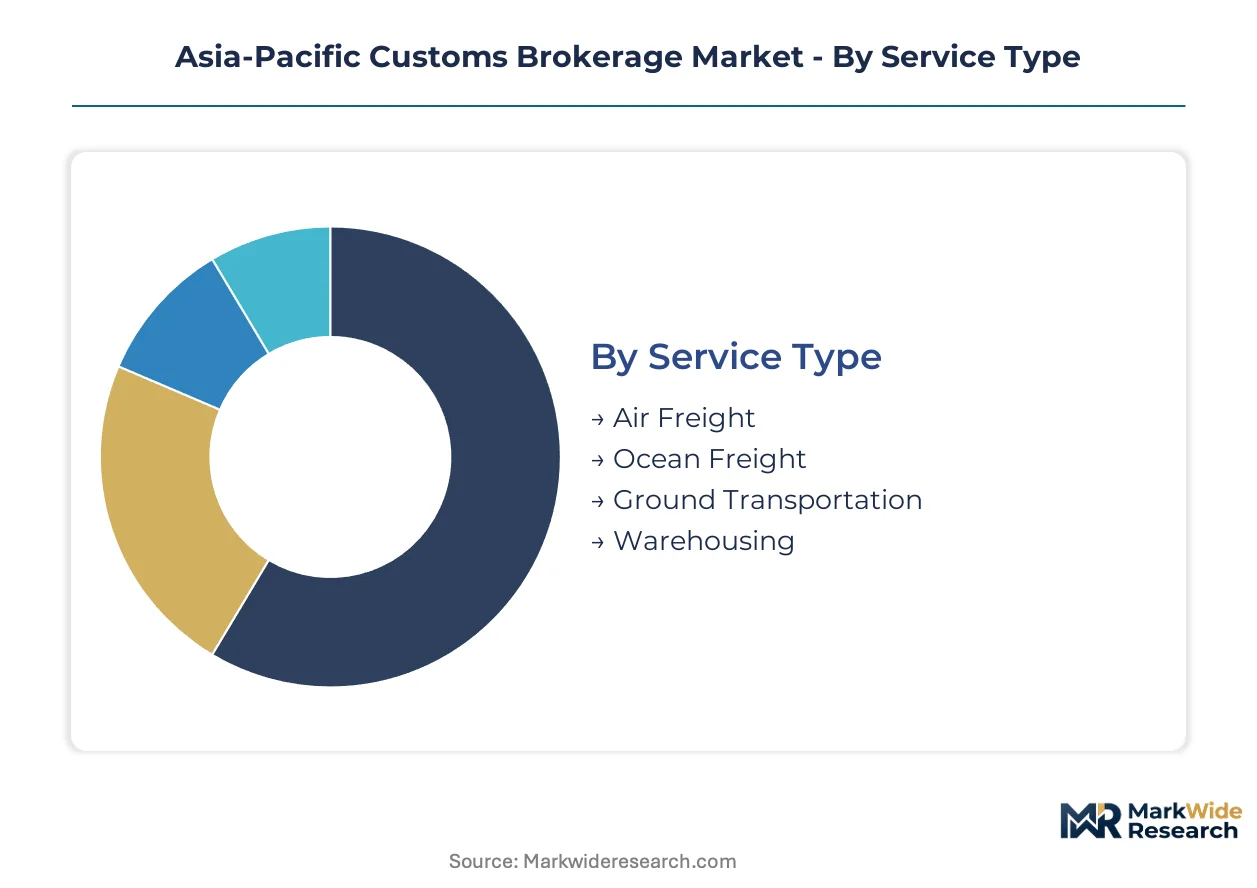
Customs brokerage service procurement diverges sharply across transport modes, industry compliance requirements, and technology sophistication levels. Segment-specific capabilities determine margin capture and client retention in Asia-Pacific's heterogeneous regulatory environment.
Service Type:
Supply concentration in containerized manufacturing exports from China and Vietnam tilts brokerage revenue toward ocean freight, though margin profiles favor expedited modes.
- Ocean Freight:Containerized clearance dominates volume flows from Chinese and Vietnamese manufacturing clusters. Customs brokers anchor automated declaration workflows around Shanghai, Shenzhen, and Ho Chi Minh City port authorities to minimize detention costs.
- Air Freight:Pharmaceutical and electronics expedited clearances generate superior per-shipment margins. South Korean semiconductor exporters and Singaporean biologics shippers demand temperature-controlled documentation chains with real-time customs status visibility.
- Ground Transportation:Cross-border trucking corridors between Thailand, Vietnam, and southern China require bonded transit expertise. Brokers coordinate with China's Golden Customs System for advance declaration compliance on overland routes.
- Warehousing:Bonded warehouse networks in Indonesia and Thailand demand specialized in-zone clearance capabilities. Licensed operators manage duty deferral and re-export documentation for regional distribution centers.
Ocean freight absorbs the bulk of installed capacity; air freight is expanding most quickly.
Industry Vertical:
Cost tier differentiation separates commodity retail clearance from compliance-intensive pharmaceutical processing, with e-commerce forcing structural fee model changes.
- Manufacturing:Electronics and automotive component exporters in China and Vietnam drive standardized tariff classification demand. Brokers invest in HS code automation to handle high-SKU velocity with minimal classification errors.
- Pharmaceuticals:Cold-chain documentation requirements from South Korean and Australian regulators command premium service tiers. TGA and MFDS inspection protocols demand specialized staff training and temperature excursion audit trails.
- E-commerce:Direct-to-consumer brands in Indonesia and the Philippines are unbundling traditional brokerage-forwarding bundles. Platforms now procure API-accessible classification engines on per-SKU subscription terms rather than per-shipment pricing.
- Retail:Apparel importers face seasonal volume spikes that strain broker staffing flexibility. Peak period clearance coordination with Singapore Customs and Australian Border Force requires pre-positioned declaration capacity.
Manufacturing captures the largest revenue share; e-commerce is gaining share fastest.
Client Type:
Customer maturity shapes technology integration depth, with large corporations demanding ERP-to-customs data architecture that smaller clients cannot justify.
- Large Corporations:Multinational manufacturers mandate real-time GST reconciliation and multi-year documentation retention. India's Central Board of Indirect Taxes and Customs integrated tax obligations force broker system upgrades for enterprise accounts.
- Small Enterprises:Limited IT infrastructure drives preference for bundled forwarding-clearance services with simplified documentation handoffs. Brokers compete on fee transparency rather than technology sophistication for this tier.
- Government Agencies:Defense and public health procurement requires security-cleared personnel and segregated data handling protocols. Australian and Singaporean government contracts specify citizenship and facility clearance requirements.
- Non-Profit Organizations:Humanitarian relief shipments demand expedited duty exemption processing under customs conventions. Brokers coordinate with China's General Administration of Customs for disaster response cargo pre-clearance.
Large corporations anchor the client base; small enterprises show the steepest expansion trajectory.
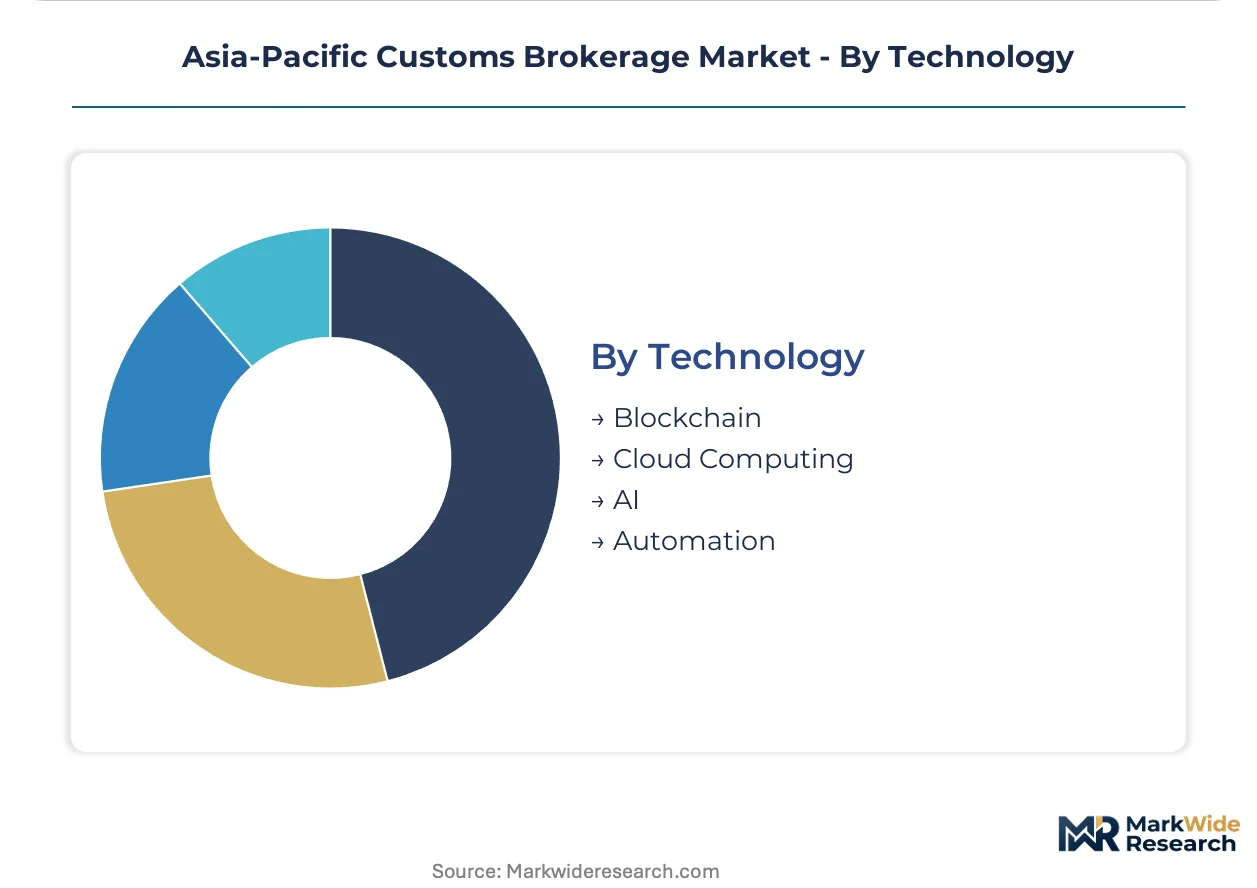
Technology:
Technology maturity gaps between Singapore's TradeNet and Indonesia's developing single window create tiered investment requirements across broker networks.
- Blockchain:Singapore's TradeTrust framework and Australia's pilot paperless trade programs accelerate distributed-ledger adoption. Pharmaceutical exporters leverage immutable documentation to eliminate discrepancy disputes with commercial banks.
- AI:China's Golden Customs System upgrade mandates machine-readable advance declarations with algorithmic risk profiling. Brokers retrain tariff classification staff on interpretive logic rather than manual HS code lookup.
- Cloud Computing:Scalable infrastructure supports multi-country broker networks facing divergent national single-window maturity levels. Indonesian and Philippine operations require flexible deployment models as local platforms evolve.
- Automation:API-only submission protocols in advanced markets compress processing timelines while elevating compliance failure costs. Hybrid paper-electronic workflows in developing markets force redundant system investments.
Automation commands the largest technology spend; blockchain is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border e-commerce volume aggregates toward mega-marketplaces and direct-to-consumer brands across Asia-Pacific, concentrating customs clearance demand in manufacturing export corridors and transshipment hubs.
China
Containerized electronics and automotive component exports from Shanghai and Shenzhen drive sustained brokerage demand. The General Administration of Customs mandates machine-readable advance declarations through its Golden Customs System upgrade. Yangtze River Delta manufacturers are retraining tariff classification staff on algorithmic risk profiling logic.
Vietnam
Electronics assembly relocation from China has expanded bonded warehouse networks in Ho Chi Minh City and Hai Phong. The country's customs administration enforces electronic submission standards that compress processing timelines. Northern manufacturing provinces are developing mirror-compatible data formats to preserve seamless cargo flow with Chinese transshipment.
Singapore
Pharmaceutical and biologics exporters command premium cold-chain clearance services through Changi air freight corridors. Singapore Customs operates the TradeNet single window and pilots TradeTrust blockchain frameworks. The Jurong Island chemical cluster demands specialized in-zone clearance expertise for re-export documentation.
India
Integrated GST reconciliation obligations from the Central Board of Indirect Taxes and Customs force real-time tax computation architecture. Mumbai and Chennai manufacturing hubs drive standardized tariff classification demand. Broker networks are upgrading ERP-to-customs data pipelines to serve enterprise accounts.
Australia
Temperature-controlled pharmaceutical clearances between South Korea and Sydney generate superior per-shipment margins. The Australian Border Force mandates multi-year documentation retention standards that strain archival infrastructure. Melbourne and Brisbane distribution centers require pre-positioned declaration capacity for seasonal retail volume spikes.
Asia-Pacific Customs Brokerage Market Competitive Environment
Chinese operators anchor one tier; European and Japanese specialists hold differentiated positions in premium expedited segments. Market structure tilts toward consolidation as digital platform investments create scale barriers for document-volume-dependent brokers. Three archetypes dominate: integrated forwarding-brokerage bundles, standalone digital customs platforms, and domestic clearance specialists with ASEAN licensing partnerships. Competitive dynamics center on API integration into national single-window systems and strategic licensing arrangements across multi-country networks.
Among integrated logistics providers, Kuehne + Nagel and DHL Group Logistics occupy positions defined by proprietary digital infrastructure and bundled service offerings. Sinotrans Limited exemplifies the domestic specialist archetype, leveraging localized licensing partnerships to extend coverage beyond its home market. These three entities represent contrasting strategic postures: technology-led automation, integrated margin capture, and regulatory depth through geographic licensing.
| Leading Market Players |
|---|
| Kintetsu World Express |
| Kuehne + Nagel |
| DHL Group Logistics |
| Sinotrans Limited |
| DB Schenker |
| Geodis Logistics |
| HTH Corporation |
| Nippon Express |
| Yusen Logistics |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists with fragmented ASEAN licensing portfolios are compressing fee transparency across multi-country broker networks, while family-owned mid-caps in Vietnam and Indonesia retain pricing power through bonded warehouse exclusivity and direct customs administration relationships.
Pricing Analysis
Volume-driven ocean freight clearance absorbs broker capacity at compressed per-container rates, while air freight corridors between South Korea and Singapore sustain premium margins through temperature-controlled documentation tiers. Price differentiation hinges on API integration depth with national single-window systems and licensed personnel density for advance declaration compliance. Cost compression in standard ocean brokerage is intensifying as e-commerce platforms unbundle forwarding-clearance contracts and procure automated classification engines on subscription terms. Small enterprises exhibit highest price sensitivity and gravitate toward bundled forwarding-clearance services, whereas pharmaceutical exporters accept premium tiers for cold-chain audit trail capabilities.
Supply Chain Analysis
Single-source vulnerability sits with China's Golden Customs System upgrade mandates, which force algorithmic risk profiling dependencies across transshipment hubs. Licensed broker capacity concentrates in China, Vietnam, and Singapore, with raw material dependencies spanning tariff classification databases, EDI protocol licenses, and customs-bonded warehouse infrastructure. Logistics chokepoint exposure runs through Shanghai and Shenzhen port authorities where detention cost minimization determines broker selection. Distribution feeds from manufacturing clusters in the Yangtze River Delta and Pearl River Delta through ASEAN transshipment networks to Australian and Indian enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's advance declaration mandates and AI-assisted risk profiling protocols erect barrier-to-entry moats for brokers with proprietary API integrations into the Golden Customs System.
For Market Incumbents: Acquire licensed personnel pools in Vietnam and Indonesia to anchor bonded warehouse expertise before regional manufacturing relocation accelerates. Consolidate fragmented ASEAN licensing partnerships to defend margin position against digital-native entrants offering per-SKU classification subscriptions. Prioritize ERP-to-customs data architecture investments for India's GST reconciliation mandate.
For New Entrants and Emerging Players: API-accessible classification engines represent the most penetrable entry vector for direct-to-consumer brands in Indonesia and the Philippines unbundling traditional brokerage-forwarding bundles. Target pharmaceutical cold-chain clearance corridors between South Korea and Australia where TGA and MFDS inspection protocols sustain premium pricing. Pursue white-label partnerships with e-commerce platforms seeking automated de minimis entry processing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic China specialists with ASEAN licensing partnerships in Vietnam and Thailand, where manufacturing relocation is expanding bonded warehouse demand. Long-term viability hinges on regulatory technology depth rather than document volume scale. Watch Singapore's TradeTrust blockchain pilot adoption rates as the inflection signal for distributed-ledger documentation becoming table stakes.
| Strategic Initiative | Industry Significance |
|---|---|
| API Integration with National Single-Windows | Proprietary Golden Customs System connections compress clearance timelines for Yangtze River Delta exporters. |
| Licensed Personnel Acquisition in ASEAN | Tariff classification expertise scarcity in Vietnam and Thailand constrains competitor expansion velocity. |
| Blockchain Documentation Infrastructure | TradeTrust framework alignment eliminates discrepancy disputes with Singaporean pharmaceutical exporters. |
| Bonded Warehouse Network Expansion | In-zone clearance capabilities in Indonesia capture duty deferral demand from regional distribution centers. |
| ERP-to-Customs Data Architecture | Real-time GST reconciliation pipelines serve India's Central Board of Indirect Taxes and Customs enterprise mandates. |
Study Parameters
Multi-period observation of clearance timeline compression, API adoption rates, and licensed broker staffing ratios anchored the trend analysis, supplemented by interviews with customs brokerage operations directors, freight forwarding procurement leads, regulatory technology platform engineers, and bonded warehouse facility managers. Secondary validation drew from China's General Administration of Customs policy circulars, Singapore Customs TradeNet documentation standards, Indian Central Board of Indirect Taxes and Customs GST integration guidelines, and Australian Border Force retention mandate specifications. Bottom-up segmentation modeling and top-down macro trade flow triangulation cross-checked volume and value estimates.
The input-output matrix framed demand drivers against regulatory compliance cost trajectories across service type, industry vertical, client maturity tier, and technology sophistication dimensions. Modeled outputs reflect shipment volume projections, per-clearance fee evolution, and automation penetration rates across the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate trade flow forecasts. Industry-specific inputs incorporated e-commerce cross-border volume aggregation patterns and pharmaceutical cold-chain corridor expansion timelines.
The model holds under stable regulatory technology investment cycles and sustained manufacturing relocation from China to Vietnam; deviation in customs platform fragmentation severity or licensed personnel training pipeline output would shift broker competitive positioning and margin capture trajectories. Forecasts reflect documented assumptions regarding national single-window maturity convergence rates and blockchain documentation adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
Middle-East and North Africa Taxi Market
Transportation & Logistics
India Intra-City Logistics Market