
 Parking Meter Market | 2026-2036
Parking Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Parking Meter Market Analysis
China is reconfiguring its parking infrastructure supply base through expanded domestic manufacturing of networked payment terminals. Flowbird leverages European design heritage to sustain premium positioning in multi-space installations. IPS Group Inc anchors North American municipal contracts through vertical control over meter housing production. METRIC Group Ltd competes on deployment speed across UK city centers.
A parking meter constitutes a self-service revenue collection device engineered to enforce time-limited vehicle parking through calibrated mechanical, electromechanical, or fully digital transaction systems, typically integrating coin validation, card readers, or near-field communication modules with tamper-resistant enclosures rated for outdoor exposure. Its commercial purpose centers on monetizing curb space while enabling traffic turnover enforcement for municipal and private asset managers. Smart meter deployments now lead value generation as wireless communication and mobile payment integration displace legacy coin-operated stock across municipalities. Solar-powered variants represent the fastest-growing product type where grid-independent operation reduces trenching costs in historic districts and remote off-street lots.
FCC certification governs wireless-enabled meter communications in the United States, while EU member states apply CE marking and RoHS substance restrictions to electromechanical components entering European procurement channels. GDPR compliance shapes data architecture for mobile payment platforms processing driver information across European deployments. Stakeholders must weigh interoperability standards against vendor lock-in risks as open-payment mandates spread across municipal procurement specifications.
Market Dynamics
Municipal procurement specifications now mandate open-payment architectures and solar-powered operation, forcing incumbent meter vendors to reengineer hardware stacks and abandon proprietary transaction protocols that locked cities into single-source maintenance contracts.
Growth Catalysts
- EU Green Deal procurement mandates:German municipal authorities face binding carbon-reduction targets that accelerate replacement of grid-dependent electromechanical meters with solar-harvesting terminals.
- Contactless payment infrastructure:NFC module integration at the curb eliminates coin-handling labor costs while reducing vandalism exposure for urban parking authorities.
- Historic district preservation constraints:Trenching moratoriums in Italian and Spanish city centers create demand for wireless, battery-independent meter deployments that avoid subgrade construction.
Market Restraints
- Lithium-ion cell supply volatility:Meter manufacturers face input cost pressure from concentrated battery production in East Asian supply chains.
- Vendor lock-in legacy architectures:Proprietary communication protocols in installed European coin-and-card meters create switching friction for municipal buyers.
- Right-of-way permitting delays:Localized approval processes for curb-mounted electronics extend deployment timelines beyond municipal fiscal cycles.
Strategic Opportunities
- Off-street lot digitization:Surface parking facilities at retail centers and transit hubs in France remain underpenetrated by networked payment systems.
- Dynamic pricing algorithm integration:Convergence of occupancy sensors with demand-responsive rate engines enables revenue-optimized curb management.
- GDPR-compliant data monetization:Aggregated parking pattern analytics create secondary revenue streams for municipal authorities with robust consent frameworks.
Industry Challenges
- FCC certification timeline compression:Wireless module approvals for US deployments require 18-24 month validation cycles that misalign with municipal procurement schedules.
- Coin-to-digital transition staffing:Field technician retraining for electromechanical repair represents a workforce bottleneck as legacy meter populations age simultaneously.
- Interoperability testing fragmentation:Absence of unified payment protocol standards forces vendors to maintain multiple firmware branches for different municipal specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parking Meter Market |
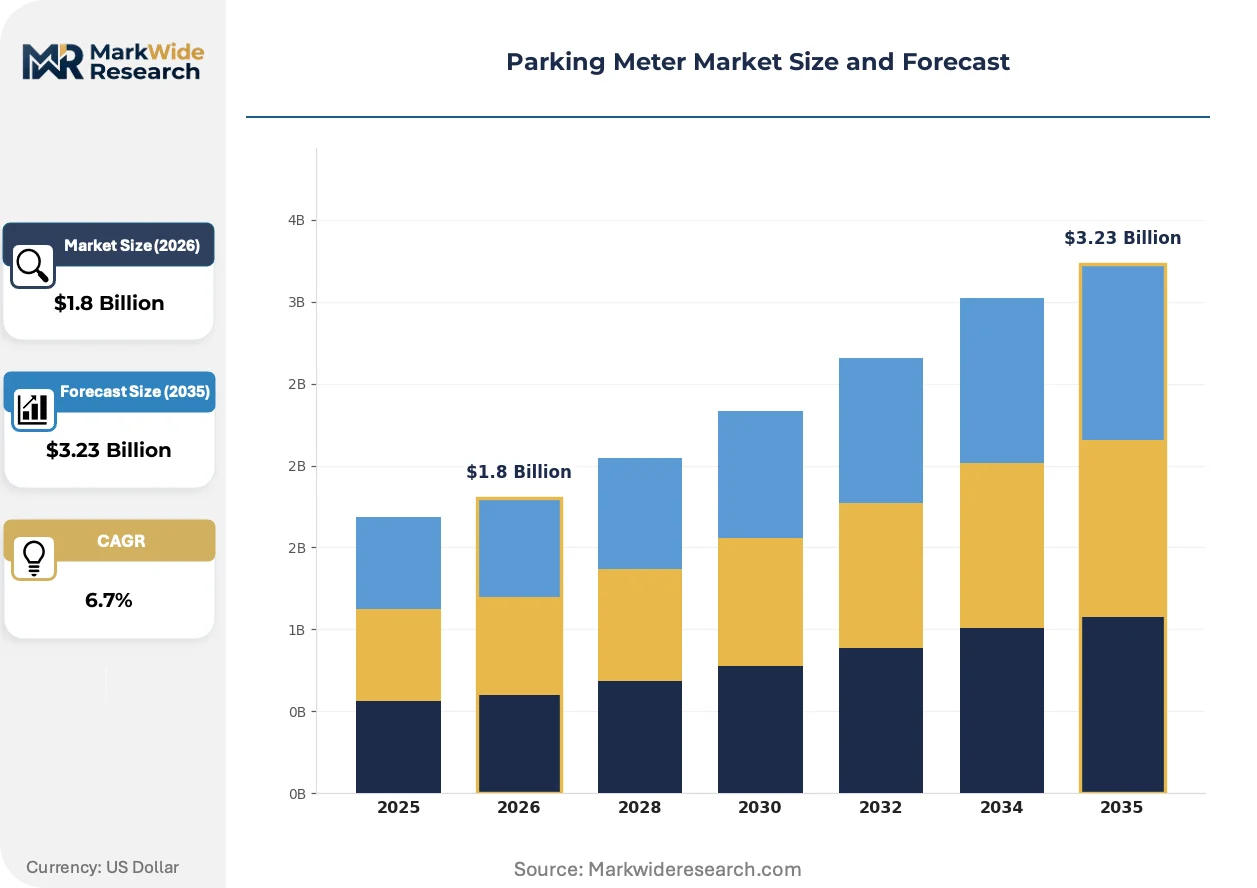
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pay-and-Display, Smart Meters, Coin-Operated, Solar-Powered Technology: Wireless Communication, RFID, Mobile Payment, Automation End User: Municipalities, Private Operators, Airports, Universities Installation Type: On-Street, Off-Street, Multi-Space, Portable |
| Companies Covered | IPS Group Inc, Parking BOXX, Flowbird, J.J. MacKay Canada Limited, Ventek International, CivicSmart Inc, METRIC Group Ltd, Duncan Solutions, LocoMobi Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parking Meter Market Emerging Trajectories
Payment friction at the curb is dissolving as license-plate recognition and smartphone-based session initiation eliminate physical meter interaction entirely, compressing hardware footprints while expanding enforcement precision.
Solar-harvesting photovoltaic arrays integrated into meter housings is collapsing the business case for trenching-dependent grid connections in remote lots and heritage districts. Spanish municipal authorities in Seville and Granada have accelerated procurement of off-grid terminals to comply with subgrade construction moratoriums. The technology is collapsing installation cost structures that previously constrained meter density in low-revenue peripheral zones.
CE marking under the EU Green Deal's extended product responsibility framework now requires documented end-of-life recyclability for electromechanical components entering European procurement channels. Meter vendors must redesign housing assemblies to satisfy RoHS substance restrictions and forthcoming circularity mandates. Italian parking authorities in Milan and Rome have inserted modular upgradeability clauses into tender specifications to avoid full replacement cycles.
Buyers now unbundle hardware acquisition from maintenance and payment processing, forcing meter vendors to compete for recurring service revenue rather than upfront equipment margins. French municipal authorities have pioneered pay-per-transaction contracting that transfers uptime risk to vendors. This model is compressing capital requirements for smaller cities while concentrating vendor performance accountability.
Parking Meter Market Segmentation
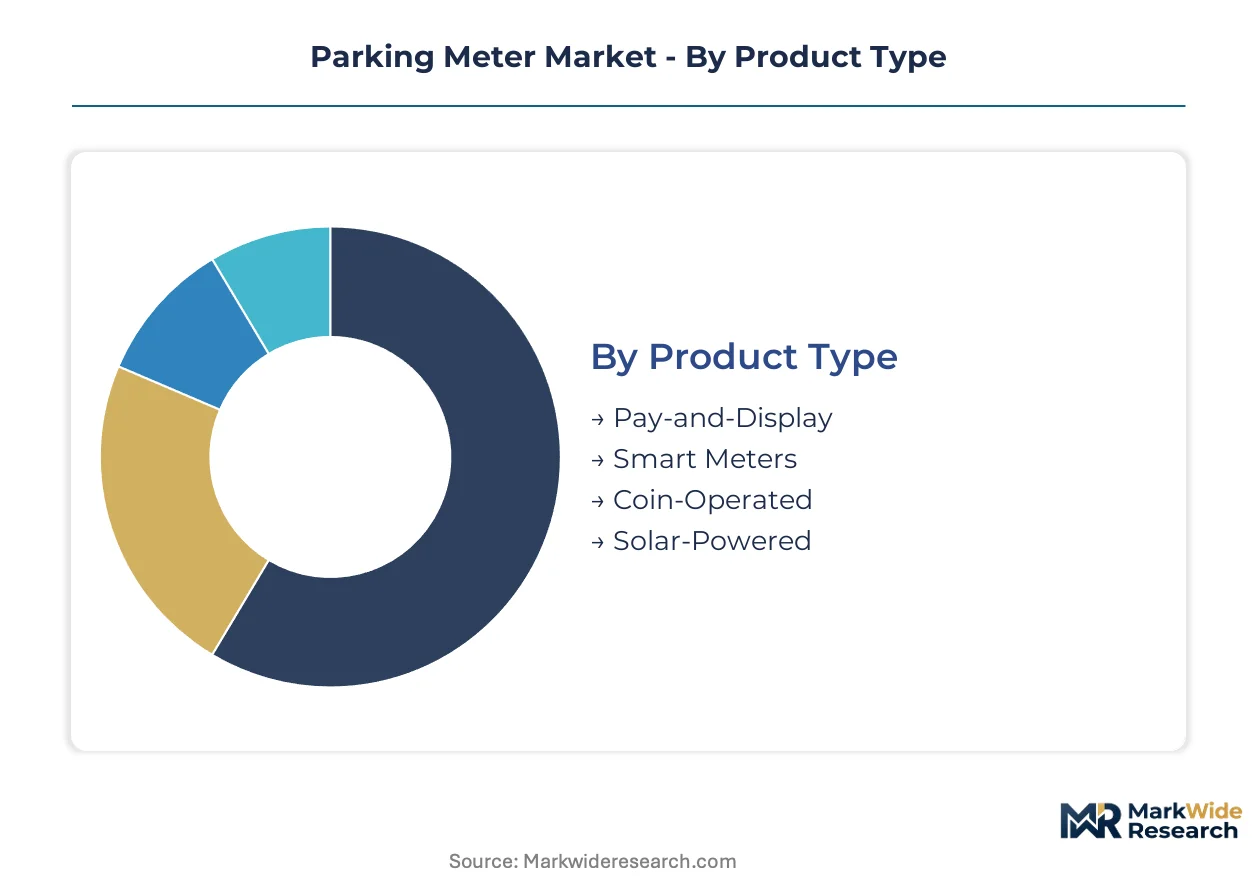
Parking meter segmentation reveals divergent technology lifecycles and procurement economics. Municipal buyers now unbundle hardware from service contracts, reshaping how vendors compete across product tiers and installation modes.
Product Type:
Mature coin-operated hardware coexists with emerging solar-harvesting terminals, creating a bifurcated replacement cycle across urban procurement offices.
- Pay-and-Display:Centralized terminal systems issue paper tickets for dashboard placement, reducing per-space hardware density. French municipal authorities in Lyon and Marseille favor these for high-turnover commercial districts where vandalism risk concentrates on single-space units.
- Smart Meters:Networked terminals integrate cellular modems, contactless readers, and occupancy sensors for real-time enforcement integration. German cities under EU Green Deal procurement mandates are accelerating deployment of these grid-independent units to satisfy carbon-reduction targets.
- Coin-Operated:Legacy mechanical and electromechanical validators still dominate installed base across Italian and Spanish city centers where transition timelines lag municipal fiscal cycles.
- Solar-Powered:Photovoltaic-integrated housings eliminate trenching requirements. Seville and Granada procurement offices have prioritized these for historic districts with subgrade construction moratoriums.
Smart meters handle the majority of throughput; solar-powered variants are climbing the fastest on share.
Technology:
Cost tier differentiation separates premium wireless stacks from basic automation modules, with mobile payment integration now table stakes for municipal tenders.
- Wireless Communication:Cellular and mesh radio modules enable centralized rate management and real-time occupancy monitoring. FCC certification timelines in the United States and CE marking requirements in Europe create 18-24 month validation cycles that constrain vendor rollout velocity.
- RFID:Proximity card readers support closed-loop payment systems for university and airport campuses. These retain niche deployment in controlled-access environments where open-payment mandates do not apply.
- Mobile Payment:NFC modules and QR-code initiation eliminate physical card handling. Contactless infrastructure reduces coin-collection labor costs for urban parking authorities while lowering vandalism exposure.
- Automation:Basic electromechanical actuators and timer mechanisms persist in budget-tier replacements. These serve peripheral zones where transaction volume cannot justify networked terminal investment.
Mobile payment anchors new procurement specifications; wireless communication carries the steepest expansion trajectory as municipalities demand centralized management platforms.
End User:
Customer type determines contract structure, with municipalities favoring capital purchase models while private operators shift toward performance-based service agreements.
- Municipalities:City parking authorities specify open-payment architectures and solar compatibility under EU Green Deal compliance. Procurement fragmentation across thousands of local governments forces vendors to maintain multiple firmware branches.
- Private Operators:Retail center and transit hub managers prioritize uptime guarantees and revenue-sharing terms. These buyers have pioneered pay-per-transaction contracting that transfers operational risk to meter vendors.
- Airports:High-throughput curb management at Frankfurt, Charles de Gaulle, and Heathrow demands license-plate recognition integration with rapid session initiation.
- Universities:Campus parking offices balance student affordability with enforcement efficiency, often deploying RFID-closed systems to control access by permit type.
Municipalities dominate installed base volume; private operators are gaining share fastest as service-based contracting spreads.
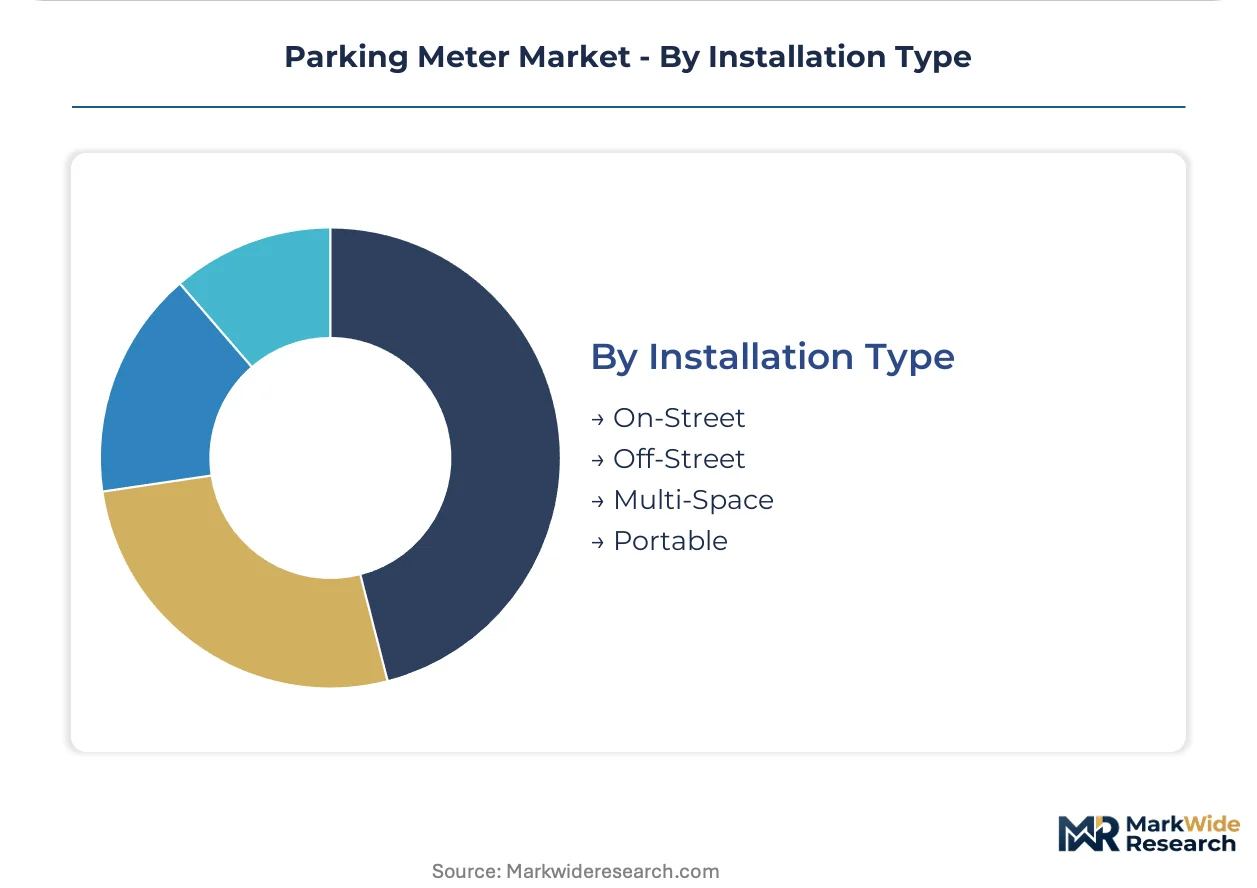
Installation Type:
Application context dictates hardware specification, with on-street deployments facing vandalism and weather exposure absent in controlled off-street environments.
- On-Street:Curb-mounted terminals in urban cores require tamper-resistant enclosures rated for vehicle impact and environmental exposure. Italian and Spanish historic district constraints favor wireless, battery-independent configurations.
- Off-Street:Surface lots and structured garages at French retail centers remain underpenetrated by networked payment systems, presenting expansion opportunity for digitization vendors.
- Multi-Space:Centralized pay stations serve multiple parking bays, reducing capital intensity for low-density peripheral zones. These configurations dominate German municipal procurement for residential district deployment.
- Portable:Temporary terminals support event parking and construction-zone management. These units prioritize rapid deployment over durability, serving seasonal demand fluctuations.
On-street installations absorb the bulk of replacement investment; off-street digitization presents the steepest untapped expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of networked payment terminals clusters in China, while design and systems integration concentrate in Europe and North America. Municipal procurement patterns diverge sharply across jurisdictions, driven by distinct regulatory timelines and infrastructure legacy conditions.
Germany
KBA oversight shapes type-approval requirements for curb-mounted electronics, while EU Green Deal carbon-reduction targets accelerate solar-harvesting terminal deployment. Municipal authorities in Berlin and Munich specify grid-independent operation to eliminate trenching in historic districts.
United States
FCC certification timelines spanning 18-24 months constrain vendor rollout velocity for wireless-enabled meters. California and New York municipal authorities lead procurement of license-plate recognition systems that eliminate physical meter interaction entirely.
China
Domestic manufacturing expansion for networked terminals reduces import dependency for municipal procurement. MIIT standards govern wireless communication modules, while dual carbon goals incentivize solar-integrated housing designs in Hangzhou and Shenzhen deployments.
France
ANSM and CNIL oversight shapes data architecture for mobile payment platforms processing driver information. Lyon and Marseille parking authorities favor pay-and-display terminals for high-turnover commercial districts where vandalism risk concentrates on single-space units.
United Kingdom
CE marking and forthcoming circularity mandates require documented end-of-life recyclability for electromechanical components. London and Birmingham city centers prioritize deployment speed, compressing installation timelines to align with municipal fiscal cycles.
Parking Meter Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying enclosures, payment modules, and wireless stacks. The vendor base separates into three strategic archetypes: full-stack platform vendors, housing and mechanical fabricators, and payment technology licensors. Consolidation pressure intensifies as municipalities unbundle hardware acquisition from maintenance contracts, forcing vendors to compete for recurring service revenue. Dominant competitive moves include geographic expansion into underpenetrated off-street markets and technology licensing partnerships to accelerate NFC and solar-harvesting integration.
Among North American specialists, IPS Group Inc anchors municipal contract positions through captive supply of meter housings. Flowbird occupies a position within the European design heritage tier, sustaining premium positioning in multi-space installations. METRIC Group Ltd exemplifies deployment-speed competitors, concentrating activity across UK city centers where compressed timelines determine vendor selection.
| Leading Market Players |
|---|
| IPS Group Inc |
| Parking BOXX |
| Flowbird |
| J.J. MacKay Canada Limited |
| Ventek International |
| CivicSmart Inc |
| METRIC Group Ltd |
| Duncan Solutions |
| LocoMobi Inc |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese solar panel production is cascading into parking meter photovoltaic module pricing, compressing margins for European housing assemblers while enabling aggressive procurement bids from German municipal authorities under EU Green Deal mandates. This utilization dynamic simultaneously rewards buyers with sourcing leverage and pressures incumbent vendors to absorb cost volatility through service contract restructuring.
Pricing Analysis
CE marking and RoHS substance restrictions dictate the pricing tier structure across European procurement channels, separating premium-certified solar-integrated terminals from basic electromechanical replacements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Cost compression in the economy tier is intensifying because lithium-ion cell supply volatility from East Asian production clusters feeds into battery backup system quotes. Municipal buyers exhibit highest price sensitivity, while airport authorities prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from municipal procurement offices are forcing housing fabricators to secure supply-chain finance facilities for raw material pre-positioning. Manufacturing concentrates in China for photovoltaic modules and wireless communication stacks, with Germany and the United States retaining final assembly and systems integration capabilities. Meter production draws from lithium-ion cells, cellular modems, and tamper-resistant aluminum enclosures. Single-source vulnerability in battery cell supply creates procurement risk for vendors serving EU Green Deal accelerated replacement timelines. Distribution runs through municipal procurement offices and private operator facility management channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parking meter market rewards vendors who command firmware architecture expertise and wireless certification velocity, assets that remain scarce relative to hardware fabrication capacity. Municipal unbundling of equipment from service contracts has shifted value capture toward recurring revenue platforms, privileging integrators over component suppliers.
For Market Incumbents: Entrench municipal relationships by embedding solar-harvesting upgrade paths into existing installed bases, foreclosing competitive replacement cycles. Captive supply of meter housings anchors contract renewals against emerging Asian terminal manufacturers. Priority investment in FCC pre-certification programs compresses validation timelines for North American expansion. For New Entrants and Emerging Players: Build out off-street lot digitization capabilities targeting French retail centers and transit hubs where networked payment penetration lags on-street deployment. License-plate recognition integration offers the most penetrable technology wedge against established meter vendors. Channel partnership with facility management operators accelerates pilot-to-scale conversion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pay-per-transaction service contracts as vendors absorb upfront hardware deployment risk. Long-term viability centers on recurring revenue platforms with municipal lock-in rather than equipment margins. Acquisition targets should demonstrate firmware branching capability across fragmented procurement specifications. Watch for EU circularity mandate enforcement as signal for modular upgradeability premium repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Harvesting Terminal Launch | EU Green Deal procurement mandates in Berlin and Munich accelerate grid-independent meter adoption. |
| License-Plate Recognition Integration | California and New York authorities eliminate physical meter interaction through camera-based enforcement. |
| Pay-Per-Transaction Contracting | French municipal pioneers transfer uptime risk to vendors while compressing capital requirements. |
| GDPR-Compliant Data Platform | Aggregated parking analytics create secondary revenue streams under CNIL and ANSM oversight. |
| Modular Upgradeability Program | Milan and Rome tender specifications avoid full replacement cycles through component refresh. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with municipal parking authority procurement officers, meter vendor product managers, and wireless module certification specialists; and secondary validation through FCC equipment authorization databases, EU tender documentation portals, and municipal budget disclosure filings. Bottom-up unit deployment estimates triangulated against top-down municipal capital expenditure aggregates.
Forecast inputs span product type substitution curves, technology adoption S-curves for contactless payment modules, and regional regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include installation type, end-user contract structure, and technology stack configuration. CAGRs derived from regression analysis of historical procurement velocity against policy mandate acceleration.
Practitioners should monitor lithium-ion supply contract renegotiations and FCC certification queue lengths for early signals of vendor delivery capacity constraints. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency and municipal fiscal cycle alignment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Customs Brokerage Market