
 North America Long-Haul Transport Market | 2026-2036
North America Long-Haul Transport Market Size, Share, and Industry Trends Forecast 2026-2036
North America Long-Haul Transport Market Analytics
Freight brokerage platforms is reshaping how carriers and shippers connect across North American lanes, compressing traditional dispatcher roles and expanding spot-market liquidity. J.B. Hunt Transport Services leverages its integrated intermodal container fleet to control box availability through peak seasons. Knight-Swift Transportation Holdings anchors its network density in the western United States with company-operated terminals. FedEx sustains premium positioning through time-definite express lanes that bypass standard less-than-truckload routing.
North America long-haul transport encompasses the movement of goods over distances exceeding 250 miles using heavy-duty vehicles, locomotives, or intermodal equipment designed for sustained highway or rail operation at gross vehicle weights up to 80,000 pounds on federal interstate corridors. The primary commercial purpose centers on connecting manufacturing clusters, port gateways, and consumption centers across thousand-mile corridors with scheduled reliability. Truck transport dominates absolute tonnage moved, though intermodal rail captures structural margin pools on dense lanes between Chicago and Los Angeles where fuel efficiency differentials compound over distance. E-commerce end users are pulling dedicated fleet investment fastest, as inventory positioning requirements compress delivery windows from regional distribution centers to last-mile nodes.
The US EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency rules are tightening allowable CO2 emissions from heavy-duty tractors, forcing fleet operators to evaluate battery-electric and hydrogen combustion platforms ahead of equipment replacement cycles. Transport Canada aligns with parallel Clean Fuel Regulations that raise carbon intensity benchmarks for diesel supplied across Canadian corridors. The US Department of Transportation Hours-of-Service rules continue constraining driver utilization rates, amplifying labor scarcity into equipment productivity decisions. Stakeholders must monitor whether charging infrastructure deployment along Interstate corridors keeps pace with OEM production commitments for zero-emission tractors, as range anxiety remains the binding constraint on fleet electrification timelines.
Market Dynamics
Fleet operators across North America are recalibrating equipment replacement cycles around zero-emission tractor availability and charging corridor density, compressing traditional diesel asset lifespans while intermodal rail captures margin on dense transcontinental lanes.
Growth Catalysts
- E-commerce fulfillment velocity:Inventory positioning requirements from regional distribution centers to last-mile nodes are pulling dedicated fleet investment fastest. Retailers are securing dedicated long-haul lanes to bypass spot-market volatility during peak seasons.
- US EPA Phase 3 standards:Tightening CO2 emissions thresholds for heavy-duty tractors are accelerating fleet turnover toward battery-electric and hydrogen combustion platforms ahead of normal replacement schedules.
- Port-to-inland corridor density:The Texas-to-California corridor concentrates demand where port throughput intersects with inland distribution nodes, creating scheduled lane density that supports dedicated fleet economics.
Market Restraints
- Driver utilization ceilings:US DOT Hours-of-Service rules constrain productive hours per tractor-day, amplifying labor scarcity into equipment productivity decisions and limiting fleet expansion without proportional headcount growth.
- Charging infrastructure lag:Interstate corridor charging deployment is trailing OEM zero-emission tractor production commitments, creating range anxiety that binds electrification timelines to infrastructure buildout speed.
- Diesel price volatility:Fuel cost swings compress margin predictability for asset-heavy operators running thin-spread contract freight against spot-market exposure.
Strategic Opportunities
- Mexico manufacturing integration:Nearshoring momentum is generating new cross-border lane density between Mexican industrial clusters and US Midwest distribution hubs, creating white space for dedicated fleet contracts.
- Intermodal rail convergence:Combining highway drayage with rail long-haul on Chicago-Los Angeles corridors compounds fuel efficiency differentials over distance, opening margin pools for integrated operators.
- Transport Canada Clean Fuel Regulations:Parallel carbon intensity benchmarks for diesel across Canadian corridors are creating regulatory tailwinds for alternative powertrain adoption in cross-border fleet operations.
Industry Challenges
- Technician skill scarcity:Battery-electric and hydrogen powertrain maintenance requires retraining or replacement of diesel-specialized technician workforces, constraining fleet uptime during transition periods.
- Asset stranding risk:Accelerated depreciation schedules for diesel tractors ahead of resale market collapse are forcing write-down decisions before equipment reaches historical replacement thresholds.
- Interoperability complexity:Mixed-fleet operations combining diesel, battery-electric, and hydrogen assets require redundant maintenance infrastructure and dispatch systems that fragment operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Long-Haul Transport Market |
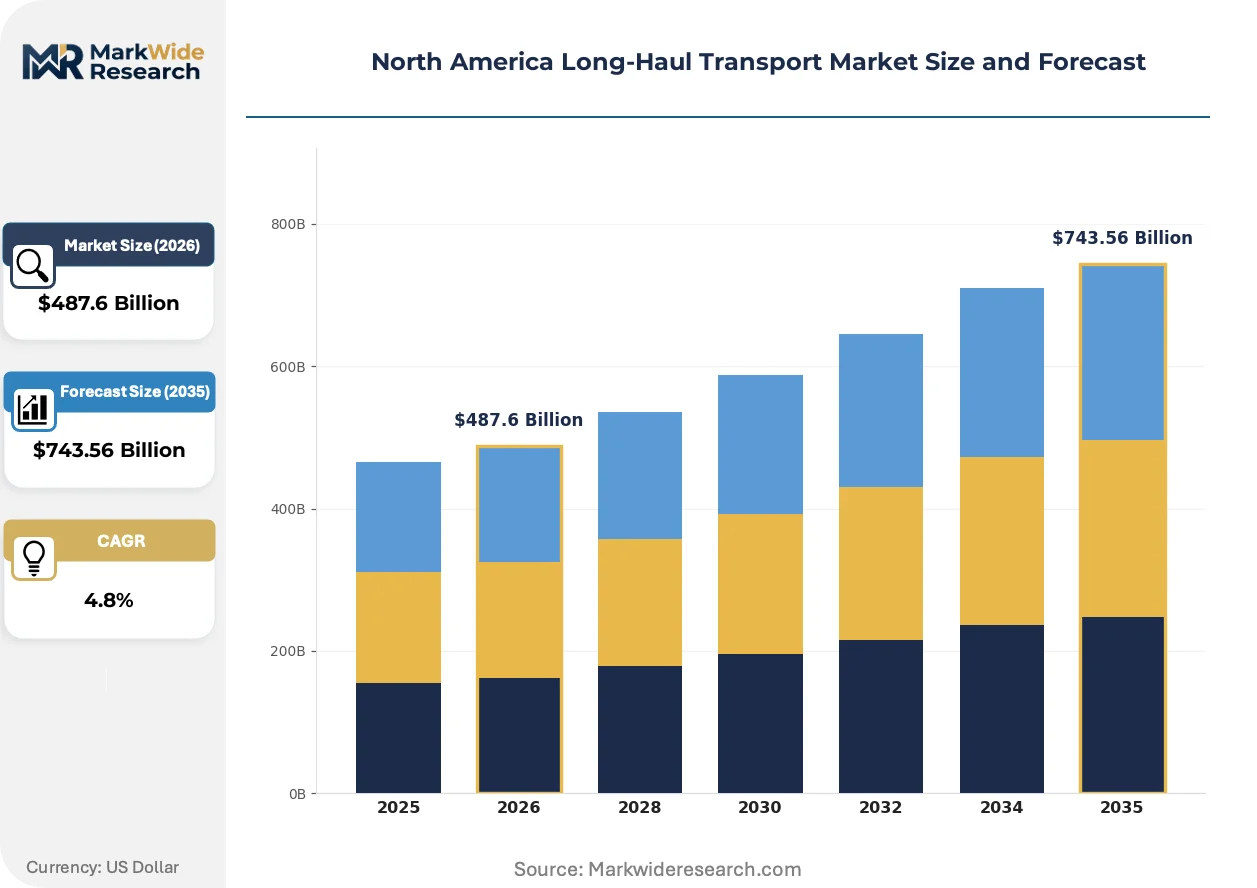
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Type: Truck, Rail, Intermodal, Air Service Type: Freight, Logistics, Courier, Warehousing End User: Retailers, Manufacturers, E-commerce, Automotive Delivery Method: Direct Shipping, Drop Shipping, Consolidated Shipping, Others |
| Companies Covered | FedEx, J.B. Hunt Transport Services, Knight-Swift Transportation Holdings, XPO, Schneider National, C.H. Robinson Worldwide, United Parcel Service of America, TFI International, Old Dominion Freight Line, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Long-Haul Transport Market Evolving Landscape
Powertrain diversification and freight-matching platform proliferation are compressing traditional dispatcher roles while reshaping how carriers and shippers connect across thousand-mile corridors with scheduled reliability requirements.
Telematics-enabled predictive maintenance is migrating from fleet management software to integrated tractor OEM platforms. Large fleet operators are adopting factory-embedded diagnostics that stream sensor data directly to maintenance scheduling systems. This technology is compressing third-party telematics vendor margins while embedding service revenue into tractor purchase contracts.
NHTSA fuel efficiency rules are tightening in parallel with US EPA Phase 3 greenhouse gas standards, forcing powertrain engineering tradeoffs between aerodynamic drag reduction and power density preservation. Sleeper-cab tractors serving 500-plus-mile lanes face the steepest compliance cost increases, driving segment consolidation toward larger fleet operators with R&D scale.
Shippers are consolidating procurement around dedicated contract capacity with penalty clauses for service failure, displacing spot-market reliance for core lane volume. Food and beverage distributors with temperature-controlled requirements are leading this shift, locking in refrigerated fleet capacity across the Texas-to-California corridor where produce seasonality creates predictable demand spikes.
North America Long-Haul Transport Market Segmentation
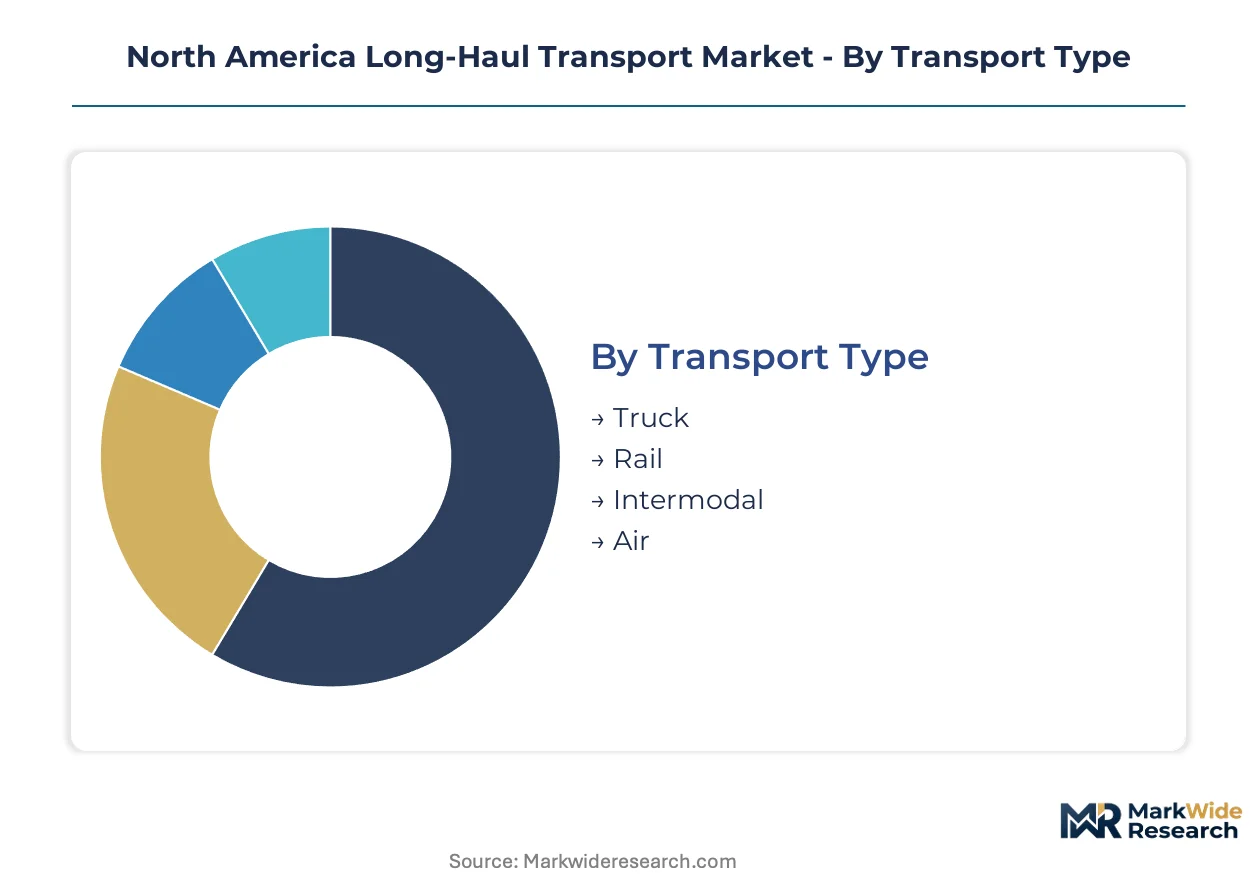
Segmentation in North American long-haul transport reveals how service intensity and asset configuration vary across operational models. Equipment utilization rates, maintenance cycles, and driver labor models diverge sharply between transport modes, creating distinct margin structures that reward specialized fleet strategies.
Transport Type:
After-sales service intensity scales directly with asset complexity and regulatory compliance burden across powertrain technologies.
- Truck:Heavy-duty tractors with sleeper cabs dominate absolute tonnage on corridors exceeding 500 miles. Fleet operators in the Texas-to-California lane are absorbing accelerated depreciation schedules as EPA Phase 3 standards force zero-emission transition timelines ahead of historical replacement cycles.
- Rail:Class I railroads deploy double-stack container equipment on dense transcontinental lanes where fuel efficiency differentials compound over distance. Chicago-to-Los Angeles corridor density supports scheduled intermodal service with lower driver labor exposure than highway alternatives.
- Intermodal:Combines highway drayage with rail long-haul to capture margin pools on lanes with sufficient volume density.
- Air:Time-definite express networks bypass standard surface routing for high-value, low-weight shipments requiring next-day delivery windows.
By volume, Truck leads. By growth pace, Intermodal is expanding most quickly as shippers seek fuel cost hedging on dense lanes.
Service Type:
Customer contract structures range from spot-market exposure to multi-year dedicated capacity agreements with penalty clauses.
- Freight:Asset-heavy operators run thin-spread contract freight against volatile fuel cost exposure. Large fleets are consolidating procurement around dedicated lanes with service failure penalties.
- Logistics:Third-party providers coordinate multi-modal routing without direct asset ownership. Mexico manufacturing integration is generating cross-border lane density requiring customs-brokerage coordination.
- Courier:Time-definite last-mile integration from regional distribution centers compresses delivery windows for e-commerce end users.
- Warehousing:Inventory positioning nodes at inland distribution points buffer demand volatility for retail and automotive supply chains.
By revenue concentration, Freight dominates. By contract duration extension, Logistics is gaining share fastest as nearshoring complexity rises.
End User:
Inventory velocity requirements and temperature control needs shape fleet specification and lane dedication intensity.
- Retailers:Seasonal demand spikes, particularly produce cycles on the Texas-to-California corridor, drive refrigerated fleet investment with predictable annual patterns.
- Manufacturers:Just-in-time assembly requirements demand scheduled reliability with penalty structures for delivery failure. Mexican industrial clusters feeding US Midwest hubs are creating new dedicated contract opportunities.
- E-commerce:Regional distribution center positioning requirements compress delivery windows to last-mile nodes.
- Automotive:Inbound parts sequencing and finished vehicle distribution require specialized equipment with strict damage liability protocols.
By fleet investment velocity, E-commerce leads. By contract stability, Manufacturers show the steepest expansion trajectory as nearshoring locks in lane density.
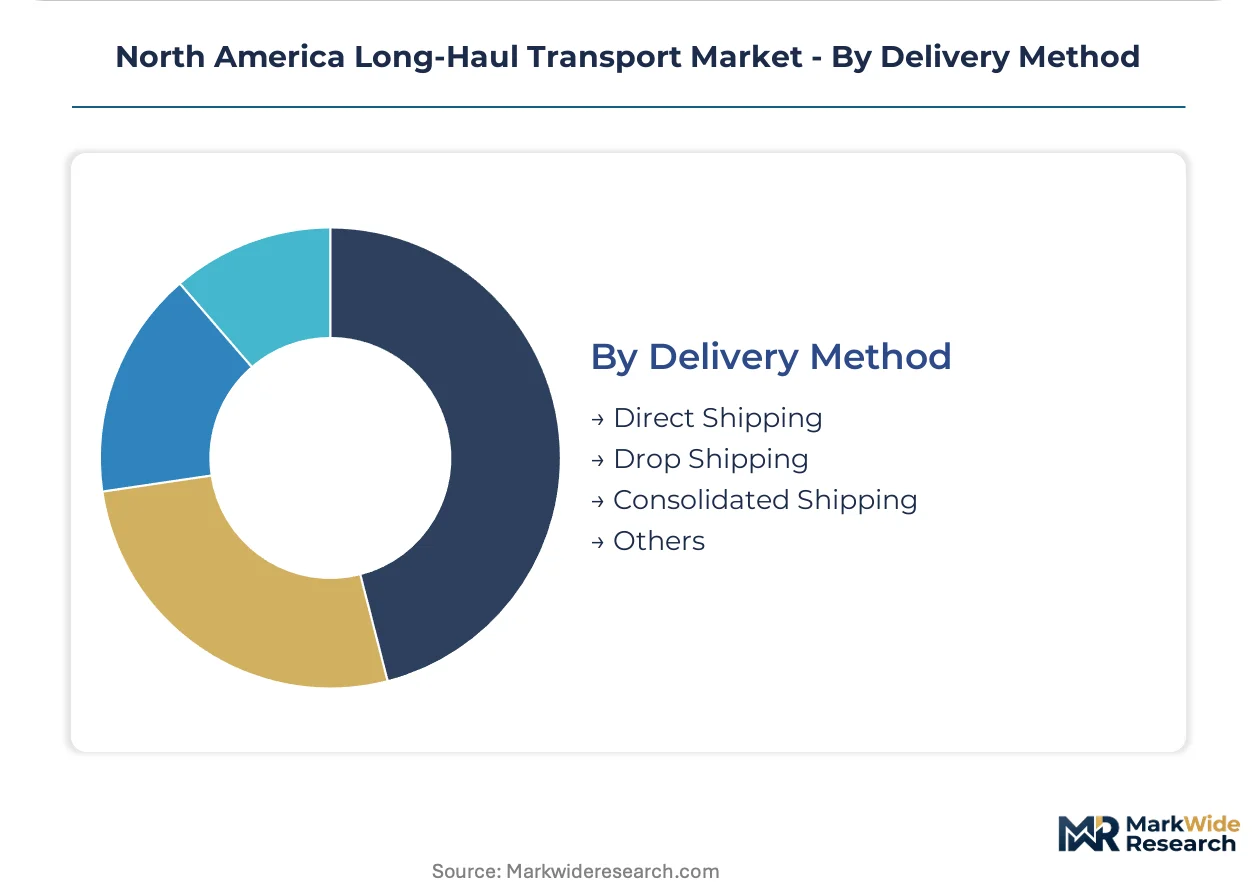
Delivery Method:
Consolidation economics and shipment size thresholds determine modal selection and pricing structure differentiation.
- Direct Shipping:Full truckload movements bypass intermediate handling for shippers with sufficient volume to justify dedicated equipment. Large retailers are securing direct capacity to bypass spot-market volatility during peak seasons.
- Drop Shipping:Supplier-to-consumer routing eliminates intermediate warehousing but requires real-time inventory visibility across distributed fulfillment networks.
- Consolidated Shipping:Less-than-truckload aggregation captures margin from shippers with sub-truckload shipment sizes on irregular schedules.
- Others:Specialized arrangements including pool distribution and cross-docking for time-sensitive or temperature-controlled requirements.
By shipment count, Consolidated Shipping leads. By margin expansion, Direct Shipping is climbing the fastest as penalty-clause contracts displace spot-market reliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US EPA Phase 3 greenhouse gas standards and Transport Canada Clean Fuel Regulations are accelerating fleet turnover toward alternative powertrains across North American corridors. Federal incentives for charging infrastructure deployment are reshaping equipment replacement cycles in high-density freight lanes.
United States
The Texas-to-California corridor concentrates port throughput from Houston and Los Angeles with inland distribution nodes in Dallas-Fort Worth and Phoenix. US EPA Phase 3 standards tighten CO2 emissions thresholds for heavy-duty tractors serving these lanes. Chicago anchors intermodal rail density where double-stack container movements compound fuel efficiency differentials over transcontinental distance.
Canada
Cross-border manufacturing supply chains between Ontario and Michigan generate dedicated fleet demand for automotive parts sequencing. Transport Canada Clean Fuel Regulations raise carbon intensity benchmarks for diesel supplied across the Windsor-Quebec City corridor. Vancouver port throughput feeds prairie distribution networks through rail-highway intermodal convergence.
Mexico
Nearshoring momentum in Nuevo León and Baja California is creating new lane density between Monterrey industrial clusters and Texas distribution hubs. Mexican federal logistics infrastructure programs support cross-border customs-brokerage coordination. Mexico City Metro serves as the primary consumption center pulling finished goods north through Laredo and Eagle Pass border crossings.
North America Long-Haul Transport Market Competitive Landscape
On the supply side, the industry is consolidating around integrated operators with captive equipment and terminal networks. Asset-heavy carriers with dedicated fleet contracts are displacing spot-market brokers on dense corridors. Three archetypes dominate: integrated intermodal specialists with container control, asset-light freight brokers with digital matching platforms, and premium express operators with time-definite lane structures. Competitive moves center on dedicated contract expansion with service failure penalties and zero-emission fleet pre-orders ahead of regulatory deadlines.
Within the integrated tier, J.B. Hunt Transport Services and Knight-Swift Transportation Holdings exemplify asset-heavy positioning through company-operated terminal density. FedEx occupies the premium express archetype with time-definite lane structures that bypass standard routing. These operators represent contrasting strategic bets on equipment ownership depth versus network speed differentiation.
| Leading Market Players |
|---|
| FedEx |
| J.B. Hunt Transport Services |
| Knight-Swift Transportation Holdings |
| XPO |
| Schneider National |
| C.H. Robinson Worldwide |
| United Parcel Service of America |
| TFI International |
| Old Dominion Freight Line |
| Others |
Value Network & Pricing Analysis
The Dallas-Fort Worth distribution cluster anchors capacity dynamics that cascade downstream into dedicated contract pricing power across the Texas-to-California corridor. Fleet operators with captive terminal density leverage this concentration to secure multi-year agreements with penalty structures that insulate margins from spot-market volatility.
Pricing Analysis
Certification level creates the primary spread between asset-heavy dedicated contracts and spot-market brokerage rates. EPA Phase 3 compliance tiers separate premium zero-emission fleet pricing from standard diesel-equivalent rates, with after-sales service bundling widening the gap further. Cost compression in the spot tier is intensifying because freight-matching platforms compress dispatcher margins and expand liquidity. Small shippers with irregular lane requirements show the highest price sensitivity, while food and beverage distributors with temperature-controlled mandates accept premium positioning for scheduled reliability.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculations for cross-border manufacturing lanes. Equipment manufacturing draws from Mexico, Canada, and the United States for final assembly, while battery cell production rests on South Korean and Chinese supply anchors. Single-source vulnerability in semiconductor components for telematics and powertrain control systems threatens fleet uptime during transition periods. Distribution runs through company-operated terminal networks that integrate drayage, rail interchange, and final-mile handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American long-haul transport functions as a defensive-moat market where terminal network density creates switching costs that lock in shipper relationships across multi-year contract horizons.
For Market Incumbents: Pre-empt emerging freight-matching platforms by embedding predictive maintenance diagnostics into OEM purchase contracts, capturing service revenue streams that third-party telematics vendors currently extract. Accelerate zero-emission fleet pre-orders ahead of EPA Phase 3 enforcement deadlines to strand competitor diesel assets in collapsing resale markets. Deepen terminal density in the Monterrey-to-Texas corridor before nearshoring momentum saturates available real estate. For New Entrants and Emerging Players: Pursue cross-border customs-brokerage coordination as the most penetrable white-space target, where Mexico manufacturing integration outpaces established carrier capabilities. Target refrigerated dedicated contracts on produce-seasonal lanes where incumbent capacity constraints create predictable demand spikes. Lead with digital freight-matching platforms that compress dispatcher roles and expand spot-market liquidity for small shippers bypassing traditional brokerage. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because terminal network density and captive equipment fleets create moats that software-only entrants cannot replicate. Acquisition targets should emphasize integrated intermodal operators with container control and rail-highway convergence capabilities. Watch charging infrastructure deployment pace along Interstate corridors as the inflection signal determining electrification timeline feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Emission Fleet Pre-Order | EPA Phase 3 compliance deadlines accelerate asset replacement cycles ahead of competitor stranded cost exposure. |
| Terminal Network Expansion | Company-operated density in Dallas-Fort Worth and Monterrey locks in dedicated contract economics. |
| Intermodal Rail Convergence | Chicago-Los Angeles double-stack integration compounds fuel efficiency differentials over transcontinental distance. |
| Cross-Border Customs Coordination | Mexico nearshoring lanes require integrated brokerage capabilities that fragment competitors lack. |
| Predictive Maintenance Embedding | Factory-embedded diagnostics stream sensor data directly to scheduling systems, compressing third-party vendor margins. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, intermodal terminal managers, shipper procurement leads, and freight brokerage platform executives. Secondary validation drew from US EPA regulatory filings, Transport Canada Clean Fuel Regulation impact assessments, Class I railroad operating reports, and customs trade data covering cross-border freight flows. Bottom-up equipment deployment models triangulated against top-down corridor volume estimates to reconcile fleet capacity with tonnage demand.
Calibration anchored volume and value outputs across the analysis window to observed replacement cycle timing, regulatory enforcement schedules, and infrastructure deployment commitments. Segmentation dimensions modeled include transport mode, service contract structure, end-user inventory velocity requirements, and powertrain technology tier. CAGRs were derived from equipment order backlogs, port throughput projections, and e-commerce fulfillment network expansion plans.
Sensitivities concentrate around charging infrastructure deployment pace, zero-emission tractor production ramp timelines, and cross-border trade policy shifts affecting Mexico manufacturing integration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM delivery commitments. Material shifts in EPA Phase 3 implementation timing or hydrogen fuel cell commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Middle-East and North Africa Taxi Market
Transportation & Logistics
Traction Equipment Market