
 Latin America Inland Waterway Transport Market | 2026-2036
Latin America Inland Waterway Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Inland Waterway Transport Market Insights
Qualified river pilots and licensed towboat operators are reorganizing capacity deployment across the Hidrovía system as training pipelines struggle to match fleet expansion timelines. Hermasa Navegacao Da Amazonia Ltda leverages its Amazon basin operational footprint to sustain year-round cargo movements despite seasonal draft fluctuations. CMA CGM anchors its South American inland strategy through integrated barge-feeder connections at Brazilian river ports.
Latin America inland waterway transport encompasses the movement of goods and passengers via navigable rivers, lakes, and canals using vessels with draft ratings typically below three meters to accommodate seasonal depth variations. The primary commercial purpose centers on bulk commodity logistics, particularly soybeans, iron ore, petroleum products, and containerized manufactures, where waterborne unit costs undercut trucking alternatives over distances exceeding five hundred kilometers. Cargo Transport dominates service type revenue as agribusiness and mining houses lock in long-term barge contracts, while Tankers within vessel type classifications capture disproportionate margin pools from fuel distribution contracts along the Paraguay-Paraná corridor. Navigation Systems technology spending is accelerating fastest as fleet operators digitize route optimization to mitigate shallow-draft operational risks.
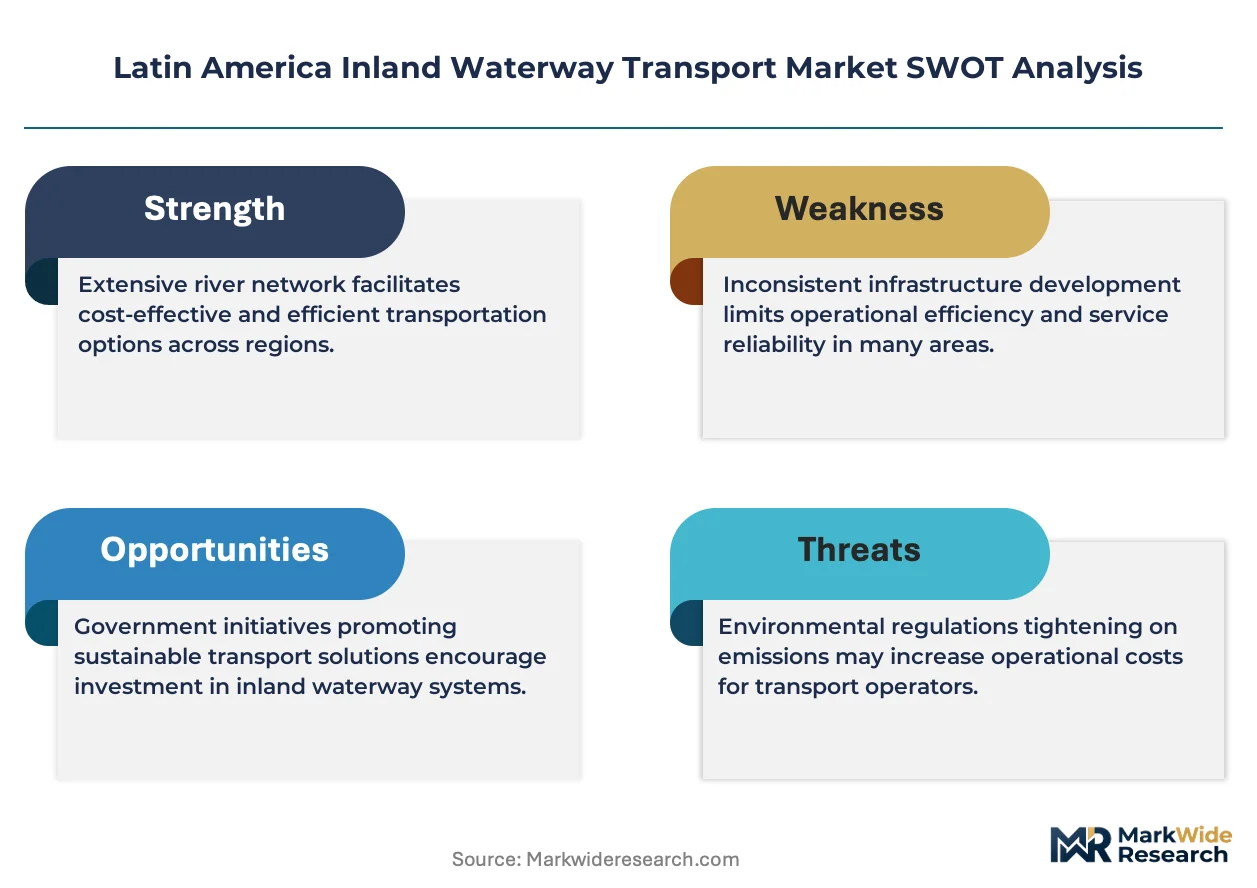
ANTAQ in Brazil, the Comisión Administradora del Río de la Plata in Argentina, and the Autoridad de Regulación y Fiscalización de Electricidad y Aguas in Bolivia collectively shape waterway access through concession terms, environmental permitting, and tariff regulation. These frameworks determine which operators gain terminal leases, what vessel standards apply for cross-border traffic, and how fuel taxation affects route economics. Stakeholders must monitor pending infrastructure concession rounds and draft harmonization negotiations to anticipate capacity bottlenecks and regulatory arbitrage opportunities.
Market Dynamics
Draft harmonization negotiations between Brazil, Argentina, and Paraguay are restructuring fleet deployment economics across the Hidrovía Paraguay-Paraná system, forcing operators to recalculate vessel utilization rates against seasonal depth guarantees.
Growth Catalysts
- ANTAQ Port Concession Reforms:Brazil's regulatory framework for private terminal investments is accelerating barge-loading infrastructure deployment along the Paraguay-Paraná waterway, reducing cargo transfer delays.
- Soybean Corridor Migration:Agricultural commodity flows from Mato Grosso are shifting volume from road haulage to river routes as exporters lock in long-term barge contracts for bulk export efficiency.
- Digital Route Optimization:Navigation Systems technology spending is enabling real-time draft monitoring that extends the operational window for shallow-water vessel movements.
Market Restraints
- Qualified Crew Scarcity:Training pipelines for licensed towboat operators and river pilots lag fleet expansion timelines, creating operational bottlenecks during peak harvest windows.
- Seasonal Draft Volatility:Rainfall-dependent depth variations in the Amazon basin and Pantanal wetlands constrain year-round vessel sizing and cargo load factors.
- Cross-Border Tariff Friction:Divergent fuel taxation regimes between Argentina, Brazil, and Paraguay distort route economics and complicate multi-country voyage planning.
Strategic Opportunities
- Bolivian Waterway Access:The Autoridad de Regulación y Fiscalización de Electricidad y Aguas is opening new navigable corridors connecting the Chapare region to Atlantic export routes.
- Integrated Barge-Feeder Networks:Containerized manufactures are creating demand for synchronized river-ocean transshipment at Brazilian deepwater ports.
- Autonomous Navigation Pilots:Convergence of satellite positioning and machine-learning depth prediction is enabling safer night operations on unlit river stretches.
Industry Challenges
- Environmental Permitting Delays:Wetland protection mandates from the Comisión Administradora del Río de la Plata extend terminal construction timelines and increase pre-operational capital lockup.
- Legacy Fleet Retrofit Costs:Older pushboats and hopper barges require engine upgrades to meet emerging emissions standards, straining mid-size operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Inland Waterway Transport Market |
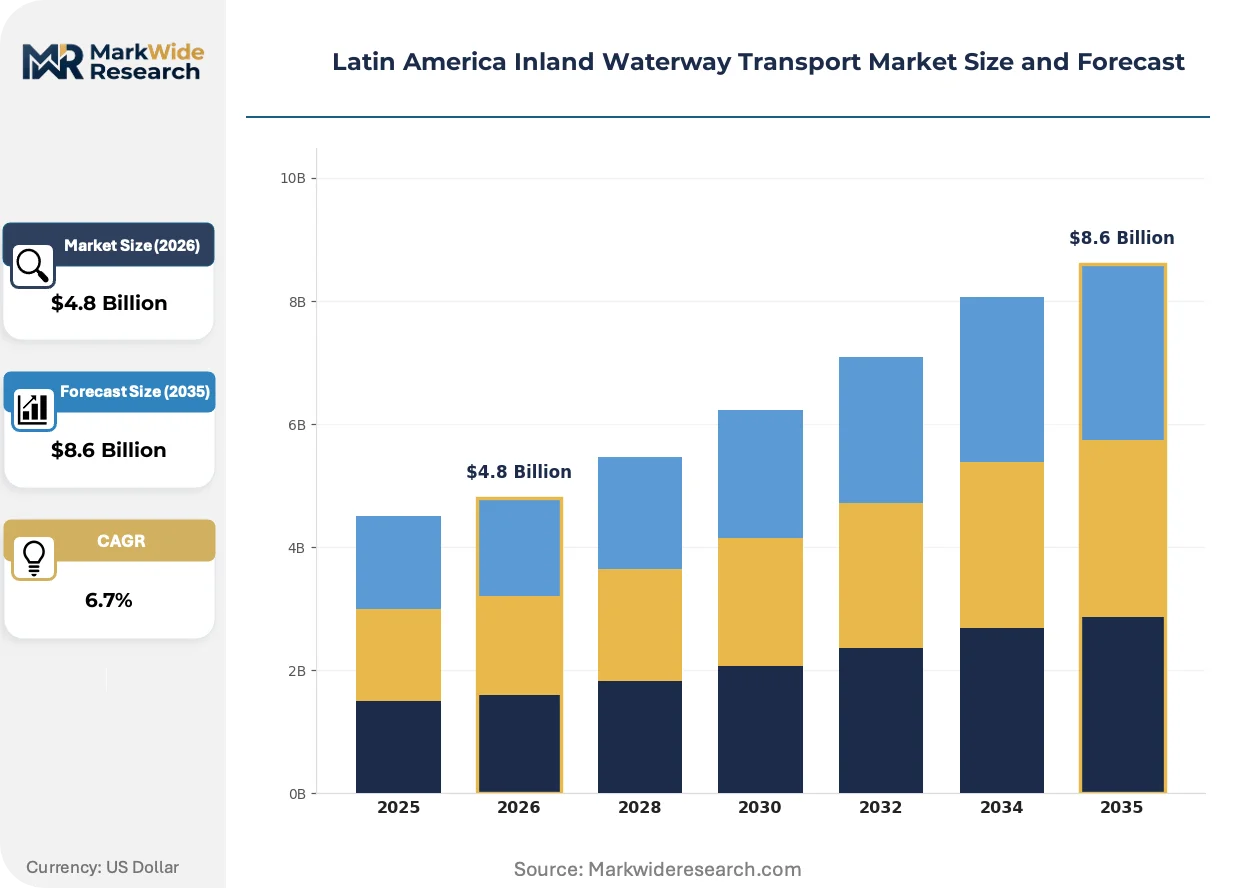
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cargo Transport, Passenger Transport, Hybrid Services, Logistics Solutions Vessel Type: Barges, Tankers, Container Ships, Tugboats End User: Agriculture, Manufacturing, Oil & Gas, Tourism Technology: Navigation Systems, Communication Tools, Fuel Management, Cargo Tracking |
| Companies Covered | Agnamar SA, Hermasa Navegacao Da Amazonia Ltda, National Shipping SA, Chibatao Navegacao E Comercio Ltda, UABL Paraguay SA, Maersk Line, CMA CGM, MSC Mediterranean Shipping Company, Hamburg Sud, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Inland Waterway Transport Market Trends and Innovations
Digital instrumentation is displacing manual depth sounding and paper chart navigation across South American river operations, compressing the skill premium previously commanded by veteran pilots.
Real-time sonar bathymetry combined with cloud-based hydrological modeling is decomposing the traditional reliance on seasonal draft assumptions. Fleet operators in the Paraguay-Paraná corridor are adopting these systems to maximize cargo loading during historically marginal water periods. The technology is decomposing the buffer capacity that operators previously maintained to accommodate navigation uncertainty, allowing tighter fleet utilization.
Brazil's ANTAQ environmental licensing protocols are mandating ballast water treatment and hull coating standards for cross-border traffic. These requirements are accelerating capital expenditure cycles for vessel owners serving the tri-border region. The grain export segment is responding by consolidating contract volumes with larger fleet operators possessing in-house compliance capabilities.
Agribusiness buyers are unbundling long-term barge contracts into shorter voyage charters with fuel-adjustment clauses. This shift transfers price volatility risk from grain traders to vessel operators while enabling more flexible harvest-timing decisions. The pattern is most visible in Mato Grosso, where soybean cooperatives now procure river capacity through spot-market platforms rather than annual commitments.
Latin America Inland Waterway Transport Market Segmentation
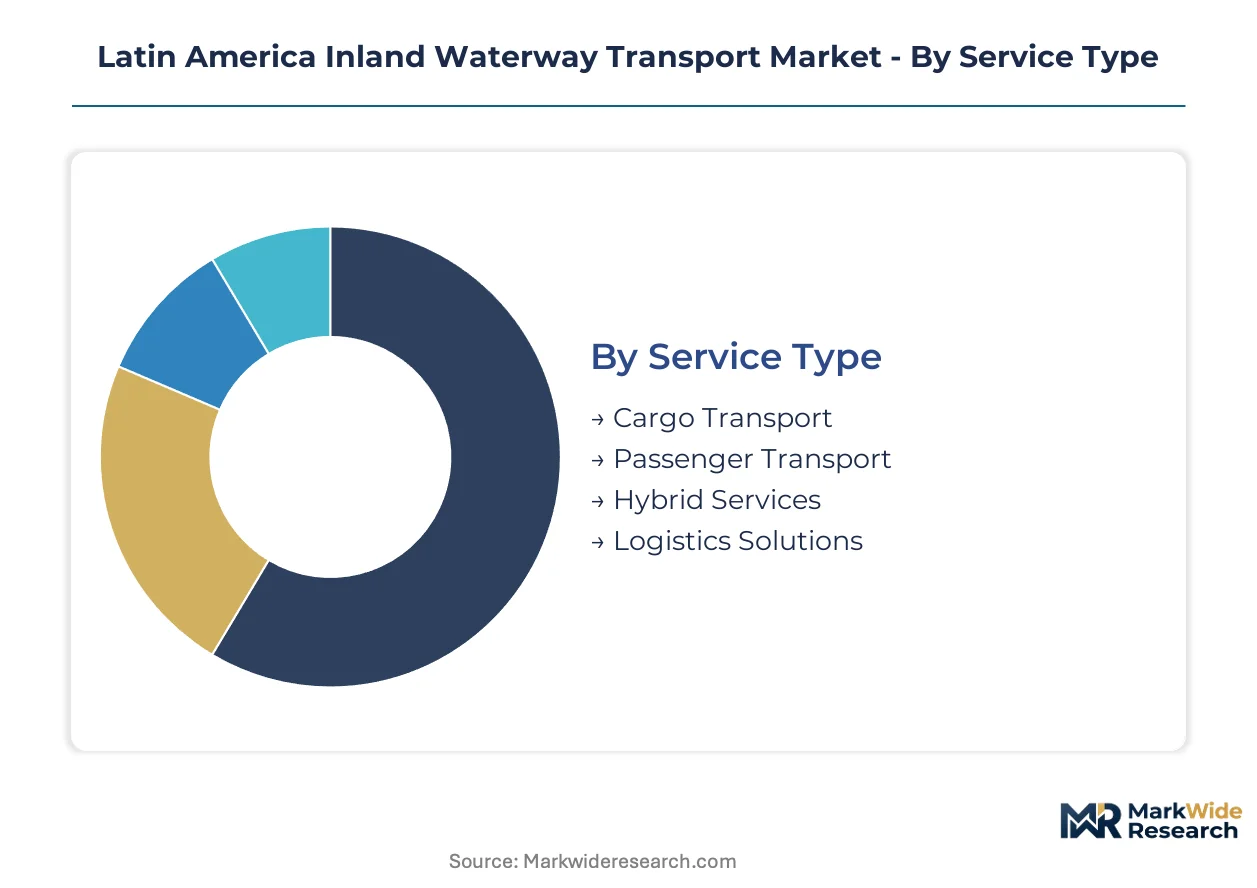
River transport economics vary sharply across service modes, vessel classes, and cargo types. Segment boundaries determine which operators capture margin pools from Brazil's soybean corridors versus Argentina's petroleum distribution networks.
Service Type:
Domestic cargo movements dominate northern Amazon basin operations, while export-led services concentrate along the Paraguay-Paraná corridor connecting Mato Grosso to Atlantic ports.
- Cargo Transport:Bulk commodity logistics for soybeans, corn, iron ore, and petroleum products utilizing shallow-draft barges with sub-three-meter ratings. Agricultural exporters across Brazil's interior are locking in long-term contracts as road-to-river migration accelerates.
- Passenger Transport:Scheduled ferry services and riverboat tourism connecting isolated communities across the Amazon basin and Pantanal wetlands. Demand clusters in Bolivia's Beni Department and Brazil's Pará state where road infrastructure remains sparse.
- Hybrid Services:Combined cargo-passenger operations serving remote riverine settlements with mixed-load vessels.
- Logistics Solutions:Integrated warehousing, transshipment, and customs coordination at tri-border terminals.
Cargo Transport commands the established base. The steepest expansion runs through Logistics Solutions.
Vessel Type:
Capital intensity and draft requirements create distinct competitive tiers across the fleet, with larger operators consolidating ownership of specialized tanker and container assets.
- Barges:Flat-bottomed cargo carriers designed for bulk agricultural and mineral movements across variable-depth waterways. Brazilian grain cooperatives in Mato Grosso are expanding barge fleet commitments to secure export capacity.
- Tankers:Double-hulled petroleum product distributors serving fuel depots along the Paraguay-Paraná corridor. ANTAQ environmental licensing mandates are accelerating ballast water treatment retrofits for cross-border traffic.
- Container Ships:Box-handling vessels enabling river-ocean transshipment at Brazilian deepwater ports.
- Tugboats:Pushboat and towboat fleets providing motive power for barge tows through shallow-draft stretches.
Barges anchor the volume base. Tankers capture the widest margin spreads.
End User:
Customer concentration patterns reflect commodity export cycles, with agribusiness procurement timing driving seasonal fleet utilization spikes.
- Agriculture:Soybean and corn exporters utilizing river routes for bulk movements from Brazil's interior to Atlantic terminals. Mato Grosso cooperatives are unbundling long-term contracts into shorter voyage charters with fuel-adjustment clauses.
- Oil & Gas:Petroleum distributors and downstream fuel marketers dependent on tanker fleets for interior supply. Divergent fuel taxation regimes between Argentina, Brazil, and Paraguay distort route economics for multi-country voyages.
- Manufacturing:Industrial shippers of containerized manufactures and heavy equipment.
- Tourism:Expedition cruise operators and community ferry services.
Agriculture commands the established base. Oil & Gas maintains the most stable contract pricing.
Technology:
Digital adoption rates split between navigation safety systems and back-office cargo management platforms, with regulatory mandates accelerating certain upgrade cycles.
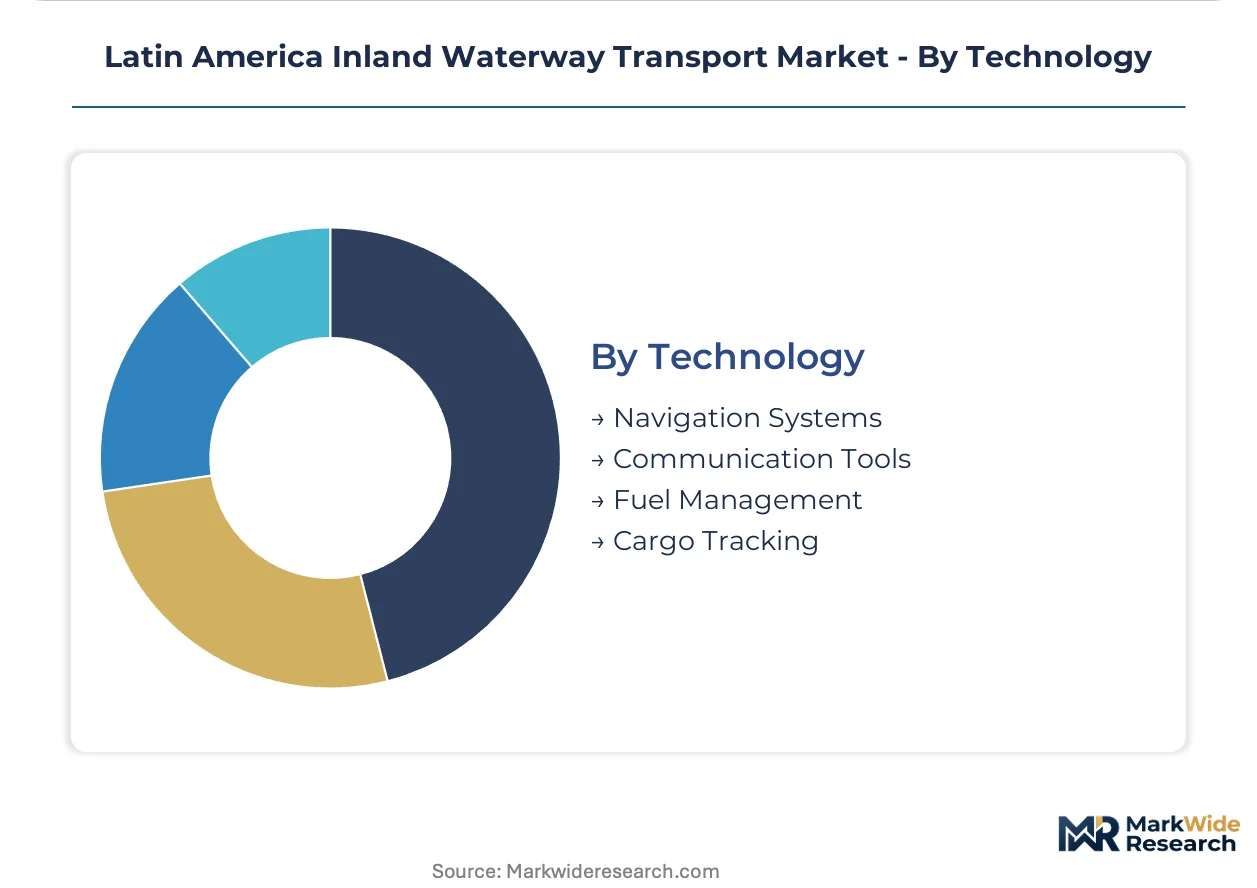
- Navigation Systems:Real-time sonar bathymetry and cloud-based hydrological modeling for draft optimization. Fleet operators across the Paraguay-Paraná corridor are deploying these systems to maximize loading during marginal water periods.
- Cargo Tracking:RFID and GPS-enabled shipment visibility platforms for grain traders monitoring export timing. Agribusiness buyers are demanding granular location data to coordinate harvest-to-port logistics.
- Communication Tools:VHF radio networks and satellite connectivity for remote river stretches.
- Fuel Management:Consumption monitoring and emissions compliance systems for engine performance optimization.
Navigation Systems commands the established base. Cargo Tracking is climbing the fastest as spot-market platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along Brazil's Paraguay-Paraná corridor where ANTAQ concession reforms attract terminal investments, while Argentine operators face compressed margins from divergent fuel taxation regimes that distort cross-border voyage economics.
Brazil
Soybean and corn exporters in Mato Grosso are accelerating barge fleet commitments as agricultural volumes migrate from road haulage to river routes. ANTAQ port concession frameworks are unlocking private capital for barge-loading infrastructure along the Paraguay-Paraná waterway. The tri-border region where Brazil meets Argentina and Paraguay anchors the continent's densest concentration of shallow-draft bulk terminals.
Argentina
Petroleum distributors along the Paraná River depend on tanker fleets for interior fuel supply despite navigation depth constraints during dry seasons. The Comisión Administradora del Río de la Plata imposes wetland protection mandates that extend terminal construction timelines. Rosario and Santa Fe provinces cluster the country's principal river-ocean transshipment capacity for agricultural exports.
Paraguay
Landlocked grain traders leverage the Hidrovía system for Atlantic export access, with barge movements dominating soybean and corn logistics. Cross-border tariff friction with neighboring Brazil and Argentina complicates multi-country voyage planning for fleet operators. The Asunción-Ciudad del Este corridor concentrates national waterway commerce and customs coordination infrastructure.
Bolivia
The Autoridad de Regulación y Fiscalización de Electricidad y Aguas is opening navigable corridors connecting the Chapare region to Atlantic export routes via Paraguay. Rainfall-dependent depth variations in the Pantanal wetlands constrain year-round vessel sizing for commodity movements. Beni Department and Santa Cruz province host the primary riverine settlements where mixed cargo-passenger services sustain isolated communities.
Uruguay
Feeder barge connections at Montevideo's deepwater port are integrating with Brazilian river networks for containerized manufactures transshipment. The country's smaller fleet footprint limits direct competition with larger neighbors but creates niche opportunities for logistics coordination services. The Río de la Plata estuary serves as the critical convergence point for Paraguay-Paraná basin exports reaching Atlantic markets.
Latin America Inland Waterway Transport Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Latin America inland waterway transport market. The competitive structure splits between integrated ocean carriers extending feeder services into river networks and specialized barge operators with basin-specific operational knowledge. Three archetypes dominate: Amazon basin specialists with year-round draft management capabilities, Hidrovía system bulk commodity haulers, and container line affiliates synchronizing river-ocean transshipment. Capacity expansion through barge fleet commitments and concession-based terminal investments represent the primary competitive vectors as agricultural exporters lock in long-term contracts.
Among Brazilian river specialists, Hermasa Navegacao Da Amazonia Ltda and Chibatao Navegacao E Comercio Ltda exemplify the basin-focused archetype with Amazon operational footprints. CMA CGM occupies a position representing integrated ocean carrier strategies that anchor South American inland networks through barge-feeder connections. These three entities illustrate the strategic divergence between geographically concentrated expertise and global network integration that shapes competitive positioning across the region's waterway systems.
| Leading Market Players |
|---|
| Agnamar SA |
| Hermasa Navegacao Da Amazonia Ltda |
| National Shipping SA |
| Chibatao Navegacao E Comercio Ltda |
| UABL Paraguay SA |
| Maersk Line |
| CMA CGM |
| MSC Mediterranean Shipping Company |
| Hamburg Sud |
| Others |
Pricing and Supply Chain Analysis
ANTAQ environmental licensing protocols gate both vessel qualification and contract pricing tiers across Brazil's Paraguay-Paraná corridor, creating dual barriers that separate compliant operators from price-competitive alternatives.
Pricing Analysis
Cross-border spreads between Brazilian and Argentine terminals compress barge rate premiums as fuel taxation divergences distort voyage economics. Contract structures stratify across premium, standard, and economy tiers based on ballast water treatment certification and fuel-adjustment clause inclusion. Pricing pressure stems from agribusiness buyers unbundling long-term commitments into shorter voyage charters. Grain cooperatives in Mato Grosso exhibit highest price sensitivity, while petroleum distributors maintain stable contract pricing.
Supply Chain Analysis
Port congestion at Rosario and seasonal container availability constraints along the Río de la Plata feed into inbound logistics cost volatility for vessel equipment imports. Supply concentrates in Brazil, Argentina, and China for pushboat engines, barge hull materials, and navigation electronics. Fleet operators draw from steel plate, marine diesel, and satellite positioning hardware inputs. Single-source vulnerability runs through specialized river pilot training pipelines. Distribution runs through concession-based terminal networks and spot-market charter platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as digital route optimization and spot-market charter platforms restructure how cargo capacity matches export timing across the Hidrovía system.
For Market Incumbents: Shield terminal lease positions through ANTAQ concession renewals while accelerating ballast water treatment retrofits ahead of compliance deadlines. Consolidate contract volumes with Mato Grosso grain cooperatives to defend against spot-market fragmentation. Vertical integration into pilot training programs addresses qualified crew scarcity threatening fleet expansion timelines. For New Entrants and Emerging Players: Night navigation services on unlit Amazon stretches represent underserved demand where autonomous pilot technologies can establish first-mover positioning. Target Bolivia's Chapare corridor as the most penetrable geography given new navigable corridor openings. Pursue integrated logistics solutions bundling warehousing and customs coordination at tri-border terminals. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across tanker fleet segments as ANTAQ environmental mandates accelerate vessel upgrade cycles. Long-term viability favors operators with in-house compliance capabilities and basin-specific operational knowledge. Monitor draft harmonization negotiation outcomes between Brazil, Argentina, and Paraguay as the critical inflection signal for cross-border route economics.| Strategic Initiative | Industry Significance |
|---|---|
| Concession-Based Terminal Investment | ANTAQ framework unlocks private capital for barge-loading infrastructure along Paraguay-Paraná waterway. |
| Ballast Water Treatment Retrofit | Environmental compliance investments separate certified operators from price-competitive alternatives in cross-border traffic. |
| Digital Route Optimization Deployment | Real-time sonar bathymetry extends operational windows during historically marginal water periods. |
| Integrated Barge-Feeder Network | Synchronized river-ocean transshipment captures containerized manufacture demand at Brazilian deepwater ports. |
| Autonomous Navigation Pilot Program | Machine-learning depth prediction enables safer night operations on unlit stretches. |
Research Methodology
Operator-level perspectives from fleet managers, terminal concession holders, river pilots, agribusiness logistics directors, and ANTAQ regulatory officials anchored the qualitative base. These primary inputs combined with secondary validation from customs trade records, ANTAQ concession filings, hydrological monitoring databases, and vessel registration systems. Bottom-up fleet capacity assessments and top-down commodity flow estimates provided triangulation across analysis approaches.
Sensitivity analysis tested forecast robustness across draft variability scenarios and concession timing assumptions throughout the projection horizon. Segmentation dimensions modeled include service type, vessel class, cargo category, technology adoption tier, and country-level regulatory cluster. CAGRs derived from historical volume trajectories and infrastructure investment pipelines. Industry-specific inputs incorporated soybean export cycle timing and seasonal rainfall patterns affecting navigable depth.
Material uncertainties — regulatory harmonization delays, extreme weather disruptions, and crew training pipeline failures — sit outside the modeled envelope. Forecasts reflect assumptions about concession implementation schedules and commodity price stability sustaining road-to-river migration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Hungary Road Freight Transport Market