
 Italy Road Freight Transport Market | 2026-2036
Italy Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Road Freight Transport Market Foresight
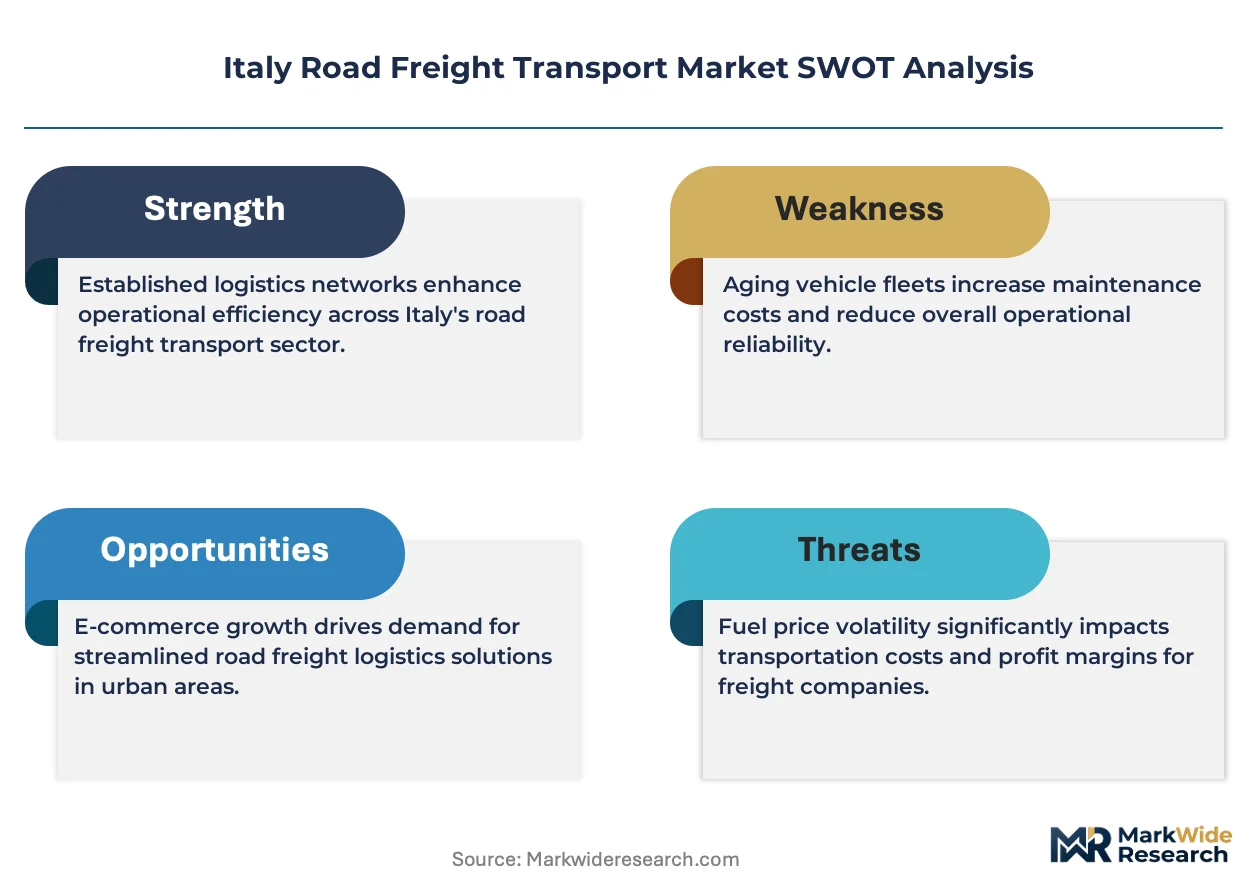
Last-mile distribution networks are tilting toward consolidated hub-and-spoke models across northern Italy. DACHSER leverages its European network density to anchor cross-border flows through the Brenner corridor. Arcese Trasporti SpA sustains competitive positioning via specialized temperature-controlled fleets serving pharmaceutical clients. Poste Italiane controls extensive last-mile infrastructure that competes with parcel specialists in e-commerce fulfillment.
Italy road freight transport encompasses the movement of goods by motorized vehicles on the national road network, utilizing trucks with gross vehicle weights ranging from 3.5 tonnes to 44 tonnes under EU Directive 96/53/EC. The sector functions as the dominant domestic cargo mode, handling manufactured goods, perishables, and construction materials across a peninsula-shaped geography with limited rail alternatives. Full Truck Load operations dominate volume throughput on the Milan-Rome-Naples axis, while Less Than Truck Load services capture margin concentration in fragmented SME manufacturing supply chains. Refrigerated Trucks represent the fastest-expanding vehicle category, driven by pharmaceutical cold-chain requirements and fresh food export protocols.
Italy's Ministry of Infrastructure and Transport enforces EU Regulation 2019/1242 on CO2 emissions standards for heavy-duty vehicles, while the National Recovery and Resilience Plan allocates dedicated funding for green fleet renewal. The EU Green Deal's Fit for 55 package tightens carbon intensity benchmarks that reshape vehicle procurement timelines and route optimization investments. Stakeholders must monitor how the EU Emissions Trading System extension to road transport alters total cost of ownership calculations and carrier consolidation incentives.
Market Dynamics
The EU Green Deal's Fit for 55 package is compressing fleet procurement timelines as carriers scramble to meet 2030 CO2 reduction benchmarks for heavy-duty vehicles. This regulatory pressure intersects with pharmaceutical cold-chain expansion to reshape asset allocation across the peninsula.
Growth Catalysts
- Pharmaceutical Cold-Chain Mandates:Temperature-sensitive biologics now require validated refrigerated transport from manufacturing sites in Lombardy to distribution hubs, expanding specialized fleet demand.
- EU Emissions Trading System Extension:The phased inclusion of road transport under carbon pricing mechanisms alters total cost of ownership calculations and accelerates green fleet renewal investments.
- Brenner Corridor Freight Intensity:Cross-border flows between Italy and German-speaking markets concentrate volume through Alpine passes, sustaining dedicated route density for full truckload operators.
Market Restraints
- Diesel Price Volatility:Fuel represents 30-35% of operating costs for Italian carriers, exposing margins to energy market swings without full pass-through mechanisms.
- Driver Shortage Concentration:The profession's aging demographic and restricted non-EU labor access tighten capacity in the Po Valley manufacturing belt.
- Rail Infrastructure Underinvestment:Limited intermodal alternatives in the Apennine spine force road dependence on long-haul routes, inflating per-ton-kilometer costs.
Strategic Opportunities
- Sicily-Linked Continental Connectivity:Ferry-integrated road services connecting Catania and Palermo to mainland distribution networks remain underdeveloped relative to freight potential.
- Biomethane Retrofit Incentives:Italy's National Recovery and Resilience Plan allocates dedicated funding for alternative fuel conversions, lowering entry barriers for smaller fleet operators.
- Last-Mile Consolidation Hubs:E-commerce fulfillment density in the Milan metropolitan area supports multi-tenant logistics platforms that pool delivery capacity across retailers.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems resist seamless connection to real-time carbon monitoring platforms required by EU Regulation 2019/1242 compliance.
- Refrigeration Technician Scarcity:Specialized maintenance skills for pharmaceutical-grade temperature control units command premium wages and extended recruitment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Road Freight Transport Market |
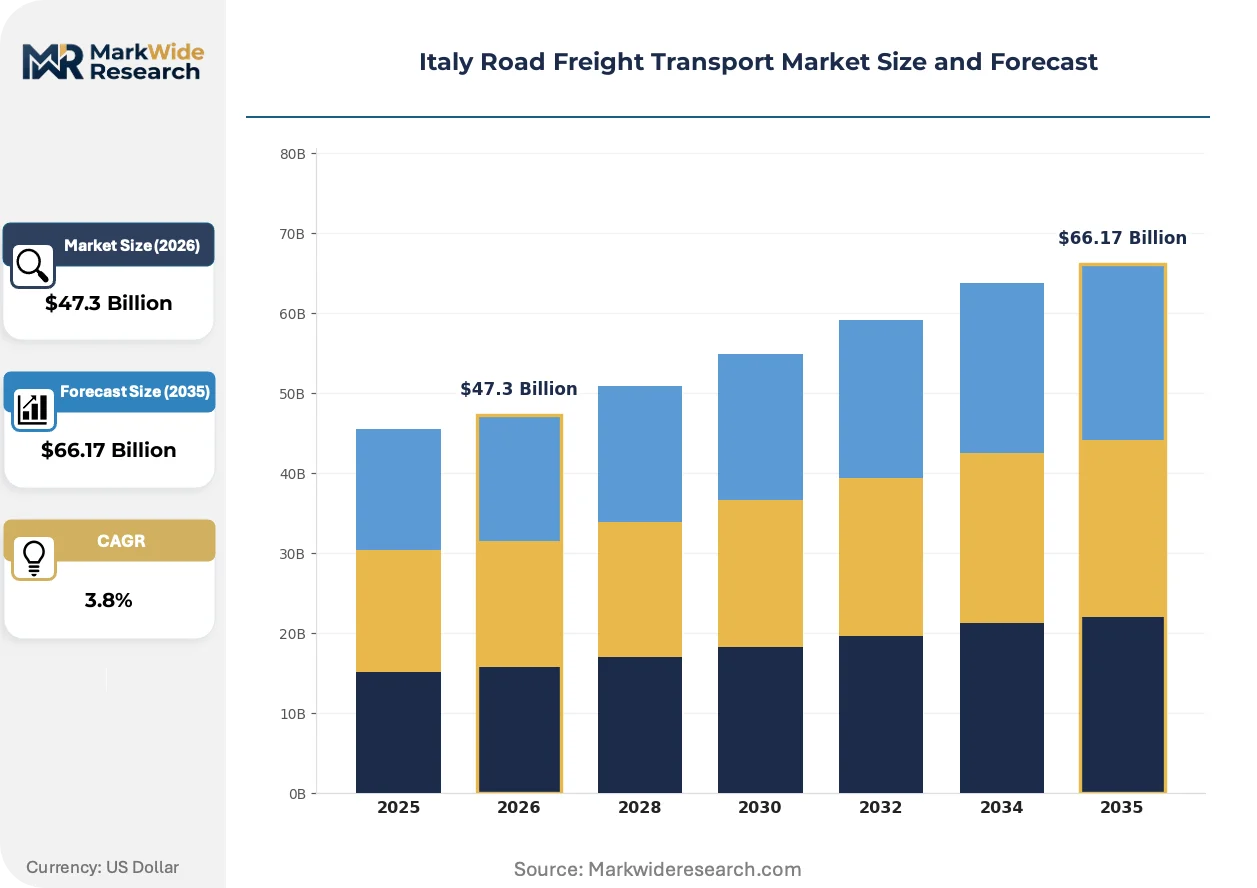
| Market Size in 2026 | $47.3 Billion |
| Market Size in 2035 | $66.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Express Delivery, Intermodal Transport End User: Retail, Manufacturing, Construction, Pharmaceuticals Vehicle Type: Heavy-Duty Trucks, Light Commercial Vehicles, Refrigerated Trucks, Container Trucks Delivery Method: Direct Delivery, Scheduled Delivery, On-Demand Delivery, Consolidated Shipment |
| Companies Covered | DACHSER, Kuehne+Nagel, DSV A/S (Including DB Schenker), Girteka, Poste Italiane, DHL Group, Arcese Trasporti SpA, Savino Del Bene, La Poste Group (Including BRT), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Road Freight Transport Market Shifts & Advancements
Digital freight platforms are compressing traditional broker margins while telematics penetration enables outcome-based pricing models. Fleet electrification timelines accelerate as charging infrastructure density improves along the A1 motorway corridor.
Telematics-enabled predictive maintenance is collapsing unplanned downtime costs for temperature-controlled fleets. Pharmaceutical shippers now mandate real-time cargo monitoring as a contract precondition. This capability compression is eliminating smaller carriers lacking capital for sensor deployment and cloud analytics integration.
EU Regulation 2019/1242 tightens CO2 emissions standards for heavy-duty vehicles through 2030. Carriers must accelerate procurement of alternative drivetrain technologies or face penalties that erode contract competitiveness. The Lombardy-Veneto logistics corridor sees earliest compliance investment due to multinational shipper pressure.
Shippers increasingly unbundle transportation from warehousing contracts to optimize modal flexibility. Fragmentated Italian manufacturing SMEs now aggregate volumes through digital freight marketplaces rather than maintaining dedicated carrier relationships. This disintermediation concentrates most rapidly in the automotive component supply chain serving Emilia-Romagna assembly plants.
Italy Road Freight Transport Market Segmentation
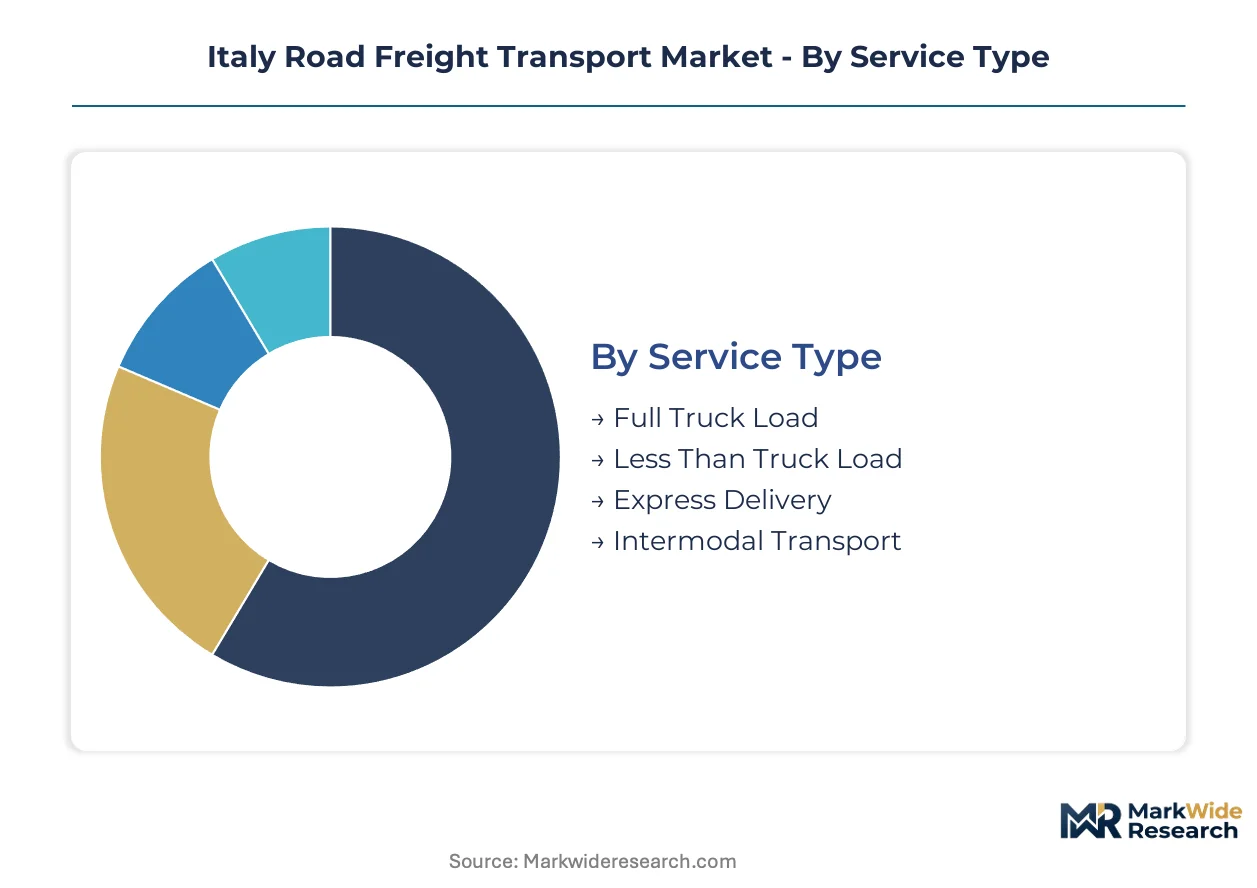
Segmentation in Italy's road freight market exposes how service specialization, regulatory pressure, and geographic constraints fragment carrier economics. Understanding these divisions clarifies where capital deployment yields returns and where margin compression threatens sustainability.
Service Type:
Cost tier differentiation separates asset-heavy full truckload operations from margin-concentrated consolidation services.
- Full Truck Load:Dedicated vehicle capacity moves single-shipper cargo across the Milan-Rome-Naples axis. Manufacturing clusters in Emilia-Romagna sustain dense route economics for steel, automotive components, and industrial machinery.
- Less Than Truck Load:Multi-shipper consolidation captures premium margins from fragmented SME manufacturing supply chains. Hub-and-spoke density in the Lombardy-Veneto corridor enables overnight regional coverage that full truckload cannot match.
- Express Delivery:Time-definite services command surcharge pricing for automotive just-in-sequence and pharmaceutical emergency shipments.
- Intermodal Transport:Rail-road combinations reduce carbon exposure on long-haul routes, though limited terminal infrastructure constrains penetration south of Rome.
Full Truck Load commands the established base. The steepest expansion runs through Express Delivery.
End User:
Application-specific requirements reshape fleet specifications and compliance investments across customer verticals.
- Retail:E-commerce fulfillment drives demand for flexible last-mile capacity with real-time tracking integration. Milan metropolitan density supports multi-tenant consolidation hubs that pool delivery resources across competing retailers.
- Manufacturing:Just-in-time automotive and machinery supply chains require synchronized inbound logistics to assembly plants in Turin, Bologna, and Melfi. EU Emissions Trading System extension pressures contract renegotiation toward lower-carbon carrier selection.
- Construction:Project-based bulk material movement faces seasonal volume swings and permitting delays for heavy-load corridor access.
- Pharmaceuticals:Temperature-sensitive biologics mandate validated cold-chain transport from Lombardy manufacturing sites to distribution hubs.
Manufacturing anchors volume throughput. Pharmaceuticals posts the steepest expansion trajectory.
Vehicle Type:
Supply concentration in alternative drivetrain procurement is forcing accelerated fleet renewal timelines under EU Regulation 2019/1242.
- Heavy-Duty Trucks:Tractor-trailer combinations from 18 to 44 tonnes handle bulk commodity and full truckload volume across Alpine transit corridors. The Brenner Pass route concentration sustains dedicated fleet deployment for German-speaking market access.
- Refrigerated Trucks:Insulated cargo bodies with integrated refrigeration units maintain pharmaceutical-grade temperature protocols. Cold-chain validation requirements from EMA guidelines expand specialized fleet demand faster than standard dry van replacement cycles.
- Light Commercial Vehicles:Urban last-mile delivery operates under stricter municipal access restrictions in Milan, Rome, and Naples low-emission zones.
- Container Trucks:Skeletal chassis configurations serve intermodal terminal drayage at Genoa, La Spezia, and Gioia Tauro ports.
Heavy-Duty Trucks command the established base. Refrigerated Trucks are climbing the fastest.
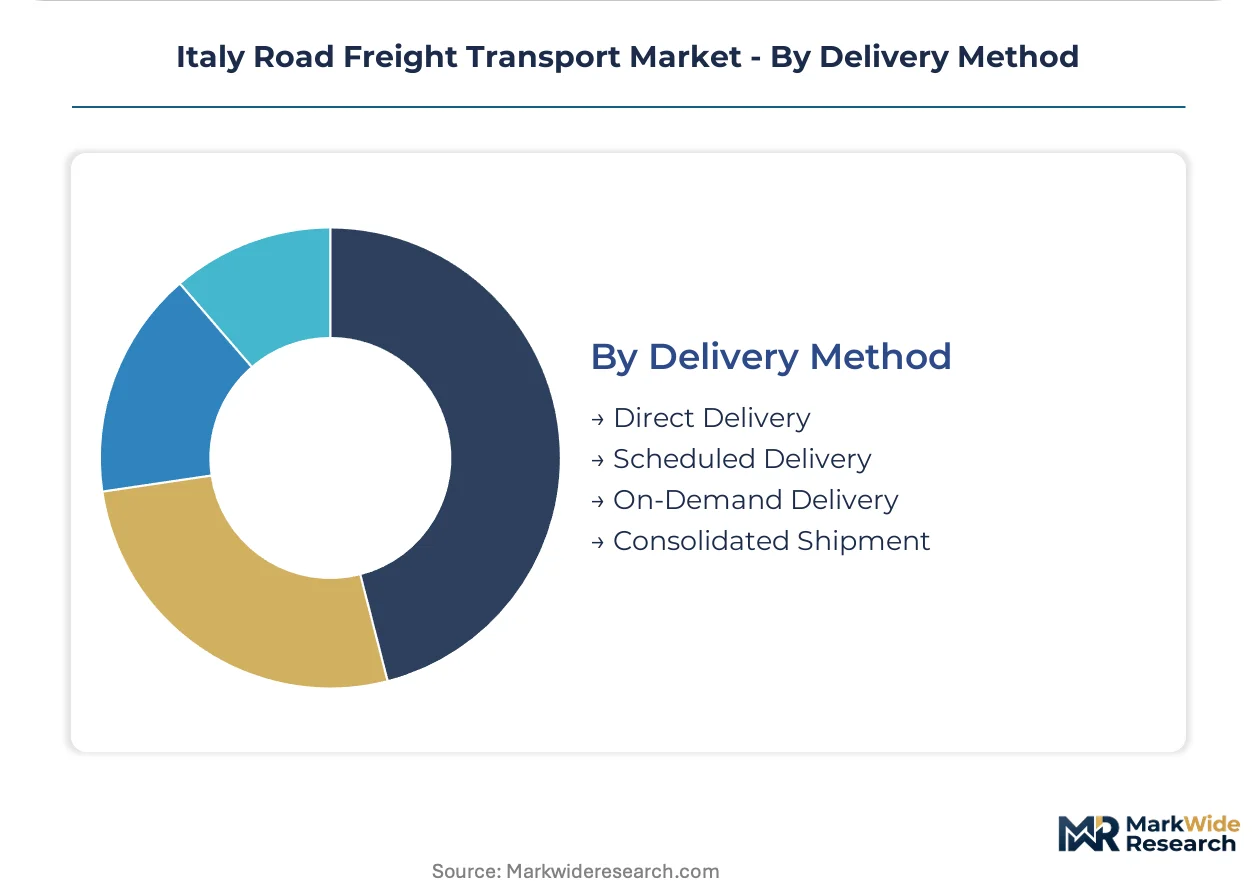
Delivery Method:
Customer type stratification separates enterprise contract logistics from transactional spot market engagement.
- Direct Delivery:Point-to-point shipment without intermediate handling preserves cargo integrity for high-value pharmaceuticals and precision manufacturing components. Shipper payment terms and fuel surcharge pass-through mechanisms vary by contract tenure.
- Scheduled Delivery:Recurring lane assignments with fixed departure windows enable carrier fleet optimization and driver route familiarization.
- On-Demand Delivery:Spot market capacity procurement through digital freight platforms compresses traditional broker margins while expanding SME access to flexible transport.
- Consolidated Shipment:Multi-order aggregation reduces per-unit transport cost for fragmented Italian manufacturing exporters.
Scheduled Delivery commands the established base. On-Demand Delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Pass motorway corridor underwrites northern Italy's dominance in trans-Alpine freight flows, connecting Milan and Verona to German-speaking markets through Austria.
Lombardy
Pharmaceutical manufacturing in Milan and Bergamo generates temperature-controlled cargo requiring validated cold-chain transport to European distribution hubs. The National Recovery and Resilience Plan directs alternative fuel subsidies toward fleet operators serving the Milan metropolitan logistics zone. Multinational contract logistics providers concentrate warehouse capacity around Malpensa Airport and the A4 motorway corridor.
Veneto
Fresh produce exports from Verona and Padua drive refrigerated truck demand toward German and Austrian retail networks. EU Green Deal emissions benchmarks accelerate biomethane retrofit investments among Padua-based fleet operators. The Port of Venice container terminal expansion feeds intermodal drayage demand across the Veneto-Friuli industrial belt.
Emilia-Romagna
Automotive component suppliers in Modena and Bologna synchronize just-in-time deliveries to Turin and Melfi assembly plants. EU Regulation 2019/1242 compliance timelines pressure carrier procurement of lower-emission tractor units serving the A1 motorway. Bologna's logistics platforms consolidate Less Than Truck Load volumes from fragmented machinery manufacturing SMEs.
Piedmont
Steel and industrial machinery shipments from Turin and Novara sustain Full Truck Load density on Alpine transit routes toward France and Switzerland. The EU Emissions Trading System extension alters total cost calculations for cross-border operators maintaining Turin-Lyon corridor capacity. Fiat Stellantis assembly plants in Mirafiori anchor dedicated inbound logistics networks.
Lazio
E-commerce fulfillment demand in Rome concentrates last-mile delivery capacity competition between postal operators and parcel specialists. Municipal low-emission zone restrictions in the capital accelerate light commercial vehicle fleet renewal toward electric drivetrains. Ciampino and Fiumicino airport cargo zones attract pharmaceutical distribution hub investment serving central-southern markets.
Italy Road Freight Transport Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in niche capacity segments. The Italian road freight market exhibits tiered consolidation, with pan-European networks controlling cross-border volume while regional carriers defend specialized temperature-controlled lanes. Three archetypes dominate: multinational contract logistics platforms, family-owned temperature-specialist fleets, and postal-owned parcel networks. Competitive dynamics center on cross-border acquisition activity and alternative drivetrain fleet renewal.
Among pan-European network operators, DACHSER and DSV A/S exemplify the platform integrator archetype through Brenner corridor density. Kuehne+Nagel occupies a position within pharmaceutical cold-chain logistics. Arcese Trasporti SpA and Poste Italiane represent contrasting specialization paths—temperature-controlled manufacturing supply chains versus postal last-mile infrastructure.
| Leading Market Players |
|---|
| DACHSER |
| Kuehne+Nagel |
| DSV A/S (Including DB Schenker) |
| Girteka |
| Poste Italiane |
| DHL Group |
| Arcese Trasporti SpA |
| Savino Del Bene |
| La Poste Group (Including BRT) |
| Others |
Supply & Pricing Matrix
The Lombardy-Veneto logistics corridor concentrates refrigerated truck capacity for pharmaceutical cold-chain distribution, granting specialized carriers pricing leverage over multinational shippers demanding validated temperature protocols. Diesel price volatility and EU Emissions Trading System extension compress margins for standard dry van operators while insulating premium-tier cold-chain specialists from cost pass-through disputes.
Pricing Analysis
Volume-discount tiering structures separate contract-based full truckload rates from spot-market less than truckload premiums. Three-tier pricing stratifies across pharmaceutical-grade certified, standard temperature-controlled, and economy dry van levels, with EMA validation requirements commanding the widest spreads. Pricing pressure stems from digital freight platforms compressing traditional broker margins in fragmented SME manufacturing lanes. Automotive just-in-sequence shippers exhibit lowest price sensitivity due to penalty cost exposure, while construction material buyers negotiate hardest on fuel surcharge mechanisms.
Supply Chain Analysis
Contract manufacturing concentration in German and Austrian automotive component plants anchors northbound cross-border demand through the Brenner Pass. Vehicle chassis and powertrain components from Germany, precision electronics from Austria, and steel feedstock from Poland feed the Milan-Turin-Bologna manufacturing triangle. Single-source vulnerability concentrates in Alpine corridor capacity during winter closure windows. Distribution runs through hub-and-spoke consolidation centers in Verona and Padua before final mile injection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward multinational pharmaceutical and automotive OEMs consolidating carrier panels around EU Green Deal compliance credentials. This concentration fragments negotiating leverage for smaller fleet operators lacking alternative drivetrain scale.
For Market Incumbents: Harden cold-chain certification moats by investing in real-time telematics integration that EU Regulation 2019/1242 mandates for carbon monitoring. Secure biomethane retrofit capacity through National Recovery and Resilience Plan funding allocations before subsidy exhaustion. Defend against digital freight platform disintermediation by embedding into pharmaceutical shipper quality agreements as validated logistics partners rather than transactional vendors.
For New Entrants and Emerging Players: Sicily-linked continental connectivity through Catania and Palermo ferry-integrated road services represents the most penetrable entry point, with underdeveloped freight potential relative to mainland distribution density. Target last-mile consolidation hubs in the Milan metropolitan area where e-commerce fulfillment density supports multi-tenant platform economics. Enter through specialized refrigeration technician training partnerships that address scarcity premiums in pharmaceutical-grade maintenance.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned temperature-specialist fleets in the Veneto-Friuli industrial belt lacking succession liquidity or green fleet capital access. Long-term viability hinges on EU Emissions Trading System compliance cost pass-through capability and pharmaceutical shipper contract tenure. Watch for inflection in Brenner Pass toll rate negotiations and Austrian HGV transit restrictions as corridor economics shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomethane Fleet Retrofit | Italy's National Recovery and Resilience Plan subsidies lower total cost of ownership for alternative fuel conversions. |
| Telematics Platform Integration | Real-time carbon monitoring satisfies EU Regulation 2019/1242 compliance and pharmaceutical shipper contract preconditions. |
| Cross-Border Corridor Acquisition | Brenner Pass route density commands premium positioning for German-speaking market access. |
| Refrigeration Technician Training | Specialized maintenance skills scarcity creates wage premiums and extended recruitment cycles for validated cold-chain units. |
| Last-Mile Hub Consolidation | Milan metropolitan multi-tenant logistics platforms pool delivery capacity across competing retail e-commerce networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, pharmaceutical logistics procurement managers, automotive supply chain planners, and intermodal terminal operators. Secondary validation drew from EU Regulation 2019/1242 implementation guidance, Italy's Ministry of Infrastructure and Transport fleet renewal disclosures, EMA cold-chain validation guidelines, and Alpine corridor transit statistics. Bottom-up carrier capacity modeling and top-down GDP-correlated freight demand projections were triangulated against cross-border trade flow data.
Calibration approach anchored volume forecasts to segment-specific growth differentials across service type, vehicle category, and end-user vertical. The analytical framework modeled full truckload, less than truckload, express delivery, and intermodal transport segments alongside refrigerated truck, heavy-duty truck, and light commercial vehicle fleet composition. CAGRs were derived from regression against industrial production indices and pharmaceutical export volumes. Forecast inputs included EU Emissions Trading System carbon price assumptions and National Recovery and Resilience Plan subsidy allocation trajectories.
Macroeconomic conditions sit as an overlay; deviation in diesel price volatility, Alpine pass closure frequency, or EU carbon pricing enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline adherence and fleet renewal capital availability. Quarterly review of pharmaceutical export volumes, Brenner Pass freight intensity metrics, and biomethane infrastructure deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Germany Cold Chain Logistics Market