
 Global Industrial and Commercial LED Lighting Market | 2026-2036
Global Industrial and Commercial LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial and Commercial LED Lighting Market Intelligence
The EU Green Deal is realigning procurement priorities across European industrial estates by binding member states to phased mercury-lamp phaseouts and minimum efficacy thresholds. Signify NV leverages its intercontinental manufacturing footprint to sustain volume leadership in connected luminaire systems. Acuity Brands anchors North American specification channels through deep distributor relationships and digital lighting controls integration. Zumtobel Group AG specializes in high-bay architectural solutions for German automotive and logistics campuses.
Industrial and commercial LED lighting encompasses solid-state luminaires engineered from gallium nitride semiconductor substrates that emit directional photons at correlated color temperatures typically spanning 3000K to 6500K with system efficacies exceeding 130 lumens per watt, designed to replace legacy metal halide and fluorescent sources in facilities where operating hours exceed twelve daily cycles. High bay and panel light categories dominate current revenue pools across warehousing facilities and office buildings where ceiling heights and uniform glare control dictate specification. Surface mount device technology leads unit economics through automated pick-and-place assembly, while chip-on-board architectures capture premium positioning in floodlight and street light segments demanding superior thermal management.
The US Department of Energy's efficacy standards and China's GB certification requirements for solid-state lighting products shape baseline performance floors and market access conditions across the two largest manufacturing geographies. Ecodesign regulations under REACH and RoHS constrain phosphor chemistry and driver component selection for vendors serving European industrial buyers. Stakeholders must track how building electrification mandates and time-of-use rate structures reshape total-cost-of-ownership calculations against simple payback metrics.
Market Dynamics
Connected LED arrays with embedded sensors and wireless controls are compressing replacement cycles across industrial facilities, as warehouse operators prioritize energy data visibility over simple lumen output. This convergence of lighting and building automation is restructuring procurement criteria and vendor selection frameworks.
Growth Catalysts
- EU Green Deal mercury-lamp phaseouts:Binding member-state deadlines for fluorescent tube elimination are forcing retrofit decisions in German and French logistics campuses before equipment end-of-life.
- Industrial electricity rate spreads:Facilities in Italy and California face peak demand charges exceeding fifteen cents per kilowatt-hour, making high-efficacy LED payback periods attractive to CFOs.
- Gallium nitride driver miniaturization:Semiconductor advances are shrinking power-supply footprints, enabling slimmer high-bay housings that reduce shipping cube and installation labor.
Market Restraints
- Rare earth phosphor concentration:Europium and terbium supply chains route through Chinese state-controlled refiners, creating input cost volatility for warm-white LED formulations.
- Legacy magnetic-ballast infrastructure:Thousands of US manufacturing plants retain T12 fluorescent systems with incompatible wiring topologies that complicate LED retrofit electrical work.
- REACH substance restrictions:ECHA constraints on halogenated flame retardants are eliminating established driver PCB materials, forcing rapid supplier qualification cycles.
Strategic Opportunities
- Human-centric lighting in healthcare:Circadian-tunable LED systems for hospital patient rooms and surgical suites remain underdeployed in Spain and Poland relative to Nordic adoption rates.
- Li-Fi data transmission convergence:Integration of visible-light communication chips into commercial panels creates new revenue streams from building connectivity infrastructure.
- US Inflation Reduction Act 179D deductions:Accelerated depreciation for energy-efficient commercial building upgrades expands project finance capacity for multi-site retrofit portfolios.
Industry Challenges
- Controls integration talent scarcity:Facility managers lack personnel trained in DALI-2 and Bluetooth Mesh commissioning, delaying connected lighting deployment timelines.
- Dual-carbon compliance documentation:Chinese manufacturers must navigate MEE emissions reporting and EU CBAM carbon-border declarations simultaneously, adding administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial and Commercial LED Lighting Market |
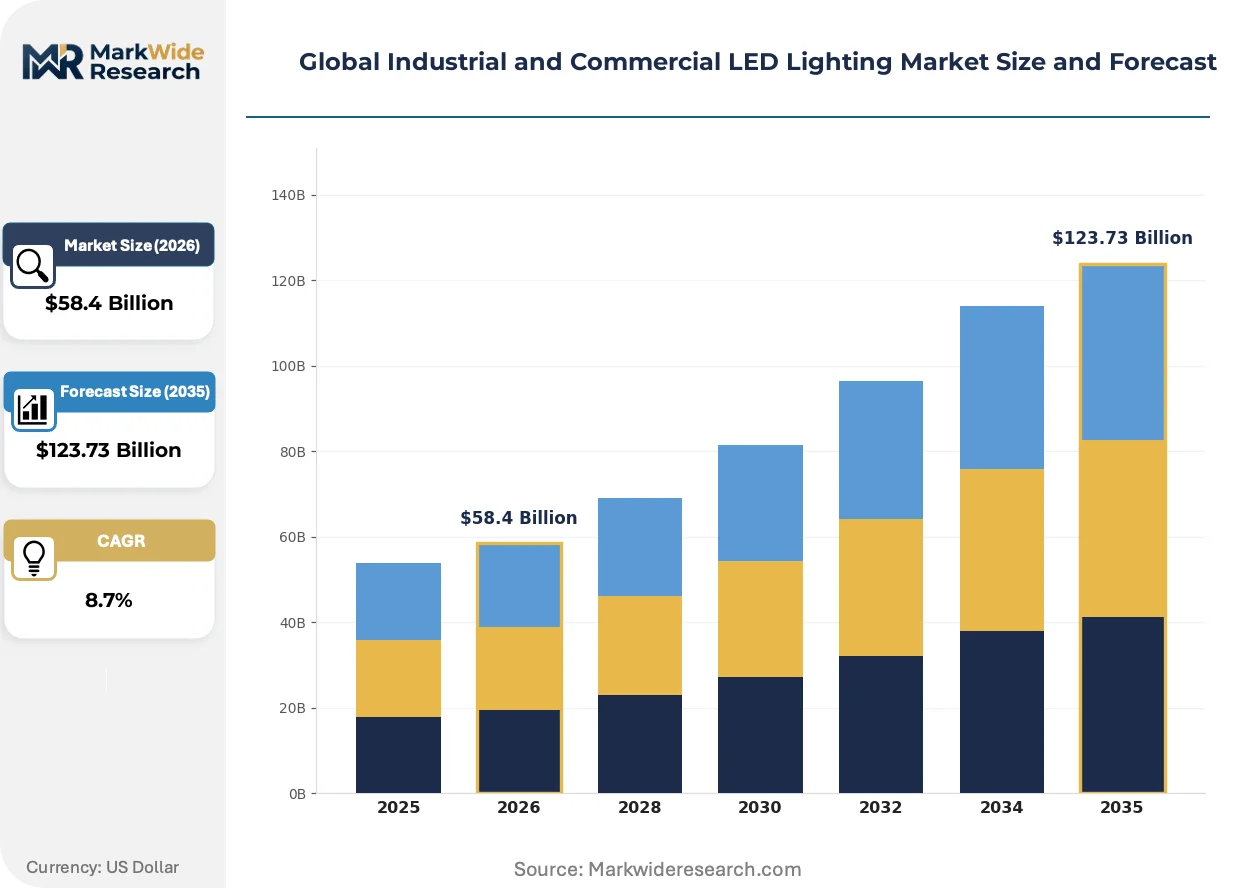
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Bay, Low Bay, Floodlights, Panel Lights, Street Lights Technology: SMD, COB, Filament, Chip-on-Board, Surface Mount Application: Warehouses, Warehousing Facilities, Shopping Complexes, Office Buildings, Convention Centers End User: Manufacturing Plants, Corporate Offices, Logistics Centers, Hospitality Venues |
| Companies Covered | Osram GmbH, Hubbell Incorporated, Signify NV (Philips Lighting), Siteco GmbH, WAC Lighting, Acuity Brands Inc., Zumtobel Group AG, Eaton Corporation, Cree Lighting (Ideal Industries Inc.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial and Commercial LED Lighting Market Strategic Shifts & Innovations
Lighting hardware is becoming a software-defined platform, with firmware updates and sensor fusion replacing static luminaire specifications. This transition is rewiring R&D priorities across the supplier base.
Chip-on-board LED engines with integrated optics and thermal management are modularizing high-bay product architectures. Automotive paint-booth operators in Stuttgart and Wolfsburg are specifying these units for rapid field replacement without electrician dispatch. The technology is modularizing maintenance contracts into component-swap subscriptions rather than fixture-warranty models.
China's GB certification requirements for solid-state lighting are tightening efficacy floors and flicker metrics ahead of IEC harmonization. Domestic manufacturers in Guangdong and Zhejiang are retooling driver designs to meet the stricter thresholds. Export-oriented suppliers face dual-track testing protocols that extend product launch timelines by eight to twelve weeks.
Lighting-as-a-service contracting is displacing capital purchase models in US commercial real estate portfolios. Blackstone and Prologis are bundling LED upgrades into triple-net lease structures where efficiency guarantees replace equipment ownership. This shift concentrates buyer power with national facility-management platforms and marginalizes regional electrical distributors.
Global Industrial and Commercial LED Lighting Market Segmentation
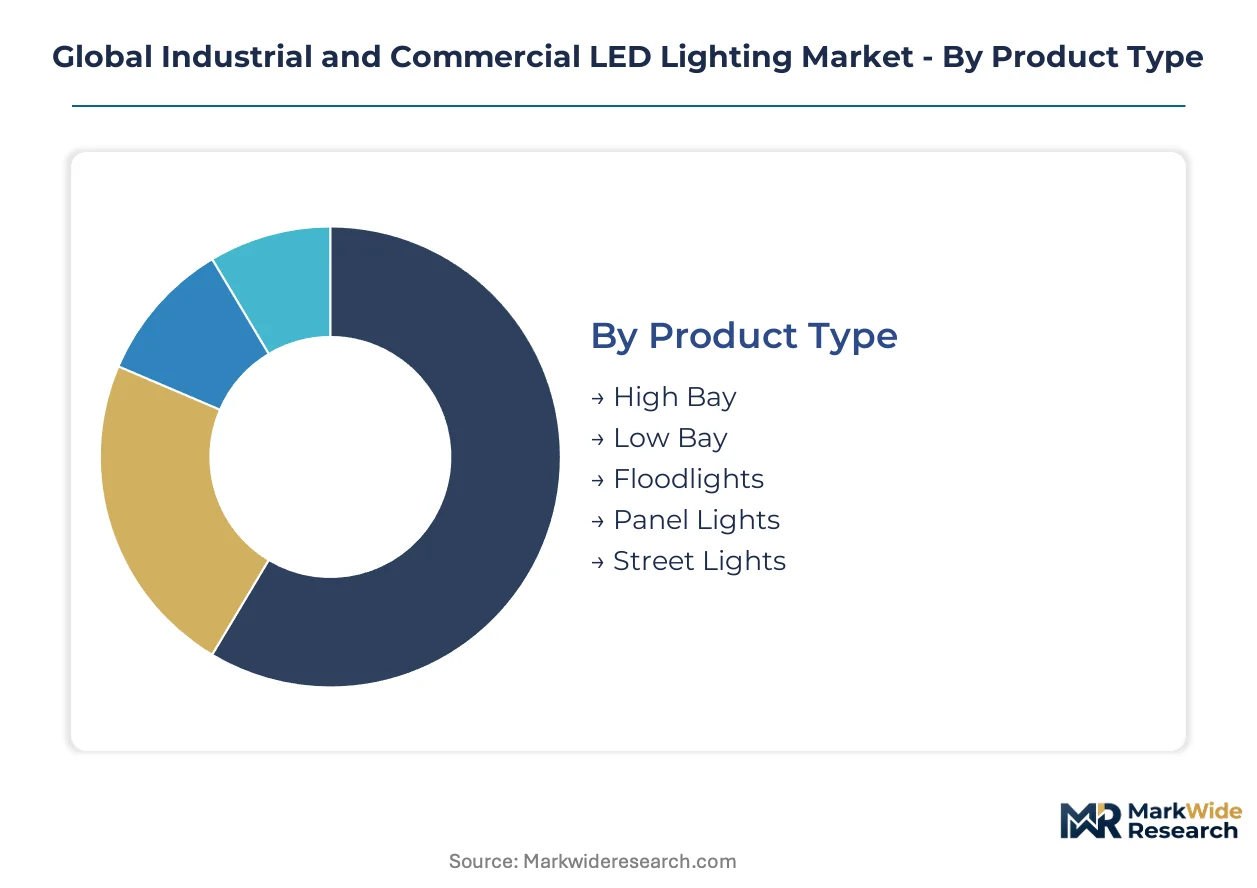
LED lighting procurement divides sharply between specification-driven industrial retrofits and cost-sensitive commercial rollouts. Understanding where volume concentrates versus where margins expand allows vendors to align R&D spend and channel strategy against actual buyer behavior.
Product Type:
Volume concentrates in high-bay and panel formats where warehouse and office retrofits drive repeat purchase contracts; premium positioning belongs to specialized floodlight and street-light architectures demanding thermal engineering excellence.
- High Bay:Engineered for mounting heights exceeding six meters with lumen packages above 15,000 lumens and integrated motion-sensing capabilities. Demand clusters in German automotive assembly plants and US cold-storage distribution centers where the EU Green Deal and California Title 24 mandates accelerate HID replacement timelines.
- Panel Lights:Recessed or surface-mounted flat-form luminaires delivering uniform illuminance across open-plan office ceilings. Corporate real estate managers in London and Singapore specify these for WELL Building certification compliance, though price compression from Chinese OEMs erodes specification margins.
- Low Bay:Lower-lumen variants for retail and light-manufacturing environments with ceiling heights under six meters.
- Floodlights:High-output directional luminaires for perimeter security and sports-field illumination requiring IP66+ ingress protection.
- Street Lights:Cobra-head and decorative pole-mounted fixtures governed by municipal procurement cycles and dark-sky compliance ordinances.
Today's leader: High Bay. Tomorrow's challenger: Panel Lights.
Technology:
Cost structure separates automated surface-mount assembly from premium chip-on-board thermal architectures; the technology choice determines whether vendors compete on unit economics or specification consulting.
- SMD:Surface-mount device packages assembled through high-speed pick-and-place automation achieving sub-dollar per-kilolumen production costs. Guangdong contract manufacturers dominate volume output for commercial retrofit projects across Southeast Asia and Eastern Europe.
- COB:Chip-on-board configurations with phosphor-coated LED arrays directly bonded to metal-core PCBs for superior thermal dissipation. German automotive paint booths and Dutch greenhouse operators specify COB engines for color stability under continuous operation.
- Filament:Vintage-aesthetic LED designs mimicking incandescent tungsten for hospitality and retail ambiance applications.
- Chip-on-Board:Modular integrated engines combining optics, thermal management, and driver electronics for rapid field replacement.
- Surface Mount:Standardized LED packages for linear and troffer retrofit lamps serving T8 and T5 fluorescent replacement markets.
SMD commands current volume leadership; COB architectures are climbing the fastest as industrial buyers prioritize thermal reliability over first cost.
Application:
Facility type dictates specification intensity: logistics campuses demand sensor-integrated energy management while commercial interiors prioritize glare control and circadian tuning.
- Warehouses:High-rack storage facilities with operating schedules exceeding 18 hours daily where connected LED arrays with daylight harvesting deliver measurable demand-charge reductions. Prologis and GLP facilities in California and the Netherlands anchor specification-grade procurement.
- Office Buildings:Multi-tenant commercial towers where landlord-tenant split incentives complicate retrofit financing and human-centric lighting specifications vary by lease class.
- Warehousing Facilities:Third-party logistics operations with shorter lease terms favoring capital-light lighting-as-a-service contracts.
- Shopping Complexes:Retail environments with high color-rendering requirements and dynamic dimming for merchandise presentation.
- Convention Centers:Multi-purpose venues with extreme lumen variability between exhibition hall and breakout room modes.
Warehouses dominate current deployment; office buildings represent the steepest expansion trajectory as hybrid work patterns force landlord efficiency investments.
End User:
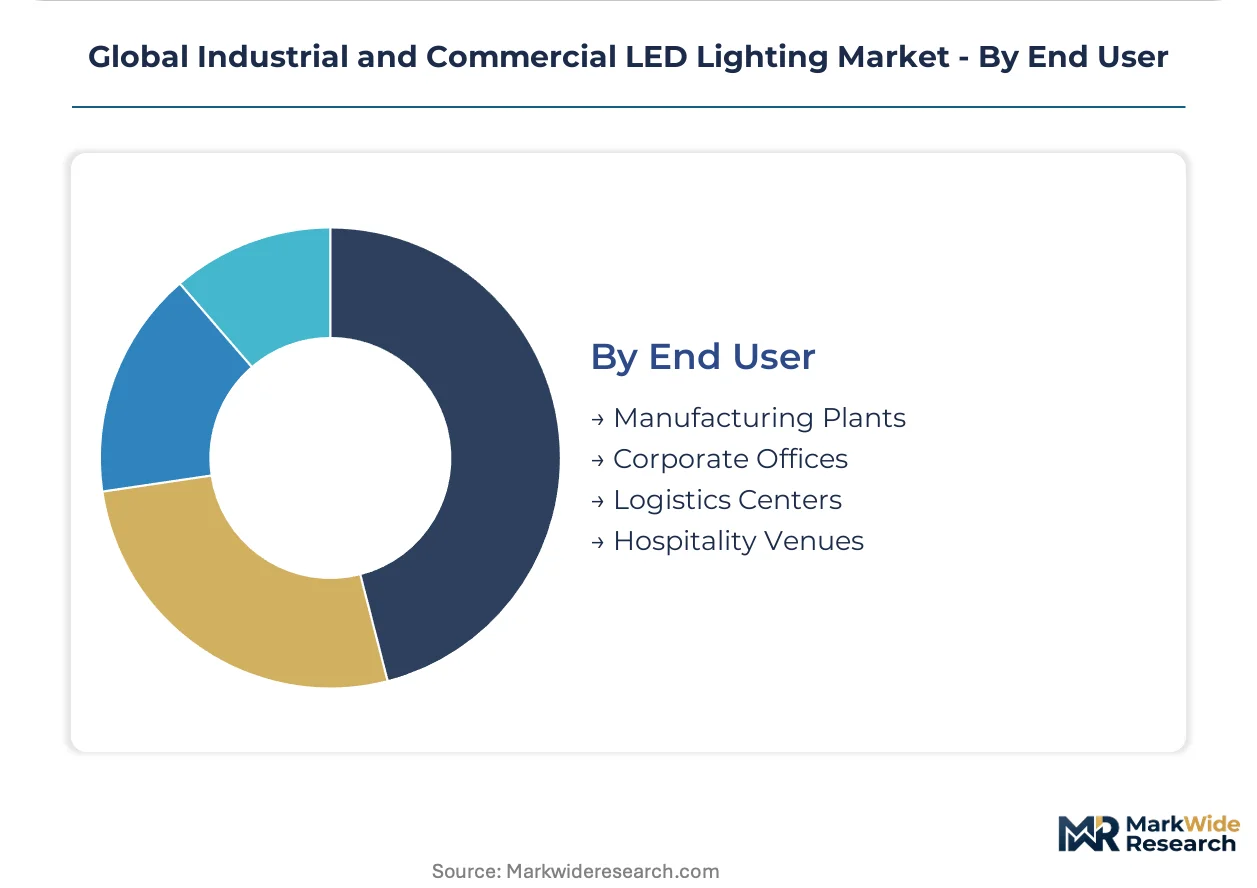
Ownership structure shapes procurement: corporate balance sheets fund efficiency upgrades while logistics operators increasingly outsource lighting infrastructure to facility-management platforms.
- Manufacturing Plants:Heavy industrial facilities with 24-hour production schedules where OSHA illumination standards and energy cost visibility drive connected lighting adoption. BASF and Siemens campuses in Ludwigshafen specify DALI-2 networked systems for granular zone control.
- Logistics Centers:E-commerce fulfillment networks where Blackstone and EQT portfolio companies bundle LED upgrades into triple-net lease efficiency guarantees.
- Corporate Offices:Single-tenant headquarters with sustainability reporting obligations favoring WELL and LEED certification pathways.
- Hospitality Venues:Hotels and conference properties where ambiance tuning and guest-room circadian lighting differentiate brand positioning.
Manufacturing Plants anchor specification-grade revenue; Logistics Centers are gaining share fastest through service-contract displacement of capital purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial LED lighting scaled through German engineering clusters in the 1990s before migrating to East Asian manufacturing centers. The current map reflects this bifurcation: European specification-grade demand against Asian volume production.
United States
California warehouse operators face Title 24 mandates and peak demand charges exceeding fifteen cents per kilowatt-hour. The Inflation Reduction Act's 179D deductions accelerate multi-site retrofit financing for logistics portfolios. Prologis facilities across the Central Valley anchor specification-grade procurement for connected high-bay arrays.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg drive demand for circadian-tunable systems and DALI-2 networked controls. The EU Green Deal's mercury-lamp phaseouts bind member states to fluorescent elimination deadlines by 2027. BASF's Ludwigshafen campus exemplifies granular zone-control deployments across chemical processing environments.
China
Guangdong and Zhejiang contract manufacturers dominate surface-mount device output for cost-sensitive commercial retrofits. GB certification requirements for solid-state lighting tighten efficacy floors ahead of IEC harmonization. Domestic suppliers face dual-track testing protocols that extend export product launch timelines.
Netherlands
Greenhouse operators in the Westland region specify chip-on-board engines for color stability under continuous horticultural operation. Ecodesign regulations under REACH constrain phosphor chemistry for European industrial buyers. Rotterdam logistics corridors concentrate lighting-as-a-service contracting within triple-net lease structures.
India
PLI scheme incentives for LED component manufacturing attract domestic assembly investment. Bureau of Energy Efficiency standards mandate minimum efficacy thresholds for commercial building retrofits. Maharashtra industrial zones around Pune and Mumbai drive warehousing facility upgrades amid electricity rate volatility.
Global Industrial and Commercial LED Lighting Market Key Industry Players
Premium-margin players sit above commodity-margin players across specification intensity and controls integration capability. The vendor base clusters around three strategic archetypes: diversified electrical conglomerates with building-automation portfolios, specialized architectural lighting houses, and Asian contract manufacturers competing on unit economics. Dominant competitive moves include M&A for controls software capabilities and geographic expansion through distributor network acquisition.
Among diversified electrical conglomerates, Signify NV and Eaton Corporation exemplify scale-driven positions spanning specification and commodity tiers. Acuity Brands anchors North American specification channels through deep distributor relationships. Zumtobel Group AG occupies a specialist position within German automotive and logistics campus applications.
| Leading Market Players |
|---|
| Osram GmbH |
| Hubbell Incorporated |
| Signify NV (Philips Lighting) |
| Siteco GmbH |
| WAC Lighting |
| Acuity Brands Inc. |
| Zumtobel Group AG |
| Eaton Corporation |
| Cree Lighting (Ideal Industries Inc.) |
| Others |
Cost & Logistics Intelligence
Specification-grade versus commodity-grade divergence in LED luminaire procurement splits the market into two distinct economic zones, with German automotive campuses paying premiums for DALI-2 networked systems while Guangdong contract manufacturers compete on sub-dollar per-kilolumen unit economics. This bifurcation feeds directly into supply chain configuration: premium tiers anchor in European phosphor chemistry and driver electronics, while volume production clusters around automated surface-mount assembly corridors in coastal China.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with differentiation driven by certification grade (UL/CE efficacy tiers) and after-sales service bundling. Cost compression in the economy tier intensifies because Guangdong OEMs automate pick-and-place assembly at scale. Logistics operators and third-party fulfillment networks exhibit highest price sensitivity, whereas German chemical processing campuses prioritize thermal reliability over first cost.
Supply Chain Analysis
Container freight rates from Shenzhen to Rotterdam directly impact landed costs for European distributors sourcing surface-mount device packages. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies on gallium nitride substrates, europium-doped phosphors, and aluminum-core PCBs. Single-source vulnerability in Chinese state-controlled rare earth refiners creates input cost volatility. Distribution runs through national electrical distributors and direct-to-facility logistics platforms serving multi-site retrofit portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between European specification premiums and Asian manufacturing scale, with the EU Green Deal's mercury-lamp phaseouts creating regulatory-driven demand clusters that offset higher Italian and German industrial electricity rates.
For Market Incumbents: Cement specification-channel control through captive distributor relationships in North America and accelerated DALI-2 software certification programs. Backward integration into gallium nitride driver design protects margin position against commoditization pressure from Guangdong contract manufacturers. Prioritize M&A targets with building-automation software stacks to defend against lighting-as-a-service displacement. For New Entrants and Emerging Players: Chip-on-board thermal management specialization offers entry into German automotive paint booth and Dutch greenhouse applications where color stability commands specification premiums. Target underpenetrated healthcare circadian-tuning deployments in Spain and Poland relative to Nordic adoption baselines. Pursue Li-Fi visible-light communication integration as a connectivity infrastructure play to bypass entrenched luminaire incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale controls software specialists possessing Bluetooth Mesh commissioning capabilities and existing hospital or logistics facility relationships. Long-term viability hinges on recurring revenue streams from lighting-as-a-service contracts displacing capital purchase models. Watch for inflection when US Inflation Reduction Act 179D deduction utilization rates cross threshold levels in multi-site commercial real estate portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Controls Software Acquisition | Integrates DALI-2 and Bluetooth Mesh capabilities into legacy luminaire portfolios for facility-management platforms. |
| Lighting-as-a-Service Contracting | Transforms capital equipment sales into recurring efficiency guarantees for Blackstone and Prologis logistics portfolios. |
| Gallium Nitride Driver Miniaturization | Shrinks power-supply footprints to enable slimmer high-bay housings reducing shipping cube and installation labor. |
| Li-Fi Communication Integration | Embeds visible-light data transmission chips into commercial panels creating building connectivity infrastructure revenue. |
| Regional Distributor Network Expansion | Deepens specification-channel presence in German automotive clusters and California Title 24 compliance corridors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facility managers at Prologis and BASF campuses, electrical distributor procurement leads, and lighting controls commissioning specialists with secondary validation against US Department of Energy efficacy standard filings, EU Ecodesign regulation databases, and China GB certification registries. Bottom-up luminaire shipment data and top-down energy retrofit spending estimates were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baseline through post-supply-shock recovery established the forecast anchor points across the projection horizon. Segmentation dimensions modeled include product architecture (high-bay, panel, floodlight), technology platform (SMD versus COB), application intensity (warehouse versus office), and ownership structure (capital purchase versus service contract). CAGRs were derived from regression analysis against industrial electricity rate spreads and regulatory mandate implementation timelines, with explicit modeling of EU Green Deal phaseout deadlines and US Inflation Reduction Act incentive uptake curves.
The model holds under stable rare earth supply conditions and continued REACH phosphor chemistry constraints; deviation in Chinese export licensing regimes or accelerated F-Gas Regulation tightening would shift replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Gan Substrate Market
LED
LED Display Control Card Market
LED
North America Indoor LED Lighting Market
LED
Mini LED Display Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Smart LED Indoor Signage Market
LED
Global LED Phosphor Market
LED
Japan LED Lighting Market
LED
Germany Outdoor LED Lighting Market
LED
North America LED Lighting Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
Biometrics Infrared LED Market
LED
North America Micro-LED Display Market
LED
Asia Pacific LED Lighting Market
LED
Global Waterproof LED Module Market
LED
LED Lamp Market