
 Light Emitting Diode (LED) Backlight Display Market | 2026-2036
Light Emitting Diode (LED) Backlight Display Market Size, Share, and Industry Trends Forecast 2026-2036
Light Emitting Diode (LED) Backlight Display Market Foresight
China's display component manufacturing corridor is narrowing the cost gap with legacy LCD supply bases. Samsung leverages captive semiconductor capacity to anchor premium direct-lit module production. LG Innotek sustains edge-lit dominance through precision optical film integration. Seoul Semiconductor differentiates via proprietary WICOP chip-scale packaging for ultra-slim form factors.
Light Emitting Diode backlight displays employ solid-state semiconductor junctions emitting photons when forward-biased, typically operating at 2-4V with luminous efficacy exceeding 100 lm/W for white phosphor-converted variants, to provide uniform illumination behind liquid crystal matrices in screens where emissive pixels remain impractical. Mini-LED architectures command the fastest expansion as local dimming zones multiply from hundreds to thousands per panel, while edge-lit configurations retain volume leadership in sub-24-inch monitors where thickness constraints dominate design priorities. Direct-lit segments concentrate margin pools in professional color-critical applications where luminance uniformity standards exceed 95% across the active area.
EPA Energy Star display specifications and EU Ecodesign requirements jointly constrain standby power and on-mode consumption, forcing module redesigns around higher-efficiency blue pump LEDs. China's SAMR enforces GB 21520 compliance for computer monitor energy efficiency, creating market access barriers for uncertified imports. Korea's MFDS medical device electromagnetic compatibility standards shape demand in diagnostic imaging panels where backlight stability affects clinical interpretation. Stakeholders must track regulatory divergence between efficiency mandates and emerging right-to-repair disclosure rules affecting modular backlight replaceability.
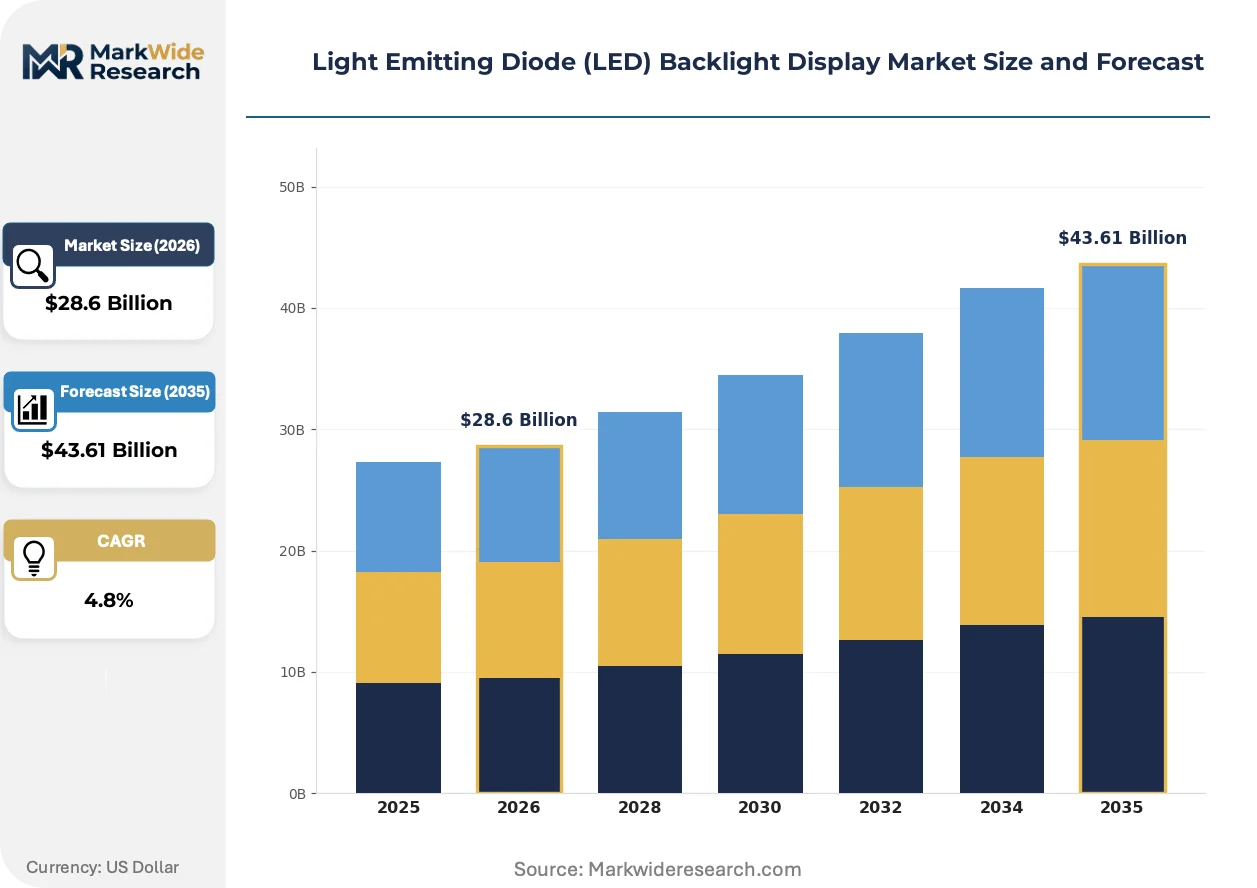
Market Dynamics
Mini-LED zone multiplication is compressing the performance gap with OLED while preserving LCD infrastructure, forcing module suppliers to reconfigure optical stacks around precision quantum dot films and denser driver IC placement.
Growth Catalysts
- Automotive Digital Cluster Mandates:OEMs in Germany, Japan, and the United States are replacing analog gauges with curved high-brightness panels, creating specification pull for local dimming architectures that operate across extreme temperature ranges.
- GB 21520 Efficiency Compliance:China's SAMR enforcement tightens certification windows for computer monitors, filtering uncertified imports and advantaging domestic module integrators with pre-approved optical designs.
- Phosphor-Converted White Efficacy Gains:Luminous efficacy exceeding 100 lm/W in blue-pump LED architectures reduces thermal management burden, enabling thinner form factors in edge-lit configurations for sub-24-inch applications.
Market Restraints
- Blue Pump LED Supply Concentration:Epitaxial wafer production clusters in East Asia create vulnerability to regional logistics disruptions, with South Korean and Taiwanese foundries controlling critical MOCVD capacity.
- Mini-LED Die Cost Structure:Chip-scale packaging yields for sub-200-micron dies remain below mature LED levels, inflating bill-of-materials for direct-lit local dimming modules targeting professional color-critical segments.
- OLED Substitution in Premium Mobile:Emissive pixel technology captures flagship smartphone and tablet backlight displacement, constraining LED module addressable market in high-ASP portable devices.
Strategic Opportunities
- Diagnostic Imaging Panel Certification:Korea's MFDS electromagnetic compatibility standards for medical devices create specialized demand for backlight stability in radiology workstations, commanding premium positioning.
- Right-to-Repair Modular Design:Emerging EU disclosure rules on component replaceability incentivize backlight unit separation from liquid crystal assemblies, opening aftermarket service revenue streams.
- Quantum Dot Film Convergence:Integration of perovskite-enhanced color conversion layers with Mini-LED architectures enables wider color gamut without cadmium content, satisfying RoHS evolution and REACH substance restrictions.
Industry Challenges
- Optical Film Lamination Precision:Maintaining luminance uniformity above 95% across active areas requires sub-micron alignment tolerances in diffuser and brightness enhancement film stacking, constraining yield at scale.
- Driver IC Thermal Co-Design:Thousands of local dimming zones per panel multiply integrated circuit density, forcing simultaneous optimization of LED junction temperature and silicon placement within slim bezels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Emitting Diode (LED) Backlight Display Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge-Lit, Direct-Lit, Ultra-Slim, Mini-LED Application: Televisions, Monitors, Laptops, Smartphones Technology: OLED, Quantum Dot, MicroLED, Liquid Crystal Display End User: Consumer Electronics, Automotive Displays, Industrial Equipment, Medical Devices |
| Companies Covered | Samsung, NICHIA, LG Innotek, Epistar, Lumileds, Seoul Semiconductor, TOYODA GOSEI, Unity Opto Technology, Genesis Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Emitting Diode (LED) Backlight Display Market Shifts & Advancements
Backlight architecture is bifurcating between ultra-slim edge-lit dominance in volume monitors and zone-dense direct-lit penetration in professional and automotive applications, with optical film innovation bridging the performance divide.
Mini-LED backlighting is hybridizing discrete die placement with traditional LCD infrastructure to deliver emissive-like contrast without abandoning existing panel investments. Automotive OEMs in Germany and Japan are qualifying thousand-zone configurations for curved instrument clusters within compressed 18-month development cycles. The technology is hybridizing supply chain relationships, requiring LED die houses to coordinate directly with optical film laminators rather than through discrete module tiers.
EPA Energy Star display specifications and EU Ecodesign requirements are jointly constraining standby power and on-mode consumption thresholds, forcing redesigns around higher-efficiency blue pump LEDs and intelligent dimming algorithms. Module suppliers must now certify across diverging test protocols, with EPA focusing on eight-hour daily use simulations and EU emphasizing annual energy consumption metrics. Professional color-critical monitors face the steepest compliance burden, as luminance uniformity standards exceed 95% while power budgets tighten.
Hospital procurement departments are consolidating display purchasing through group purchasing organizations, unbundling backlight module specifications from complete monitor supplier relationships. Original equipment manufacturers for diagnostic imaging are responding with certified subsystem sales to GPOs, bypassing traditional integrator channels. This concentration is most visible in the United States, where health system mergers have reduced the number of independent radiology department buying centers by half over the past decade.
Light Emitting Diode (LED) Backlight Display Market Segmentation
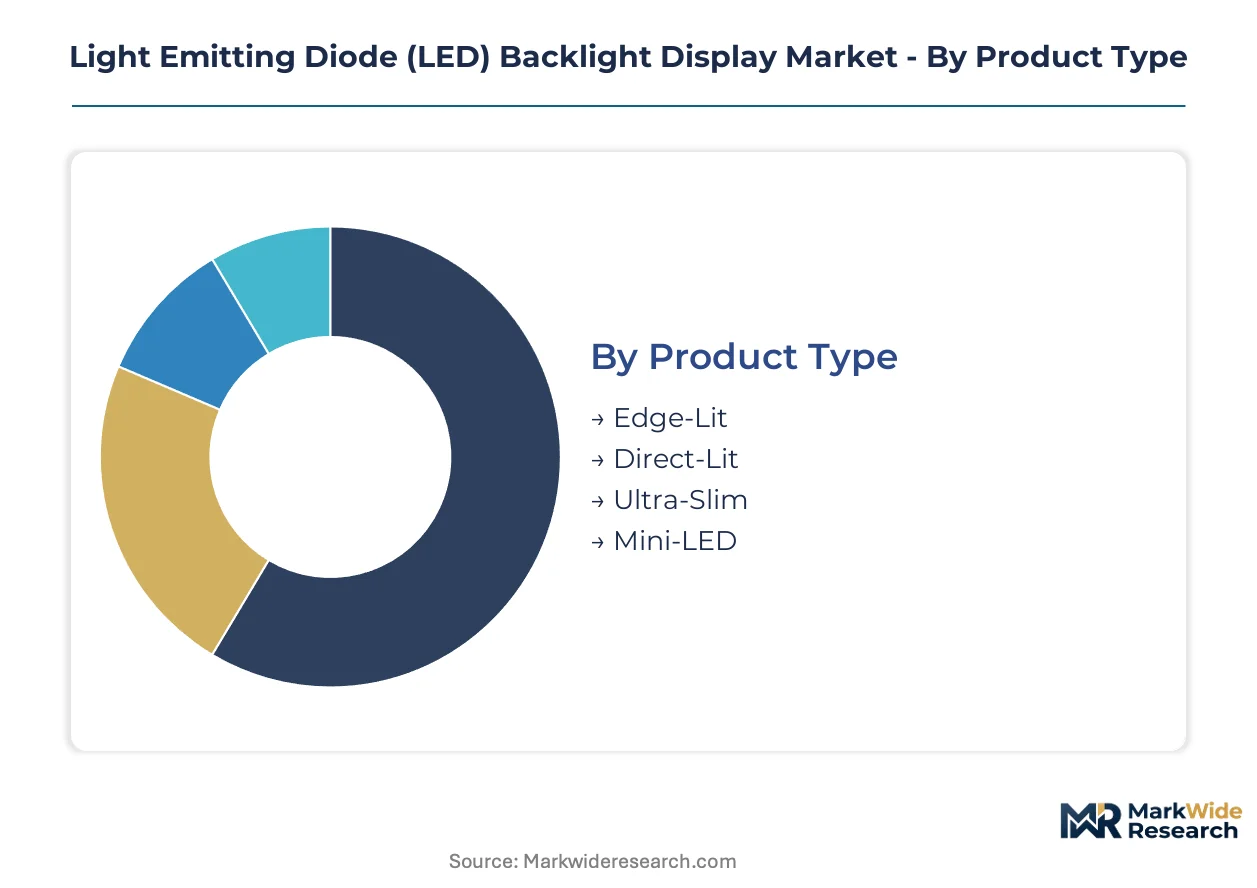
Backlight architecture selection determines thermal load, form factor constraints, and dimming precision across display categories. Module suppliers configure optical stacks differently for each segment, creating distinct margin pools and certification requirements.
Product Type:
Mature edge-lit configurations dominate volume shipments while emerging Mini-LED architectures redefine performance ceilings.
- Edge-Lit:LED arrays mounted along panel perimeters channel light through precision waveguides and diffuser films. Sub-24-inch monitors in corporate procurement favor this configuration where thickness below 8mm commands specification wins.
- Direct-Lit:Full-array LED placement behind the liquid crystal matrix enables zone-based dimming without optical distance constraints. Professional color-critical monitors for broadcast color grading require the luminance uniformity this architecture delivers.
- Ultra-Slim:Compressed optical stacks below 5mm thickness sacrifice local dimming zone count for industrial design flexibility. Premium laptop panels integrate these modules where hinge mechanics limit depth.
- Mini-LED:Chip-scale dies below 200 microns multiply dimming zones from hundreds to thousands per panel. Automotive digital clusters in Germany and Japan specify thousand-zone configurations for curved instrument displays.
Edge-Lit retains volume leadership; Mini-LED holds the steepest expansion curve.
Application:
Screen size and mobility requirements split demand between stationary large-format and portable precision segments.
- Televisions:55-inch and above panels drive direct-lit module consumption where contrast ratio specifications exceed 1,000,000:1. Living room viewing distance tolerates thicker chassis in exchange for HDR performance.
- Monitors:Desktop displays span 21 to 32 inches with professional segments demanding factory calibration to Delta E below 2.0. Corporate refresh cycles concentrate procurement in Q2 and Q4.
- Laptops:Mobile computing constraints prioritize power efficiency and weight reduction over peak brightness. Thin-bezel industrial design forces driver IC placement along panel edges.
- Smartphones:Compact form factors and OLED substitution have nearly eliminated LED backlighting except in entry-level LCD models. Remaining volume concentrates in emerging market price tiers.
Televisions anchor module revenue; monitors deliver the most stable procurement cadence.
Technology:
Emissive versus transmissive pixel architectures determine whether backlight units remain necessary or become displaced.
- OLED:Self-emissive organic compounds eliminate backlight requirements entirely, constraining LED module addressable market in premium mobile and television segments. Burn-in susceptibility preserves LCD relevance in static image applications.
- Quantum Dot:Cadmium-free perovskite films convert blue LED emission to narrow-spectrum red and green, expanding color gamut beyond phosphor-converted white. RoHS evolution and REACH substance restrictions favor this pathway.
- MicroLED:Monolithic gallium nitride microchips promise emissive performance with inorganic longevity, though transfer yield challenges delay mass production. Commercial installations in luxury retail command prototype premiums.
- Liquid Crystal Display:Transmissive pixel technology requires continuous backlight illumination, preserving LED module demand across price-accessible volume tiers. Mini-LED enhancement extends LCD competitiveness against emissive alternatives.
Liquid Crystal Display sustains installed base dominance; Quantum Dot commands the fastest technology transition.
End User:
Certification intensity and operating environment severity differentiate procurement specifications across verticals.
- Consumer Electronics:Price-sensitive volume procurement prioritizes cost-per-lumen and supply chain responsiveness. Retail channel concentration in East Asian manufacturing clusters shapes module sourcing patterns.
- Automotive Displays:OEM qualification protocols spanning -40°C to 85°C operational ranges filter module suppliers. Curved digital instrument clusters in German and Japanese vehicle programs specify thousand-zone Mini-LED architectures.
- Industrial Equipment:Extended operating lifecycles above 50,000 hours and 24/7 duty cycles demand conservative thermal design. Factory automation HMI panels favor direct-lit configurations for sunlight readability.
- Medical Devices:Korea's MFDS electromagnetic compatibility standards and FDA diagnostic imaging requirements govern backlight stability. Radiology workstations command premium positioning where luminance drift affects clinical interpretation.
Consumer Electronics generates module volume; Medical Devices extracts the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes LED backlight modules predominantly for television and monitor manufacturing, whereas automotive and medical applications concentrate in Germany, Japan, and South Korea where OEM qualification standards diverge sharply from consumer electronics procurement patterns.
China
Domestic panel manufacturers drive module demand for 55-inch and above television production, with SAMR enforcing GB 21520 energy efficiency compliance that filters uncertified imports. The Yangtze River Delta manufacturing corridor spanning Shanghai, Suzhou, and Hefei hosts precision optical film laminators serving both local and export-bound assembly operations.
South Korea
OLED substitution pressure in premium mobile segments redirects LED module investment toward automotive digital clusters and diagnostic imaging panels. MFDS electromagnetic compatibility standards for medical devices shape backlight stability requirements, with Seoul-Incheon metropolitan area foundries maintaining critical MOCVD epitaxial capacity for blue pump LED production.
Japan
Automotive OEMs in Toyota City and Nagoya specify thousand-zone Mini-LED architectures for curved instrument displays operating across -40°C to 85°C ranges. METI industrial policy supports domestic quantum dot film development, with Osaka-Kobe manufacturing clusters integrating perovskite-enhanced color conversion layers for cadmium-free RoHS compliance.
Germany
BMW, Mercedes-Benz, and Volkswagen procurement mandates for digital instrument clusters create specification pull for local dimming modules with extreme temperature resilience. KBA automotive certification protocols filter suppliers, while Bavaria and Baden-Württemberg industrial regions concentrate module integration facilities serving premium vehicle programs.
United States
Hospital procurement consolidation through group purchasing organizations unbundles backlight specifications from complete monitor supplier relationships, concentrating demand in radiology workstation applications. EPA Energy Star display specifications constrain standby power and on-mode consumption, with health system mergers reducing independent radiology department buying centers across metropolitan markets.
Light Emitting Diode (LED) Backlight Display Market Competitive Landscape
Capability concentration sits with semiconductor die houses and precision optical film specialists; scale advantage sits with diversified electronics conglomerates with captive display panel operations. The vendor base stratifies across three tiers: integrated conglomerates controlling epitaxial through module assembly, specialized LED die houses supplying external laminators, and regional optical film processors serving cost-sensitive volume tiers. Dominant competitive moves include backward integration into epitaxial wafer production and strategic partnerships between die houses and automotive tier-one module integrators.
Among East Asian semiconductor specialists, Samsung and LG Innotek exemplify the integrated conglomerate archetype with captive supply chain control from epitaxial growth through finished module assembly. Seoul Semiconductor occupies a distinct position within the specialized die house tier, differentiating through proprietary chip-scale packaging approaches for ultra-slim form factors. NICHIA represents the precision phosphor and optical materials specialist archetype, supplying conversion layers across multiple downstream module configurations without direct panel integration.
| Leading Market Players |
|---|
| Samsung |
| NICHIA |
| LG Innotek |
| Epistar |
| Lumileds |
| Seoul Semiconductor |
| TOYODA GOSEI |
| Unity Opto Technology |
| Genesis Photonics |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta manufacturing corridor spanning Shanghai, Suzhou, and Hefei concentrates precision optical film laminators and LED die packaging capacity, translating upstream MOCVD bottlenecks into asymmetric pricing power for South Korean and Taiwanese foundries serving automotive and medical display tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and tier-one module integrators, while spot purchasing persists in consumer electronics volume tiers. Three-tier pricing structure across premium, standard, and economy levels separates thousand-zone Mini-LED automotive configurations from edge-lit corporate monitors and entry-level laptop panels. Cost compression in standard-tier edge-lit modules is intensifying because Chinese domestic integrators leverage GB 21520 pre-certification to displace uncertified imports. Corporate procurement teams exhibit highest price sensitivity, whereas diagnostic imaging departments prioritize luminance stability over unit cost.
Supply Chain Analysis
Extended payment terms from automotive OEMs force module integrators to utilize supply-chain finance facilities, squeezing working capital for specialized LED die houses. Epitaxial wafer production clusters in South Korea, Taiwan, and coastal China control critical MOCVD capacity for blue pump LEDs. Gallium nitride substrates, phosphor conversion materials, and precision optical films constitute non-substitutable inputs. Single-source vulnerability in sub-200-micron Mini-LED die packaging creates qualification risk for thousand-zone automotive configurations. Distribution runs through tier-one module integrators for automotive and medical verticals, while direct OEM relationships dominate consumer electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in precision optical film lamination capability—where sub-micron alignment tolerances constrain yield at scale—creates defensive moats for incumbent laminators and entry barriers for aspirants lacking automotive qualification track records.
For Market Incumbents: Insulate margin pools in professional color-critical monitors by deepening backward integration into phosphor-converted white LED die production, countering OLED substitution pressure in premium mobile segments through Mini-LED zone multiplication investments in automotive digital clusters. Lock in automotive OEM qualification protocols spanning -40°C to 85°C operational ranges before competitor die houses achieve MFDS electromagnetic compatibility certification for diagnostic imaging panels. For New Entrants and Emerging Players: Mid-market industrial HMI panels for factory automation in Southeast Asia represent the most penetrable entry point, as established suppliers prioritize automotive and medical certification investments. Target aftermarket backlight module replacement for aging corporate monitor fleets under emerging EU right-to-repair disclosure rules. Partner with regional optical film processors to bypass captive supply chain relationships controlled by Korean and Japanese conglomerates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized LED die houses with proprietary chip-scale packaging IP and automotive qualification momentum over diversified panel manufacturers facing OLED cannibalization. Long-term viability hinges on Mini-LED cost curve convergence with OLED in television applications and sustained LCD competitiveness in automotive instrument clusters. Monitor transfer yield breakthroughs in MicroLED monolithic integration as inflection indicator for emissive display substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Fast-Track | Compressed 18-month OEM development cycles in Germany and Japan favor pre-certified module suppliers. |
| Phosphor-Converted White Efficacy Investment | Blue pump LEDs exceeding 100 lm/W reduce thermal management burden for edge-lit laptop configurations. |
| Perovskite Quantum Dot Film Integration | Cadmium-free color conversion satisfies REACH substance restrictions while expanding gamut beyond phosphor limits. |
| Right-to-Repair Modular Design | EU disclosure rules on component replaceability open aftermarket service revenue for backlight unit separation. |
| Diagnostic Imaging Panel Certification | Korea's MFDS electromagnetic compatibility standards create premium positioning for radiology workstation stability. |
Research Methodology
Cross-validation between primary interviews with LED die house technical directors, automotive tier-one module integrators, and hospital GPO procurement managers anchors the qualitative findings, supplemented by secondary analysis of SAMR GB certification databases, EPA Energy Star display specifications, and Korean MFDS medical device filings. Bottom-up triangulation across MOCVD capacity utilization reports and top-down validation against panel manufacturer procurement disclosures ensure segmentation integrity.
Calibration against historical adoption curves for Mini-LED zone multiplication and edge-lit thickness reduction anchors projections across the analysis window. Segmentation dimensions include backlight architecture, application category, display technology, and end-user vertical with regulatory intensity scoring. CAGRs derive from driver IC density trends, optical film lamination yield improvements, and automotive digital cluster mandate timelines. Quantum dot film cost curves and OLED substitution elasticities in premium mobile segments inform scenario weighting.
Practitioners should monitor MOCVD equipment lead times, GB 21520 certification queue depths, and automotive OEM thousand-zone specification adoption for early signals of supply constraint or demand acceleration. Forecasts reflect assumptions about phosphor-converted white efficacy gains, Mini-LED die packaging yield maturation, and regulatory harmonization between EU Ecodesign and EPA Energy Star protocols. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Downlight Market
LED
South America LED Lighting Market
LED
India LED Outdoor Lighting Market
LED
Outdoor LED Display Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
LED Encapsulation Market
LED
Middle East LED Lights Market
LED
Mini LED Display Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Microled Market
LED
Middle East LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
Japan Indoor LED Lighting Market
LED
LED Phosphor Materials Market
LED
LED High Bay Drivers Market
LED
Global LED Phosphor Market