
 South America LED Lighting Market | 2026-2036
South America LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
South America LED Lighting Market Insights
The EU Green Deal's extraterritorial efficiency benchmarks are restructuring import compliance expectations for South American LED manufacturers serving export-adjacent sectors. Signify Holding leverages its Philips brand infrastructure and localized assembly partnerships to anchor premium fixture distribution across Brazilian commercial channels. OSRAM Licht AG sustains chip-level supply relationships that dominate high-lumen industrial retrofits in Chilean mining operations. Cree Lighting specializes in horticultural spectrum engineering, competing for controlled-environment agricultural projects in Colombia's flower export belt.
South America LED lighting comprises solid-state electroluminescent devices utilizing gallium nitride semiconductor junctions emitting visible light at 80-150 lumens per watt efficacy, designed to replace incandescent and fluorescent sources in commercial, residential, and infrastructure illumination. The technology's primary purpose centers on reducing energy consumption and maintenance cycles in electrically constrained grid environments. Bulbs and fixtures together command the dominant revenue share, with fixtures capturing higher margin pools through integrated driver and thermal management systems. Smart Lighting technology is expanding fastest as Brazilian retail and hospitality operators deploy sensor-networked controls for demand-responsive energy management. Solar LED integration is gaining structural traction in Peru's off-grid Andean communities where centralized grid extension remains economically prohibitive.
Brazil's INMETRO certification requirements and ANEEL efficiency regulations mandate minimum luminous efficacy thresholds that filter lower-tier imports from Asian suppliers. Chile's Ministry of Energy technical standards and Peru's OSINERGMIN grid codes shape product specification sheets for cross-border procurement tenders. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and national energy ministry rulemakings when configuring regional SKU portfolios and warranty terms.
Market Dynamics
ANEEL efficiency mandates and INMETRO certification thresholds are compressing demand for legacy fluorescent systems across Brazilian commercial and infrastructure channels, forcing fixture manufacturers to reconfigure regional SKU portfolios around gallium nitride efficacy benchmarks.
Growth Catalysts
- Street Retrofit Programs:Brazilian municipalities are accelerating fixture replacements in São Paulo and Minas Gerais industrial corridors, channeling public procurement toward high-efficacy LED highway luminaires.
- EU Green Deal Benchmarks:Extraterritorial efficiency standards are restructuring import compliance expectations for South American manufacturers serving export-adjacent flower and agricultural sectors.
- Solar-LED Convergence:Off-grid Andean communities in Peru are adopting integrated photovoltaic-LED systems where centralized grid extension remains economically prohibitive.
Market Restraints
- Gallium Nitride Supply Concentration:Chip-level substrate sourcing concentrates among East Asian foundries, exposing Brazilian fixture assemblers to input cost volatility and lead time compression.
- Mercosur Regulatory Divergence:Harmonization gaps between Brazilian INMETRO rules and Chilean Ministry of Energy technical standards force manufacturers to maintain parallel certification tracks.
- Legacy Fluorescent Inventory:Existing installed bases in Argentine commercial buildings delay replacement cycles despite operational cost disadvantages.
Strategic Opportunities
- Colombian Horticultural Belt:Controlled-environment agriculture in flower export zones creates demand for spectrum-engineered LED systems optimized for photomorphogenic response.
- Smart Lighting Convergence:Sensor-networked demand-responsive controls are penetrating Brazilian retail and hospitality verticals, opening integrated energy management service contracts.
- OSINERGMIN Grid Code Alignment:Peruvian regulatory frameworks for distributed generation are creating procurement pathways for solar-LED hybrid infrastructure in rural electrification programs.
Industry Challenges
- Thermal Management Engineering Talent:Fixture manufacturers face scarcity of specialists capable of optimizing heat dissipation architectures for high-lumen mining applications in Chilean operations.
- Multi-Jurisdiction Certification Timelines:Cross-border tender compliance requires simultaneous navigation of ANEEL efficiency rules, Chilean Ministry of Energy standards, and Peruvian OSINERGMIN codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America LED Lighting Market |
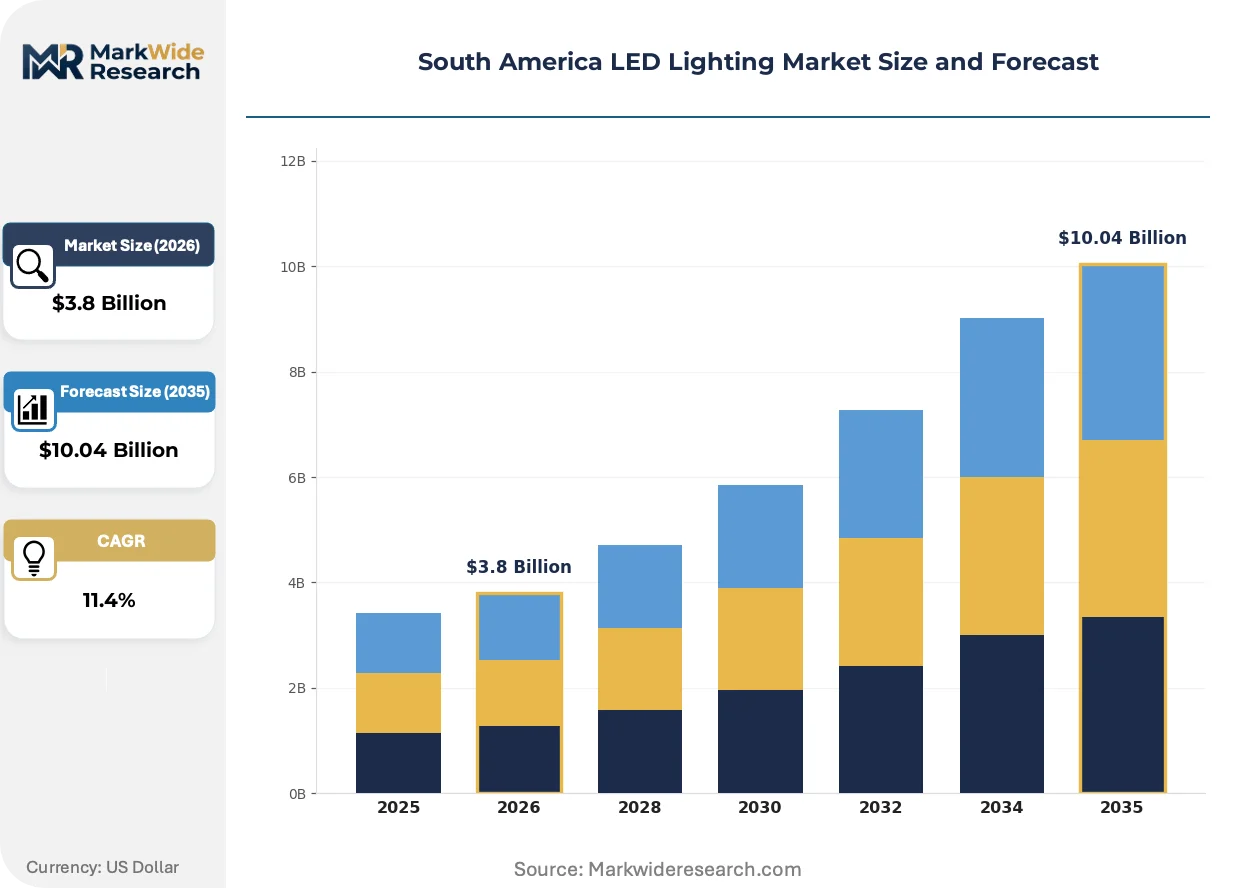
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Downlights Application: Commercial, Residential, Outdoor, Industrial Technology: Smart Lighting, Human Centric, Conventional, Solar End User: Retail, Hospitality, Manufacturing, Healthcare |
| Companies Covered | Signify Holding, OSRAM Licht AG, Acuity Brands, Cree Lighting, OPPLE Lighting, Hubbell Incorporated, Eaton Corporation, Nichia Corporation, Panasonic Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America LED Lighting Market Trends and Innovations
Human-centric lighting and circadian rhythm engineering are penetrating South American healthcare and education facilities, while integrated sensor architectures compress the boundary between illumination and building automation systems.
Chip-on-board LED modules are unifying driver electronics and thermal substrates into single-package architectures. Chilean mining operators are adopting these consolidated systems for high-bay industrial retrofits. This unification is compressing fixture assembly costs and shortening replacement cycles in mechanically stressed environments.
Chile's Ministry of Energy efficiency mandates are accelerating technical standard updates that filter legacy fluorescent imports from cross-border procurement. Industrial facilities in the Atacama mining corridor face compressed compliance timelines. High-lumen LED retrofits are capturing dominant share in tender specifications as fluorescent efficacy thresholds phase out.
Facility managers in Brazilian commercial real estate are bundling lighting upgrades with energy performance contracting rather than capital purchase. Engineering-procurement-construction firms are displacing traditional distributor channels in São Paulo's southeastern corridor. This procurement evolution concentrates vendor relationships among turnkey service providers capable of guaranteed savings verification.
South America LED Lighting Market Segmentation
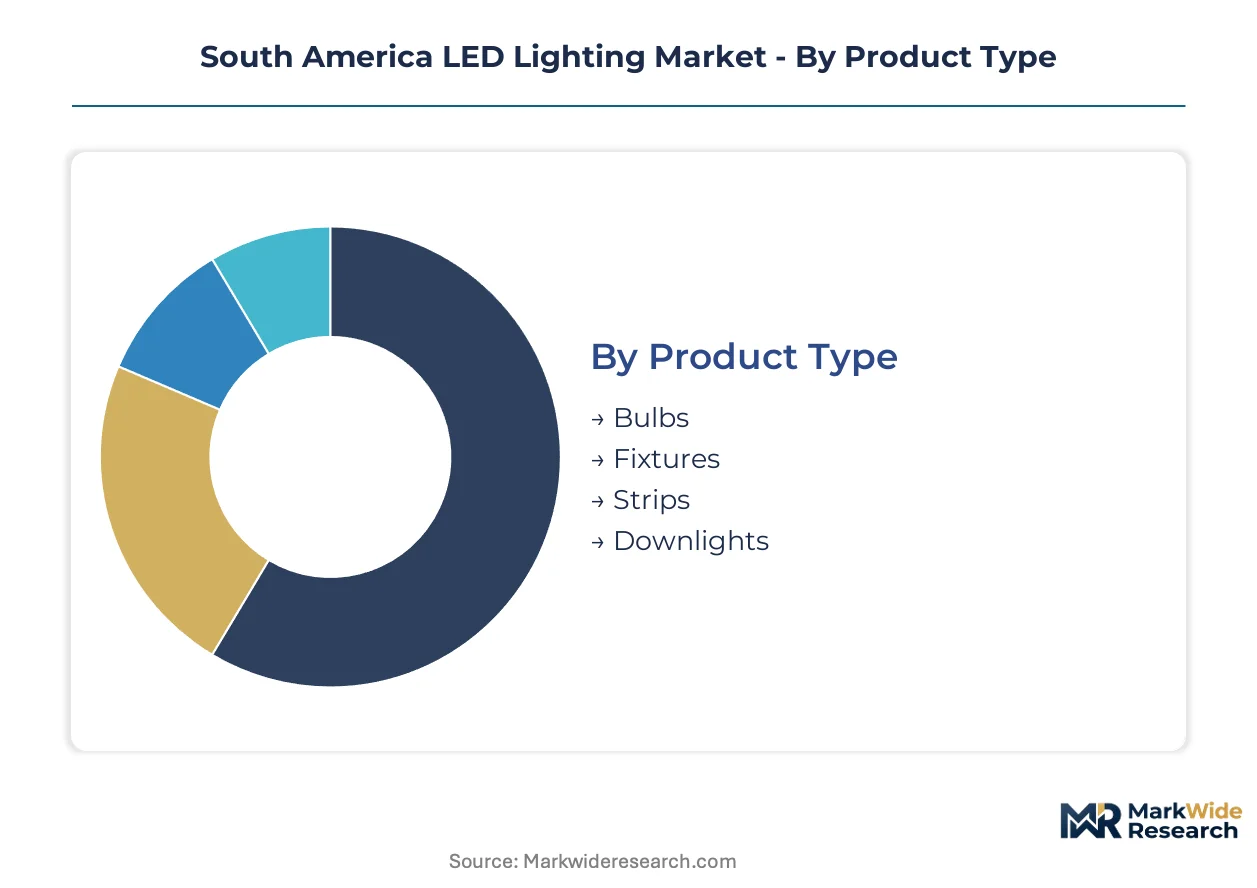
LED lighting procurement in South America fragments across four distinct decision axes: hardware form factor, installation environment, control intelligence, and sector-specific operational requirements. Each axis carries different margin profiles and certification burdens that shape vendor positioning.
Product Type:
Fixture selection hinges on thermal management sophistication and driver integration depth, not merely lumen output.
- Fixtures:Integrated luminaires with captive LED arrays, driver electronics, and heat-dissipation architectures dominate high-bay industrial and street-retrofit tenders. Brazilian municipalities in São Paulo and Minas Gerais states channel public procurement toward efficacy-certified fixtures meeting ANEEL thresholds.
- Bulbs:Retrofit lamps designed for existing Edison or bi-pin sockets capture residential replacement cycles and legacy commercial upgrades. Price compression from Asian chip sourcing concentrates margin pressure in this category, though INMETRO certification filters lower-tier imports.
- Strips:Flexible linear arrays with adhesive mounting substrates serve architectural accent and cove illumination in hospitality fit-outs.
- Downlights:Recessed ceiling luminaires with integrated trim and reflector optics target premium residential and commercial retrofit segments.
Volume sits with Bulbs; growth tilts toward Fixtures.
Application:
Installation environment dictates ingress protection ratings, thermal operating windows, and regulatory compliance tracks.
- Commercial:Office, retail, and institutional installations demanding 50,000-hour lifespans and dimming compatibility. Brazilian retail operators are bundling lighting upgrades with energy performance contracting rather than capital purchase.
- Outdoor:Street, highway, and area lighting requiring IP66+ sealing and surge protection. Chilean mining corridor operators specify high-lumen packages for 24-hour operational continuity.
- Residential:Single-family and multi-unit dwelling retrofits driven by electricity tariff sensitivity and distributor availability.
- Industrial:Manufacturing and extraction facilities with vibration tolerance and extreme temperature specifications. Thermal management engineering scarcity constrains local fixture design for Atacama mining applications.
Commercial commands current deployment scale; Outdoor is climbing the fastest on infrastructure retrofit programs.
Technology:
Control layer sophistication separates commodity hardware from value-captured energy services.
- Smart Lighting:Sensor-networked systems with occupancy detection, daylight harvesting, and centralized energy management interfaces. Brazilian retail and hospitality verticals are deploying demand-responsive controls for guaranteed savings verification.
- Solar:Photovoltaic-LED integrated systems with battery storage for off-grid operation. Peru's Andean communities adopt these where OSINERGMIN grid codes make centralized extension uneconomical.
- Human Centric:Tunable white and circadian spectrum engineering for healthcare and education facilities.
- Conventional:Fixed-output LED replacements without networked controls or spectral tuning.
Conventional retains installed base dominance; Smart Lighting exhibits the steepest expansion trajectory.
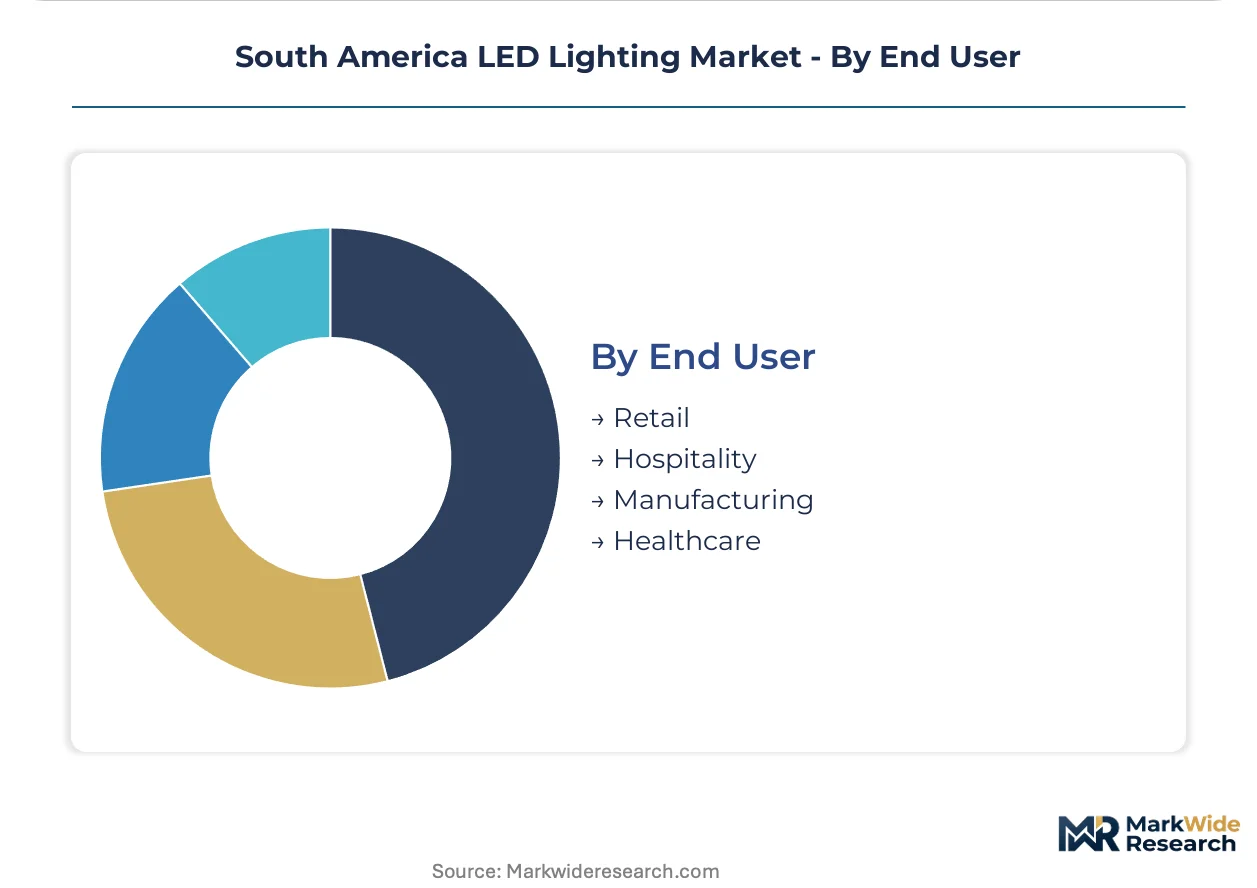
End User:
Sector-specific operational rhythms determine payback period calculations and specification stringency.
- Manufacturing:Continuous-operation facilities with high-lumen density requirements and maintenance access constraints. Chilean mining operators specify chip-on-board modules for mechanically stressed high-bay environments.
- Retail:Merchandise illumination with color rendering index priorities and hours-of-operation flexibility. São Paulo engineering-procurement-construction firms are displacing traditional distributors in this vertical.
- Hospitality:Guest experience environments balancing aesthetic control with energy accountability.
- Healthcare:Clinical and patient care settings with infection control surface requirements and circadian lighting protocols.
Manufacturing anchors industrial demand; Retail is gaining share fastest on energy service contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fixture assembly concentrates in Brazil while consumption spreads across Andean mining corridors and Atlantic commercial zones. Local manufacturers import gallium nitride substrates from East Asian foundries, exposing regional assemblers to input cost volatility. Municipal procurement programs in southeastern Brazil and Chilean mining retrofits absorb the dominant volume share.
Brazil
São Paulo and Minas Gerais industrial corridors anchor fixture demand from highway retrofit programs and commercial real estate upgrades. ANEEL efficiency regulations and INMETRO certification thresholds filter lower-tier imports from Asian suppliers. Brazilian municipalities channel public procurement toward efficacy-certified highway luminaires meeting national grid standards.
Chile
Atacama mining operators specify high-lumen LED packages for 24-hour operational continuity in mechanically stressed environments. Ministry of Energy technical standards accelerate fluorescent phase-out timelines across industrial procurement. Northern mining clusters drive chip-on-board module adoption for consolidated thermal management in high-bay retrofits.
Colombia
Flower export zones in the Bogotá savanna create specialized demand for spectrum-engineered horticultural systems. Controlled-environment agriculture operators optimize photomorphogenic response for crop timing and quality. Cundinamarca and Antioquia departments concentrate greenhouse retrofit activity around international export compliance requirements.
Peru
Andean communities above 3,000 meters elevation adopt solar-LED hybrid systems where OSINERGMIN grid codes render centralized extension uneconomical. Rural electrification programs prioritize off-grid photovoltaic integration for public lighting and small commercial loads. Cusco and Puno regions lead distributed generation procurement for isolated settlement illumination.
Argentina
Buenos Aires commercial buildings retain legacy fluorescent inventories that delay replacement cycles despite operational cost disadvantages. Existing installed bases in AMBA metropolitan zone create retrofit lag compared to regional neighbors. Mendoza wine production facilities show faster LED adoption driven by export-sector energy accountability requirements.
South America LED Lighting Market Competitive Landscape
The competitive structure tilts toward diversified multinational electronics conglomerates with localized assembly partnerships. Market concentration remains moderate as global lighting specialists compete against regional electrical distributors with captive installation channels. Three archetypes dominate: premium-brand fixture manufacturers, chip-level component suppliers, and turnkey energy service contractors. Strategic moves center on portfolio diversification into smart controls and backward integration into driver electronics.
Among diversified multinational lighting groups, Signify Holding and OSRAM Licht AG exemplify the premium-brand archetype through established distribution infrastructure. Cree Lighting occupies a position within the specialized application tier focused on spectrum-engineered systems. These three companies represent distinct competitive vectors: one anchored in commercial channel breadth, one in component supply relationships, and one in horticultural and industrial specialization.
| Leading Market Players |
|---|
| Signify Holding |
| OSRAM Licht AG |
| Acuity Brands |
| Cree Lighting |
| OPPLE Lighting |
| Hubbell Incorporated |
| Eaton Corporation |
| Nichia Corporation |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
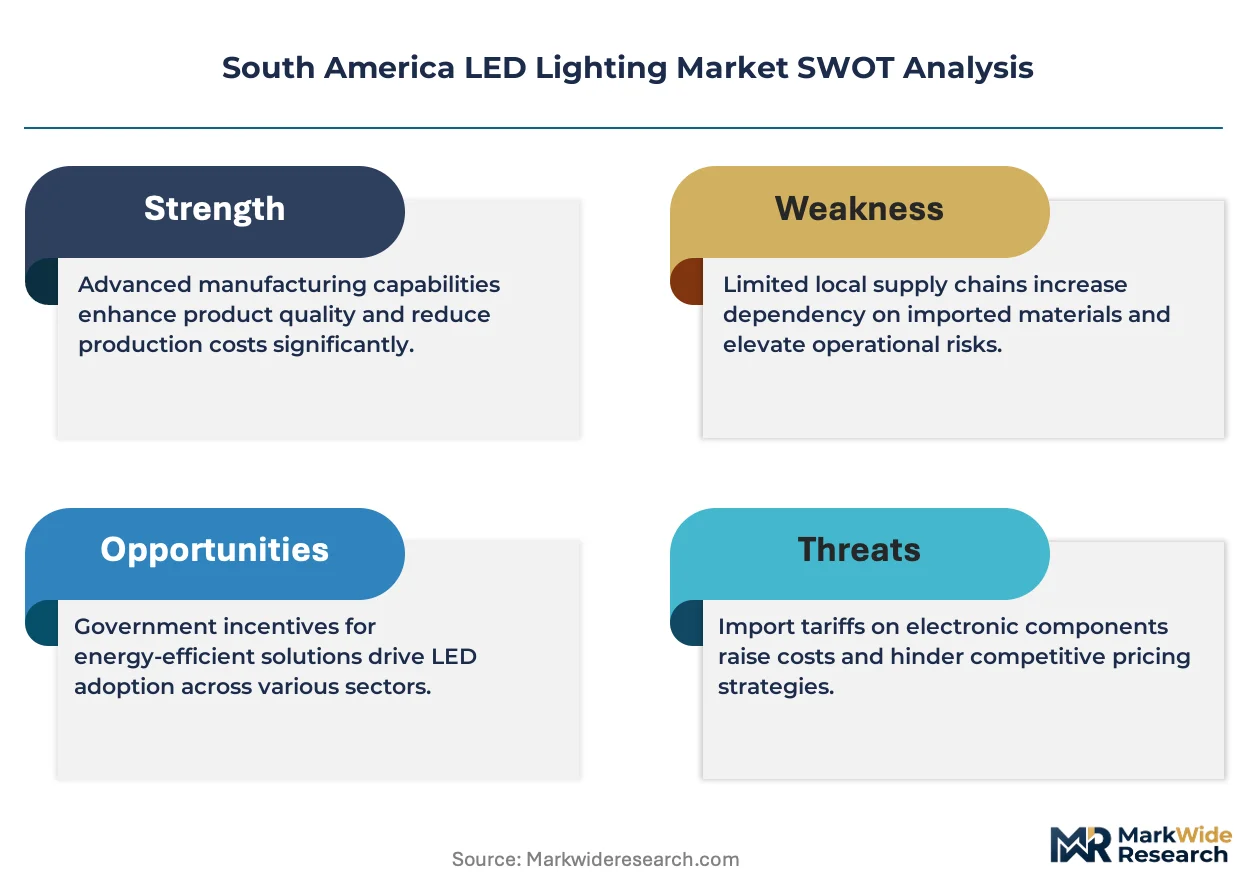
Gallium nitride substrate costs cascade from East Asian foundries through Brazilian fixture assemblers into three-tier pricing structures across premium, standard, and economy levels. ANEEL efficacy thresholds compress margins in the economy tier while certified premium fixtures capture value through integrated thermal management and driver electronics.
Pricing Analysis
Outcome-based energy savings contracts anchor value-based pricing for Brazilian commercial retrofits, with engineering-procurement-construction firms bundling guaranteed savings verification into project fees. Price differentiation hinges on INMETRO certification grade and thermal management sophistication, with premium tiers commanding substantial markups for mining-grade durability. Cost compression in the bulb category intensifies as Asian chip sourcing floods residential replacement channels with uncertified imports. Municipal procurement officers exhibit lowest price sensitivity due to lifecycle cost mandates, while residential distributors face acute margin pressure from commoditized LED lamps.
Supply Chain Analysis
Direct-to-municipality channels handle Brazilian highway retrofit demand while distributor networks serve residential replacement cycles. Taiwan, China, and South Korea concentrate gallium nitride wafer production, exposing regional assemblers to input cost volatility and lead time compression. Raw material dependencies center on sapphire substrates, rare-earth phosphors, and aluminum heat-sink extrusions. Single-source vulnerability in chip-level sourcing creates procurement risk for fixture manufacturers serving Chilean mining tenders. Distribution runs through electrical wholesalers in São Paulo's southeastern corridor and specialized mining suppliers in Antofagasta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANEEL efficiency mandates and INMETRO certification thresholds construct a cost-of-compliance barrier that favors incumbent players with established regulatory navigation capabilities and parallel certification infrastructure.
For Market Incumbents: Extend warranty-backed service contracts into energy performance guarantees for Brazilian retail and hospitality verticals, leveraging existing INMETRO relationships to exclude uncertified competitors from municipal tenders. Deepen backward integration into driver electronics manufacturing to offset gallium nitride cost volatility and compress assembly lead times for Chilean mining retrofits. For New Entrants and Emerging Players: Solar-LED hybrid systems offer a technology-first wedge into Peru's Andean off-grid communities where OSINERGMIN grid codes render centralized extension uneconomical. Target Colombian horticultural operators in Cundinamarca and Antioquia with spectrum-engineered fixtures optimized for flower export compliance, bypassing saturated Brazilian commercial channels through direct greenhouse developer relationships. For Investors and Strategic Acquirers: Brazilian EPC firm consolidation announcements are the leading indicator that turnkey energy service contracting is displacing traditional distributor channels in the southeastern industrial corridor. Acquire specialized thermal management engineering capabilities to capture high-margin mining retrofit share in Chile's Atacama corridor, monitoring Ministry of Energy standard updates as inflection signals for fluorescent replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captive supply of driver components insulates Brazilian assemblers from gallium nitride cost volatility. |
| Smart Lighting Platform Integration | Sensor-networked controls open recurring revenue streams beyond hardware margins in São Paulo retail. |
| Horticultural Spectrum Engineering Partnership | Collaboration with Colombian flower exporters aligns LED specifications with EU phytosanitary import standards. |
| Solar-LED Hybrid System Certification | OSINERGMIN alignment unlocks Peruvian rural electrification program procurement pathways. |
| Thermal Management Talent Acquisition | Specialist hiring addresses scarcity constraining high-lumen fixture design for Chilean mining applications. |
Research Methodology
Trade databases, regulatory filings from ANEEL and Chile's Ministry of Energy, and customs import records formed the secondary backbone, cross-referenced with primary interviews of fixture procurement managers at Brazilian municipalities, mining maintenance directors in Antofagasta, and greenhouse operations leads in Cundinamarca. Bottom-up and top-down triangulation validated volume estimates across product tiers.
Bottom-up modeling aggregated segment-level deployment trajectories while top-down approaches cross-checked against national energy efficiency targets and grid investment disclosures. Segmentation dimensions included fixture form factor, application environment, control technology layer, and end-user operational intensity. CAGRs derived from fitted growth curves applied to efficacy-mandated replacement timelines and solar-LED adoption patterns in off-grid zones.
Several conditions sit outside the modeled scope, including potential Mercosur regulatory harmonization failures, gallium nitride supply disruptions from East Asian foundries, and Argentine macroeconomic volatility delaying commercial retrofit cycles. Forecasts reflect assumptions about continued ANEEL enforcement intensity and Chilean mining investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Asia Pacific LED Lighting Market
LED
UK LED Lighting Market
LED
Architectural LED Products Market
LED
Indonesia LED Market
LED
LED Modules and Light Engines Market
LED
Micro LED Display Market
LED
North America Indoor LED Lighting Market
LED
UK Outdoor LED Lighting Market
LED
Infrared (IR) LED Market
LED
Vietnam LED Lighting Market
LED
LED Modular Display Market
LED
LED Display Market
LED
LED Phosphor Materials Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
LED Power Supplies Market
LED
Egypt LED Lighting Market