
 Zinc-Manganese Oxide Printed Battery Market | 2026-2036
Zinc-Manganese Oxide Printed Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc-Manganese Oxide Printed Battery Market Analytics
Multi-source procurement of zinc-manganese oxide active materials is expanding as cell makers diversify beyond traditional Japanese suppliers. Imprint Energy leverages its proprietary zinc-rechargeable chemistry to anchor flexible form-factor production in California. Panasonic Corporation sustains manufacturing scale through its legacy battery operations while navigating printed electronics partnerships. Enfucell Oy specializes in thin-cell architectures for disposable medical applications, differentiating through ISO-compliant healthcare certifications.
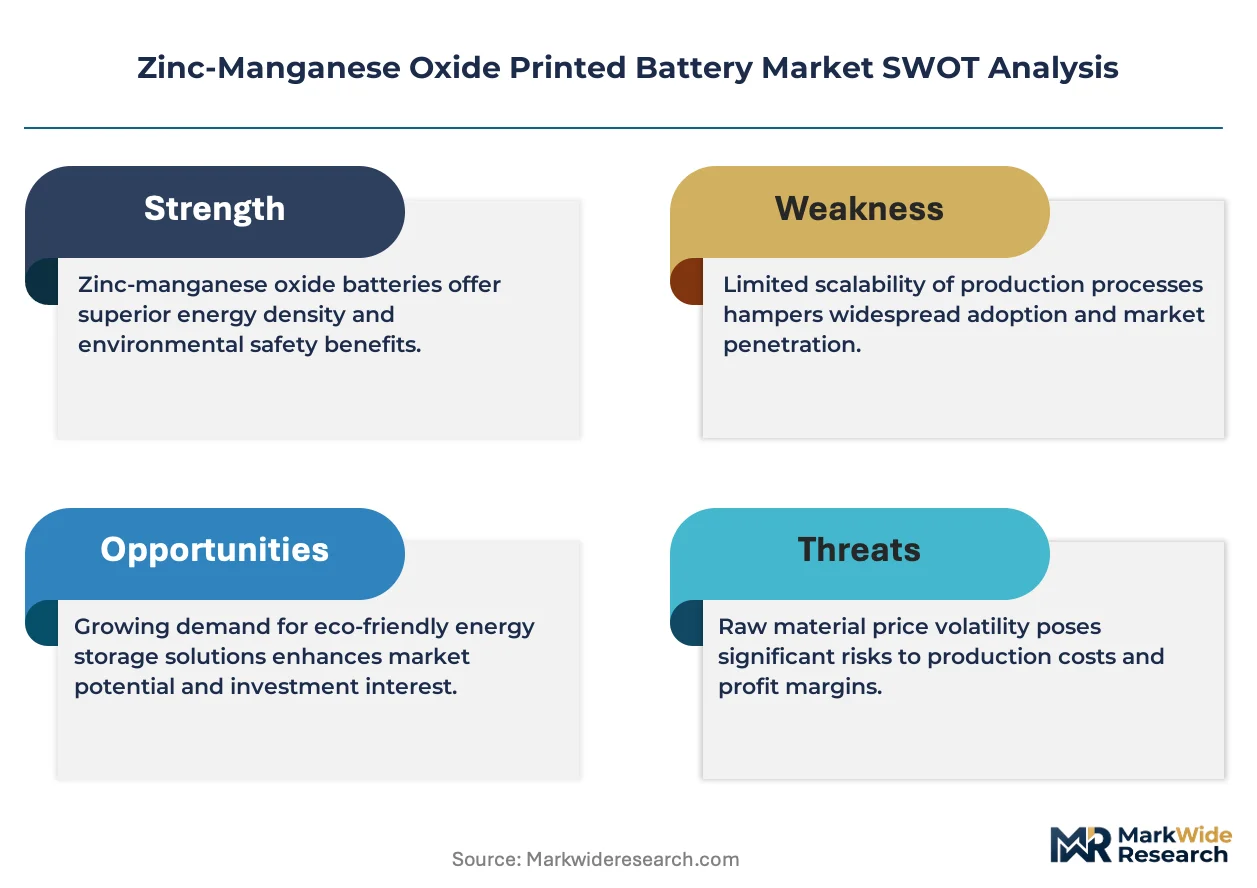
A zinc-manganese oxide printed battery consists of sequentially deposited zinc anode and manganese dioxide cathode layers on flexible polymer substrates, typically achieving 1.5V nominal output through aqueous or gel electrolyte formulations, with total thickness below 0.5mm enabling conformal integration. Its primary purpose is to power disposable and semi-permanent electronics where conventional cylindrical or pouch cells impose unacceptable bulk or assembly cost. Flexible batteries currently dominate prototype volumes due to their compatibility with roll-to-roll manufacturing, while rechargeable batteries represent the fastest-expanding category as IoT OEMs seek to eliminate replacement logistics. Medical devices command the highest margin pools among application segments, driven by sterilization-tolerant designs and regulatory-validated supply chains.
The EPA governs zinc and manganese waste streams under RCRA hazardous waste provisions, compelling domestic manufacturers to implement closed-loop electrolyte recovery systems. The EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds for portable batteries sold in member states, directly shaping cathode material sourcing strategies. ISO 13485 certification requirements from medical device regulators in Germany and the United States further constrain supplier qualification timelines. Stakeholders must monitor how forthcoming solid-state electrolyte patents intersect with existing zinc-manganese aqueous chemistries to assess technology obsolescence risk.
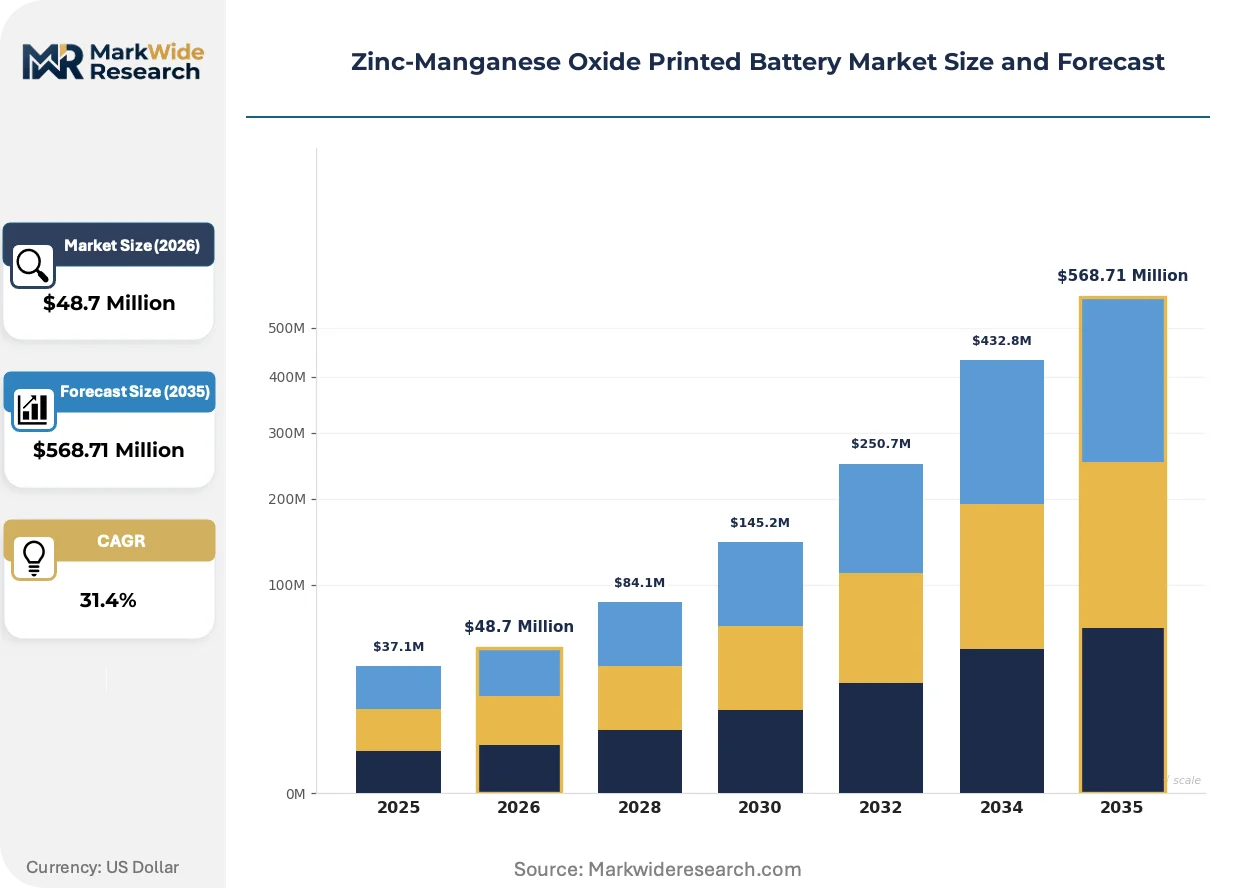
Market Dynamics
Roll-to-roll manufacturing scale-up is compressing unit economics for zinc-manganese oxide printed cells, forcing legacy batch-process suppliers to retool or exit the flexible battery segment entirely.
Growth Catalysts
- EU Battery Regulation:Carbon footprint disclosure mandates are accelerating cathode material traceability investments across European cell manufacturers.
- Wearable medical patches:Sterilization-tolerant thin-cell designs are capturing premium pricing in disposable diagnostic applications.
- Dresden-Munich corridor:Germany's printed electronics cluster is concentrating specialized substrate coating and electrolyte formulation expertise.
Market Restraints
- Zinc price volatility:Active anode material costs fluctuate with London Metal Exchange pricing and Chinese smelter output.
- Japanese supplier concentration:Manganese dioxide cathode precursors remain captive to legacy battery chemical producers in Osaka and Tokyo prefectures.
- Aqueous electrolyte freeze-thaw limitation:Gel formulations degrade below -20°C, excluding outdoor IoT deployments in Nordic climates.
Strategic Opportunities
- India BIS standards:Emerging domestic certification pathways for printed batteries open import-substitution manufacturing for medical device OEMs.
- Solid-state electrolyte convergence:Hybrid aqueous-solid architectures promise wider temperature tolerance without sacrificing flexibility.
- Direct-to-medical-device procurement:Bypassing traditional battery distributors reduces qualification friction for ISO 13485-certified cell makers.
Industry Challenges
- Roll-to-roll process engineering talent:Thin-film coating specialists command premium compensation in competing display and solar segments.
- ISO 13485 certification timelines:Medical device quality system validation extends supplier onboarding to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc-Manganese Oxide Printed Battery Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $568.71 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Batteries, Rechargeable Batteries, Flexible Batteries, Ultra-thin Batteries Application: Consumer Electronics, Wearable Devices, IoT Devices, Medical Devices End User: Retail, Manufacturing, Healthcare, Telecommunications Technology: Printed Electronics, Nano-coating, Thin-film Technology, Energy Harvesting |
| Companies Covered | EVE Energy Co., Ltd., Imprint Energy, Hitachi Maxell, Molex, LLC, Enfucell Oy, Panasonic Corporation, Blue Spark Technologies, Nexcell Battery, VARTA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc-Manganese Oxide Printed Battery Market Evolving Landscape
Electrolyte formulation advances and substrate handling automation are collapsing the cost gap between printed zinc-manganese cells and conventional coin cells in low-power applications.
Sequential screen-printed zinc anode deposition is automating layer uniformity control at speeds exceeding 50 meters per minute. Medical patch manufacturers in Germany and the United States are adopting these lines for glucose monitoring and cardiac rhythm products. The technology is automating yield improvements that previously required manual inspection stations.
REACH substance restrictions on nickel and cadmium are redirecting portable battery chemistry selection toward zinc-based aqueous systems in European consumer electronics. Manufacturers must reformulate solder pastes and contact platings to maintain CE marking compliance. The regulation most affects disposable wearable OEMs sourcing cells from Asian contract manufacturers.
Long-term service contracts with integrated battery replacement logistics are displacing spot purchasing in industrial IoT sensor networks. Facility managers now specify 5-7 year total cost of ownership rather than unit cell pricing. This shift is most visible in German smart building deployments where maintenance access costs dominate lifecycle economics.
Zinc-Manganese Oxide Printed Battery Market Segmentation
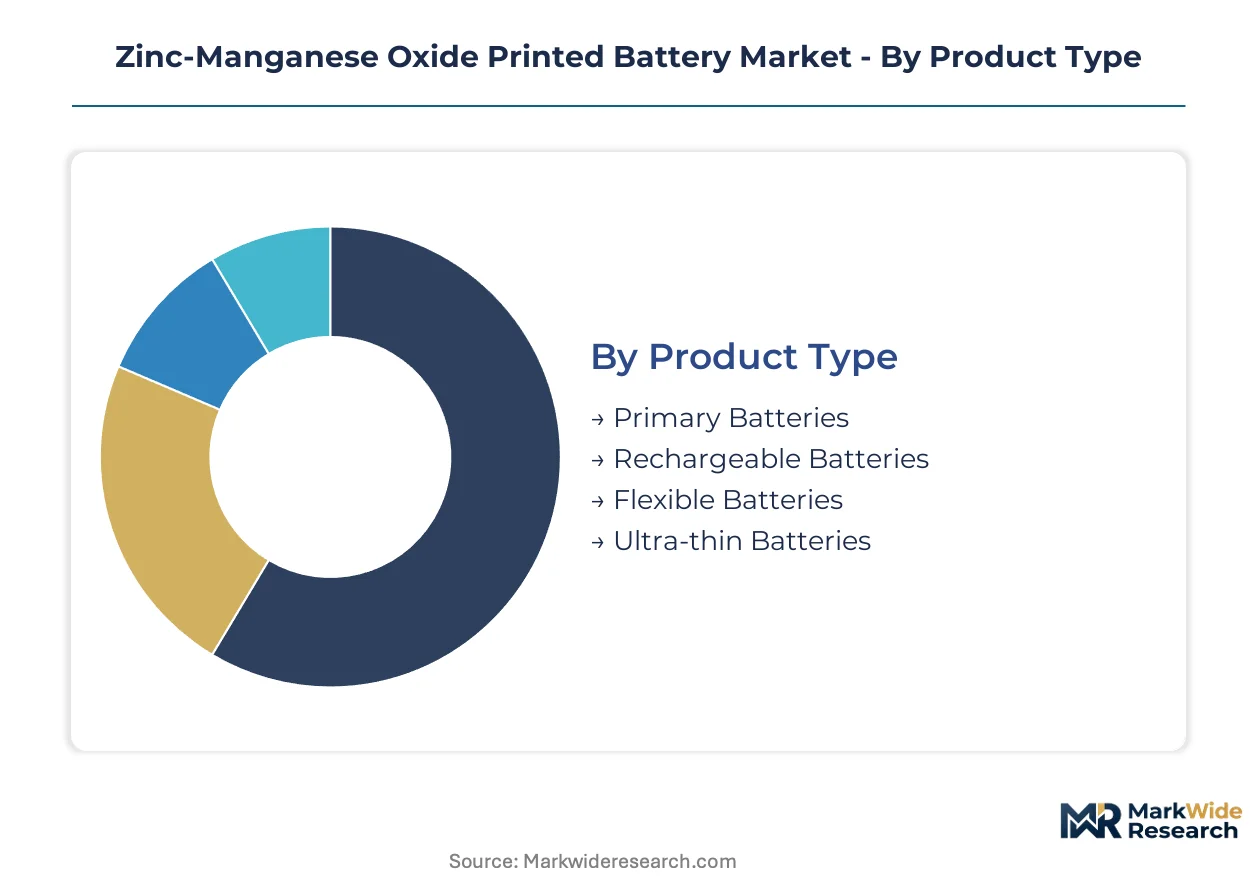
Zinc-manganese oxide printed batteries fragment across product architectures, application requirements, and manufacturing technologies. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape competitive positioning.
Product Type:
Volume concentration favors single-use formats while rechargeable architectures capture expanding replacement of disposable designs.
- Primary Batteries:Non-rechargeable zinc-manganese cells deliver 1.5V nominal output through aqueous electrolyte formulations. Demand clusters in disposable medical patches and single-use logistics sensors where battery replacement infrastructure is uneconomical.
- Rechargeable Batteries:Cyclable zinc-anode designs with proprietary electrolyte additives achieve 100+ cycles while maintaining sub-0.5mm profiles. IoT OEMs in Germany and the United States are adopting these for smart building sensors to eliminate five-year replacement logistics.
- Flexible Batteries:Polyimide or PET substrate-based cells bend to 25mm radius without capacity degradation. Roll-to-roll manufacturing lines in California and Saxony produce these for conformal wearable integration.
- Ultra-thin Batteries:Sub-0.3mm total thickness enables lamination into credit-card form factors and smart labels. Japanese and Korean consumer electronics OEMs specify these for disposable authentication devices.
Mature deployment sits with primary batteries. Newer deployment is concentrated in rechargeable batteries.
Application:
Medical and IoT segments command premium pricing against consumer electronics commodity dynamics.
- Consumer Electronics:Disposable authentication tags and promotional smart packaging drive high-volume, low-margin procurement. Asian contract manufacturers dominate sourcing through centralized purchasing.
- Wearable Devices:Skin-contact patches for glucose monitoring and cardiac rhythm tracking require ISO 10993 biocompatibility validation. German medical device OEMs pay 3-4x consumer pricing for sterilization-tolerant cell designs.
- IoT Devices:Environmental sensors and asset trackers prioritize decade-long shelf stability over cycle life. Nordic deployments exclude aqueous electrolyte formulations due to -20°C operational floors.
- Medical Devices:FDA and MDR-regulated diagnostic disposables impose 18-24 month supplier qualification timelines. Dresden-area cell makers leverage proximity to Siemens Healthineers and B. Braun for just-in-time integration.
Margin compression defines consumer electronics procurement. Steepest expansion trajectory belongs to medical devices.
End User:
Healthcare procurement patterns diverge sharply from manufacturing and retail volume purchasing.
- Retail:Big-box electronics chains and pharmacy distributors stock replacement cells for consumer wearables. Pricing transparency through e-commerce platforms compresses distributor margins to single digits.
- Manufacturing:Industrial IoT sensor OEMs specify 10-year shelf life and wide temperature tolerance. German automotive suppliers integrate printed cells into tire pressure monitors and predictive maintenance tags.
- Healthcare:Hospital procurement consortiums and home health device makers demand ISO 13485-certified supply chains. Direct-to-manufacturer contracts bypass traditional battery distributors to accelerate qualification.
- Telecommunications:5G infrastructure OEMs test printed backup power for remote microcells. Field trials in rural India and Indonesia evaluate zinc-manganese against lithium primary for tropical humidity resistance.
Healthcare procurement concentrates in long-term supply agreements. Telecommunications represents the most experimental adoption profile.
Technology:
Manufacturing process selection determines substrate compatibility and layer uniformity at speed.
- Printed Electronics:Screen and inkjet deposition of zinc anode and manganese dioxide cathode layers achieves 50+ meters per minute throughput. Dresden-Munich corridor suppliers specialize in multi-layer registration accuracy.
- Nano-coating:Atomic layer deposition of electrolyte barriers extends shelf life in high-humidity environments. Medical device OEMs specify this for tropical market registrations.
- Thin-film Technology:Vacuum-deposited active materials enable sub-100 micron total cell thickness. Korean display manufacturers repurpose OLED coating lines for battery production.
- Energy Harvesting:Hybrid architectures combine printed zinc-manganese storage with photovoltaic or RF harvesting front-ends. Building automation integrators in Germany deploy these for maintenance-free sensor networks.
Printed electronics anchors current manufacturing scale. Energy harvesting integration is gaining share fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc anode sourcing from Chinese smelters and manganese dioxide refining in Japanese prefectures anchor the supply geography. Cell manufacturing concentrates in Germany, the United States, Japan, and China. Regulatory divergence across EPA, EU Battery Regulation, and BIS standards shapes regional deployment timelines.
Germany
Wearable medical patches and IoT sensor networks drive procurement from Dresden-area cell makers. EU Battery Regulation carbon footprint disclosure mandates accelerate cathode material traceability investments. The Dresden-Munich corridor concentrates specialized substrate coating and electrolyte formulation expertise for ISO 13485-certified supply chains.
United States
Flexible battery adoption accelerates in California's printed electronics cluster and Massachusetts medical device corridors. EPA RCRA hazardous waste provisions govern zinc and manganese waste streams, compelling closed-loop electrolyte recovery systems. Imprint Energy anchors proprietary zinc-rechargeable chemistry production in California for conformal wearable integration.
Japan
Legacy battery chemical producers in Osaka and Tokyo prefectures retain captive supply of manganese dioxide cathode precursors. METI industrial standards and JIS certification requirements shape export qualification protocols. Panasonic Corporation sustains manufacturing scale through legacy operations while navigating printed electronics partnerships.
China
Domestic zinc smelter output and manganese refining capacity support cost-competitive anode material production. MIIT battery industry standards and GB certification pathways govern domestic medical device integration. Contract manufacturers in the Yangtze River Delta supply high-volume consumer electronics and authentication tag applications.
India
Import-substitution manufacturing opportunities open for medical device OEMs under emerging BIS standards for printed batteries. CDSCO medical device regulations and PLI scheme incentives attract cell production investment. Field trials in rural telecommunications infrastructure evaluate zinc-manganese against lithium primary for tropical humidity resistance.
Zinc-Manganese Oxide Printed Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as roll-to-roll manufacturing scale-up compresses unit economics. The vendor base spans legacy battery conglomerates, thin-film specialists, and printed electronics startups. Three archetypes define positioning: diversified chemical conglomerates with legacy scale, venture-backed flexible battery specialists, and ISO-certified medical cell makers. Competitive moves concentrate on strategic partnerships with medical device OEMs and technology licensing for hybrid aqueous-solid architectures.
Among Asia-Pacific-based conglomerates, EVE Energy Co., Ltd. and Hitachi Maxell exemplify diversified chemical operations with captive material supply chains. Panasonic Corporation occupies a position bridging legacy cylindrical battery scale and printed electronics partnerships. Within the medical-specialist tier, Enfucell Oy and Blue Spark Technologies represent ISO 13485-certified thin-cell architects targeting disposable diagnostic applications. Imprint Energy anchors the venture-backed flexible battery segment with proprietary zinc-rechargeable chemistry. Molex, LLC and VARTA AG sit within the component-integrated tier, leveraging connector and microbattery heritage for embedded power solutions.
| Leading Market Players |
|---|
| EVE Energy Co., Ltd. |
| Imprint Energy |
| Hitachi Maxell |
| Molex, LLC |
| Enfucell Oy |
| Panasonic Corporation |
| Blue Spark Technologies |
| Nexcell Battery |
| VARTA AG |
| Others |
Value Network & Pricing Analysis
Hospital procurement consortiums and home health device makers concentrate purchasing power for ISO 13485-certified supply chains, anchoring contract-based long-term offtake agreements that bundle five-year replacement logistics with unit cell pricing. This buyer concentration shifts negotiation leverage toward direct-to-manufacturer contracts that bypass traditional battery distributors and compress qualification friction.
Pricing Analysis
Warranty and service bundling separates premium-tier medical cell procurement from unbundled consumer electronics spot purchasing. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and sterilization-tolerant design complexity. Cost compression in consumer electronics tier runs through Asian contract manufacturer concentration and e-commerce pricing transparency. Healthcare procurement exhibits lowest price sensitivity due to regulatory validation requirements and maintenance access cost dominance.
Supply Chain Analysis
Zinc anode material supply rests on Chinese smelter output and London Metal Exchange pricing dynamics. Manganese dioxide cathode precursors draw from legacy battery chemical producers in Osaka and Tokyo prefectures. Roll-to-roll manufacturing equipment sources from German and Japanese precision coating specialists. Single-source vulnerability concentrates in Japanese cathode precursor supply. Distribution runs through medical device OEM direct procurement and industrial IoT sensor network integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roll-to-roll process engineering talent scarcity props pricing for qualified cell output, constraining capacity expansion timelines and preserving margin pools for certified manufacturers.
For Market Incumbents: Lock in cathode material supply agreements with Osaka and Tokyo prefecture producers to hedge against Japanese supplier concentration risk. Secure ISO 13485 certification maintenance through Dresden-area substrate coating partnerships. Capacity addition in California printed electronics cluster reinforces flexible form-factor positioning against emerging solid-state electrolyte substitutes. For New Entrants and Emerging Players: Capture import-substitution manufacturing opportunities under India's emerging BIS standards for printed batteries. Rural telecommunications infrastructure field trials represent most penetrable deployment channel. Direct-to-medical-device procurement relationships accelerate qualification timelines versus distributor-dependent models. For Investors and Strategic Acquirers: The window for entry favors venture-backed flexible battery specialists with proprietary zinc-rechargeable chemistry and established medical device OEM partnerships. Long-term viability hinges on hybrid aqueous-solid architecture development timelines. Solid-state electrolyte patent filings intersecting with zinc-manganese chemistries signal technology obsolescence inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Enables supplier qualification for Siemens Healthineers and B. Braun integration. |
| Backward Integration into Zinc Anode Production | Reduces London Metal Exchange price volatility exposure for California manufacturers. |
| Hybrid Aqueous-Solid Electrolyte R&D Partnership | Addresses Nordic climate deployment limitations through wider temperature tolerance. |
| Dresden-Munich Corridor Manufacturing Scale-Up | Concentrates substrate coating expertise for EU Battery Regulation carbon footprint compliance. |
| Direct-to-Medical-Device Distribution Channel | Bypasses traditional battery distributors to compress 18-24 month qualification timelines. |
Research Methodology
Independent corroboration across cell manufacturing executives, medical device procurement managers, and printed electronics equipment suppliers underwrites the qualitative findings. Primary interviews with roll-to-roll process engineers, ISO 13485 quality system auditors, and zinc anode material procurement leads combined with secondary validation from EPA RCRA filings, EU Battery Regulation disclosure databases, and SEC 10-K battery segment reports. Bottom-up cell production capacity estimates and top-down medical device OEM demand projections complete the triangulation.
Comparable historical periods across printed electronics adoption curves and thin-film battery commercialization timelines anchored the forecast window. The analytical framework segments by product architecture, application requirement, and manufacturing technology across the projection horizon. CAGRs derive from roll-to-roll throughput expansion rates and medical device OEM procurement cycle analysis. Forecast inputs include electrolyte formulation patent filing trajectories and REACH substance restriction implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state electrolyte technology maturation and zinc price volatility extremes. Forecasts reflect documented assumptions regarding EU Battery Regulation recycled content threshold enforcement and medical device regulatory validation timeline stability. A small set of triggers—including hybrid aqueous-solid architecture field trial results and India BIS standard finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
48 Volt Battery System Market
Batteries
Japan Mobile Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
VRLA Batteries Market
Batteries
East Africa Battery Market
Batteries
Battery Materials Market
Batteries
Battery Cell Market
Batteries
Portable Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Lead Acid Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Iron Salt Battery Market
Batteries
Lithium Starters Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Two Wheeler Lead Acid Batteries Market