
 Tubular GEL Battery Market | 2026-2036
Tubular GEL Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Tubular GEL Battery Market Intelligence
Modular battery rack configurations is expanding as the dominant procurement format for large-scale buyers, replacing standalone unit purchases with stackable, capacity-scalable systems. Exide Technologies leverages its European manufacturing footprint to anchor supply contracts with telecom infrastructure operators. EnerSys competes through deep specialization in motive power and reserve power gel architectures. Sacred Sun Power Sources dominates procurement tenders across China's state-backed renewable storage programs.
A tubular GEL battery employs positive plates cast with vertical lead-alloy spines surrounded by active material, immobilized electrolyte in silica-thickened gel form, and a vented or valve-regulated recombination design; this construction tolerates deep cycling, elevated temperatures, and prolonged standby duty without electrolyte stratification. Tubular Gel product types sustain premium pricing in heavy-cycling applications where flat plate alternatives degrade faster. Renewable Energy applications are recording the fastest structural expansion as solar-plus-storage deployments displace diesel backup across off-grid and weak-grid installations. Data Centers represent the most concentrated margin pool among end users, driven by uptime guarantees and long-duration discharge requirements.
ISO 9001 quality frameworks and IEC 60896-21 stationary battery standards govern product certification and cross-border market access, while India's BIS certification mandates local testing for imported units. The EU Battery Regulation and REACH chemical compliance are reshaping material sourcing and end-of-life recycling obligations for manufacturers serving European demand. Stakeholders must monitor how carbon-border adjustment mechanisms and national energy storage procurement rules alter competitive access across priority supply corridors.
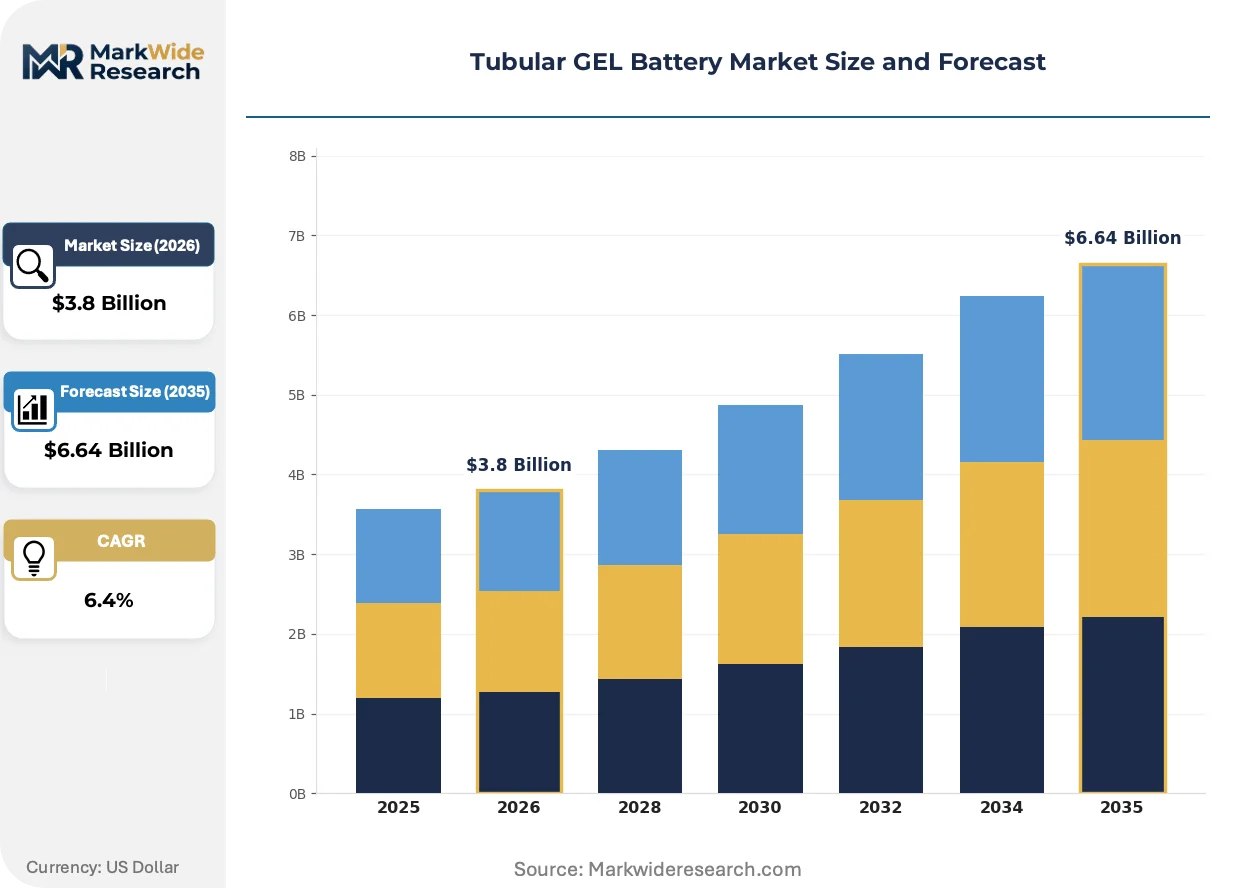
Market Dynamics
Grid reliability volatility across emerging economies is compressing replacement cycles for tubular GEL batteries while forcing procurement toward modular, scalable architectures that tolerate deep cycling and elevated ambient temperatures without electrolyte maintenance.
Growth Catalysts
- EU F-Gas Regulation:The regulation's phase-down of hydrofluorocarbon refrigerants and auxiliary cooling systems accelerates sealed gel adoption over vented lead-acid in stationary backup applications across European telecom infrastructure.
- Telecom infrastructure expansion:Operators in India and Southeast Asia are standardizing tubular GEL configurations for tower backup as grid instability forces longer discharge durations and reduced maintenance windows.
- Solar-plus-storage displacement:Off-grid and weak-grid installations are substituting diesel generator sets with tubular GEL banks integrated behind solar inverters, creating procurement pull in rural electrification programs.
Market Restraints
- Lead price volatility:Primary lead smelter output constraints and secondary lead scrap availability fluctuations compress manufacturing margins and destabilize long-term contract pricing for battery assemblers.
- Lithium-ion substitution pressure:Declining lithium iron phosphate pack costs threaten tubular GEL positioning in cycling-intensive applications where weight and energy density penalties matter less than capital expenditure minimization.
- Recycling infrastructure gaps:Inadequate spent battery collection networks and lead-acid processing capacity in sub-Saharan Africa and parts of Southeast Asia create compliance liabilities and limit market entry.
Strategic Opportunities
- India commercial and industrial procurement:Frequent power outages and renewable integration mandates in Maharashtra, Gujarat, and Tamil Nadu create consistent tender volumes for industrial-scale tubular GEL installations.
- Data center uptime guarantees:Long-duration discharge requirements and thermal tolerance specifications favor tubular GEL chemistry over valve-regulated lead-acid flat plate alternatives in hyperscale facility specifications.
- Modular rack standardization:Stackable capacity-scalable systems are replacing standalone unit purchases, enabling vendors to capture recurring expansion revenue from existing installed bases rather than one-time replacement sales.
Industry Challenges
- IEC 60896-21 certification timelines:Extended type-testing durations and laboratory capacity constraints delay product launches and tender eligibility for manufacturers introducing new capacity variants.
- Silica gel formulation expertise:The specialized knowledge required for electrolyte immobilization consistency and recombination efficiency optimization remains concentrated among a narrow technical workforce, constraining production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubular GEL Battery Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubular Gel, Flat Plate Gel, Spiral Gel, Recombinant Gel Application: Telecommunication Systems, Renewable Energy, UPS Systems, Electric Vehicles, Emergency Lighting End User: Data Centers, Residential Buildings, Commercial Complexes, Industrial Plants Distribution Channel: Direct Sales, Distributors, Online Retailers, Authorized Dealers |
| Companies Covered | Exide Technologies, EnerSys, Vision Battery, Sacred Sun Power Sources, FIAMM Energy Technology, Hoppecke Batteries, Leoch Battery, East Penn Manufacturing, Wolong Electric Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubular GEL Battery Market Strategic Shifts & Innovations
Battery system architecture is fragmenting from monolithic blocks toward configurable subunits, while regulatory chemistry restrictions and buyer procurement rationalization simultaneously reshape competitive positioning across end-use verticals.
Containerized and rack-mounted tubular GEL assemblies are modularizing from fixed-capacity units into scalable building blocks that data center operators and telecom infrastructure managers can expand without full system replacement. Hyperscale facility engineers in India and Southeast Asia are specifying these configurations to match backup duration requirements to actual load profiles rather than oversizing for theoretical peaks. This architecture is modularizing competitive dynamics by lowering switching costs between suppliers and compressing the value capture of proprietary form factors.
REACH chemical compliance and the EU Battery Regulation's end-of-life recycling obligations are forcing material sourcing audits and closed-loop recovery partnerships for manufacturers serving European demand. The regulations mandate carbon footprint disclosure and recycled content thresholds that reshape supply chain geography toward regional lead smelter networks. Tubular GEL product lines with established European recycling infrastructure are capturing preferential placement in utility-scale storage tenders subject to sustainability scoring.
Telecom tower operators are consolidating supplier relationships around integrated power system vendors who bundle battery procurement with rectifier, inverter, and remote monitoring services. This bundling displaces standalone battery purchasing and compresses pure-play manufacturer margins in markets where tower companies have achieved operational scale. The shift is most visible in India's infrastructure sharing arrangements, where Indus Towers and American Tower Corporation affiliates specify turnkey energy solutions rather than component-level tenders.
Tubular GEL Battery Market Segmentation
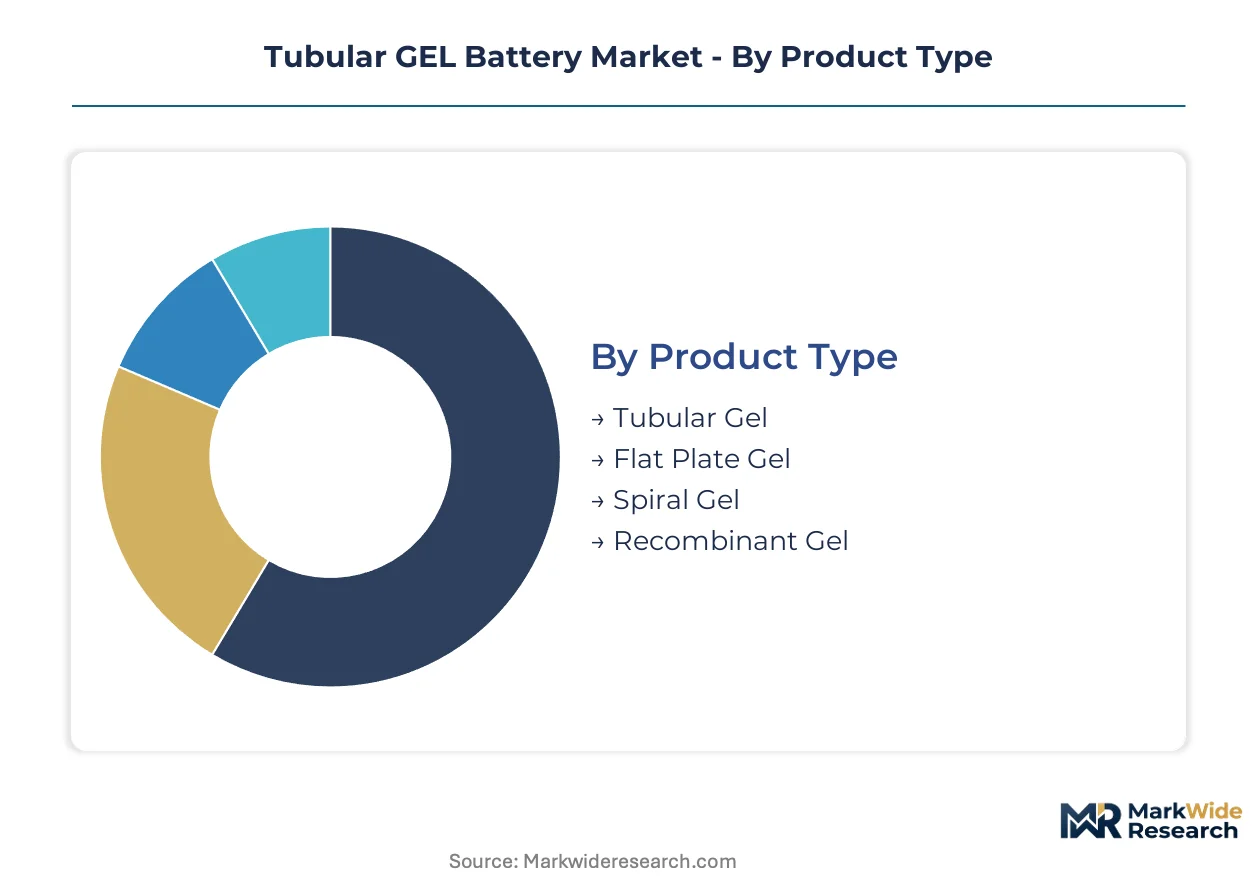
Tubular GEL battery procurement patterns diverge sharply across product architectures, with upgrade cycles and replacement timelines varying by application intensity and thermal exposure. Understanding these segment boundaries clarifies where manufacturers capture recurring revenue versus one-time installation sales.
Product Type:
Replacement cycle economics favor architectures that tolerate deep discharge without electrolyte stratification, driving procurement toward tubular designs in cycling-intensive installations.
- Tubular Gel:Vertical lead-alloy spines surrounded by active material and immobilized silica-thickened electrolyte deliver superior deep-cycling tolerance and thermal stability. Telecom tower operators in India standardize this configuration for discharge durations exceeding eight hours in weak-grid zones.
- Flat Plate Gel:Horizontal plate construction with gel electrolyte offers lower upfront capital cost but shortened service life under partial state-of-charge operation. Residential UPS installations in Maharashtra and Gujarat specify flat plate variants for cost-sensitive backup applications with infrequent cycling.
- Spiral Gel:Wound electrode design optimized for high-rate discharge in compact footprints.
- Recombinant Gel:Valve-regulated gas recombination eliminates watering maintenance in sealed enclosures.
Tubular Gel sits at the top of the volume ranking, with Spiral Gel climbing the fastest in motive power niches requiring vibration resistance.
Application:
Capital deployment intensity varies by duty cycle requirements, with continuous-float applications demanding different performance guarantees than daily-cycling installations.
- Telecommunication Systems:Tower backup power mandates 48Vdc configurations with 10-20 year design life under elevated ambient temperatures. Indus Towers and American Tower Corporation affiliates in India consolidate procurement around integrated power systems bundling tubular GEL banks with rectifiers and remote monitoring.
- Renewable Energy:Solar-plus-storage displacement of diesel generators creates procurement pull in rural electrification programs across Southeast Asia. Weak-grid installations specify tubular GEL chemistry for daily cycling tolerance behind solar inverters without active thermal management.
- UPS Systems:Uninterruptible power supply for critical infrastructure requiring instantaneous transfer capability.
- Electric Vehicles:Low-speed electric mobility and industrial motive power applications with weight-tolerant battery compartments.
- Emergency Lighting:Standby illumination systems with annual test-discharge duty cycles.
Telecommunication Systems commands the largest installed base, while Renewable Energy gains share fastest as solar penetration accelerates across off-grid territories.
End User:
Facility uptime guarantees and thermal envelope constraints reshape procurement specifications across building types and industrial process requirements.
- Data Centers:Hyperscale facilities in India specify long-duration discharge configurations with 15-minute to 4-hour backup windows. Tubular GEL chemistry captures preference over flat plate alternatives for thermal tolerance in non-climate-controlled battery rooms.
- Industrial Plants:Manufacturing facilities in Tamil Nadu and Gujarat require modular rack configurations scalable to process-critical load profiles. Frequent grid instability forces procurement toward deep-cycling architectures with reduced maintenance windows.
- Residential Buildings:Individual household backup systems with intermittent duty cycles.
- Commercial Complexes:Multi-tenant facilities with shared infrastructure and standardized maintenance protocols.
Data Centers represents the most concentrated margin pool, with Industrial Plants expanding most quickly on renewable integration mandates.
Distribution Channel:
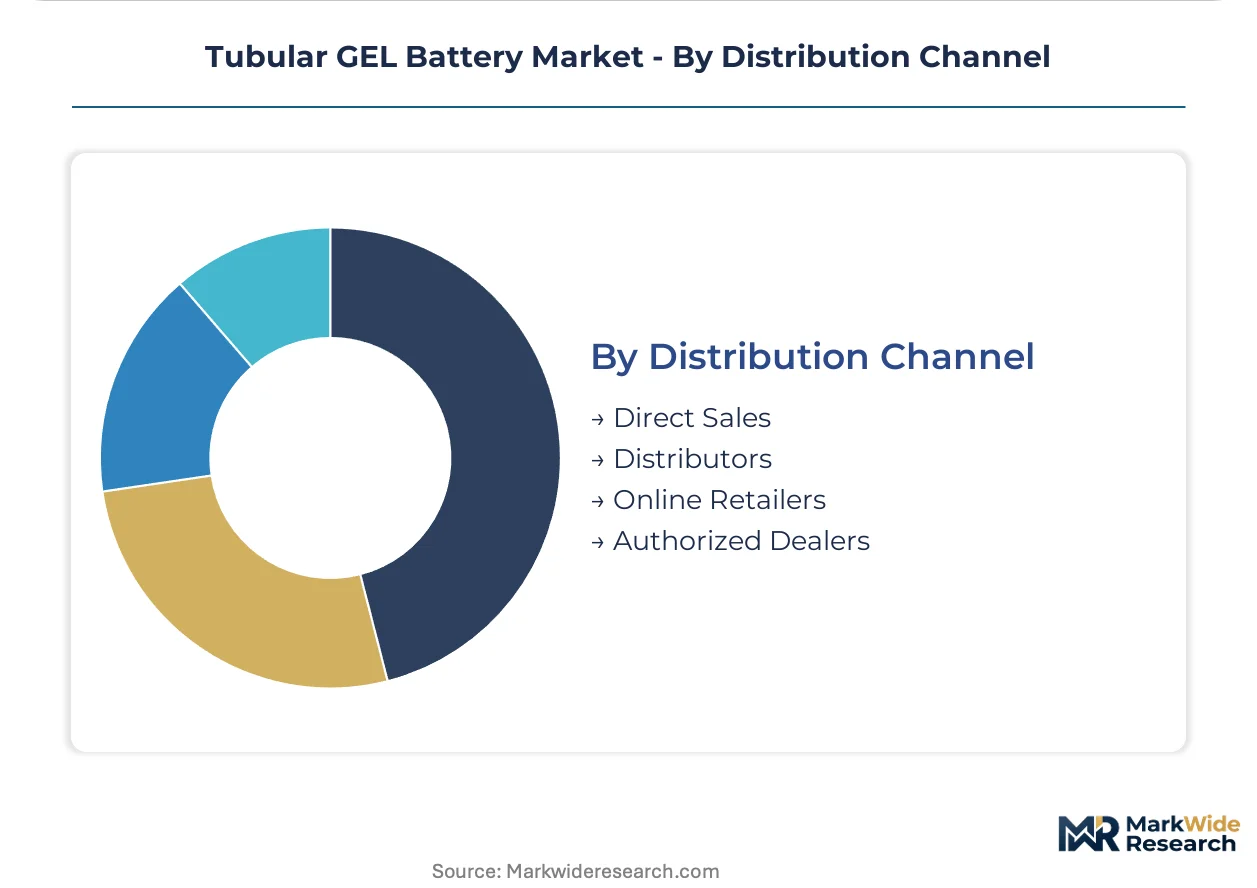
Channel selection reflects buyer scale and technical specification complexity, with large tenders bypassing intermediaries while fragmented demand flows through dealer networks.
- Direct Sales:Manufacturer-direct contracting for utility-scale storage tenders and telecom infrastructure operators. Exide Technologies anchors European supply relationships through direct engagement with tower companies.
- Distributors:Regional inventory and logistics intermediaries serving mid-scale commercial and industrial procurement.
- Authorized Dealers:Certified installation and service networks required for warranty validation in India BIS-compliant sales.
- Online Retailers:E-commerce platforms capturing replacement battery sales for residential UPS and small commercial applications.
Direct Sales dominates value capture in institutional tenders, with Authorized Dealers expanding fastest on certification complexity in regulated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tubular GEL battery manufacturing originated in European industrial centers during the 1980s, with German and Italian engineering firms pioneering the silica-thickened electrolyte immobilization techniques that enabled deep-cycling tolerance. Production subsequently dispersed to Asia-Pacific manufacturing clusters as telecom infrastructure deployment accelerated across emerging economies.
India
Telecom tower operators Indus Towers and American Tower Corporation affiliates standardize tubular GEL configurations for 48Vdc backup systems exceeding eight-hour discharge durations. The Bureau of Indian Standards mandates local testing certification for imported battery units under BIS 16046 specifications. Manufacturing concentrates in Maharashtra and Gujarat industrial corridors where grid instability forces procurement toward maintenance-free deep-cycling architectures.
Germany
Stationary backup applications across European telecom infrastructure accelerate sealed gel adoption as the EU F-Gas Regulation phases down hydrofluorocarbon-dependent cooling systems. REACH chemical compliance and the EU Battery Regulation's recycled content thresholds reshape material sourcing toward regional lead smelter networks. Industrial battery production clusters in North Rhine-Westphalia and Baden-Württemberg anchor supply contracts with hyperscale data center operators.
China
State-backed renewable storage programs drive procurement pull for tubular GEL banks integrated behind solar inverters across rural electrification initiatives. The Ministry of Industry and Information Technology enforces GB/T standards for stationary battery safety and performance validation. Manufacturing gravity centers on Shandong Peninsula and Yangtze River Delta regions where vertical integration into lead smelting and battery assembly compresses production costs.
United States
Data center uptime guarantees favor tubular GEL chemistry for thermal tolerance in non-climate-controlled battery rooms with 15-minute to 4-hour backup windows. EPA hazardous waste regulations and state-level renewable portfolio standards influence procurement specifications for stationary energy storage. Hyperscale facility construction concentrates in Northern Virginia and Dallas-Fort Worth metroplexes where modular rack configurations enable capacity scaling without full system replacement.
Brazil
Weak-grid installations across Northeast and Amazon regions substitute diesel generator sets with solar-plus-storage configurations specifying tubular GEL daily cycling tolerance. ANVISA and national environmental agencies enforce lead-acid battery collection and recycling obligations for imported units. Distributed generation programs in Minas Gerais and São Paulo industrial zones create tender volumes for off-grid commercial and industrial backup systems.
Tubular GEL Battery Market Key Industry Players
The competitive structure tilts toward integrated power system vendors bundling battery procurement with rectifier, inverter, and remote monitoring services. Tier-one manufacturers with European recycling infrastructure capture preferential placement in utility-scale tenders subject to sustainability scoring. Three archetypes dominate: legacy lead-acid specialists with silica gel formulation expertise, diversified industrial conglomerates with captive lead smelting capacity, and telecom-integrated energy solution providers. Dominant competitive moves include vertical integration into secondary lead recovery networks and technology licensing partnerships for recombination efficiency optimization.
Among European-headquartered specialists, Exide Technologies and EnerSys occupy positions anchoring supply relationships with telecom infrastructure operators. Sacred Sun Power Sources exemplifies the state-backed renewable storage archetype serving China's utility-scale procurement programs. These three companies represent distinct competitive vectors: European regulatory compliance leadership, deep specialization in motive and reserve power architectures, and integration with national renewable energy mandates respectively.
| Leading Market Players |
|---|
| Exide Technologies |
| EnerSys |
| Vision Battery |
| Sacred Sun Power Sources |
| FIAMM Energy Technology |
| Hoppecke Batteries |
| Leoch Battery |
| East Penn Manufacturing |
| Wolong Electric Group |
| Others |
Cost & Logistics Intelligence
Lead ingot pricing volatility cascades through tubular GEL battery manufacturing, compressing margins for assemblers without captive smelting while amplifying price premiums for certified suppliers serving European telecom and data center procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 60896-21 certification status and gel formulation consistency. Premium tiers command sustained margins from data center operators in Northern Virginia and Maharashtra hyperscale facilities where thermal tolerance guarantees outweigh capital expenditure sensitivity. Cost compression in economy-tier flat plate variants intensifies as lithium iron phosphate substitution pressure mounts for cycling-intensive applications. Telecom tower operators in India exhibit acute price sensitivity in standalone battery tenders, while bundled power system procurement masks component-level pricing transparency.
Supply Chain Analysis
Freight cost escalation from Shandong Peninsula and Yangtze River Delta manufacturing clusters to Southeast Asian installation sites is reshaping regional sourcing strategies for European and Brazilian distributors. Supply concentrates in China, India, and Germany, with lead smelter proximity determining competitive access to secondary raw material streams. Raw material dependencies center on primary lead ingots, silica fume for electrolyte immobilization, and ABS resin for cell enclosures. Single-source vulnerability in high-purity silica gel formulations constrains production scaling for emerging manufacturers. Distribution runs through authorized dealer networks in India BIS-regulated markets and direct sales channels for European utility-scale tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tubular GEL battery market functions as a geographic-arbitrage play between European regulatory premium capture and Asian manufacturing cost compression, with carbon-border adjustment mechanisms widening the spread.
For Market Incumbents: Extend certification coverage into India's BIS 16046 compliance framework before local testing mandates harden import barriers. Deepen backward integration into secondary lead recovery networks to offset primary smelter output constraints. Counter lithium iron phosphate substitution threat by emphasizing thermal tolerance specifications in data center uptime guarantee contracts. For New Entrants and Emerging Players: E-commerce platform routes into residential UPS replacement markets in Maharashtra and Gujarat bypass entrenched dealer networks and certification complexity. Target flat plate gel white space in cost-sensitive commercial backup applications where eight-hour discharge durations remain rare. Pursue technology licensing partnerships for recombination efficiency optimization rather than building silica formulation expertise in-house. For Investors and Strategic Acquirers: Consolidation pressure builds where recycling infrastructure gaps in sub-Saharan Africa and Southeast Asia create compliance liabilities for pure-play manufacturers without closed-loop recovery partnerships. Long-term viability hinges on positioning against lithium-ion cost curves in cycling-intensive niches while capturing regulatory-driven premium tiers in European stationary backup. Monitor EU Battery Regulation recycled content threshold enforcement as inflection signal for supply chain geography reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Lead Recovery | Captures margin compression protection against primary smelter output constraints affecting Exide Technologies and EnerSys. |
| Modular Rack Configuration Standardization | Enables recurring expansion revenue from Indus Towers and American Tower Corporation installed bases. |
| EU Battery Regulation Compliance Certification | Unlocks preferential placement in utility-scale tenders subject to sustainability scoring across Germany and Netherlands. |
| Silica Gel Formulation Technology Licensing | Accelerates production scaling for entrants lacking concentrated technical workforce expertise in electrolyte immobilization. |
| Integrated Power System Bundling | Displaces standalone battery purchasing in India's tower infrastructure sharing arrangements. |
Research Approach
Coverage spans India, Germany, China, the United States, and Brazil, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged plant managers at lead-acid battery assembly facilities, procurement leads at telecom infrastructure operators, EPC contractors for solar-plus-storage installations, and aftermarket service heads for industrial UPS systems. Secondary sources triangulated customs and trade data for lead ingot flows, BIS and IEC certification registries, SEC filings from publicly traded energy storage manufacturers, and project development databases for rural electrification programs. Bottom-up unit economics and top-down market sizing were cross-validated across the analysis window.
Granularity-level modeling operated at product type, application, end user, and distribution channel dimensions, with additional disaggregation by regional regulatory cluster and certification tier. CAGRs were derived from regression analysis against telecom infrastructure deployment pipelines, data center construction permits, and renewable energy procurement auction volumes. Forecast inputs incorporated solar inverter integration specifications, diesel generator displacement timelines in weak-grid territories, and BIS certification timeline assumptions for imported units.
The model assumes a particular technology adoption path; alternative pathways for lithium iron phosphate cost reduction would alter the outlook for cycling-intensive applications. Forecasts reflect assumptions about EU F-Gas Regulation enforcement timing and India's grid reliability trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Home Inverter Battery Market
Batteries
Grid-Scale Battery Market
Batteries
Southeast Asia Battery Market
Batteries
South Europe Battery Market
Batteries
Seawater Battery Market
Batteries
Printable Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
United States SLI Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
India Micro Batteries Market
Batteries
Carbon Foam Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Global Industrial Battery Market
Batteries
Automotive AGM Battery Market
Batteries
Drone Lithium Battery Charger Market