
 West Africa Battery Market | 2026-2036
West Africa Battery Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Battery Market Analytics
The ECOWAS Renewable Energy Policy is shifting procurement criteria toward localized battery assembly and reduced import dependency across member states. The Ibeto Group leverages its Nigerian manufacturing footprint to supply lead-acid and lithium-ion assemblies for automotive and industrial buyers. Panasonic Corporation competes through technology leadership in lithium-ion cell chemistry adapted for tropical operating conditions. Forgo Battery Company Limited anchors its position in Ghana through channel control of telecom backup power installations.
West Africa batteries encompass electrochemical energy storage devices engineered with specific gravities of 1.215-1.280 for lead-acid variants and nominal voltages of 3.2-3.7V per cell for lithium-ion systems, manufactured through plate casting, formation cycling, and electrolyte filling processes to deliver reliable DC power in grid-unreliable environments. Lead-acid products still dominate unit volume across automotive OEM and UPS Systems applications due to established recycling infrastructure and lower upfront capital requirements. Lithium-ion chemistry is expanding fastest within Renewable Energy and Electric Vehicles applications where energy density and cycle life outweigh premium pricing. Solid-state technology remains pre-commercial in this geography but attracts R&D interest from multinationals testing tropical degradation parameters.
Nigeria's Standards Organisation of Nigeria enforces battery labeling and disposal protocols, while Ghana's Energy Commission regulates mini-grid storage procurement specifications, and Côte d'Ivoire's national quality agency monitors import conformity for telecom backup systems. These frameworks collectively raise compliance costs for uncertified imports while creating protected market access for accredited local assemblers. Stakeholders must monitor evolving ECOWAS harmonization timelines and pre-position technical documentation for cross-border product registration.
Market Dynamics
Import substitution mandates from Nigeria's Standards Organisation of Nigeria are forcing battery assemblers to relocate plate casting and formation cycling operations within ECOWAS borders, compressing margins for pure traders while rewarding manufacturers with captive lead smelting and plastic molding capabilities.
Growth Catalysts
- Rural electrification programs:Off-grid solar home systems across Nigeria's unserved settlements are creating pull-through demand for deep-cycle lead-acid and lithium-ion storage packs sized for 200-500Wh daily loads.
- ECOWAS Renewable Energy Policy:Localized assembly requirements for mini-grid storage procurement are redirecting capital toward Ghanaian and Ivorian manufacturing zones with bonded warehouse status.
- Telecom infrastructure buildout:Tower companies in Côte d'Ivoire are consolidating backup power contracts, favoring suppliers with regional service networks over distant exporters.
Market Restraints
- Lead price volatility:LME lead fluctuations transmit directly into automotive battery cost structures, compressing assembler margins when hedge coverage is unavailable.
- Cell import concentration:Prismatic lithium-ion cells for industrial applications remain concentrated in East Asian supply chains, exposing assemblers to shipping rate spikes and currency mismatches.
- Thermal degradation limits:Conventional lithium-ion electrolytes face accelerated capacity fade above 45°C ambient, restricting deployment in Nigeria's northern Sahel corridor without active cooling.
Strategic Opportunities
- Solid-state pilot programs:Multinationals are testing oxide-based electrolyte cells in Accra and Lagos for tropical cycling stability, creating first-mover positioning ahead of commercialization.
- Burkina Faso and Mali mini-grids:These underpenetrated markets lack established supplier relationships, opening channel development for assemblers with French-language technical support.
- Battery-as-a-service models:Pay-per-cycle structures for commercial and industrial storage are emerging in Ghana, decoupling upfront capital barriers from technology access.
Industry Challenges
- Electrochemical engineering talent:Formation cycling optimization and electrolyte formulation expertise remain scarce across West African technical institutes, forcing reliance on expatriate specialists.
- Cross-border certification timelines:ECOWAS harmonization delays force separate product registration in Nigeria, Ghana, and Côte d'Ivoire, extending commercialization cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Battery Market |
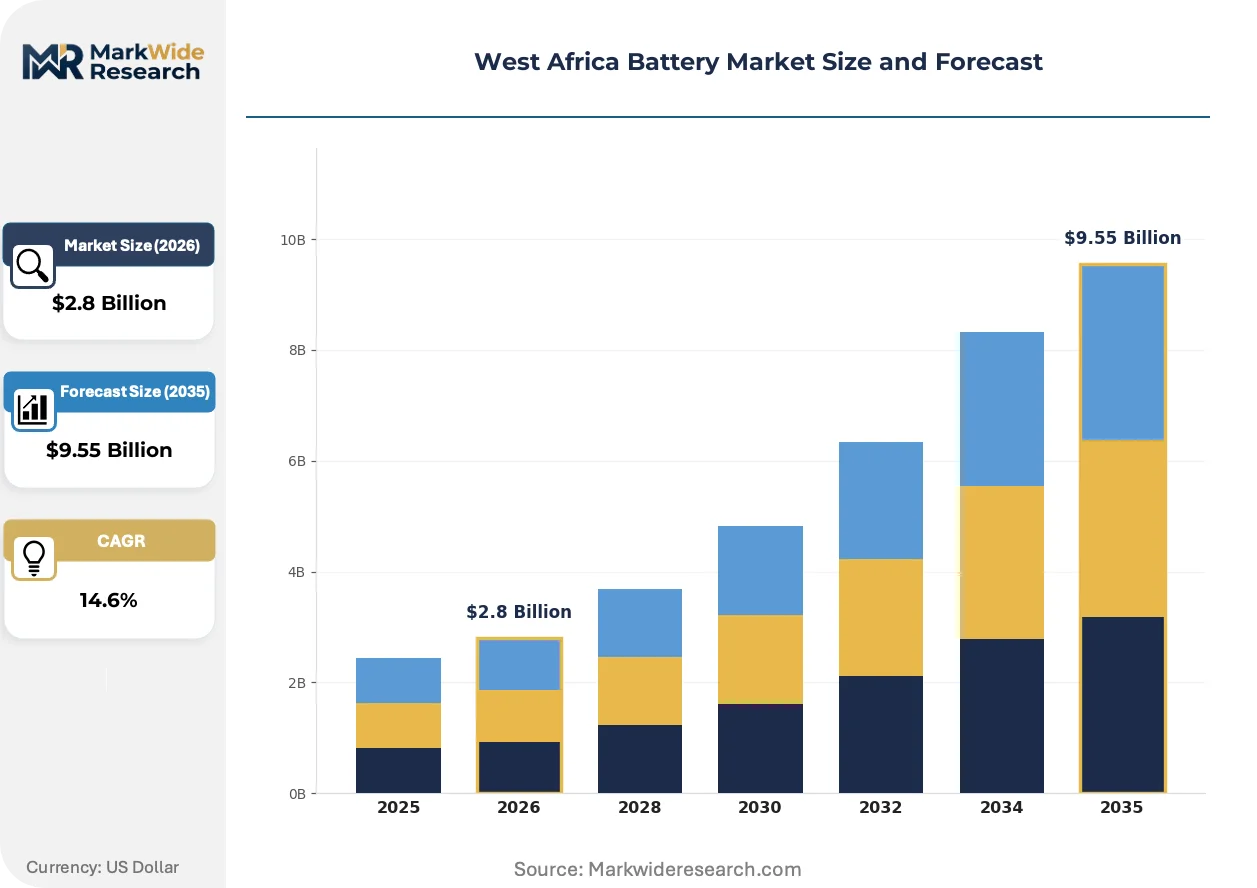
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-cadmium, Flow batteries End User: Consumer Electronics, Automotive OEMs, Energy Storage Systems, Industrial Application: Renewable Energy, Electric Vehicles, UPS Systems, Telecommunications Technology: Advanced Material, Solid-state, Hybrid, Rechargeable |
| Companies Covered | The Ibeto Group, Forgo Battery Company Limited, Luminous Power Technologies, Franerix Solutions Ltd, Robert Bosch (Pty) Ltd, Panasonic Corporation, Toshiba Corporation, GS Yuasa Corp, Johnson Controls International Plc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Battery Market Evolving Landscape
Lithium-ion phosphate chemistry is electrifying competitive positioning across West African storage applications. Three material and operational shifts are compressing technology adoption curves and rewiring procurement patterns.
Lithium iron phosphate cells are electrifying renewable energy storage deployments across Nigerian solar-diesel hybrid mini-grids. Rural electrification agencies in Kaduna and Kano states are specifying 48V rack systems with 6000-cycle ratings, displacing tubular lead-acid banks that require replacement every 18-24 months in deep-discharge duty cycles. This chemistry is electrifying total cost-of-ownership calculations for developers bidding 15-year power purchase agreements.
Ghana's Energy Commission has mandated IEC 62619 certification for all lithium-ion storage systems procured under national mini-grid tenders, effective for contracts signed after January 2024. This regulation is compressing supplier qualification lists to assemblers with in-house UN 38.3 testing capabilities or third-party laboratory partnerships. Nigerian and Ivorian regulators are observing compliance outcomes before drafting harmonized technical specifications.
Telecom tower operators are unbundling battery procurement from original equipment manufacturer supply agreements, establishing direct relationships with regional assemblers for 24V and 48V backup strings. MTN and Airtel procurement teams in Lagos and Abidjan are negotiating frame agreements with 3-5 year cycle commitments, replacing spot purchasing through distributor networks. This behavioral shift is most visible in Nigeria's Southwest corridor where tower densification is accelerating.
West Africa Battery Market Segmentation
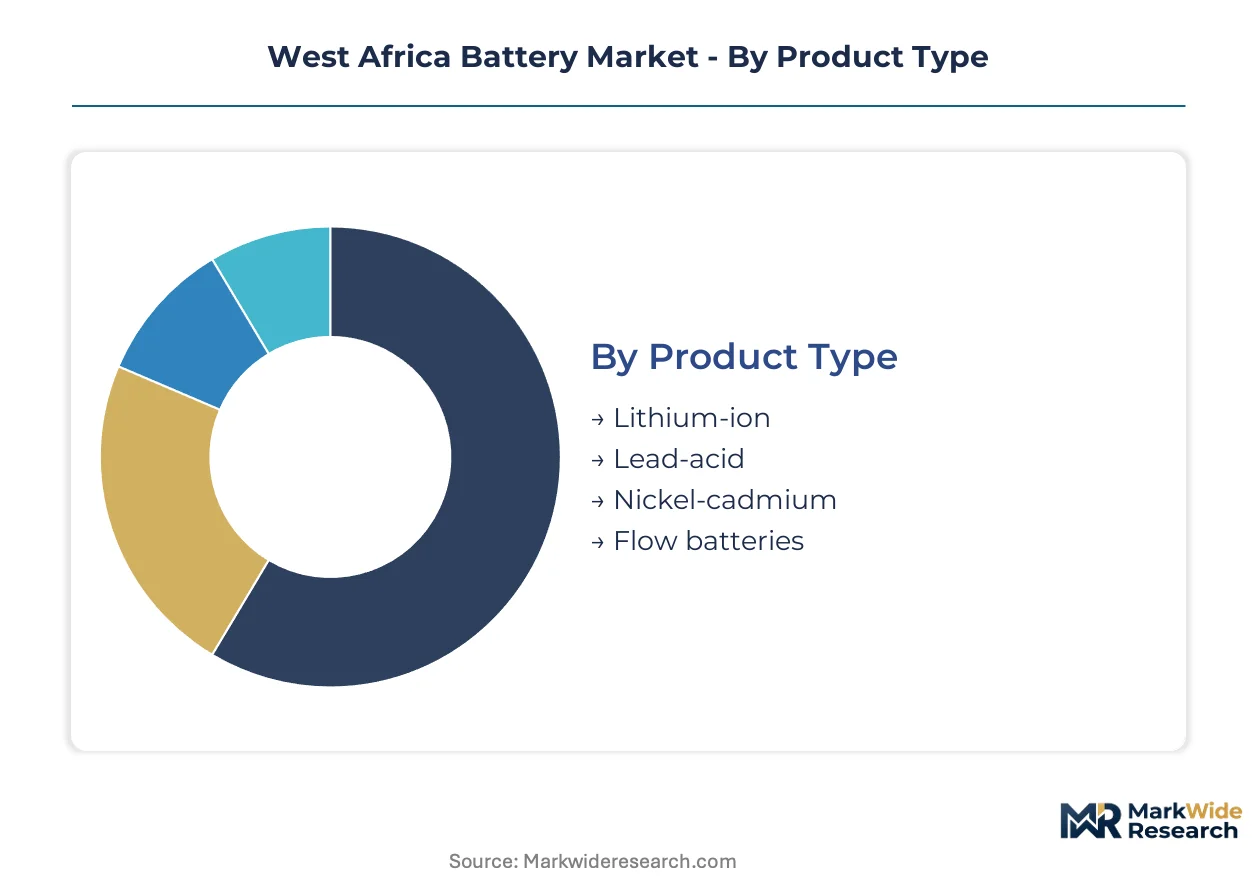
Segmentation reveals how West African procurement patterns diverge from global norms. Thermal constraints, import substitution mandates, and rural electrification priorities create distinct demand clusters that reward localized assembly capabilities over pure technology specifications.
Product Type:
Cost sensitivity and recycling infrastructure availability separate buyers across chemistry choices.
- Lithium-ion:Cells with phosphate cathode chemistry dominate Nigerian solar-diesel hybrid mini-grids due to 6000-cycle ratings and 45°C thermal tolerance. Kaduna and Kano state rural electrification agencies specify 48V rack systems, displacing lead-acid banks that fail within 18-24 months under deep-discharge duty cycles.
- Lead-acid:Flooded and AGM variants retain unit volume leadership across automotive OEM and UPS applications through established lead smelting infrastructure in Nigeria and Ghana. Specific gravities of 1.215-1.280 and lower upfront capital requirements protect market position despite weight and cycle life disadvantages.
- Nickel-cadmium:Aviation and rail signaling applications in Côte d'Ivoire specify sintered plate construction for extreme temperature resilience and maintenance-free operation in remote installations.
- Flow batteries:Vanadium redox systems pilot at Ghanaian industrial microgrids where 8-12 hour discharge duration outweighs capital cost premiums for mining and processing facilities.
Lead-acid leads volumes today; lithium-ion is gaining share fastest.
End User:
Procurement sophistication and technical specification authority determine supplier access tiers.
- Automotive OEMs:Nigerian vehicle assemblers in Lagos and Nnewi source 12V SLI batteries through frame agreements with local plate casters, with Ibeto Group supplying lead-acid assemblies under import substitution compliance.
- Energy Storage Systems:Mini-grid developers in Ghana negotiate 15-year power purchase agreements specifying IEC 62619-certified lithium-ion storage, compressing supplier lists to assemblers with UN 38.3 testing partnerships.
- Telecommunications:Tower companies across Nigeria's Southwest corridor unbundle battery procurement from OEM supply agreements, establishing direct 3-5 year frame agreements with regional assemblers for 24V and 48V backup strings.
- Consumer Electronics:Mobile phone and portable device markets in Abidjan and Lagos source cylindrical cells through distributor networks with limited technical specification involvement.
- Industrial:Manufacturing facilities in Tema and Port Harcourt specify traction batteries for forklift fleets and stationary backup, prioritizing local service response over chemistry innovation.
Automotive OEMs anchor procurement volumes; energy storage systems show steepest expansion trajectory.
Application:
Duty cycle intensity and grid reliability requirements shape chemistry selection and supplier relationships.
- Renewable Energy:Solar-diesel hybrid mini-grids across Nigeria's unserved settlements specify deep-cycle storage sized for 200-500Wh daily loads, with lithium iron phosphate displacing tubular lead-acid in 15-year contract structures.
- Telecommunications:MTN and Airtel procurement teams in Lagos and Abidjan consolidate tower backup power contracts, favoring assemblers with regional service networks and French-language technical support capabilities.
- UPS Systems:Banking and data center facilities in Accra specify valve-regulated lead-acid for 15-minute to 4-hour backup duration, with established recycling infrastructure reducing total cost of ownership calculations.
- Electric Vehicles:Two-wheeler and three-wheeler electrification in Nigerian urban corridors drives demand for lithium-ion packs, though thermal management requirements restrict deployment in northern Sahel zones without active cooling.
Telecommunications leads installed base; renewable energy applications are climbing the fastest.
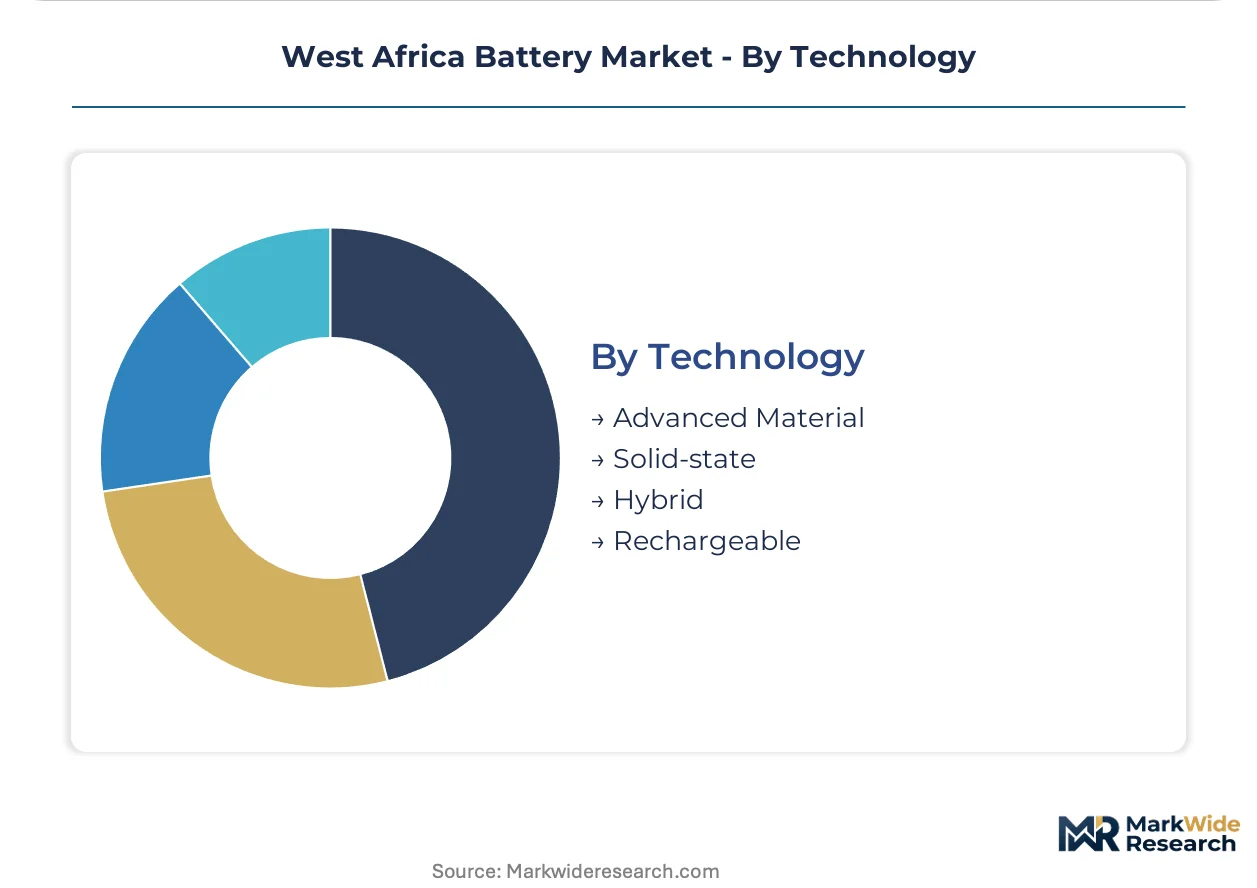
Technology:
Maturity level and manufacturing location requirements create tiered market access.
- Rechargeable:Mature lithium-ion and lead-acid chemistries dominate commercial procurement through established formation cycling and electrolyte filling processes within ECOWAS borders.
- Advanced Material:Silicon-anode and high-nickel cathode developments remain import-dependent, with Nigerian and Ghanaian assemblers sourcing prismatic cells from East Asian supply chains.
- Hybrid:Lead-carbon and lithium-lead combinations target Nigerian telecom applications seeking cost optimization without full lithium-ion capital commitment.
- Solid-state:Oxide-based electrolyte cells remain pre-commercial, with multinationals testing tropical cycling stability in Accra and Lagos pilot programs ahead of commercialization timelines.
Rechargeable technology commands current volumes; solid-state represents the longest-term displacement threat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery assembly operations first scaled in Nigeria during the 1970s oil boom, when import substitution policies attracted lead-acid manufacturers to Lagos and Nnewi industrial corridors. Ghana and Côte d'Ivoire subsequently developed competitive assembly capacity through ECOWAS trade integration and telecom infrastructure investment.
Nigeria
Rural electrification programs in Kaduna and Kano states are driving demand for 48V lithium iron phosphate storage systems sized for 200-500Wh daily loads. The Standards Organisation of Nigeria enforces battery labeling and disposal protocols that raise compliance costs for uncertified imports. Nnewi and Lagos host the region's densest concentration of lead-acid plate casting and formation cycling operations.
Ghana
Mini-grid developers are negotiating 15-year power purchase agreements specifying IEC 62619-certified lithium-ion storage, compressing supplier qualification lists. The Energy Commission regulates procurement specifications for national mini-grid tenders effective since January 2024. Tema industrial zone anchors bonded warehouse operations serving regional telecom backup contracts.
Côte d'Ivoire
MTN and Airtel procurement teams are consolidating tower backup power contracts favoring assemblers with regional service networks. The national quality agency monitors import conformity for telecom backup systems, creating protected market access for accredited local suppliers. Abidjan serves as the commercial hub for French-language technical support across Francophone West Africa.
Burkina Faso
Mini-grid deployment in unserved settlements is accelerating without established supplier relationships, opening channel development opportunities. The national energy regulator is observing Ghanaian compliance outcomes before drafting storage procurement specifications. Ouagadougou-based distributors are testing direct relationships with Nigerian and Ghanaian assemblers for solar-diesel hybrid systems.
Senegal
Off-grid solar home systems are expanding adoption through rural electrification agency programs targeting 200-500Wh daily load segments. The national standards body is aligning with ECOWAS harmonization timelines for cross-border product registration. Dakar industrial zone is attracting regional assemblers seeking bonded warehouse status for West African distribution.
West Africa Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and local assembly capabilities, with IEC 62619 and UN 38.3 testing partnerships separating qualified suppliers from pure traders. The vendor base clusters around three strategic archetypes: Nigerian manufacturers with captive lead smelting and plastic molding capabilities, Ghanaian assemblers controlling telecom channel access, and East Asian multinationals supplying prismatic lithium-ion cells. Dominant competitive moves include backward integration into plate casting operations and formation cycling partnerships with regional technical institutes.
Within the Nigerian manufacturing tier, The Ibeto Group occupies a position representing import substitution compliance through local assembly footprints. Forgo Battery Company Limited exemplifies the Ghanaian channel-control archetype, anchoring telecom backup power installation relationships. Panasonic Corporation sits within the multinational technology tier, supplying lithium-ion cell chemistry adapted for tropical operating conditions. These three players represent the competitive structure's premium, regional, and global vectors respectively.
| Leading Market Players |
|---|
| The Ibeto Group |
| Forgo Battery Company Limited |
| Luminous Power Technologies |
| Franerix Solutions Ltd |
| Robert Bosch (Pty) Ltd |
| Panasonic Corporation |
| Toshiba Corporation |
| GS Yuasa Corp |
| Johnson Controls International Plc |
| Others |
Value Network & Pricing Analysis
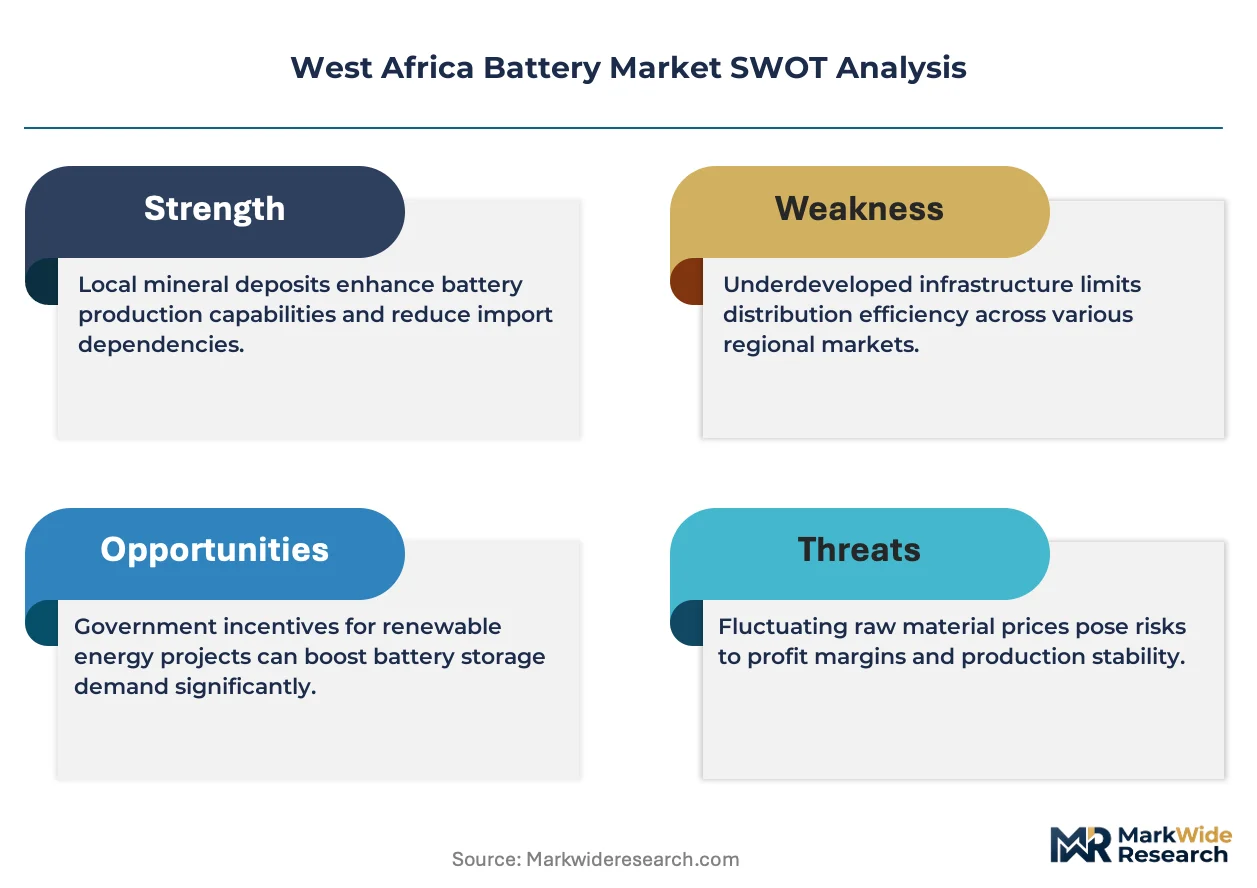
LME lead ingot pricing transmits directly into automotive battery cost structures, cascading through Nigerian plate casters and Ghanaian assemblers before reaching telecom tower operators negotiating multi-year frame agreements. This raw material pathway compresses margins for traders without hedge coverage while rewarding manufacturers with captive smelting and bonded warehouse positioning.
Pricing Analysis
Three-tier pricing structure across premium IEC 62619-certified, standard UN 38.3-tested, and economy uncertified tiers separates qualified assemblers from pure traders in Nigerian and Ghanaian procurement. Certification grade and after-sales service bundling drive price differentiation, with premium tiers commanding spreads for tropical-adapted cell chemistry. Cost compression in economy lead-acid segments is intensifying because import substitution mandates force local assembly investments. Mini-grid developers show lowest price sensitivity due to 15-year power purchase agreement structures, while consumer electronics distributors remain most elastic.
Supply Chain Analysis
Nigeria's Standards Organisation of Nigeria local-content mandates are reshaping sourcing patterns, forcing relocation of plate casting and formation cycling within ECOWAS borders. Prismatic lithium-ion cells draw from China, South Korea, and Japan, while lead oxide and plastic battery cases rest on Nigerian and Ghanaian domestic supply. Single-source vulnerability concentrates in East Asian cell supply chains, exposing assemblers to shipping rate volatility. Distribution runs through bonded warehouse operations in Tema and Lagos serving regional telecom and mini-grid contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because rural electrification programs generate predictable pull-through demand for storage systems across unserved settlements. Grid unreliability ensures persistent replacement cycles regardless of macroeconomic fluctuations.
For Market Incumbents: Extend formation cycling partnerships with Kaduna and Kano technical institutes to lock in electrochemical engineering talent before solid-state commercialization accelerates. Deepen backward integration into captive lead smelting to defend margin position against LME volatility and emerging Ghanaian competitors with channel control. Certification investment in IEC 62619 and UN 38.3 testing capabilities remains the critical lever for mini-grid procurement access. For New Entrants and Emerging Players: Ghana's Energy Commission IEC 62619 mandate opens a window for assemblers with laboratory partnerships to qualify for national mini-grid tenders before Nigerian and Ivorian harmonization spreads. Burkina Faso and Mali present the most penetrable geographies, lacking established supplier relationships and observing Ghanaian compliance outcomes before drafting specifications. French-language technical support capabilities anchor the essential go-to-market angle for Francophone West Africa expansion. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap assemblers with bonded warehouse status and regional service networks because telecom tower unbundling favors consolidated procurement relationships over fragmented distributor channels. Five-to-ten-year viability hinges on lithium-ion phosphate chemistry adoption curves displacing lead-acid in renewable energy applications. Watch solid-state pilot program outcomes in Accra and Lagos as the inflection signal for next-generation technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive supply of lead oxide insulates Nigerian assemblers from LME price volatility and import substitution compliance costs. |
| IEC 62619 Certification Investment | UN 38.3 testing partnerships qualify Ghanaian suppliers for national mini-grid tenders with 15-year contract structures. |
| Regional Service Network Expansion | French-language technical capabilities in Abidjan capture MTN and Airtel tower consolidation across Côte d'Ivoire. |
| Solid-State Pilot Programs | Oxide-based electrolyte testing in tropical conditions positions multinationals ahead of commercialization timelines. |
| Battery-as-a-Service Model Launch | Pay-per-cycle structures in Ghana decouple upfront capital barriers from commercial and industrial storage access. |
Research Methodology
Direct dialogue with mini-grid developers, telecom procurement officers, battery assemblers, and ECOWAS regulatory officials grounded qualitative findings in operational reality. Secondary validation drew from Standards Organisation of Nigeria enforcement records, Ghana Energy Commission tender documentation, IEC certification databases, and customs trade data for lead and lithium cell imports. Bottom-up assembly capacity modeling triangulated against top-down rural electrification program deployment targets.
Bottom-up volume builds aggregated country-level demand from mini-grid PPA structures, telecom tower backup specifications, and automotive OEM frame agreements. Segmentation dimensions span chemistry type, end-user procurement sophistication, application duty cycle intensity, and technology maturity tier. Value outputs reflect pricing spreads across certified and uncertified supply tiers. CAGRs derived from deployment pipeline visibility and import substitution policy implementation schedules across the analysis window.
Revisions become necessary when ECOWAS harmonization timelines accelerate, solid-state commercialization advances beyond pilot phases, or lead price volatility exceeds historical hedging bandwidth. Forecasts embed assumptions about regulatory enforcement consistency and cell import supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Iron Flow Battery Market
Batteries
North America Industrial Battery Market
Batteries
Power Tool Batteries Market
Batteries
United Kingdom SLI Battery Market
Batteries
Yacht Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Primary Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Battery-Powered Riveter Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Alkaline Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Battery Simulator Market
Batteries
Floor Scrubber Battery Market
Batteries
Lithium Starters Market
Batteries
Military Battery Packs Market