
 Vietnam Battery Market | 2026-2036
Vietnam Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Battery Market Outlook
Solid-state and sodium-ion chemistry development is fragmenting the incumbent lithium-ion supply chain across Vietnam's battery sector. VinES anchors its position through backward integration into cathode material production. Samsung SDI competes by sustaining high R&D intensity for automotive-grade cell formats. LG Energy Solution differentiates through its established relationships with Korean automakers assembling vehicles in Thai Nguyen and Ha Nam provinces.
A battery is an electrochemical device comprising cathode, anode, electrolyte, and separator that stores and releases electrical energy through reversible redox reactions, with energy density typically measured in watt-hours per kilogram. Its primary industrial purpose is to provide portable, rechargeable power for transportation, electronics, and grid-scale energy management. Lithium-ion technology leads product value creation due to its superior cycle life and energy density for electric vehicle applications. Lead-acid chemistry occupies the aftermarket for internal combustion engine starting and industrial backup systems where cost sensitivity dominates purchasing decisions. Renewable energy storage represents the fastest-expanding product type as Vietnam's solar and wind capacity additions outpace grid balancing infrastructure.
The Ministry of Industry and Trade sets national technical regulations for battery safety, while the Vietnam Environment Administration enforces hazardous waste protocols affecting end-of-life collection obligations. Circular No. 02/2022 on e-waste management imposes extended producer responsibility on importers and manufacturers, reshaping distribution and reverse logistics requirements. Stakeholders must monitor how draft national standards on battery energy density and thermal runaway testing will filter market access for imported versus domestically produced cells.
Market Dynamics
Vietnam's battery sector is restructuring around cathode material localization as VinES scales backward integration, while Korean cell makers anchor automotive supply through Thai Nguyen and Ha Nam assembly plants.
Growth Catalysts
- Electric vehicle assembly localization:Korean automakers operating in Thai Nguyen and Ha Nam provinces are scaling procurement of locally produced lithium-ion cells, creating captive demand for domestic cell manufacturing.
- Circular No. 02/2022 enforcement:Extended producer responsibility mandates on importers and manufacturers are professionalizing reverse logistics and end-of-life collection infrastructure.
- Ho Chi Minh City industrial corridor concentration:Dense electronics manufacturing clusters generate economies of scale for battery pack assembly and testing facilities.
Market Restraints
- Lithium carbonate import dependency:Vietnam lacks domestic lithium extraction, exposing cell makers to spot price volatility and currency fluctuation risks.
- Cathode precursor supply concentration:Nickel-cobalt-manganese precursor sourcing concentrates among Chinese refiners, creating single-point-of-failure vulnerabilities.
- Thermal runaway testing capacity scarcity:Limited domestic certification laboratories delay product qualification timelines for new cell formats entering the market.
Strategic Opportunities
- Northern Hai Phong manufacturing zone expansion:Deep-water port access and existing electronics supply chain density position this corridor for export-oriented cell production.
- Sodium-ion chemistry substitution:Abundant domestic salt deposits enable cost-competitive cathode material sourcing for stationary storage applications.
- Solar-plus-storage bundling:Vietnam's accelerating solar capacity additions outpace grid balancing infrastructure, creating procurement pull for integrated battery systems.
Industry Challenges
- Electrolyte formulation expertise scarcity:Domestic talent pools lack depth in solid-state and high-voltage electrolyte development, forcing reliance on foreign technical partnerships.
- Extended producer responsibility compliance costs:Reverse logistics network buildout requires capital deployment ahead of revenue-generating recycling operations.
- Cell-to-pack integration complexity:Automotive OEMs demand module elimination, pressuring pack assemblers to develop thermal management and battery management system capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Battery Market |
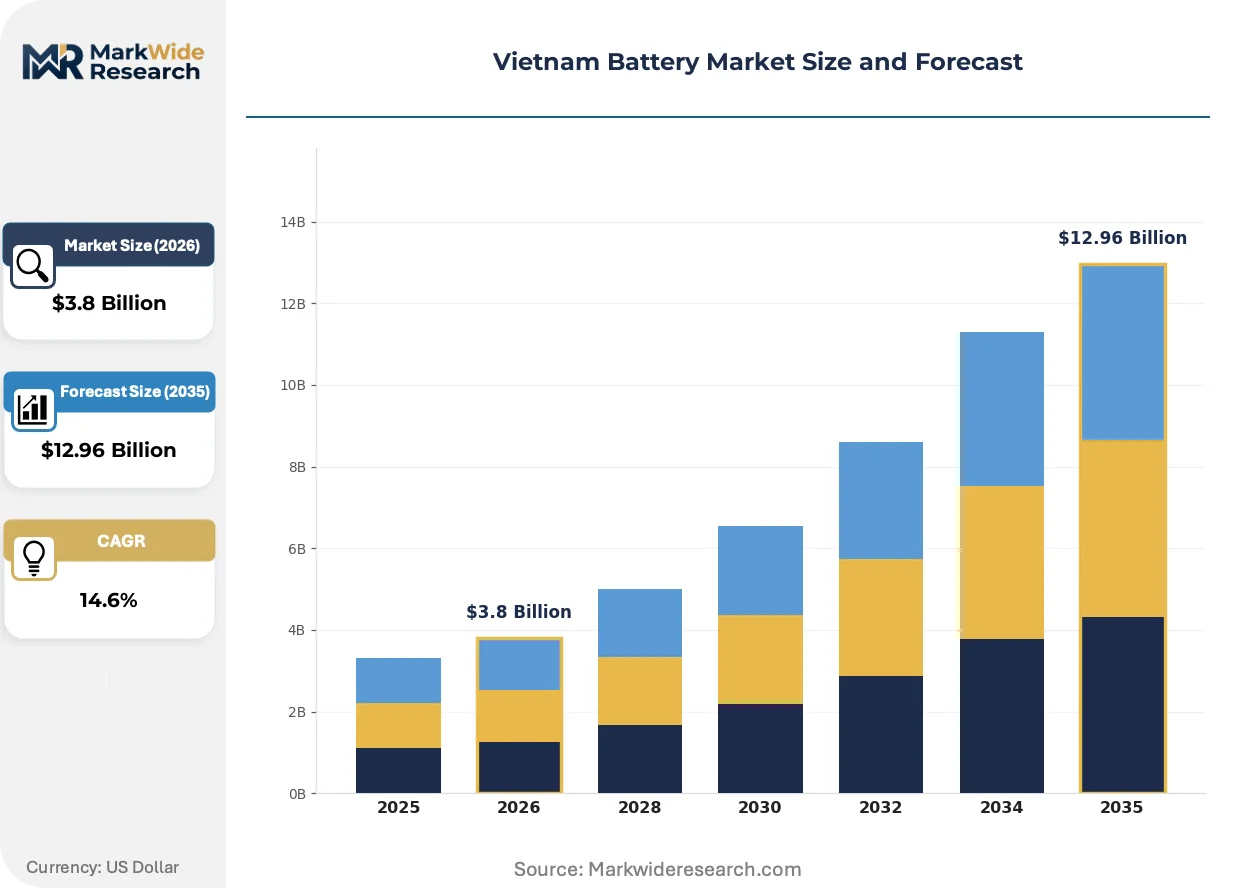
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead-acid, Nickel-cadmium, Flow Batteries Product Type: Automotive Batteries, Industrial Batteries, Consumer Electronics, Renewable Energy Storage Application: Electric Vehicles, Portable Devices, Backup Power, Grid Storage End User: Manufacturers, Retailers, Utilities, Individual Consumers |
| Companies Covered | SK On, Panasonic Energy, VinES (VinFast Energy Storage), PINACO, GS Battery Vietnam, BYD, Samsung SDI, Vision Group, LG Energy Solution, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Battery Market Strategic Shifts
Technology roadmaps are diverging as solid-state prototypes approach commercialization, while regulatory pressure on recycling intensifies operational requirements across the value chain.
Prismatic cell formats are migrating from cylindrical dominance in automotive applications. Korean vehicle assemblers in Thai Nguyen and Ha Nam provinces specify prismatic designs for space efficiency and thermal management integration. This format shift compresses cylindrical cell demand in transportation segments while expanding local pack assembly complexity.
The Ministry of Industry and Trade is tightening national technical regulations on battery energy density and thermal runaway propagation. Draft standards will filter market access based on cell testing protocols, favoring producers with captive certification capabilities. Importers face higher compliance barriers relative to domestic manufacturers with established Vietnam laboratory relationships.
Automotive OEM procurement is consolidating around long-term offtake agreements with cell makers. Korean vehicle assemblers are bypassing trading intermediaries to contract directly with Samsung SDI and LG Energy Solution for Thai Nguyen and Ha Nam plant supply. This disintermediation compresses distributor margins while locking in volume commitments for cell producers.
Vietnam Battery Market Segmentation
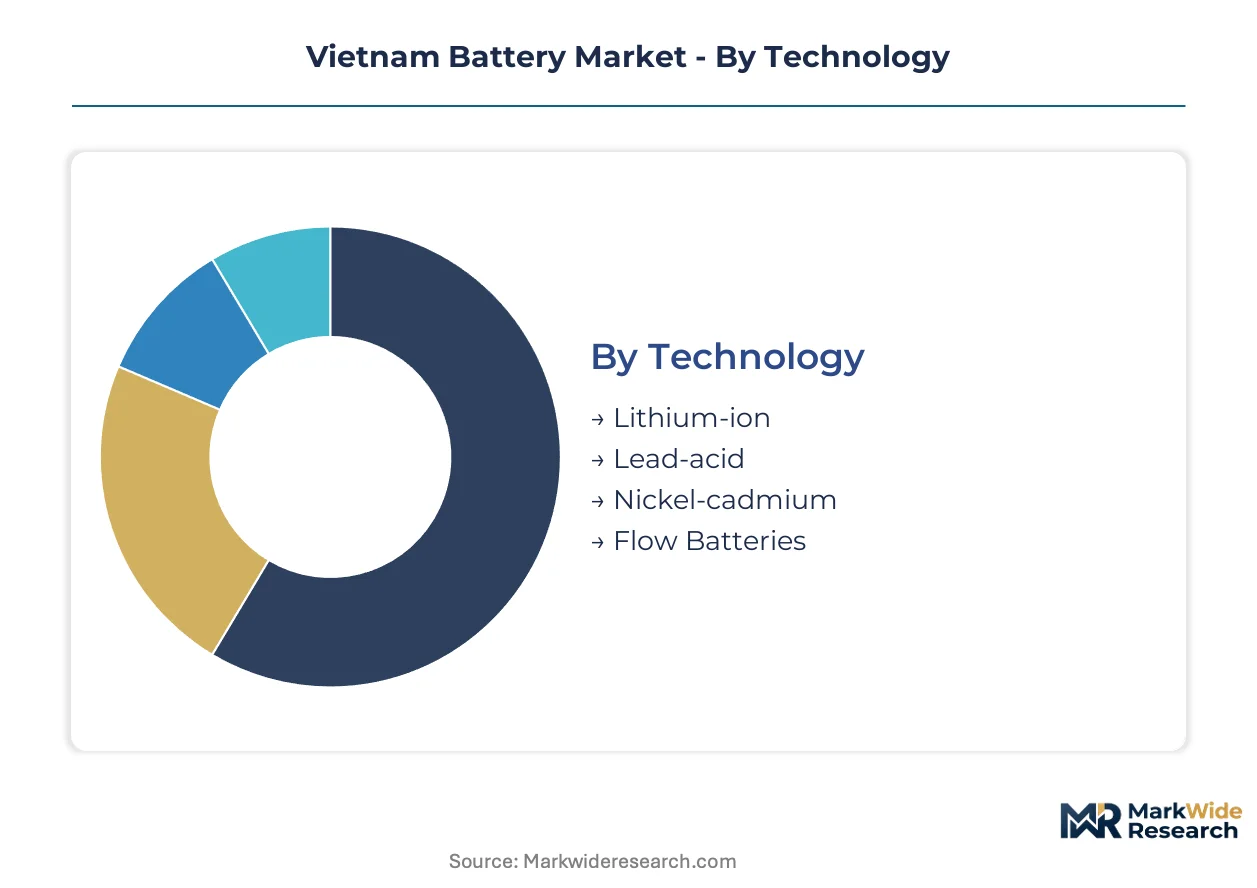
Segmentation in Vietnam's battery market reveals how technology choices, product formats, and end-use applications concentrate value creation differently across the value chain. Understanding these divisions exposes where procurement power sits and which segments drive capacity expansion decisions.
Technology:
Cost tier determines competitive positioning across cell chemistry families, with premium energy density commanding automotive premiums and commodity formulations serving price-sensitive backup applications.
- Lithium-ion:Cathode-anode-electrolyte architecture delivers 150-300 Wh/kg energy density through intercalation chemistry. Korean automakers in Thai Nguyen and Ha Nam provinces specify these cells for electric vehicle powertrains, though lithium carbonate import dependency exposes margins to spot price volatility.
- Lead-acid:Mature flooded and valve-regulated designs rely on sulfuric acid electrolyte and lead dioxide cathodes for 30-50 Wh/kg density. Industrial backup systems in Ho Chi Minh City's manufacturing corridor sustain demand where upfront cost sensitivity overrides cycle life considerations.
- Nickel-cadmium:Alkaline electrolyte systems tolerate extreme temperature cycling for aviation and rail signaling applications.
- Flow Batteries:Vanadium redox and zinc-bromine chemistries decouple power and energy scaling for multi-hour grid storage deployments.
Lithium-ion commands the established base. The steepest expansion runs through flow batteries as utility-scale solar integration outpaces conventional balancing infrastructure.
Product Type:
Application maturity shapes margin structures differently across transportation, industrial, consumer, and grid-facing product categories.
- Automotive Batteries:Prismatic and pouch cell formats integrate thermal management systems for 400-800V electric vehicle architectures. Samsung SDI and LG Energy Solution supply Korean OEM assembly plants in northern provinces, with cell-to-pack designs eliminating module complexity.
- Industrial Batteries:Forklift traction, telecom backup, and uninterruptible power systems favor lead-acid and lithium iron phosphate chemistries. Hai Phong's port-proximate manufacturing zones concentrate assembly for export-oriented industrial equipment.
- Consumer Electronics:Cylindrical 18650 and 21700 formats power laptops, power tools, and personal mobility devices.
- Renewable Energy Storage:Containerized lithium-ion and emerging sodium-ion systems buffer solar and wind intermittency.
Automotive batteries command the established base. The steepest expansion runs through renewable energy storage as Vietnam's solar capacity additions accelerate procurement for grid balancing.
Application:
Volume concentration varies sharply between mobility-focused deployments and stationary infrastructure buildouts.
- Electric Vehicles:Battery electric and plug-in hybrid platforms require 40-100 kWh packs with automotive-grade cell qualification. Korean manufacturers in Thai Nguyen and Ha Nam provinces are localizing procurement to reduce import dependency and logistics costs.
- Portable Devices:Smartphones, laptops, and power tools consume cylindrical and prismatic cells in 10-100 Wh capacities.
- Backup Power:Data centers, hospitals, and industrial facilities specify valve-regulated lead-acid or lithium-ion systems for minutes-to-hours of runtime.
- Grid Storage:Utility-scale installations aggregate megawatt-hour capacity for frequency regulation and renewable firming.
Backup power commands the established base. The steepest expansion runs through electric vehicles as assembly localization deepens captive demand for domestic cell production.
End User:
Customer type determines procurement sophistication, contract structures, and technical specification intensity across the value chain.
- Manufacturers:Automotive OEMs and electronics assemblers negotiate long-term offtake agreements directly with cell producers, bypassing distribution intermediaries. Korean vehicle plants in northern provinces contract with Samsung SDI and LG Energy Solution for dedicated supply lines.
- Retailers:Aftermarket channels serve replacement demand for automotive starting batteries and consumer electronics accessories.
- Utilities:State and private power companies procure grid-scale storage through competitive tender processes.
- Individual Consumers:Direct purchases concentrate in replacement automotive batteries and personal electronics power banks.
Retailers command the established base. The steepest expansion runs through utilities as solar-plus-storage bundling reshapes procurement for grid infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports lithium-ion cells to Korean automakers assembling vehicles in Thai Nguyen and Ha Nam provinces, while importing cathode precursors and lithium carbonate from Chinese refiners and Australian miners.
Ho Chi Minh City Industrial Corridor
Electronics contract manufacturers drive cylindrical and prismatic cell demand for power tools and consumer devices. The Ministry of Industry and Trade enforces Circular No. 02/2022 extended producer responsibility on pack assemblers operating in Binh Duong and Dong Nai satellite zones. Dense industrial parks in Thu Duc and District 9 concentrate battery testing and pack integration facilities serving export-oriented electronics brands.
Northern Manufacturing Zone (Thai Nguyen)
Korean automakers localize electric vehicle assembly and scale procurement of automotive-grade lithium-ion cells. Samsung SDI and LG Energy Solution supply directly to assembly plants under long-term offtake agreements. The zone's proximity to Chinese border crossings reduces logistics costs for cathode material imports from Hunan and Fujian refiners.
Hai Phong Port Corridor
Deep-water terminal access positions this northern hub for export-oriented cell production and industrial battery assembly. VinES operates cathode material production facilities here, backward integrating into precursor manufacturing. The city's electronics supply chain density attracts pack assemblers serving forklift and maritime equipment OEMs.
Ha Nam Province
Secondary automotive assembly clusters emerge as Korean manufacturers diversify beyond Thai Nguyen. Provincial industrial zones offer land concessions for cell-to-pack integration facilities. The area lacks domestic certification laboratories, forcing producers to ship prototypes to Ho Chi Minh City for thermal runaway testing.
Central Highlands
Solar farm developers procure containerized storage systems for grid balancing as renewable capacity additions outpace transmission infrastructure. Domestic salt deposits in Ninh Thuan and Binh Thuan provinces enable experimental sodium-ion cathode material sourcing for stationary applications. Limited skilled labor pools constrain electrolyte formulation expertise development.
Vietnam Battery Market Competitive Environment
Channel-controlling players compete with product-specialist players across three observable tiers. Korean cell makers anchor the premium automotive segment through direct OEM relationships, while Vietnamese pack assemblers occupy mid-tier industrial and consumer positions. Chinese manufacturers compete on cost for commodity cylindrical formats. The dominant competitive moves are backward integration into cathode materials and geographic expansion into northern industrial zones.
Among Korean conglomerate subsidiaries, Samsung SDI and LG Energy Solution represent the captive-supply archetype, anchoring automotive-grade production through Thai Nguyen and Ha Nam assembly plant proximity. VinES exemplifies the national-champion model, combining cell manufacturing with upstream cathode material control in Hai Phong. These three companies illustrate how market position depends on integration depth and customer lock-in through direct OEM contracting.
| Leading Market Players |
|---|
| SK On |
| Panasonic Energy |
| VinES (VinFast Energy Storage) |
| PINACO |
| GS Battery Vietnam |
| BYD |
| Samsung SDI |
| Vision Group |
| LG Energy Solution |
| Others |
Value Chain & Pricing Dynamics
The Hai Phong port corridor's freight cost dynamics compress margins for cathode material imports while amplifying price differentiation between automotive-grade and industrial-grade cell tiers. Korean cell makers leverage long-term offtake structures to lock in volume premiums, whereas domestic pack assemblers absorb spot market volatility in lithium carbonate sourcing.
Pricing Analysis
The lithium-ion to lead-acid to sodium-ion pricing gap stratifies procurement decisions across transportation, backup power, and grid storage applications. Three-tier pricing structure across premium automotive, standard industrial, and economy consumer tiers reflects certification intensity and thermal management complexity. Pricing pressure stems from lithium carbonate spot volatility and currency fluctuation exposure. Industrial backup buyers exhibit highest price sensitivity, while automotive OEMs prioritize energy density and cycle life over unit cost.
Supply Chain Analysis
Foxconn and Luxshare Precision concentrate electronics manufacturing services for cylindrical cell pack assembly serving consumer device brands. Vietnam's cell production draws from Chinese cathode precursors, Australian lithium carbonate, and Korean electrolyte formulations. Single-source vulnerability concentrates in nickel-cobalt-manganese precursor refining. Distribution runs through direct OEM contracting for automotive volumes and distributor networks for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's battery sector represents an early-cycle expansion story, with electric vehicle assembly localization creating captive demand pull before domestic cell capacity fully matures.
For Market Incumbents: Harden supply security through captive cathode material production in Hai Phong industrial zones. Deepen thermal runaway testing capabilities to accelerate product qualification timelines against Korean competitors. Lock in long-term lithium carbonate offtake with Australian miners before spot volatility intensifies. For New Entrants and Emerging Players: Sodium-ion stationary storage systems for Central Highlands solar farms represent the most penetrable entry point, given abundant domestic salt deposits and lower certification barriers versus automotive applications. Target cell-to-pack integration services for Ha Nam automotive clusters lacking module elimination expertise. Pursue joint development agreements with Vietnamese electrolyte formulators to bypass foreign technical partnership dependency. For Investors and Strategic Acquirers: Carve-out targets emerge from Korean conglomerate battery divisions seeking non-core asset rationalization. Five-to-ten-year viability hinges on cathode material localization depth and automotive OEM relationship durability. Monitor draft Ministry of Industry and Trade thermal runaway standards as regulatory inflection signal favoring domestic laboratory-equipped producers.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | VinES's Hai Phong precursor production reduces Chinese import dependency for nickel-cobalt-manganese supply. |
| Automotive Cell-to-Pack Transition | Module elimination compresses pack weight and assembly cost for Korean OEMs in Thai Nguyen. |
| Sodium-Ion Chemistry Development | Central Highlands salt deposits enable cost-competitive stationary storage without lithium carbonate exposure. |
| Extended Producer Responsibility Compliance | Circular No. 02/2022 mandates reshape reverse logistics infrastructure ahead of recycling revenue maturation. |
| Prismatic Format Manufacturing Scale-Up | Korean automaker specifications displace cylindrical dominance in northern Vietnam automotive supply. |
Study Parameters
A spread of perspectives from cell manufacturing executives, automotive procurement officers, cathode material suppliers, and Ministry of Industry and Trade regulators converged on the working assumptions. Primary interviews with Vietnamese pack assemblers and Korean cell maker technical directors combined with secondary validation from customs trade data, SEC filings of listed battery companies, Vietnam Environment Administration circulars, and IEA energy storage deployment statistics. Bottom-up capacity buildout estimates and top-down demand projections from electric vehicle assembly plans underwent triangulation.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across technology chemistry, product format, end-use application, and regional production cluster dimensions. CAGRs derived from installed capacity ramp schedules and OEM procurement commitment trajectories incorporated lithium carbonate price elasticity and cathode precursor import cost assumptions.
Macroeconomic conditions sit as an overlay; deviation in Dong-dollar exchange rates and Chinese refining export quotas would shift the trajectory. Forecasts reflect documented assumptions on automotive localization timelines and solar capacity addition rates. Quarterly review of thermal runaway standard finalization and Korean OEM production schedule adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
North Africa Battery Market
Batteries
Rechargeable Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Smart Battery Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Bio Based Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
Utility Battery Market
Batteries
Grid-Scale Battery Market
Batteries
Battery Wash System Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Iron Flow Battery Market
Batteries
Portable Battery Powered Products Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Lithium Thionyl Chloride Battery Market